
 Enterprise Generative AI Market | 2026-2036
Enterprise Generative AI Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Generative AI Market Analytics
Foundation model fine-tuning is reconfiguring how enterprises customize generative capabilities without training models from scratch. Microsoft Corporation leverages its Azure cloud infrastructure to embed OpenAI models across Office 365 and Dynamics workflows. NVIDIA Corporation dominates the specialized silicon layer, sustaining pricing power through CUDA ecosystem lock-in. Anthropic differentiates via constitutional AI safety frameworks, positioning its Claude models for regulated industries.
Enterprise Generative AI comprises transformer-based neural architectures, retrieval-augmented generation pipelines, and fine-tuning methodologies applied to proprietary corporate data for automated reasoning, content synthesis, and decision support. Natural Language Processing applications command the largest deployment share as enterprises automate contract analysis and customer service operations. Computer Vision segments within manufacturing quality inspection represent the fastest-expanding margin pool, while predictive analytics across BFSI end users absorbs the majority of professional services integration spend. Cloud-based deployment options attract initial enterprise adoption, though hybrid configurations gain traction among healthcare providers constrained by HIPAA data residency requirements.
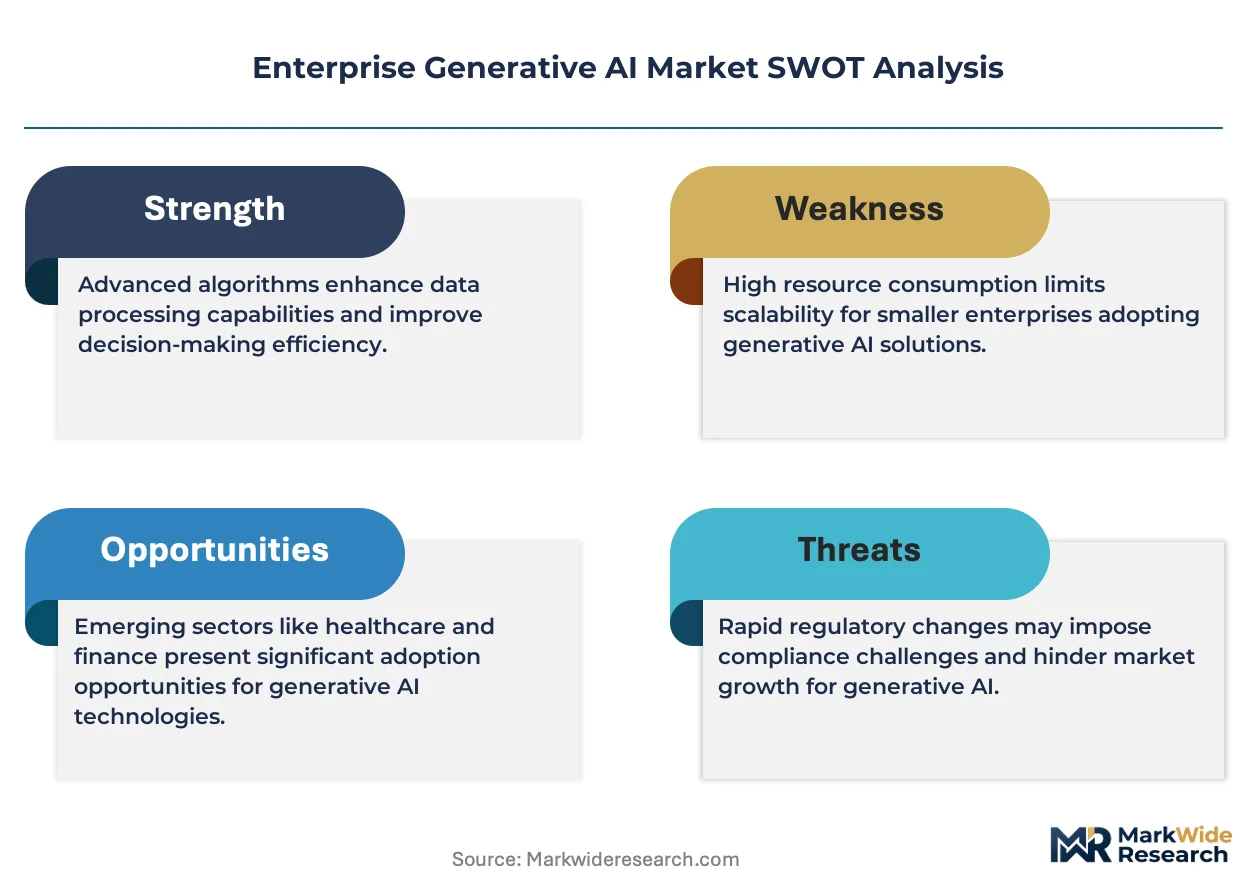
The EU AI Act imposes conformity obligations on high-risk enterprise AI deployments, while the FDA scrutinizes clinical decision support tools in healthcare settings. China's SAMR enforces algorithmic recommendation provisions that affect multinational enterprise AI rollouts. Enterprise procurement teams must weigh regulatory fragmentation against centralized model governance architectures as deployment scales.
Market Dynamics
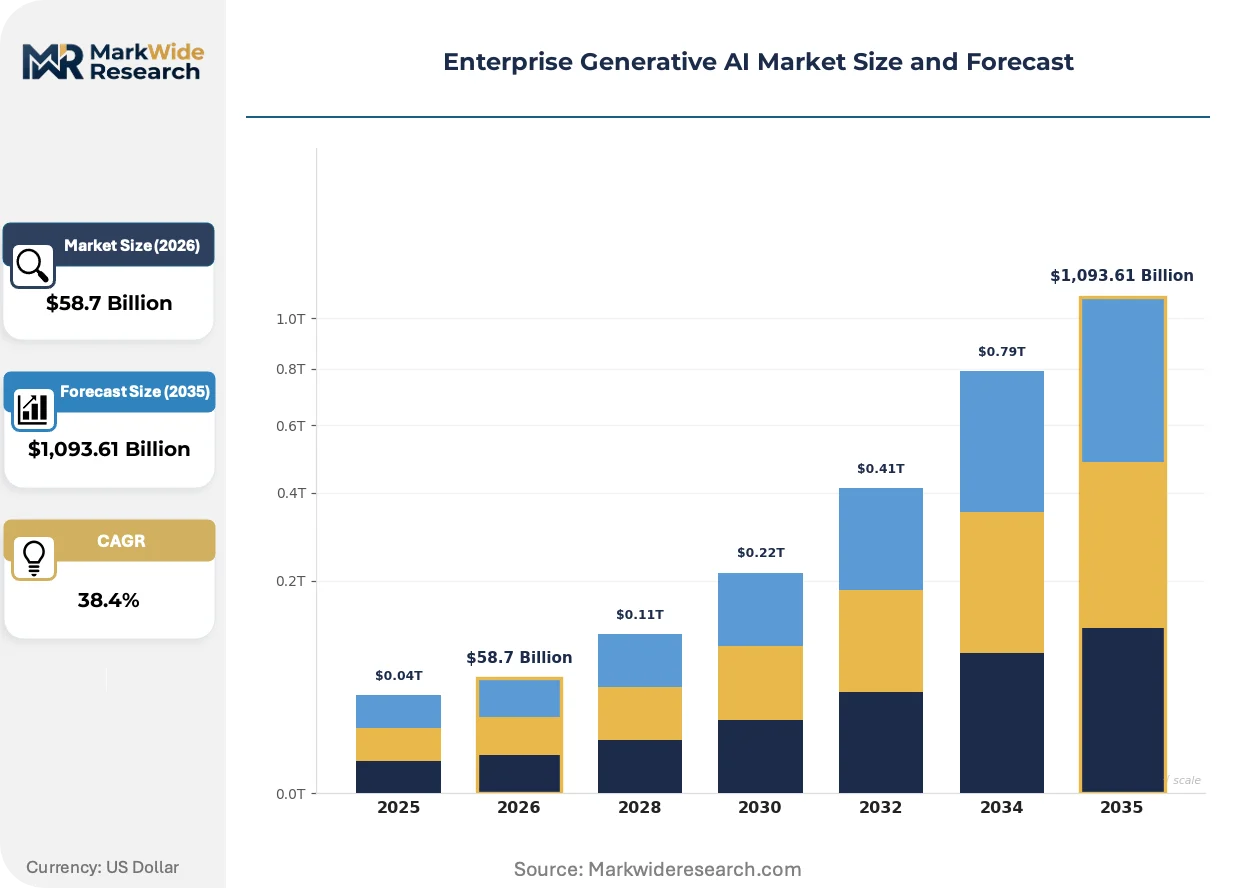
Foundation model fine-tuning is compressing the cost curve for enterprise AI deployment, allowing proprietary data integration without billion-dollar training runs. This structural shift redistributes value from model creators to infrastructure orchestrators and domain-specific application layers.
Growth Catalysts
- EU AI Act compliance mandates:High-risk classification requirements for automated decision systems are accelerating procurement of auditable AI governance platforms across financial services and healthcare sectors.
- Retrieval-augmented generation pipelines:Enterprise knowledge bases connect to large language models through vector database architectures, enabling hallucination-resistant outputs for legal and regulatory documentation.
- United States cloud infrastructure concentration:Hyperscale providers bundle compute credits with pre-trained model APIs, reducing friction for mid-market enterprise adoption.
Market Restraints
- NVIDIA silicon dependency:CUDA ecosystem lock-in constrains hardware substitution options, concentrating inference cost structures among GPU-dependent architectures.
- Training data licensing friction:Copyright disputes over web-scraped corpora create legal exposure for commercial model deployment, particularly in publishing and media verticals.
- Transformer architecture energy intensity:Datacenter power consumption for inference at scale encounters grid capacity constraints in Northern Virginia and Frankfurt clusters.
Strategic Opportunities
- India's BFSI digitization wave:RBI regulatory sandbox provisions enable pilot deployments of generative credit scoring and KYC automation for domestic banks.
- Edge inference hardware convergence:On-device model compression techniques combine with specialized neural processing units to enable manufacturing floor deployments without cloud connectivity.
- Japan METI AI governance guidelines:Voluntary human-in-the-loop standards create preferred vendor status for constitutionally aligned model providers in automotive and robotics supply chains.
Industry Challenges
- Prompt engineering talent scarcity:Enterprise IT organizations lack personnel capable of optimizing chain-of-thought reasoning pipelines for production reliability targets.
- HIPAA-aligned hybrid infrastructure:Healthcare providers face eighteen-month procurement cycles to deploy patient-facing generative tools with compliant data residency architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Generative AI Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $1,093.61 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Healthcare, BFSI, Retail, Manufacturing Technology: Natural Language Processing, Computer Vision, Deep Learning, Reinforcement Learning Application: Content Generation, Chatbots, Predictive Analytics, Automated Design |
| Companies Covered | OpenAI, Microsoft Corporation, Google LLC, Amazon Web Services, IBM Corporation, NVIDIA Corporation, Oracle Corporation, Anthropic, H2O.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Generative AI Market Evolving Landscape
Generative AI deployment patterns are fragmenting across architectural approaches, with enterprises rejecting one-size-fits-all cloud APIs in favor of composable, controllable inference stacks.
Small language models is hybridizing enterprise AI strategies by delivering task-specific performance at fractional inference cost. Manufacturing quality engineers deploy sub-10B parameter models for defect classification on factory floors. This compression is hybridizing the competitive landscape between centralized cloud APIs and distributed edge deployments.
EU AI Act conformity assessment procedures are restructuring procurement documentation requirements for high-risk applications. Financial services firms must maintain technical logs and human oversight protocols for automated credit decisions. German automotive suppliers are front-loading compliance investments to secure CE-marking equivalence for AI-enabled driver monitoring systems.
Enterprise buyers are unbundling model performance from infrastructure lock-in through portable fine-tuning artifacts. Procurement teams negotiate inference contracts across multiple cloud providers using standardized adapter weights. This flexibility is most pronounced among Series C software vendors in the United States seeking to avoid single-provider dependency.
Enterprise Generative AI Market Segmentation
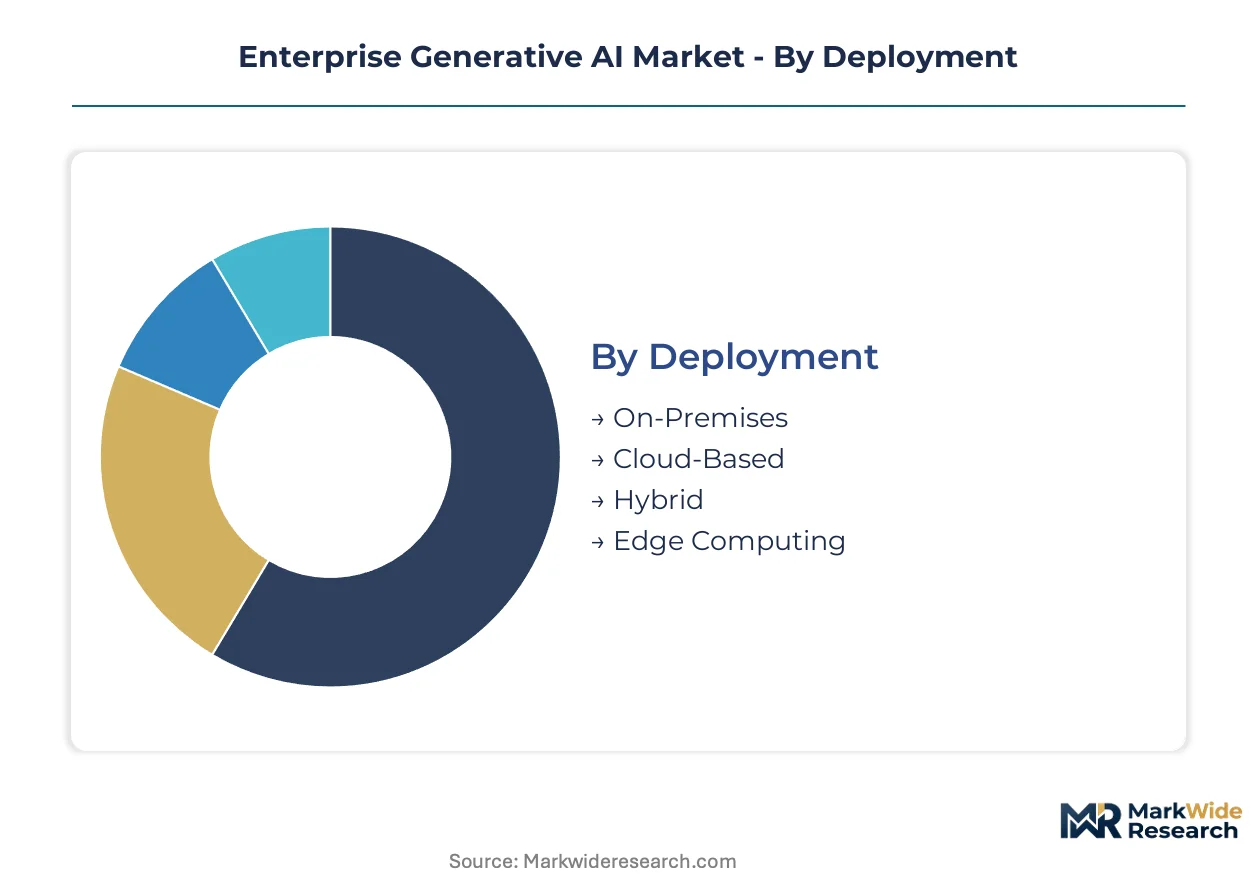
Enterprise generative AI procurement decisions fragment across infrastructure topology, regulatory exposure, and workflow integration depth. Buyers weigh data residency mandates against inference latency requirements when mapping segments to operational priorities.
Deployment:
Use-case spectrum spans air-gapped defense installations to globally distributed SaaS inference endpoints.
- On-Premises:Dedicated GPU clusters within enterprise data centers support classified government workloads and proprietary model fine-tuning. Financial services firms in Frankfurt and Singapore deploy these configurations to satisfy SAMR and EU AI Act data localization mandates.
- Cloud-Based:Hyperscale API consumption eliminates capital expenditure for model training infrastructure. United States mid-market software vendors concentrate procurement here, leveraging Azure and AWS model marketplaces for rapid prototyping.
- Hybrid:Sensitive data processing remains on-premises while model serving shifts to cloud edge nodes. Healthcare providers in Northern Virginia and London use this architecture to partition HIPAA-protected patient records from public inference workloads.
- Edge Computing:Compressed models execute on factory-floor neural processing units without connectivity. Japanese automotive suppliers deploy these for real-time weld inspection in Yokohama assembly plants.
The dominant share belongs to Cloud-Based, while Edge Computing is closing the gap fastest.
End User:
Customer archetypes diverge sharply in procurement cycle length and compliance burden.
- Healthcare:Clinical decision support tools face FDA premarket scrutiny and eighteen-month validation timelines. Mayo Clinic and Cleveland Clinic pilots concentrate on radiology report generation.
- BFSI:Automated credit scoring and KYC document processing absorb the majority of professional services integration spend. RBI sandbox provisions in Mumbai accelerate domestic bank deployments.
- Retail:Product description generation and demand forecasting drive adoption. Brief treatment: European luxury houses deploy multilingual content pipelines for catalog localization.
- Manufacturing:Quality inspection and predictive maintenance command capital budgets. Brief treatment: German automotive tier-1s prioritize CE-marked AI for driver monitoring systems.
BFSI captures the largest integration services wallet share, with Manufacturing expanding most quickly on edge inference investments.
Technology:
Technical layer selection determines model capabilities and computational requirements.
- Natural Language Processing:Transformer architectures power contract analysis, compliance documentation, and customer service automation. Legal departments in New York and London deploy these for due diligence acceleration.
- Computer Vision:Convolutional and vision-transformer models enable defect detection and medical imaging interpretation. Shenzhen electronics manufacturers lead volume deployment for PCB inspection.
- Deep Learning:Multi-layer neural networks underpin recommendation engines and fraud detection. Brief treatment: Payment processors in Bangalore embed these in transaction scoring pipelines.
- Reinforcement Learning:Reward-optimized agents refine supply chain and pricing decisions. Brief treatment: Energy traders in Houston deploy these for electricity market bidding strategies.
Natural Language Processing holds established revenue leadership, though Computer Vision is gaining share fastest on manufacturing quality budgets.
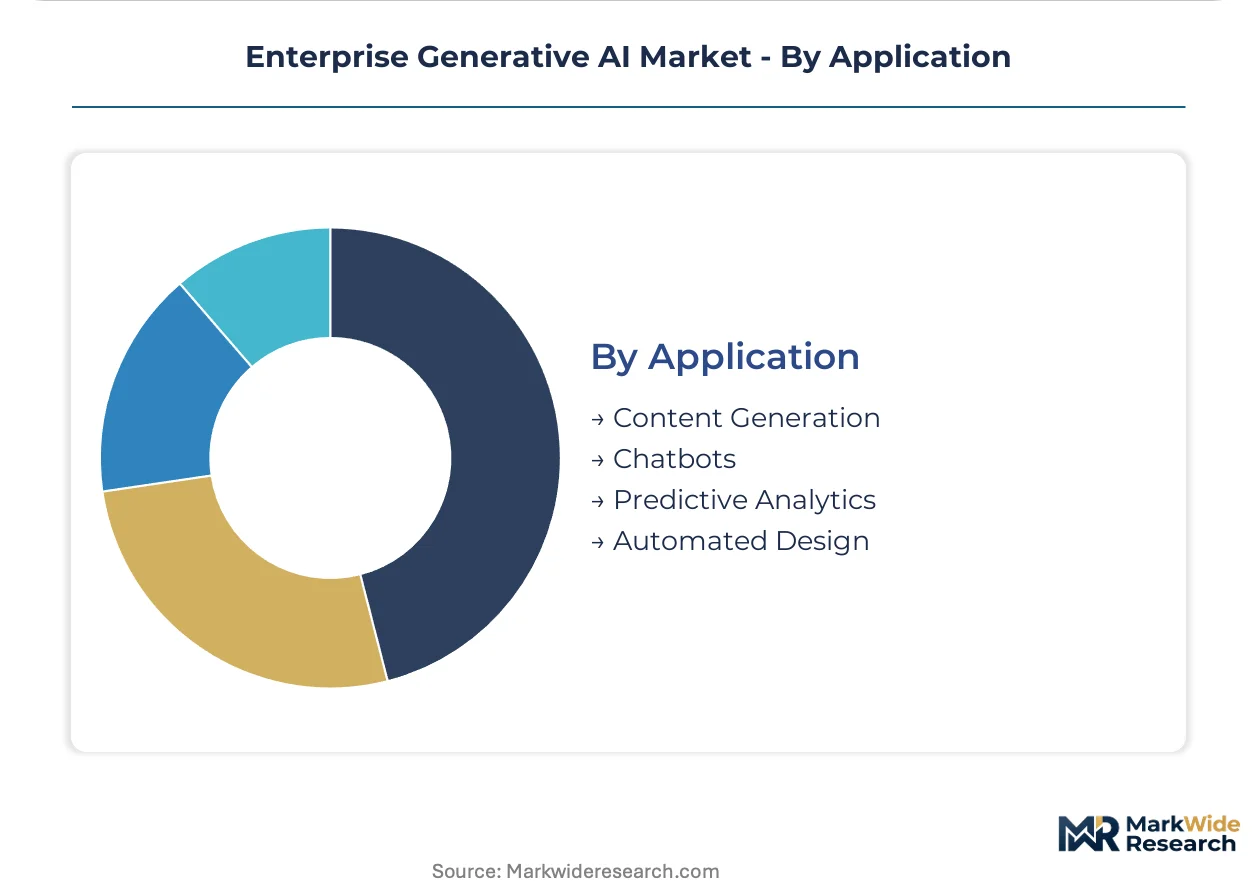
Application:
Functional use cases map to distinct ROI measurement frameworks and implementation risks.
- Content Generation:Marketing copy, code synthesis, and regulatory filing drafts reduce professional labor hours. Media conglomerates in Los Angeles negotiate licensing terms to mitigate copyright exposure from training data provenance.
- Chatbots:Customer service automation replaces tier-1 support interactions. Telcos in São Paulo and Jakarta deploy multilingual variants for emerging market subscriber bases.
- Predictive Analytics:Forecasting models inform inventory and workforce planning. Brief treatment: Retailers in Dubai use these for luxury goods demand sensing.
- Automated Design:Generative models accelerate CAD iteration and molecular discovery. Brief treatment: Pharmaceutical R&D teams in Basel integrate these into compound screening workflows.
Chatbots dominate deployment volume, while Automated Design commands the steepest expansion trajectory on engineering productivity metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services and cloud infrastructure providers concentrate procurement authority in the United States, while EU AI Act compliance mandates reshape European buying criteria. Healthcare providers in Northern Virginia and Frankfurt drive hybrid deployment architectures. Manufacturing quality engineers in Yokohama and Shenzhen accelerate edge inference adoption.
United States
Hyperscale cloud providers and enterprise software vendors anchor the deepest integration partnerships. FDA scrutiny of clinical decision support tools constrains healthcare deployment timelines. Mayo Clinic and Cleveland Clinic pilots in Minnesota and Ohio concentrate on radiology report generation with eighteen-month validation cycles.
Germany
Automotive tier-1 suppliers front-load compliance investments for AI-enabled driver monitoring systems. KBA and EU AI Act conformity assessments mandate technical logs and human oversight protocols. Frankfurt financial services firms deploy on-premises GPU clusters to satisfy data localization requirements.
China
Shenzhen electronics manufacturers lead volume deployment of computer vision models for PCB inspection. SAMR enforces algorithmic recommendation provisions affecting multinational enterprise AI rollouts. Yangtze River Delta industrial clusters absorb compressed models for factory-floor defect classification.
Japan
Automotive and robotics supply chains prioritize METI AI governance guidelines for human-in-the-loop standards. Yokohama assembly plants deploy edge inference hardware for real-time weld inspection without cloud connectivity. Kanto region suppliers secure preferred vendor status through constitutional alignment certifications.
India
Domestic banks accelerate generative credit scoring and KYC automation through RBI regulatory sandbox provisions. Mumbai financial services firms absorb the majority of professional services integration spend. Bangalore payment processors embed deep learning models in transaction scoring pipelines.
Enterprise Generative AI Market Competitive Landscape
Channel-controlling players compete with product-specialist players across infrastructure orchestration and domain-specific application layers. Hyperscale cloud providers bundle compute credits with pre-trained model APIs, reducing friction for mid-market adoption. Specialized silicon vendors and safety-focused model providers constitute distinct strategic archetypes. Competitive moves concentrate on strategic partnerships for regulatory compliance and portfolio diversification across deployment topologies.
Within the hyperscale infrastructure tier, Microsoft Corporation and Amazon Web Services occupy positions as cloud-native platform anchors. NVIDIA Corporation exemplifies the specialized silicon archetype through CUDA ecosystem concentration. Anthropic sits within the safety-aligned model provider category, targeting regulated industry procurement cycles.
| Leading Market Players |
|---|
| OpenAI |
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services |
| IBM Corporation |
| NVIDIA Corporation |
| Oracle Corporation |
| Anthropic |
| H2O.ai |
| Others |
Value Network & Pricing Analysis
NVIDIA's CUDA ecosystem concentration in Santa Clara anchors downstream margin pools across inference-as-a-service providers and domain-specific application vendors. Foundry capacity for advanced AI accelerators remains the binding constraint, redistributing pricing power toward silicon orchestrators and away from pure-play model developers.
Pricing Analysis
Cost-plus contracts with NVIDIA H100 indexation dominate enterprise procurement for training clusters, while inference workloads shift toward consumption-based SaaS tiers with volume discounts. Price differentiation hinges on model performance benchmarks and EU AI Act conformity certification tiers. Pricing pressure stems from AMD MI300 competitive entry and custom silicon programs at hyperscalers. Mid-market software vendors exhibit highest price sensitivity, whereas regulated BFSI buyers prioritize auditability over unit economics.
Supply Chain Analysis
Upstream feedstock for AI accelerators concentrates in Taiwan (TSMC foundry), South Korea (SK Hynix HBM), and the United States (NVIDIA design, Applied Materials equipment). Advanced packaging substrates, high-bandwidth memory stacks, and EUV lithography systems constitute critical input dependencies. Single-source vulnerability around CoWoS advanced packaging creates bottleneck risk for training cluster deployments. Distribution runs through direct hyperscale procurement contracts and tier-1 systems integrators serving enterprise on-premises deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as enterprise IT budget freezes from prior periods unwind and GPU supply constraints ease. Capital expenditure normalization at hyperscalers provides the cyclical driver.
For Market Incumbents: Harden API pricing structures against open-source model commoditization by embedding retrieval-augmented generation pipelines into vertical workflows. Deepen compliance investments for EU AI Act high-risk classification to create switching costs. Prioritize certification lock-in over raw inference cost competition.
For New Entrants and Emerging Players: Build out edge inference optimization capabilities for manufacturing quality inspection, the fastest-expanding margin pool with limited incumbent presence. Target German automotive tier-1 suppliers seeking CE-marked AI for driver monitoring systems. Lead with on-device model compression as the go-to-market differentiator against cloud-heavy incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward constitutionally aligned model providers with existing regulatory relationships in BFSI and healthcare. Long-term viability across the projection horizon rests on compliance infrastructure rather than raw parameter scale. Monitor FDA premarket approval timelines for clinical decision support tools as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Constitutional AI Certification | Anthropic's safety frameworks create preferred vendor status for EU AI Act high-risk deployments in Frankfurt financial services. |
| Retrieval-Augmented Generation Integration | Vector database partnerships with Pinecone and Weaviate reduce hallucination liability for legal documentation automation. |
| Edge Inference Hardware Convergence | Qualcomm and MediaTek neural processing units enable Yokohama automotive suppliers to deploy weld inspection without cloud connectivity. |
| Hybrid Cloud Architecture Deployment | HIPAA-aligned data residency configurations capture eighteen-month procurement cycles at Mayo Clinic and Cleveland Clinic. |
| Regulatory Sandbox Participation | RBI provisions accelerate domestic bank pilots for generative credit scoring in Mumbai BFSI clusters. |
Research Methodology
The analysis maps foundation model providers, vector database architectures, and edge inference hardware, each validated through primary interviews with enterprise AI procurement officers, cloud platform engineers, regulatory compliance leads, and semiconductor supply chain managers. Secondary validation draws from SEC hyperscaler capex disclosures, EU AI Act implementation guidance, FDA premarket submission databases, and RBI sandbox participant announcements. Bottom-up deployment volume estimates triangulate against top-down infrastructure spending projections.
Assumptions held fixed include transformer architecture dominance and CUDA ecosystem persistence, while variables tested include open-source model competitive pressure and regional regulatory fragmentation. Segmentation dimensions span deployment topology, end-user vertical, technology layer, and application function across the projection horizon. CAGRs derive from inference demand elasticity curves and enterprise adoption S-curve modeling. Forecast inputs incorporate datacenter power capacity constraints in Northern Virginia and Frankfurt clusters.
Sensitivities concentrate around EU AI Act enforcement timing, NVIDIA manufacturing yield improvements, and enterprise IT budget recalibration. Cross-checking against hyperscaler capex guidance and foundry revenue allocation is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market