
 Legal AI Market | 2026-2036
Legal AI Market Size, Share, and Industry Trends Forecast 2026-2036
Legal AI Market Analytics
Attorney proficiency with generative AI tools is rotating from a bottleneck into a competitive differentiator as firms race to deploy machine-learning systems. Harvey leverages its specialized focus on large-language-model applications for legal reasoning to anchor premium positioning among Am Law 100 firms. Ironclad competes through deep integration with enterprise contract lifecycle management, while Clio sustains dominance in practice-management automation for mid-sized law firms across North America.
Legal AI denotes software systems that apply natural language processing and machine learning to analyze statutes, precedents, and contractual provisions with semantic comprehension comparable to trained lawyers. These systems automate document drafting, due diligence, and litigation prediction to compress billable hours and reduce error rates in high-stakes legal work. Document automation occupies the largest revenue pool among application types, reflecting relentless pressure on law firms to cut routine drafting costs. E-discovery represents the fastest-expanding segment as data volumes in litigation explode and courts tighten deadlines for production. Among end users, corporate legal departments now outpace law firms in deployment velocity, driven by general counsel mandates to bring contract review in-house.
The EU AI Act imposes risk-classification requirements on legal AI tools used in judicial and administrative contexts, forcing vendors to redesign transparency and human-oversight features for European market access. The SEC in the United States and comparable securities regulators elsewhere scrutinize AI-generated disclosures, elevating liability concerns that shape product architecture. Stakeholders must monitor how divergent regulatory timelines across jurisdictions fragment compliance architectures and determine which vendors can sustain cross-border deployment without engineering redundant systems.
Market Dynamics
Corporate legal departments are compressing contract review cycles from weeks to hours, forcing vendors to reengineer products for non-lawyer users rather than traditional attorney workflows.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for judicial AI tools are forcing European enterprises to upgrade contract analysis systems, creating replacement demand across Germany, France, and the Netherlands.
- SEC disclosure scrutiny:Securities regulators are elevating liability for AI-generated filings, compelling issuers to deploy verified document automation for 10-K and proxy statement preparation.
- Enterprise CLM integration:Deep embedding of legal AI into Salesforce and SAP contract modules is accelerating procurement decisions by general counsel at Fortune 500 manufacturers.
Market Restraints
- Training data access costs:Curated legal corpus licensing from Westlaw and LexisNexis consumes 35-50% of vendor R&D budgets, squeezing mid-tier competitors.
- Compute infrastructure concentration:GPU cluster availability concentrates in Northern Virginia and Singapore data centers, creating latency and sovereignty barriers for EU and Middle Eastern deployments.
- Judicial skepticism of machine outputs:Federal district courts in the Southern District of New York and Eastern District of Texas are imposing heightened scrutiny on AI-assisted briefs, chilling adoption in high-stakes litigation.
Strategic Opportunities
- India legal process outsourcing:Mumbai and Bangalore legal services hubs are integrating AI-assisted contract review for US and UK clients, creating demand for localized NLP models trained on Commonwealth precedents.
- Convergence of NLP and knowledge graphs:Combining transformer architectures with structured regulatory databases enables real-time compliance monitoring for financial services clients navigating overlapping state and federal rules.
- Alternative legal service provider channel:Elevate, Axiom, and similar ALSPs are white-labeling AI tools for captive law firm networks, bypassing traditional direct-to-firm sales cycles.
Industry Challenges
- Prompt engineering talent scarcity:Firms competing for technical staff capable of tuning large language models for legal reasoning face compensation premiums of 40-60% above general software engineering roles.
- Multi-jurisdictional certification timelines:Vendors seeking approval for EU AI Act high-risk system classification face 18-24 month conformity assessment processes that delay revenue recognition.
- Legacy document management integration:iManage and NetDocument repositories at Am Law 200 firms require custom API development that extends implementation cycles and erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legal AI Market |
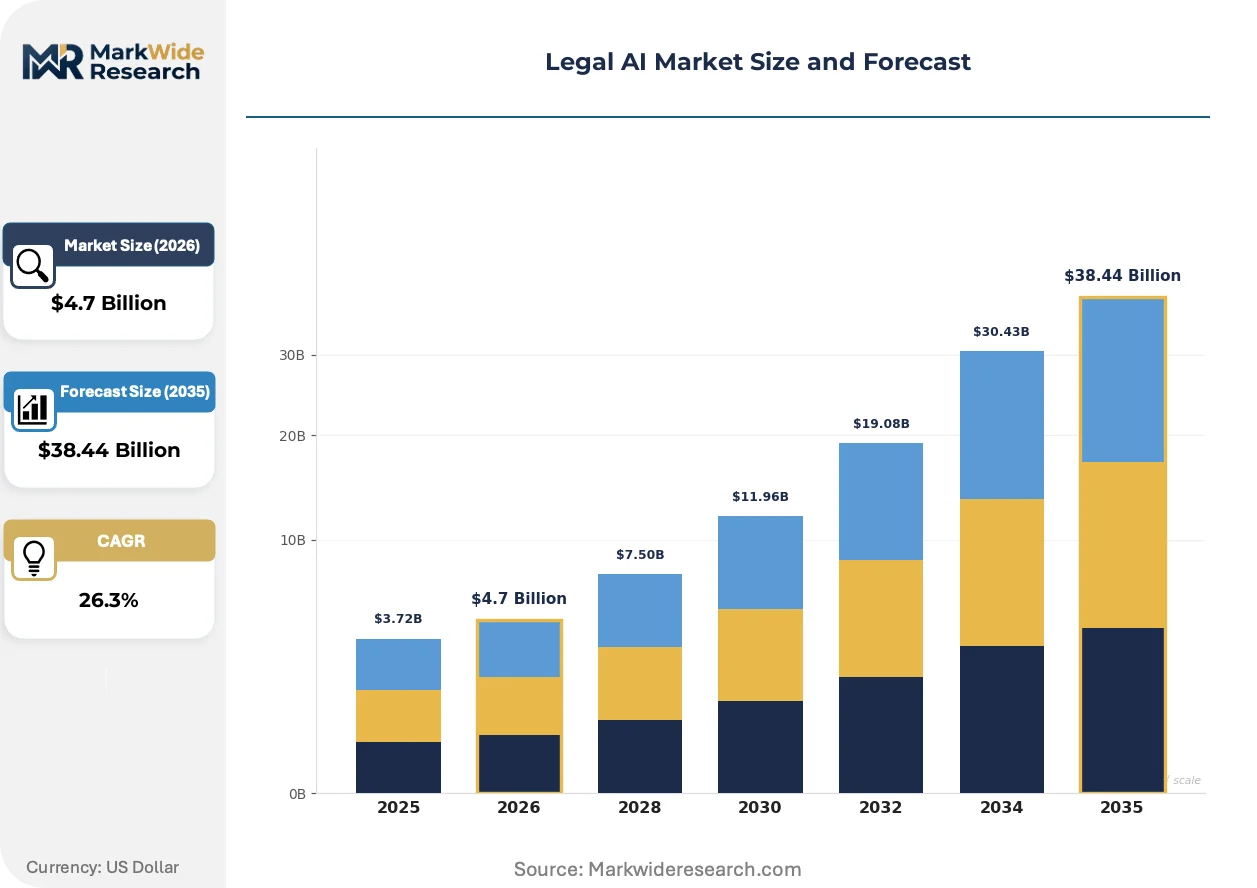
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 26.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Document Automation, Contract Review, Legal Research, E-Discovery End User: Law Firms, Corporate Legal Departments, Courts, Government Agencies Technology: Machine Learning, Natural Language Processing, Blockchain, Predictive Analytics Service Type: Consulting, Implementation, Managed Services, Training |
| Companies Covered | Everlaw, Darrow, Brightflag, Paxton, Ironclad, Harvey, Clio, LegalMation, Relativity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legal AI Market Evolving Landscape
Foundation model architectures are migrating from general-purpose to domain-specific training, with legal AI vendors racing to differentiate through proprietary reasoning capabilities rather than raw parameter scale.
Retrieval-augmented generation is miniaturizing the footprint of deployable legal AI systems. These architectures ground outputs in verified case law and contract clauses rather than parametric knowledge. Mid-sized firms in Texas and Illinois are adopting RAG-based tools at triple the pace of full fine-tuned models. The technology is miniaturizing infrastructure requirements, enabling on-premise deployment for clients with stringent data residency requirements.
The EU AI Act's high-risk system obligations are restructuring product development roadmaps. Vendors must embed human-in-the-loop checkpoints and explainability features for any tool used in judicial or administrative proceedings. European legal departments are demanding audit trails that satisfy national supervisory authorities in Germany, France, and Italy. This regulatory pressure is fragmenting product architectures between EU-compliant and rest-of-world versions.
General counsel are unbundling AI tool procurement from traditional law firm relationships. Enterprise legal teams are negotiating direct SaaS contracts with Harvey, Ironclad, and competitors, bypassing partner-led technology committees. This disintermediation concentrates buying power inside procurement departments with standardized security review processes. The shift is most visible among technology and pharmaceutical companies in California and Massachusetts with mature legal operations functions.
Legal AI Market Segmentation
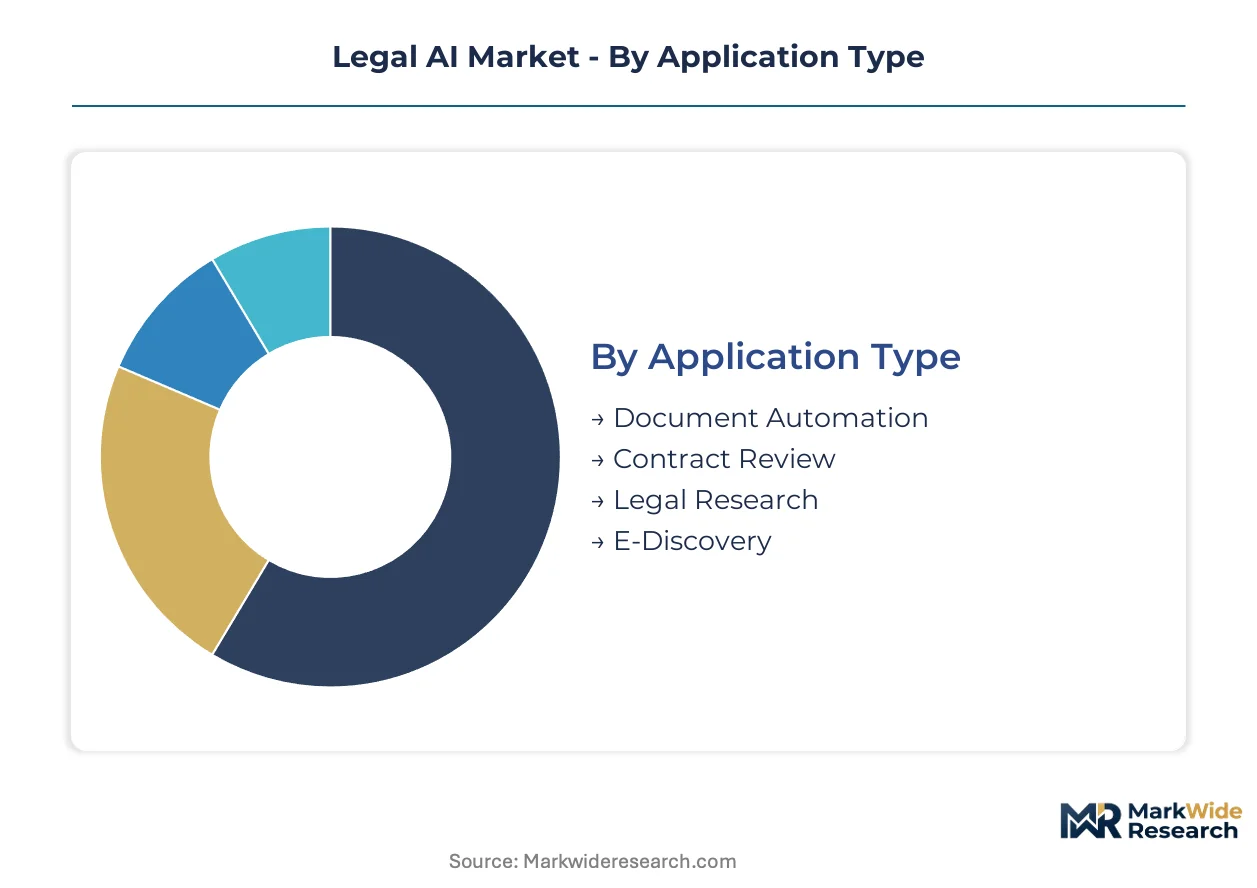
Segmentation in legal AI reveals how regulatory pressure and workflow fragmentation create divergent product requirements across user types. Vendors must architect separate compliance layers for EU high-risk classifications versus US securities disclosure standards.
Application Type:
EU AI Act risk tiers reshape feature roadmaps differently across use cases, with judicial-facing tools bearing heavier human-in-the-loop mandates than internal corporate workflows.
- Document Automation:Systems generate contracts, briefs, and regulatory filings through template-driven natural language generation. Corporate legal departments in Germany and France dominate procurement, driven by CSRD sustainability reporting deadlines and EU AI Act documentation requirements. Established volume favors Document Automation; emerging adoption favors E-Discovery.
- E-Discovery:Machine learning classifies, deduplicates, and prioritizes electronically stored information for litigation production. Southern District of New York and Eastern District of Texas federal courts are tightening scrutiny on AI-assisted privilege logs, creating compliance friction that slows deployment despite exploding data volumes.
- Contract Review:NLP engines extract obligations, risks, and deviations from third-party paper and standard templates.
- Legal Research:Semantic search surfaces precedents, statutes, and secondary sources with contextual relevance ranking.
Cost tier separation distinguishes high-touch consulting engagements from self-service SaaS subscriptions.
End User:
Procurement authority is migrating from partner-led technology committees to centralized legal operations functions with standardized vendor security assessments.
- Corporate Legal Departments:In-house teams at Fortune 500 manufacturers and pharmaceutical companies in California and Massachusetts negotiate direct SaaS contracts, bypassing traditional law firm intermediaries. General counsel mandates to compress contract cycles from weeks to hours accelerate deployment of non-lawyer-facing interfaces.
- Law Firms:Am Law 100 and mid-sized practices in Texas and Illinois adopt retrieval-augmented generation tools at divergent paces, with premium firms investing in on-premise deployments for client confidentiality assurance. Billing model disruption from flat-fee AI outputs creates partnership resistance at traditional practices.
- Courts:Judicial administrators deploy AI for case management, scheduling optimization, and limited decision support.
- Government Agencies:Administrative bodies utilize legal AI for regulatory drafting, enforcement prioritization, and public access tools.
Margin concentration sits with Corporate Legal Departments; capability building urgency defines Government Agencies.
Technology:
Foundation model architectures are fragmenting between general-purpose APIs and domain-specific legal reasoning systems with proprietary training corpora.
- Natural Language Processing:Transformer-based models parse statutory language, contractual provisions, and judicial opinions with semantic comprehension comparable to trained attorneys. Westlaw and LexisNexis curated corpus licensing consumes substantial R&D investment, creating moats for established vendors.
- Machine Learning:Supervised and unsupervised algorithms power litigation outcome prediction, pricing optimization, and client matter forecasting. Predictive Analytics climbs fastest as general counsel demand data-driven budget certainty for complex litigation portfolios.
- Predictive Analytics:Statistical models forecast case outcomes, settlement ranges, and resource allocation requirements.
- Blockchain:Distributed ledger technology enables tamper-evident contract execution and automated dispute resolution through smart contracts.
Maturity hierarchy places NLP at deployment scale; Blockchain remains experimental.
Service Type:
Customer lifecycle stage determines service mix, with implementation and training dominating early adoption and managed services capturing expansion revenue.
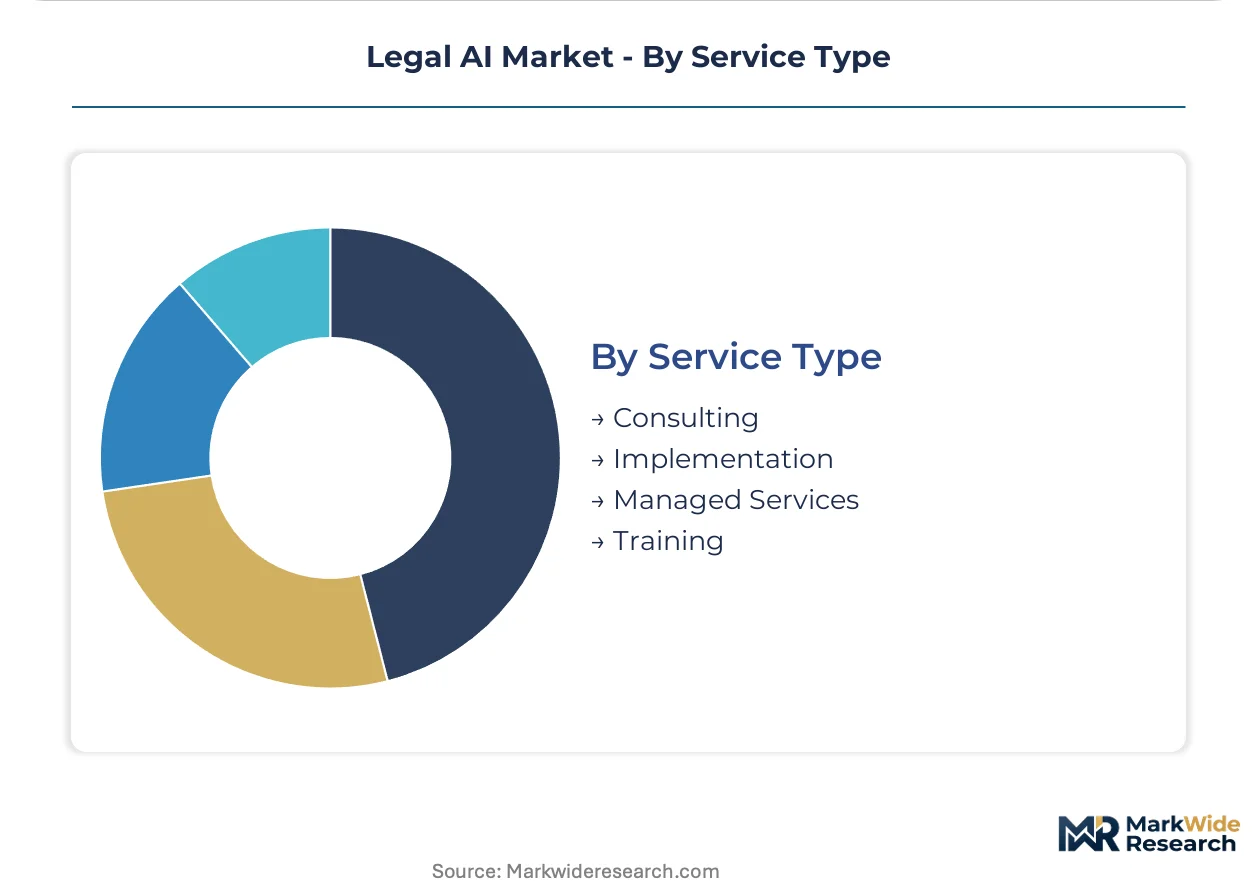
- Implementation:Systems integration with iManage and NetDocument repositories at Am Law 200 firms requires custom API development that extends project timelines. Legacy document management compatibility constraints erode project margins for mid-tier vendors lacking pre-built connectors.
- Consulting:Change management and workflow redesign services help legal departments restructure attorney roles around AI-augmented processes. Alternative legal service providers white-label these capabilities for captive law firm networks, compressing traditional direct sales cycles.
- Training:Prompt engineering and model tuning instruction builds internal competency for sustained system optimization.
- Managed Services:Ongoing monitoring, model retraining, and regulatory update integration delivered under recurring contracts.
Revenue recurrence favors Managed Services; margin expansion favors Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate legal departments in the United States deploy legal AI for contract lifecycle acceleration, while European enterprises prioritize compliance-first architectures under the EU AI Act, and Indian legal process outsourcing hubs integrate AI-assisted review for Commonwealth precedent analysis.
United States
Large law firms in New York and Washington, D.C. anchor domestic demand for document automation and litigation prediction tools. SEC disclosure scrutiny compels Fortune 500 issuers to deploy verified AI systems for 10-K and proxy statement preparation. Silicon Valley technology companies and Massachusetts pharmaceutical firms negotiate direct SaaS contracts with vendors, bypassing traditional law firm intermediaries.
Germany
Industrial manufacturers and automotive conglomerates drive procurement of contract analysis systems to meet CSRD sustainability reporting deadlines. The EU AI Act risk-classification framework forces vendors to embed human-in-the-loop checkpoints and explainability features for judicial-facing tools. Frankfurt and Munich legal departments concentrate replacement demand as enterprises upgrade legacy systems for European market access.
United Kingdom
Magic Circle firms and alternative legal service providers in London adopt retrieval-augmented generation tools for Commonwealth precedent research. Post-Brexit regulatory divergence creates demand for dual-compliant systems satisfying both UK and EU algorithmic accountability standards. The City of London financial services cluster accelerates deployment of real-time compliance monitoring for overlapping regulatory regimes.
India
Mumbai and Bangalore legal services hubs integrate AI-assisted contract review for US and UK clients, creating demand for localized NLP models trained on Common Law precedents. The country's national technology regulator promotes domestic AI development through targeted incentive programs. Indian legal process outsourcing providers white-label foreign vendor tools for captive law firm networks, compressing traditional direct sales cycles.
France
Corporate legal departments in Paris prioritize EU AI Act conformity assessments for high-risk judicial AI applications. The national data protection authority enforces stringent audit trail requirements for automated decision systems used in administrative proceedings. Île-de-France enterprise legal teams negotiate standardized security reviews with procurement departments, concentrating vendor selection authority inside legal operations functions.
Legal AI Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with premium positioning concentrated among Am Law 100-focused vendors and mid-market penetration dominated by practice-management generalists. The market structure reflects divergent customer workflows: corporate legal departments demand deep enterprise software integration, while law firms prioritize attorney-facing reasoning interfaces. Three archetypes define competitive positioning: foundation-model specialists, contract lifecycle integrators, and practice-management platforms. Dominant competitive moves include strategic partnerships with document management repositories and geographic expansion through alternative legal service provider channels.
Within the foundation-model specialist tier, Harvey occupies a position exemplifying premium deployment among elite US law firms. Ironclad and Clio represent contrasting archetypes—Ironclad anchors contract lifecycle integration for enterprise procurement teams, while Clio exemplifies practice-management automation scale across North American mid-sized firms. These three companies collectively illustrate how vendor specialization around distinct legal workflows fragments competitive dynamics despite shared underlying NLP capabilities.
| Leading Market Players |
|---|
| Everlaw |
| Darrow |
| Brightflag |
| Paxton |
| Ironclad |
| Harvey |
| Clio |
| LegalMation |
| Relativity |
| Others |
Value Network & Pricing Analysis
EU AI Act high-risk system classification gates both vendor qualification and price differentiation simultaneously, forcing enterprises to pay premiums for compliant architectures while squeezing mid-tier competitors unable to absorb conformity assessment costs. This regulatory threshold stratifies procurement decisions between multinational issuers with centralized legal operations and fragmented regional practices.
Pricing Analysis
Long-term SaaS contracts with annual escalators dominate enterprise procurement, though project-based implementation fees persist for legacy system integration. Three-tier pricing structure across premium, standard, and economy levels separates Harvey's Am Law 100 deployments from Clio's mid-market subscriptions and Ironclad's per-seat enterprise tiers. Pricing pressure stems from GPU cluster leasing costs concentrated in Northern Virginia and Singapore data centers. Corporate legal departments exhibit lowest price sensitivity due to general counsel mandates, while mid-sized Texas and Illinois firms negotiate hardest on implementation scope.
Supply Chain Analysis
Extended lead times for NVIDIA H100 GPU allocations stretch model training schedules, compressing vendor delivery windows. Curated legal corpus licensing draws from Westlaw and LexisNexis repositories in the United States, Commonwealth precedent databases in the United Kingdom, and domestic case law collections in Germany and France. Single-source vulnerability concentrates in Northern Virginia cloud infrastructure for US deployments and Frankfurt data centers for EU workloads. Distribution runs through direct SaaS contracts with enterprise legal departments, bypassing traditional law firm technology committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Legal AI represents a high-growth disruption anchored by generative AI capability inflection and EU AI Act compliance mandates reshaping procurement authority. Foundation model specialization and retrieval-augmented generation architectures are displacing general-purpose tool deployments.
For Market Incumbents: Fortify position through exclusive corpus licensing agreements with Westlaw and LexisNexis, locking training data access against emerging challengers. Build captive GPU clusters in Frankfurt and Singapore to circumvent latency barriers and data sovereignty requirements. Deepen API connectors for iManage and NetDocument repositories to accelerate implementation cycles and defend margins against mid-tier competitors. For New Entrants and Emerging Players: Anchor in India legal process outsourcing channels, where Mumbai and Bangalore hubs seek white-label AI tools for US and UK contract review. Target mid-sized Illinois and Texas law firms adopting retrieval-augmented generation at triple the pace of full fine-tuned models. Pursue alternative legal service provider partnerships with Elevate and Axiom to bypass traditional direct-to-firm sales cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across foundation model training and EU compliance certification, favoring scaled players with recurring revenue bases. Prioritize vendors with proven high-risk system conformity assessments and established procurement relationships with Fortune 500 general counsel. Monitor SEC disclosure scrutiny intensity as signal for document automation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Unlocks procurement from German automotive and French pharmaceutical legal departments facing high-risk system mandates. |
| Retrieval-Augmented Generation Deployment | Enables on-premise installation for Am Law 100 firms with stringent client confidentiality requirements. |
| Alternative Legal Service Provider Partnership | Compresses sales cycles through Elevate and Axiom white-label channels for captive law firm networks. |
| Curated Corpus Licensing Agreement | Secures moats against mid-tier competitors facing 35-50% R&D budget allocation to Westlaw and LexisNexis fees. |
| GPU Cluster Regionalization | Addresses latency and sovereignty barriers for EU and Middle Eastern deployments beyond Northern Virginia concentration. |
Research Methodology
Cross-validation between primary interviews with general counsel, legal operations directors, and Am Law 100 technology committees anchors the qualitative findings against secondary validation from SEC filings, EU AI Act implementation guidance, and hyperscaler capex disclosures. Bottom-up triangulation against top-down market sizing incorporates vendor revenue segmentation, procurement database analysis, and legal technology trade association surveys.
Sensitivity analysis across deployment model, organization size, and regional regulatory cluster shapes the analytical framework over the projection horizon. Modeled segmentation spans application type, end user archetype, and technology architecture, with CAGRs derived from adoption velocity differentials between corporate legal departments and law firm partnerships. Forecast inputs include GPU infrastructure availability curves and EU conformity assessment timeline distributions.
Decision-makers should treat outputs as directional under assumptions of sustained SEC disclosure scrutiny and EU AI Act enforcement continuity; material deviation in regulatory intensity or training data access costs would warrant model refresh. Specific vendor performance, partnership outcomes, and certification timelines introduce variance not captured in aggregate projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
AI Dubbing Software Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
AI Development Service Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market