
 AI in Robotics Market | 2026-2036
AI in Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Robotics Market Outlook
The gap between premium sensor-integrated robotic platforms and basic programmable arms is rebalancing procurement patterns across manufacturing floors. NVIDIA Corporation leverages GPU-accelerated perception stacks for real-time autonomous navigation. Boston Dynamics sustains leadership in legged locomotion systems for unstructured terrain operations. FANUC Corporation anchors volume production through its captive controller and servo motor supply chain.
AI in robotics denotes electromechanical systems embedding machine learning inference, computer vision pipelines, and adaptive control algorithms to execute tasks without deterministic programming. These systems process multimodal sensor inputs through neural networks to adjust grip force, path planning, and object recognition parameters in milliseconds. Industrial Automation applications currently dominate installed base volumes, while Medical Robotics segments command premium pricing due to FDA and EMA validation requirements. Machine Learning technology layers absorb the majority of R&D allocation, though Edge Computing deployments are expanding fastest in warehouse logistics settings where cloud latency proves prohibitive.
The EU AI Act, ISO 10218 safety standards, and OSHA workplace robotics guidelines collectively shape product certification timelines and liability frameworks for commercial deployment. Compliance with these overlapping regimes extends time-to-market by twelve to eighteen months for systems operating near human workers. Stakeholders must monitor divergence between regional conformity assessment procedures when scaling platforms across multiple jurisdictions.
Market Dynamics
The EU AI Act's mandatory conformity assessments are compressing time-to-market timelines while automotive manufacturers accelerate deployment of intelligent robotic systems on assembly lines. This regulatory pressure is reshaping competitive positioning between sensor-integrated platforms and basic programmable arms.
Growth Catalysts
- EU AI Act compliance mandates:High-risk autonomous machines now require mandatory conformity assessments, creating standardized procurement criteria for industrial buyers across Germany's automation corridor.
- Automotive assembly line automation:Manufacturers are embedding machine learning inference and computer vision pipelines into electromechanical systems for real-time adaptive control.
- Edge Computing expansion:Warehouse logistics operators are deploying neural network processing at the edge where cloud latency proves prohibitive for path planning and object recognition.
Market Restraints
- GPU supply concentration:Accelerated perception stacks depend on specialized semiconductor fabrication capacity concentrated in Taiwan and South Korea.
- Overlapping certification regimes:ISO 10218 safety standards, OSHA workplace robotics guidelines, and EU AI Act requirements collectively extend commercial deployment timelines by twelve to eighteen months.
- Legacy system integration costs:Deterministic programmable arms in installed bases require substantial capital expenditure to interface with adaptive AI control algorithms.
Strategic Opportunities
- Medical Robotics premium segments:FDA and EMA validation requirements create pricing power for systems achieving regulatory clearance in surgical and diagnostic applications.
- India's industrial automation corridor:PLI scheme incentives for manufacturing automation are attracting robotic system deployments in automotive and electronics assembly.
- 5G-private network convergence:Ultra-reliable low-latency communication is enabling cloud-native robotic control architectures that reduce on-board compute requirements.
Industry Challenges
- Multimodal sensor fusion expertise:The talent pool for integrating LiDAR, tactile arrays, and visual pipelines through neural networks remains concentrated among specialized research institutions.
- Cross-jurisdiction liability frameworks:Divergence between OSHA workplace guidelines and EU AI Act liability provisions complicates platform scaling across North American and European deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Robotics Market |
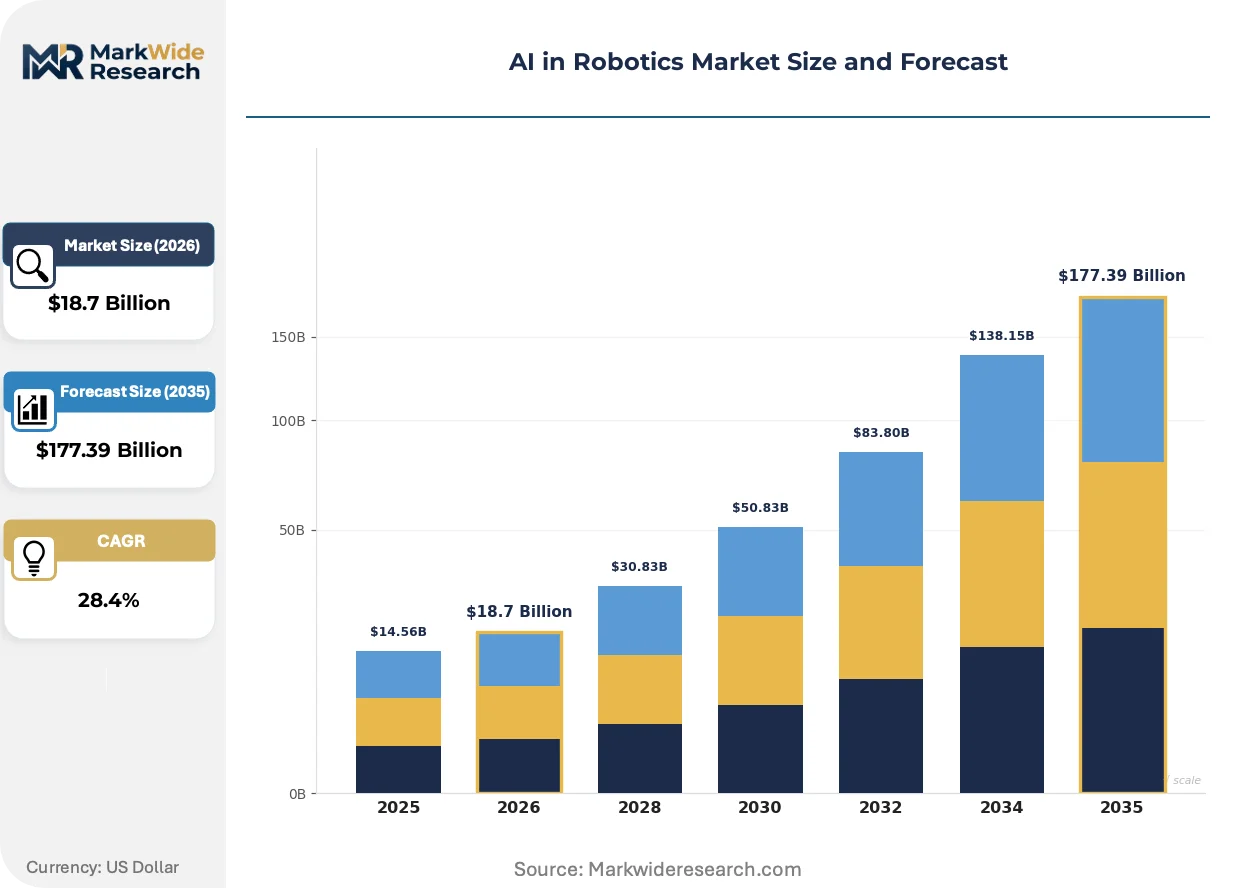
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Industrial Automation, Medical Robotics, Service Robots, Military Robotics Technology: Machine Learning, Computer Vision, Natural Language Processing, Edge Computing End User: Manufacturing, Healthcare, Logistics, Agriculture Product Type: Collaborative Robots, Autonomous Guided Vehicles, Drones, Humanoid Robots |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Boston Dynamics, FANUC Corporation, YASKAWA ELECTRIC CORPORATION, ABB, Tesla, SoftBank Robotics Group, Universal Robots A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Robotics Market Strategic Shifts
Foundation models trained on robotic manipulation datasets are compressing programming cycles from weeks to hours. This shift is altering how manufacturers evaluate total cost of ownership and supplier relationships.
Vision-language-action models are integrating pre-trained transformer architectures with proprioceptive feedback loops for zero-shot task generalization. Automotive tier-one suppliers are piloting these systems for bin-picking and assembly sequencing. The technology is integrating previously separate perception, planning, and control modules into unified inference pipelines.
The EU AI Act's risk-based classification system is mandating human oversight protocols for collaborative robots operating near workers. Industrial OEMs in Germany are redesigning safety architectures to satisfy conformity assessment requirements before CE marking. Medical device manufacturers face the strictest scrutiny, with high-risk autonomous surgical systems requiring notified body intervention at design phases.
Capital equipment buyers are unbundling after-sales service contracts from hardware procurement, favoring third-party maintenance providers with AI-driven predictive diagnostics. German automotive manufacturers are leading this transition, negotiating service-level agreements separate from robot arm purchases. The shift is most pronounced in high-volume production environments where downtime costs exceed hardware depreciation schedules.
AI in Robotics Market Segmentation
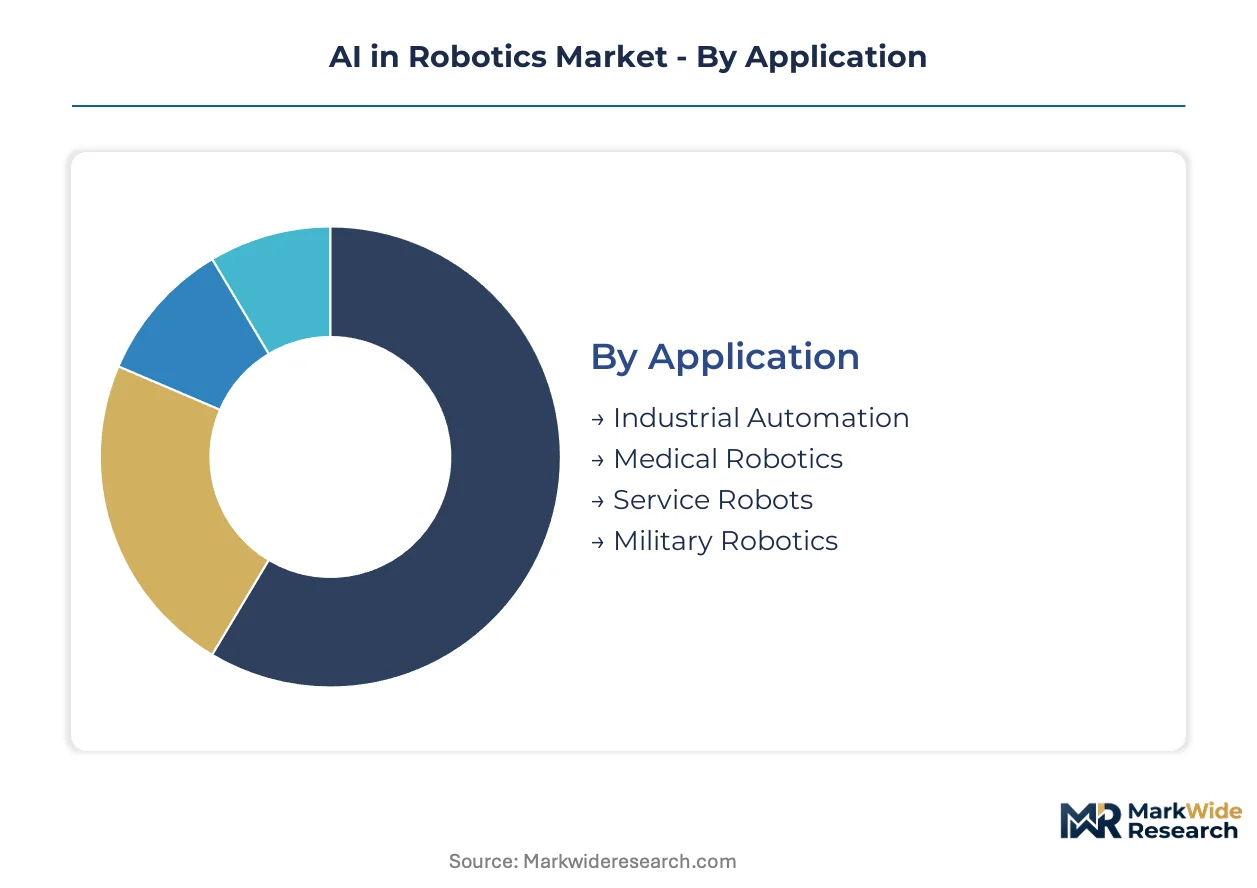
Segmentation in AI robotics reveals divergent technology requirements between volume manufacturing deployments and premium regulated applications. Procurement criteria vary sharply across safety-critical medical systems versus warehouse logistics platforms.
Application:
Industrial Automation commands installed base volumes while Medical Robotics extracts premium pricing through regulatory validation.
- Industrial Automation:Assembly line systems embed machine learning inference for adaptive grip force and path planning. Demand concentrates in Germany's automotive corridor around Stuttgart, where OEMs mandate ISO 10218 compliance for human-robot collaboration.
- Medical Robotics:Surgical and diagnostic platforms require FDA and EMA pre-market clearance with extensive clinical validation. Systems command pricing premiums in North American hospital networks where liability frameworks favor approved devices.
- Service Robots:Hospitality and retail automation platforms integrate natural language processing for customer interaction protocols.
- Military Robotics:Unmanned ground and aerial systems prioritize ruggedized edge computing for denied communication environments.
Mature deployment sits with Industrial Automation. Newer deployment is concentrated in Medical Robotics.
Technology:
Machine Learning absorbs dominant R&D allocation while Edge Computing expands fastest in latency-sensitive logistics settings.
- Machine Learning:Neural network training for manipulation tasks consumes GPU clusters and specialized semiconductor fabrication. Development concentrates in research institutions with multimodal sensor fusion expertise.
- Edge Computing:On-device inference reduces cloud dependency for real-time path planning in warehouse operations. Adoption accelerates where 5G-private network convergence enables distributed control architectures.
- Computer Vision:Real-time object recognition pipelines process LiDAR and camera inputs for autonomous navigation.
- Natural Language Processing:Voice command interfaces enable operator control without dedicated programming terminals.
Established deployment sits with Machine Learning. Steepest expansion trajectory belongs to Edge Computing.
End User:
Manufacturing anchors hardware volumes while Healthcare segments justify premium software and service contracts.
- Manufacturing:Automotive tier-one suppliers deploy adaptive control algorithms for bin-picking and assembly sequencing. Procurement concentrates in high-volume environments where downtime costs exceed hardware depreciation.
- Logistics:Warehouse operators demand millisecond-latency path planning for autonomous guided vehicle fleets. India's PLI scheme incentives are attracting robotic system deployments in electronics assembly.
- Healthcare:Hospital networks require FDA-cleared platforms with predictive maintenance capabilities.
- Agriculture:Precision farming applications integrate computer vision for crop monitoring and selective harvesting.
Volume concentration sits with Manufacturing. Margin expansion concentrates in Healthcare.
Product Type:
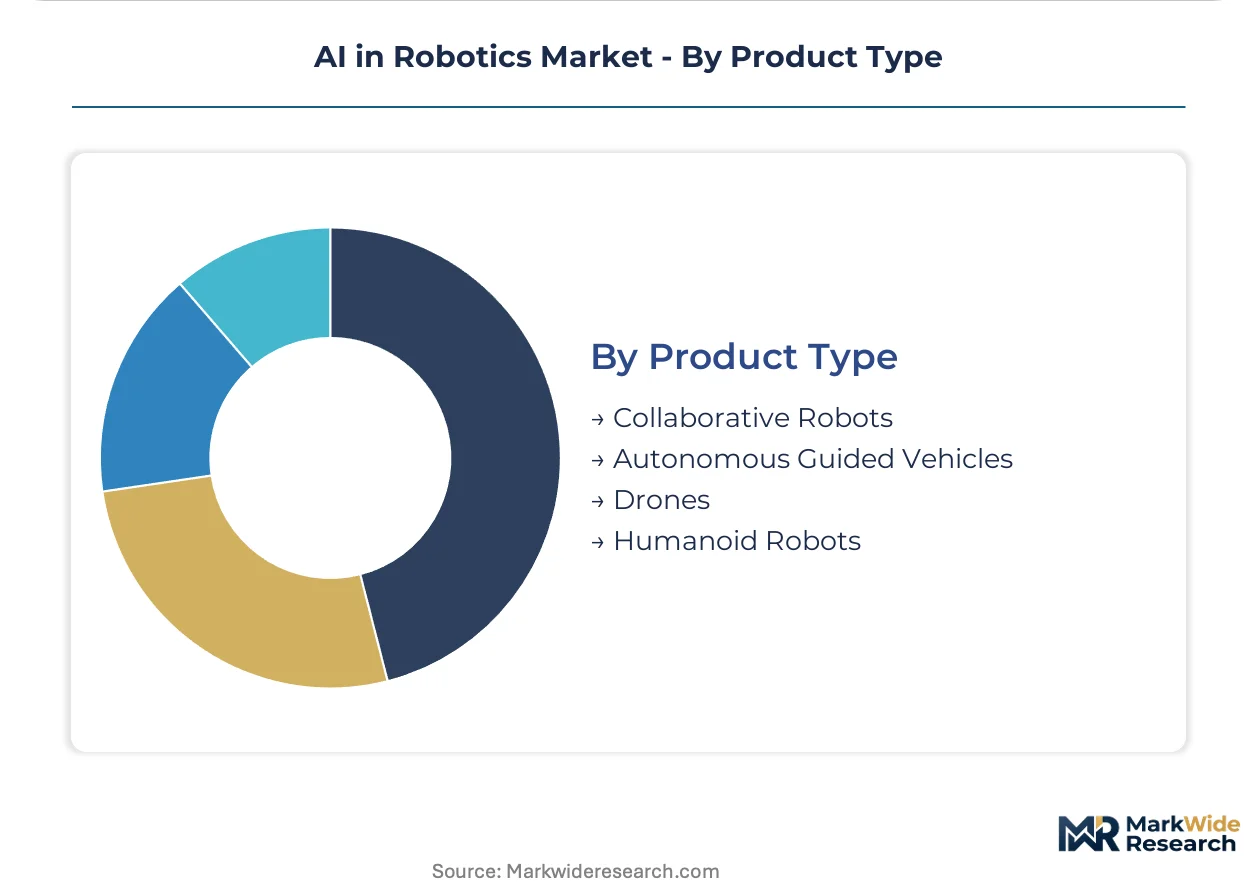
Collaborative Robots dominate unit shipments while Humanoid Robots capture development attention for unstructured terrain.
- Collaborative Robots:Force-limited arms operate alongside workers under EU AI Act human oversight protocols. German OEMs are redesigning safety architectures to satisfy conformity assessment requirements before CE marking.
- Autonomous Guided Vehicles:Warehouse logistics fleets deploy neural network processing at the edge where cloud latency proves prohibitive. Capital equipment buyers are unbundling after-sales service contracts from hardware procurement.
- Drones:Aerial platforms integrate vision-language-action models for infrastructure inspection and inventory management.
- Humanoid Robots:Bipedal locomotion systems target unstructured terrain operations with legged mobility advantages.
Commercial maturity sits with Collaborative Robots. Development priority concentrates in Humanoid Robots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors industrial robotics deployment through Germany's automotive automation corridor, where OEMs mandate ISO 10218 compliance for human-robot collaboration on assembly floors.
United States
Automotive tier-one suppliers in Michigan and Ohio embed machine learning inference for adaptive bin-picking and assembly sequencing. FDA clearance requirements for surgical robotic systems create pricing premiums in hospital networks. Boston Dynamics exemplifies legged locomotion development for unstructured terrain operations.
Germany
Baden-Württemberg's manufacturing belt concentrates demand for collaborative robots with force-limited arms operating under EU AI Act human oversight protocols. CE marking conformity assessments extend time-to-market by twelve to eighteen months for systems near workers. Munich hosts edge computing pilots for warehouse logistics where cloud latency proves prohibitive.
China
Guangdong Province's electronics assembly sector absorbs autonomous guided vehicle fleets with millisecond-latency path planning. MIIT standards for industrial robot safety shape domestic certification timelines. Shenzhen's technology corridor concentrates GPU-accelerated perception stack development for real-time navigation.
Japan
Automotive manufacturers in Aichi Prefecture deploy servo motor-integrated controllers for high-volume production environments. METI funding for next-generation robotics supports adaptive control algorithm research. Nagoya anchors FANUC Corporation's captive supply chain for volume production.
South Korea
Semiconductor fabrication capacity in Gyeonggi Province supplies specialized GPUs for neural network training clusters. MFDS medical device regulations create parallel validation tracks for surgical robotic platforms. Seoul's research institutions concentrate multimodal sensor fusion expertise for LiDAR and tactile array integration.
AI in Robotics Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory certification depth and sensor integration complexity. The vendor base stratifies into three tiers: semiconductor suppliers providing GPU-accelerated perception hardware, industrial OEMs with captive controller supply chains, and legged mobility specialists targeting unstructured terrain. Consolidation pressure concentrates among mid-scale integrators lacking proprietary training data or safety certification expertise. Dominant competitive moves include strategic partnerships for multimodal sensor fusion and geographic expansion into India's PLI scheme corridors.
Within the semiconductor-hardware tier, NVIDIA Corporation and Intel Corporation anchor GPU-accelerated inference stack supply. Among industrial automation incumbents, FANUC Corporation exemplifies captive vertical integration through in-house controller and servo motor production. Boston Dynamics occupies a position in the legged locomotion specialist archetype for terrain-adaptive mobility systems. These three company types represent the structural segmentation between compute-layer suppliers, volume manufacturers, and frontier mobility developers.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Boston Dynamics |
| FANUC Corporation |
| YASKAWA ELECTRIC CORPORATION |
| ABB |
| Tesla |
| SoftBank Robotics Group |
| Universal Robots A/S |
| Others |
Value Chain & Pricing Dynamics
Captive vertical integration through in-house controller and servo motor production anchors both supply security and pricing power for industrial automation incumbents. FANUC Corporation's captive supply chain insulates it from GPU semiconductor volatility while commanding premium positioning against modular competitors sourcing externally.
Pricing Analysis
Outcome-based pricing tied to production line uptime anchors premium tiers for automotive OEM contracts. Three-tier pricing structure across premium sensor-integrated platforms, mid-tier adaptive arms, and basic programmable units reflects certification depth and after-sales bundling. Cost compression in the mid-tier is intensifying because warehouse logistics buyers are unbundling service contracts from hardware procurement. Tier-one automotive manufacturers in Germany's Stuttgart corridor exhibit lowest price sensitivity, while small-batch electronics assemblers in India face acute margin pressure.
Supply Chain Analysis
GPU supply rests on specialized semiconductor fabrication capacity concentrated in Taiwan and South Korea. NVIDIA Corporation's accelerated perception stacks and Intel Corporation's inference hardware both draw from TSMC and Samsung foundry output. Single-source vulnerability in advanced node production creates chokepoint exposure for real-time navigation systems. Distribution runs through direct OEM relationships for volume automotive contracts, with third-party integrators serving mid-scale manufacturing deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation models trained on robotic manipulation datasets are displacing deterministic programming paradigms, compressing deployment cycles from weeks to hours. This transition favors suppliers with proprietary training data and safety certification expertise over hardware-centric incumbents.
For Market Incumbents: Cement defensive positioning by deepening backward integration into edge computing silicon and expanding notified body relationships for EU AI Act pre-certification. The threat of vision-language-action models from frontier AI labs erodes traditional programming-based moats. Priority investment in multimodal sensor fusion talent pools protects premium tier positioning against modular disruptors.
For New Entrants and Emerging Players: Systems integrators with automotive aftermarket relationships offer the fastest channel to deployed volume. India's PLI scheme corridors present the most penetrable geography for cost-optimized collaborative robot platforms. A software-first go-to-market emphasizing rapid task reprogramming without specialized robotics expertise unlocks mid-tier manufacturing accounts.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by industrial conglomerates seeking AI-enabled automation capabilities. Long-term viability across the analysis window favors targets with validated safety architectures and recurring software revenue streams. Watch FDA pre-submission feedback timelines for surgical robotics as an inflection indicator for medical segment capital allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundation Model Integration | Compresses programming cycles by embedding pre-trained transformer architectures into unified inference pipelines. |
| EU AI Act Pre-Certification | Accelerates CE marking timelines through early notified body engagement for high-risk autonomous systems. |
| Edge Computing Hardware Development | Reduces cloud dependency for millisecond-latency path planning in warehouse logistics environments. |
| 5G-Private Network Deployment | Enables distributed control architectures that lower on-board compute requirements for AGV fleets. |
| After-Sales Service Unbundling | Captures predictive maintenance revenue separate from hardware procurement in high-volume automotive settings. |
Study Parameters
Independent corroboration across robotics OEM product managers, automotive tier-one procurement directors, and warehouse logistics operators underwrites the qualitative findings. Secondary validation draws from MIIT industrial robot safety filings, EU AI Act implementation guidance, FDA 510(k) clearance databases, and hyperscaler edge computing capex disclosures. Bottom-up installed base estimates triangulate against top-down semiconductor shipment data for GPU-accelerated inference hardware.
Rate-of-change decomposition across technology adoption curves, regulatory implementation timelines, and manufacturing automation investment cycles structures the analytical framework. Segmentation dimensions span application type, technology layer, end-user industry, and product architecture throughout the projection horizon. CAGR derivation weights historical deployment velocity against EU AI Act compliance friction and foundation model capability advances.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor fabrication, abrupt shifts in FDA surgical robotics clearance standards, and breakthrough advances in general-purpose humanoid locomotion. Forecasts reflect assumptions about regulatory harmonization progress and GPU supply elasticity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Saudi Arabia Big Data and Artificial Intelligence Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market