
 Generative AI in Healthcare Market | 2026-2036
Generative AI in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Generative AI in Healthcare Market Analytics
EU AI Act enforcement is hardening the cost-of-entry calculus for generative AI healthcare vendors seeking European market access. NVIDIA Corporation leverages its GPU infrastructure to dominate training workloads for medical foundation models. Google LLC anchors its position through deep learning integrations with academic medical centers. IBM differentiates via natural language processing specialized for clinical documentation and administrative automation.
Generative AI in healthcare denotes systems that synthesize novel clinical content, including diagnostic imagery, molecular structures, and patient-facing communications, through probabilistic models trained on multimodal medical datasets; these systems typically operate on transformer architectures with parameter counts exceeding one hundred billion, requiring specialized inference hardware and federated data pipelines to preserve patient privacy under HIPAA and GDPR constraints. Clinical decision making currently occupies the largest application margin pool as hospitals prioritize FDA-aligned diagnostic support tools. Pharmaceutical companies represent the fastest-growing end user segment as generative molecular design compresses preclinical timelines. Deep learning leads the technology hierarchy, though reinforcement learning is gaining traction for treatment optimization protocols.
The FDA's software-as-a-medical-device pathway, alongside EU AI Act risk classification and HIPAA security rule enforcement, collectively shapes product development roadmaps and go-to-market sequencing for vendors. China's NMPA has introduced analogous review channels for AI-enabled diagnostic devices, adding a third compliance jurisdiction for multinational firms. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmented certification costs that erode scale economics.
Market Dynamics
Pharmaceutical procurement of generative AI tools is compressing preclinical drug discovery timelines while FDA software-as-a-medical-device enforcement hardens deployment requirements for diagnostic applications.
Growth Catalysts
- EU AI Act risk classification:The regulation's clarity on high-risk AI systems is accelerating vendor investment in European compliance infrastructure, reducing market entry uncertainty.
- Transformer architectures exceeding 100 billion parameters:These foundation models enable novel molecular structure generation that pharmaceutical R&D teams are embedding into discovery pipelines.
- Hospital systems in the United States:These institutions command the largest implementation budgets for clinical decision support tools aligned with FDA diagnostic pathways.
Market Restraints
- Specialized inference hardware costs:GPU clusters required for billion-parameter model deployment create capital barriers for mid-tier healthcare systems.
- GDPR and HIPAA federated data pipeline requirements:Cross-border patient data restrictions fragment training dataset scale and increase engineering overhead.
- Reinforcement learning protocols:These treatment optimization methods remain technically immature for clinical deployment, limiting expansion beyond deep learning applications.
Strategic Opportunities
- Administrative automation via clinical NLP:Natural language processing for documentation workflows remains underpenetrated relative to diagnostic applications.
- China's NMPA review channels:The regulator's AI-enabled device pathway offers multinational firms a third compliance jurisdiction beyond FDA and EU frameworks.
- Reinforcement learning convergence with electronic health records:This technology pairing enables dynamic treatment protocol optimization in acute care settings.
Industry Challenges
- Multimodal medical dataset engineering:Curating imaging, genomic, and clinical text data requires specialized bioinformatics talent in short supply.
- FDA software-as-a-medical-device certification timelines:Extended premarket review cycles compress revenue realization windows for diagnostic support vendors.
- Legacy electronic health record integration:Proprietary data formats in incumbent hospital IT systems create friction for AI tool deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generative AI in Healthcare Market |
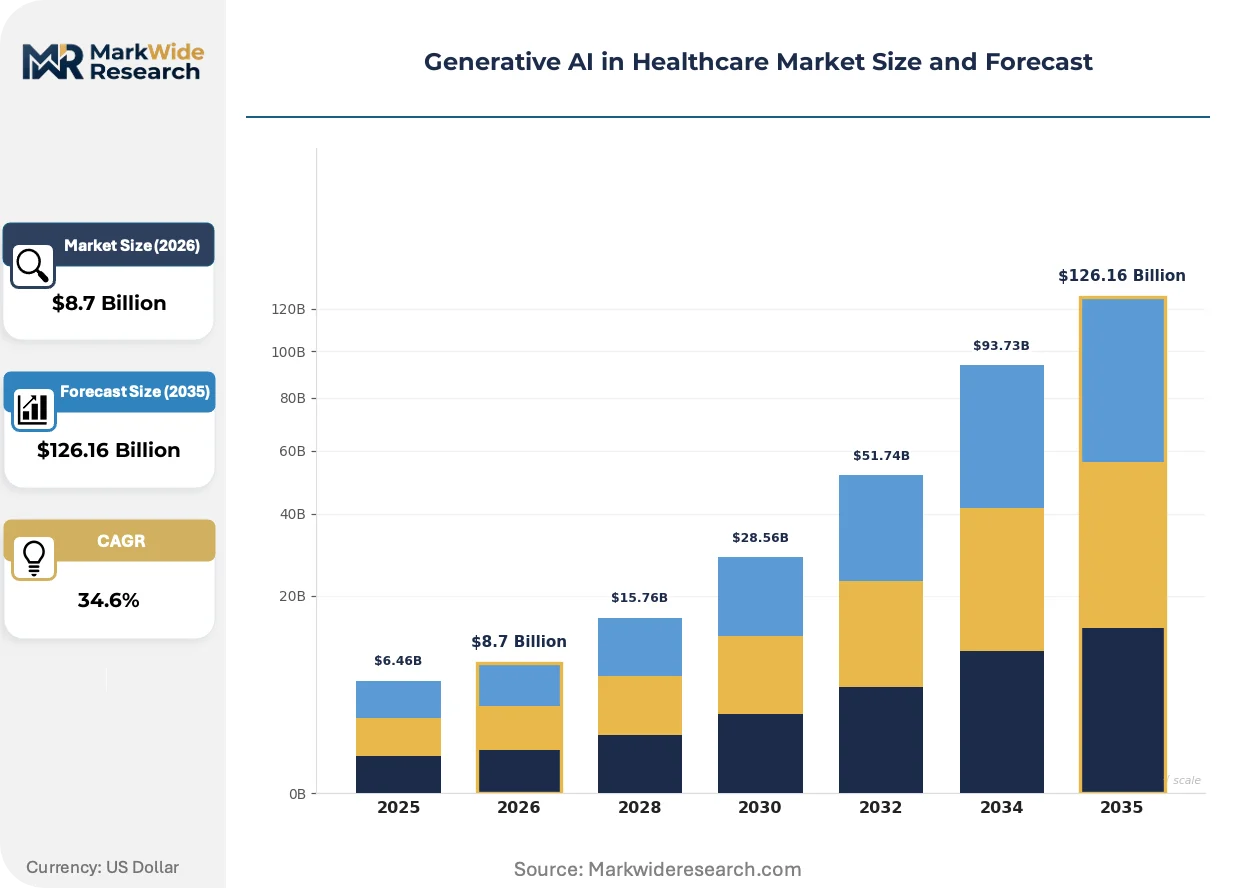
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $126.16 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AI Algorithms, Natural Language Processing, Machine Learning Models, Decision Support Systems Application: Clinical Decision Making, Diagnostics, Personalized Treatment, Administrative Automation End User: Hospitals, Research Institutions, Pharmaceutical Companies, Diagnostics Laboratories Technology: Deep Learning, Neural Networks, Cloud Computing, Reinforcement Learning |
| Companies Covered | NVIDIA Corporation, Google LLC, IBM, Microsoft Corporation, OpenAI, Oracle, Johnson & Johnson, Tencent Holdings Ltd, Abridge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generative AI in Healthcare Market Evolving Landscape
Foundation model architectures trained on multimodal medical datasets are reshaping how clinical content gets synthesized, with regulatory frameworks racing to keep pace with deployment velocity.
Diffusion models for diagnostic imagery generation are electrifying radiology workflows by producing synthetic training data that addresses class imbalance in rare disease detection. Academic medical centers in the United States are piloting these tools for residency education and algorithm validation. The technology is electrifying quality assurance processes while reducing reliance on patient consent for retrospective studies.
The EU AI Act's high-risk system obligations are forcing vendors to implement post-market monitoring infrastructure and human oversight protocols before European commercialization. Medical device manufacturers must now maintain risk management systems throughout product lifecycles. Diagnostic imaging AI bears the heaviest compliance burden, with notified body involvement required for CE marking.
Hospital procurement committees are consolidating vendor relationships around integrated platform solutions rather than point applications. Standalone generative AI tools face extended sales cycles as buyers prioritize EHR-embedded functionality. This concentration is most visible in United States health systems where capital allocation authority has shifted to centralized digital transformation offices.
Generative AI in Healthcare Market Segmentation
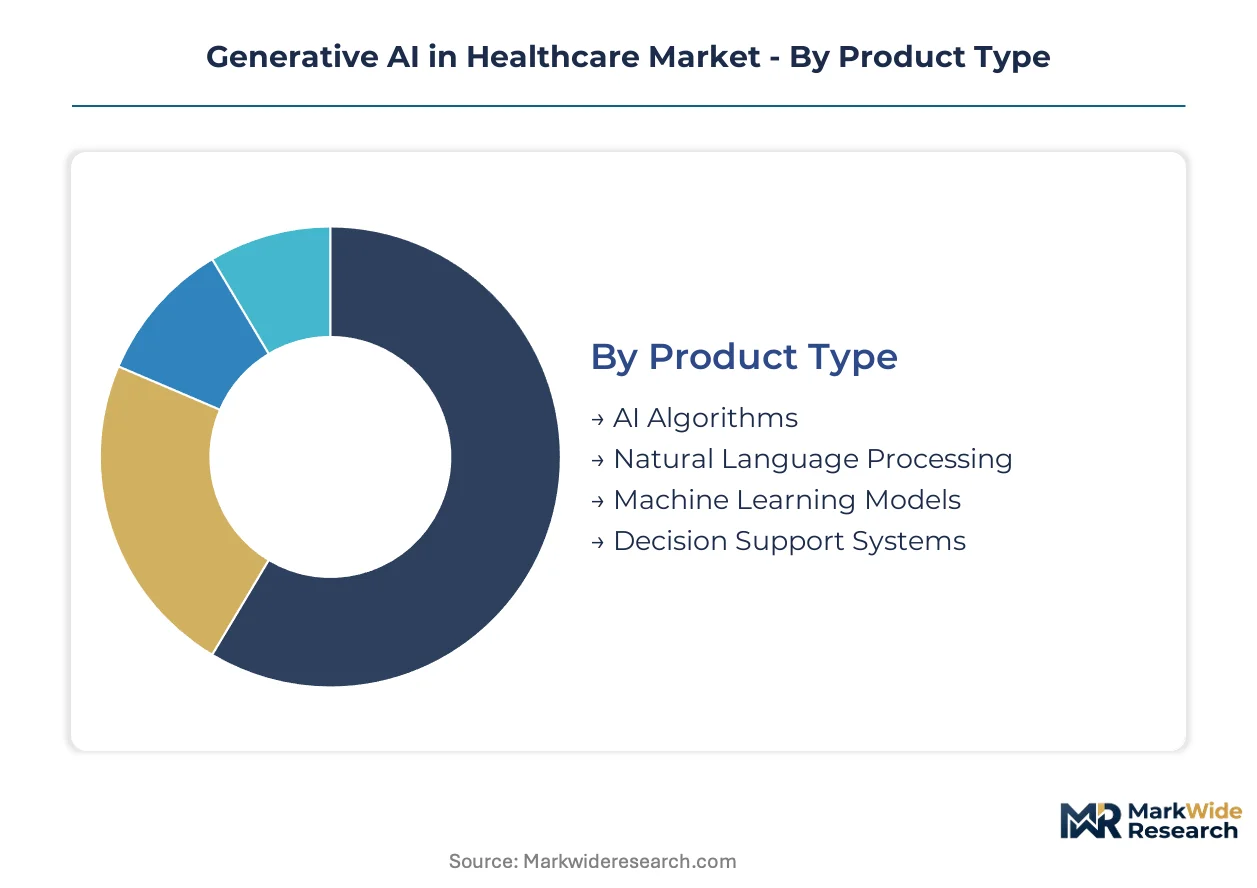
Generative AI healthcare vendors must align product architecture with distinct regulatory pathways. Each segment category imposes different compliance burdens, hardware requirements, and customer procurement cycles that reshape commercial strategy.
Product Type:
FDA software-as-a-medical-device classification, EU AI Act high-risk system designation, and HIPAA security rule enforcement apply unevenly across product categories, creating tiered certification costs.
- AI Algorithms:Foundation model architectures exceeding 100 billion parameters require specialized GPU infrastructure for training and inference. Pharmaceutical companies in the United States dominate procurement for molecular generation and protein folding applications, driven by compressed preclinical timelines and competitive patent positioning.
- Natural Language Processing:Clinical documentation and administrative automation systems process unstructured EHR data through transformer-based architectures. Hospital systems prioritize NLP tools embedded within existing Cerner and Epic workflows, with procurement committees favoring platform-integrated solutions over standalone deployments.
- Machine Learning Models:Supervised learning systems for risk stratification and readmission prediction.
- Decision Support Systems:Diagnostic recommendation engines requiring FDA 510(k) or De Novo pathway clearance.
AI Algorithms sits at the top of the volume ranking, with Natural Language Processing climbing the fastest.
Application:
Margin concentration varies sharply by application, with diagnostic support tools commanding premium pricing due to liability exposure and clinical workflow integration costs.
- Clinical Decision Making:Real-time diagnostic assistance and treatment protocol recommendations embedded at the point of care. United States academic medical centers allocate the largest implementation budgets, prioritizing FDA-aligned tools that reduce malpractice exposure while accelerating resident training.
- Diagnostics:Medical imaging interpretation and pathology screening through computer vision models. Radiology departments in tertiary hospitals drive demand for diffusion-model-based synthetic data generation that addresses class imbalance in rare disease detection.
- Personalized Treatment:Genomic-informed therapy selection and dosing optimization.
- Administrative Automation:Prior authorization, coding, and scheduling workflows.
Clinical Decision Making captures the largest share of current revenue, with Diagnostics gaining share fastest.
End User:
Procurement authority and technical readiness diverge substantially across customer types, shaping sales cycle length and implementation complexity.
- Pharmaceutical Companies:Generative molecular design platforms compress lead identification from months to weeks through probabilistic structure generation. These firms represent the steepest expansion trajectory as R&D teams embed AI into discovery pipelines, with procurement concentrated among top-20 global developers.
- Hospitals:Integrated delivery networks and academic medical centers command capital allocation authority through centralized digital transformation offices. United States health systems prioritize EHR-embedded functionality, extending sales cycles for standalone tools while consolidating vendor relationships around platform solutions.
- Research Institutions:Academic medical centers piloting foundation models for algorithm validation and residency education.
- Diagnostics Laboratories:High-throughput pathology and genomic testing facilities.
Hospitals anchor current deployment volume, with Pharmaceutical Companies expanding most quickly.
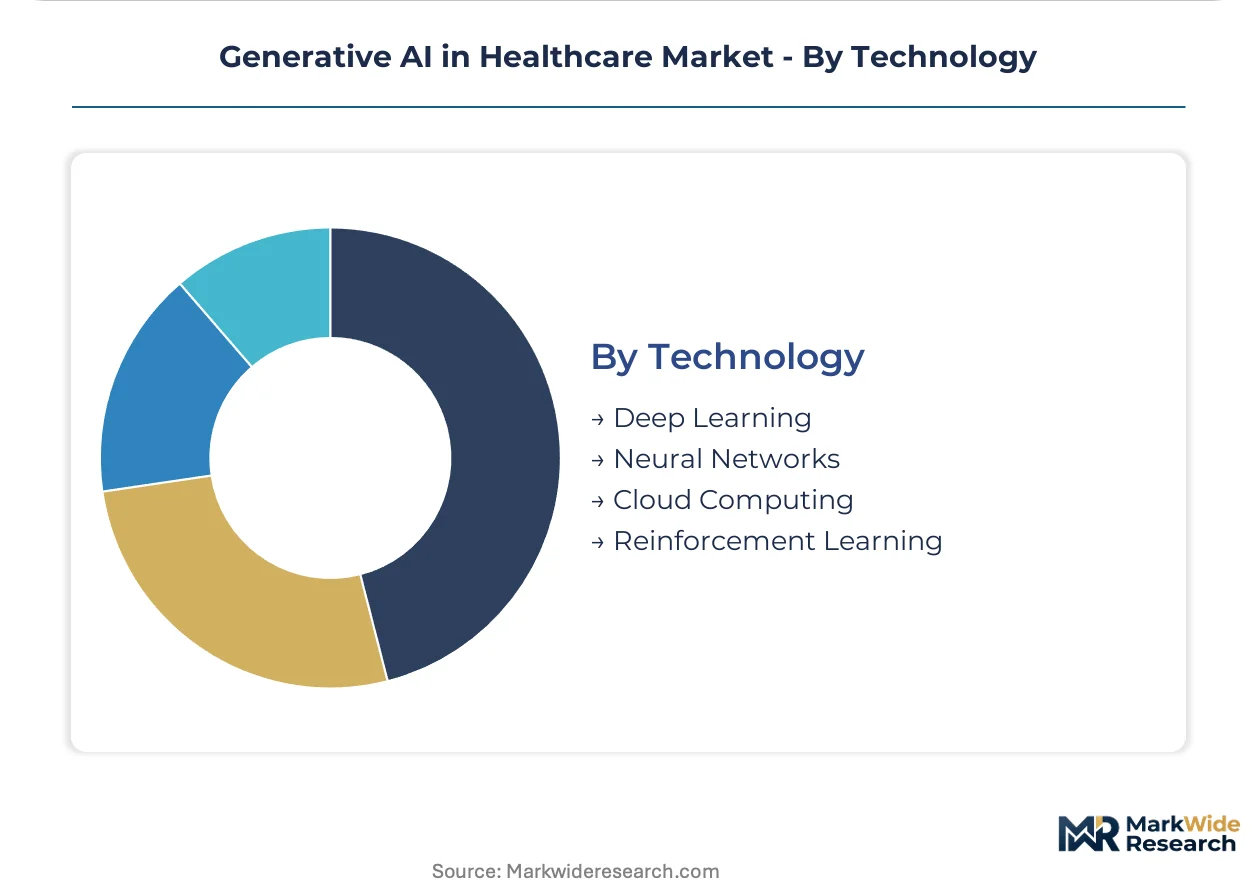
Technology:
Infrastructure requirements and talent scarcity create divergent cost structures across technical approaches, with cloud-native architectures lowering entry barriers for mid-tier health systems.
- Deep Learning:Multilayer neural networks trained on multimodal medical datasets including imaging, genomic, and clinical text. This technology dominates current implementations through mature frameworks and established regulatory precedents at FDA and EMA.
- Reinforcement Learning:Dynamic treatment optimization protocols that learn from electronic health record outcomes. Technical immaturity limits clinical deployment, though academic medical centers in the United States are piloting acute care applications for sepsis and ventilation management.
- Neural Networks:Feedforward and recurrent architectures for structured data processing.
- Cloud Computing:Federated infrastructure enabling HIPAA and GDPR-compliant data pipelines.
Deep Learning leads deployment volume, with Reinforcement Learning positioned for steepest future expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized bioinformatics talent clusters in the United States, Germany, and China anchor regional deployment capacity for billion-parameter medical foundation models.
United States
Academic medical centers in Boston and Stanford drive demand for FDA-aligned diagnostic support tools that reduce malpractice exposure. HIPAA security rule enforcement shapes federated data pipeline architecture for training workloads. The Mayo Clinic in Rochester anchors pilot programs for diffusion-model-based synthetic imaging in rare disease detection.
Germany
Pharmaceutical R&D teams in Frankfurt and Munich embed generative molecular design into preclinical discovery pipelines. The EU AI Act's high-risk system designation accelerates investment in post-market monitoring infrastructure. The Heidelberg University Hospital cluster leads European piloting of transformer-based clinical decision support.
China
Hospital systems in Beijing and Shanghai prioritize NMPA-cleared AI-enabled diagnostic devices for radiology workflows. The national pharmaceutical regulator's review channels add a third compliance jurisdiction for multinational firms deploying generative tools. The Yangtze River Delta concentration anchors domestic GPU infrastructure for medical foundation model training.
United Kingdom
NHS digital transformation offices in London and Manchester consolidate vendor relationships around EHR-embedded functionality. GDPR constraints on cross-border patient data fragment training dataset scale for multinational AI deployments. The Cambridge life sciences cluster pilots reinforcement learning protocols for acute care treatment optimization.
Japan
PMDA regulatory clarity accelerates hospital procurement of clinical NLP tools for administrative automation in Tokyo and Osaka. METI funding programs support domestic development of medical foundation models to reduce reliance on foreign GPU infrastructure. The Kansai region's academic medical centers lead pilot programs for genomic-informed therapy selection.
Generative AI in Healthcare Market Competitive Landscape
The competitive structure tilts toward cloud infrastructure providers with captive GPU supply. Three tiers have crystallized: hyperscalers operating medical foundation model training clusters, enterprise software vendors embedding generative tools into EHR workflows, and specialized clinical NLP firms targeting administrative automation. Dominant competitive moves include strategic partnerships with academic medical centers for algorithm validation and vertical integration into federated data pipeline infrastructure.
Within the hyperscaler tier, NVIDIA Corporation exemplifies infrastructure dominance through GPU cluster provisioning for billion-parameter model training. Google LLC and Microsoft Corporation occupy positions as platform-integrated solution providers embedding generative capabilities into cloud-based healthcare workflows. These three anchors represent distinct strategic archetypes: captive hardware supply, academic research integration, and enterprise software distribution.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Google LLC |
| IBM |
| Microsoft Corporation |
| OpenAI |
| Oracle |
| Johnson & Johnson |
| Tencent Holdings Ltd |
| Abridge |
| Others |
Value Network & Pricing Analysis
Hospital procurement committees in the United States are consolidating vendor relationships around EHR-embedded platform solutions rather than standalone point applications, forcing suppliers to absorb integration engineering costs and compressing margins on unbundled AI algorithm licenses.
Pricing Analysis
Bundled platform subscriptions dominate enterprise sales to hospital systems, while unbundled per-algorithm licensing persists in pharmaceutical R&D procurement. Price differentiation rests on FDA 510(k) clearance tier and federated data pipeline certification under HIPAA. Pricing pressure stems from GPU cluster operating costs that vendors struggle to pass through to mid-tier health systems. Pharmaceutical companies show the lowest price sensitivity due to compressed preclinical timeline value, while community hospitals resist subscription escalations.
Supply Chain Analysis
Reverse-logistics flows for GPU hardware refurbishment and model retraining cycles are emerging as cost centers as billion-parameter architectures require frequent hardware refresh. Supply concentrates in the United States, Taiwan, and China for advanced GPU fabrication and cloud infrastructure. Raw material dependencies include high-bandwidth memory modules, specialized cooling systems, and rare earth elements for semiconductor substrates. Single-source vulnerability in NVIDIA's GPU architecture creates concentration risk. Distribution runs through hyperscaler cloud marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI healthcare vendors operate in a margin-expansion environment as cloud infrastructure commoditization drives down training costs and FDA-cleared diagnostic tools command premium pricing tiers.
For Market Incumbents: Deploy captive GPU infrastructure partnerships to defend against hyperscaler pricing power. Consolidate around EHR-embedded platform architectures to extend contract duration and raise switching costs. Reinforcement learning technical immaturity from emerging entrants threatens diagnostic application margins, requiring accelerated R&D in acute care protocols. For New Entrants and Emerging Players: Capture administrative automation white space where clinical NLP penetration lags diagnostic applications. Community hospital systems in secondary United States markets offer the most penetrable procurement entry points due to centralized digital transformation office consolidation fatigue. Position through Epic and Cerner integration partnerships rather than standalone tool sales cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized clinical NLP firms possessing HIPAA-compliant federated data pipeline infrastructure. Five-to-ten year viability favors vendors with EU AI Act high-risk system certification capabilities and post-market monitoring infrastructure already deployed. Monitor FDA software-as-a-medical-device premarket review timeline announcements as inflection indicators for diagnostic support vendor revenue realization windows.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic and Cerner integration contracts anchor platform stickiness and extend sales cycle efficiency. |
| FDA 510(k) Submission Pathway | Diagnostic algorithm clearance unlocks premium pricing tiers and reduces malpractice exposure liability. |
| GPU Infrastructure Partnership | NVIDIA cluster provisioning secures training capacity and insulates against hyperscaler compute pricing volatility. |
| EU AI Act Compliance Investment | High-risk system certification and post-market monitoring infrastructure enable European market entry. |
| Pharmaceutical R&D Collaboration | Generative molecular design platform embedding compresses preclinical timelines and anchors recurring revenue. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement committee members, pharmaceutical R&D executives, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement registries, and hyperscaler healthcare vertical revenue disclosures. Bottom-up deployment volume estimates triangulated against top-down market sizing from cloud infrastructure spending patterns.
Historical reference periods anchored the projection horizon to pre-pandemic baseline adoption curves and post-2023 regulatory enforcement inflection points. The analytical framework modeled segmentation across product type, application, end user, and technology hierarchy, with regional regulatory cluster as an additional dimension. CAGRs derived from curve-fitting adoption velocity against comparable technology diffusion patterns in regulated healthcare IT markets. Forecast inputs included GPU cost decline trajectories and FDA review queue length projections.
Regulatory enforcement divergence, GPU supply concentration shocks, and hospital capital expenditure cycle turns are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about EU AI Act implementation timelines and HIPAA enforcement consistency. Practitioners should monitor FDA premarket review backlog announcements and hyperscaler healthcare vertical earnings disclosures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Cognitive Collaboration Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Consumer Facing AI Products Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Egypt Artificial Intelligence Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Artificial Intelligence in Workspace Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
Emotion AI Software Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Brain Computer Interface Market