
 AI Infrastructure Market | 2026-2036
AI Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
AI Infrastructure Market Intelligence
The capability gap between hyperscale cloud providers and on-premise hardware specialists is reorganizing the competitive landscape. Amazon Web Services (AWS) leverages its massive capital expenditure to offer scalable, on-demand AI infrastructure services. In contrast, NVIDIA Corporation dominates the critical accelerator component segment with its specialized processor architecture. Intel Corporation competes by offering a broad portfolio of processors and integrated solutions for diverse enterprise workloads.
AI infrastructure comprises the integrated hardware and software systems specifically engineered to run machine learning and deep learning workloads. This includes high-performance computing components like accelerators with tensor core capabilities, high-bandwidth memory, and low-latency networking fabrics essential for model training. The Accelerators category, particularly GPUs, represents the most critical and high-margin component in the value chain. While Hybrid Cloud deployment models gain traction among financial institutions, on-premises solutions remain vital for data-sensitive academic research.
The EU AI Act, US export controls on advanced semiconductors, and China's dual carbon goals for data centers are creating distinct regional compliance pathways for market participants. These regulations directly influence hardware design, energy efficiency standards, and cross-border data processing capabilities for infrastructure providers. Stakeholders must now decide between building regionally compliant infrastructure stacks or developing globally adaptable, albeit more complex and costly, platforms.
Market Dynamics
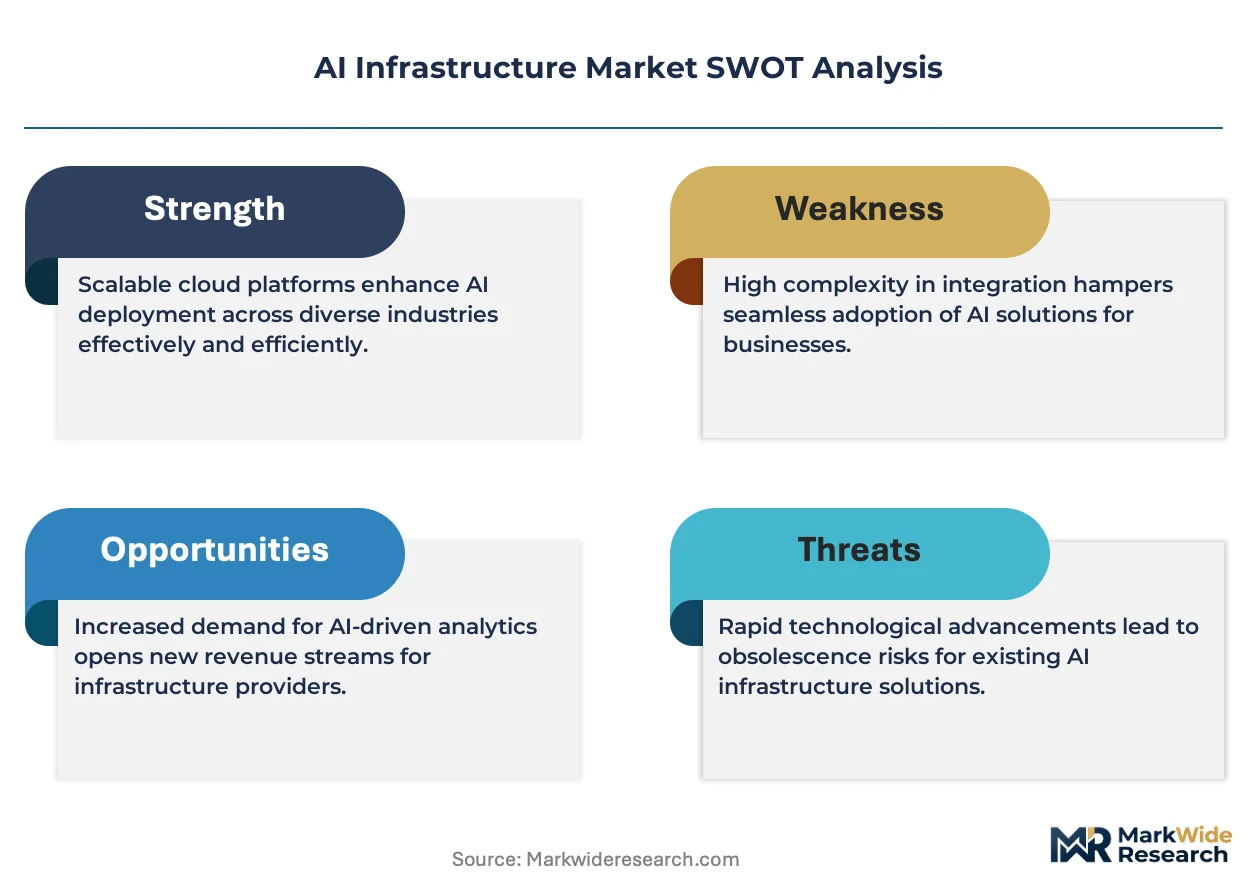
Divergent regulatory frameworks, including US export controls, the EU AI Act, and China's data center efficiency mandates, represent the central structural force shaping the market. This fragmentation creates distinct regional compliance pathways, influencing hardware design, supply chain access, and cross-border data processing.
Growth Catalysts
- Financial Sector Adoption:Demand from financial institutions for algorithmic trading, fraud detection, and risk management models is a primary catalyst, requiring low-latency and high-throughput infrastructure.
- Generative AI Expansion:The proliferation of large language models and diffusion models across enterprise and consumer applications necessitates massive-scale training and inference clusters, driving accelerator and high-bandwidth memory sales.
- Sovereign AI Initiatives:National strategies in countries like India, France, and Canada to build domestic AI capabilities are unlocking public sector investment in dedicated supercomputing and cloud infrastructure.
Market Restraints
- Semiconductor Supply Bottlenecks:The supply of leading-edge accelerators is highly concentrated, creating significant lead times and pricing power that can slow down infrastructure deployment for all but the largest hyperscalers.
- Extreme Power Consumption:The immense electrical power and cooling required for high-density AI clusters present a major structural barrier, particularly in regions with constrained energy grids or stringent environmental standards.
- High Capital Expenditure:The upfront cost of acquiring high-performance servers, networking fabrics, and building out specialized data center facilities remains prohibitive for many enterprises and academic institutions.
Strategic Opportunities
- Edge AI Infrastructure:Developing optimized hardware and software for AI inference at the network edge opens opportunities in autonomous vehicles, industrial automation, and smart city applications where low latency is critical.
- AI for Scientific Research:Infrastructure tailored for life sciences, particularly for genomics, proteomics, and drug discovery, represents a significant growth vector with specialized performance requirements.
- Liquid Cooling Solutions:The thermal limits of traditional air cooling create a substantial opportunity for advanced liquid and immersion cooling technologies, which enable greater compute density and energy efficiency.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of engineers with expertise in high-performance computing, distributed systems, and ML operations (MLOps) hinders the effective deployment and management of complex AI infrastructure.
- System Integration Complexity:Integrating state-of-the-art accelerators and networking components with existing enterprise IT environments and legacy software stacks poses a significant technical and operational hurdle for adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Infrastructure Market |
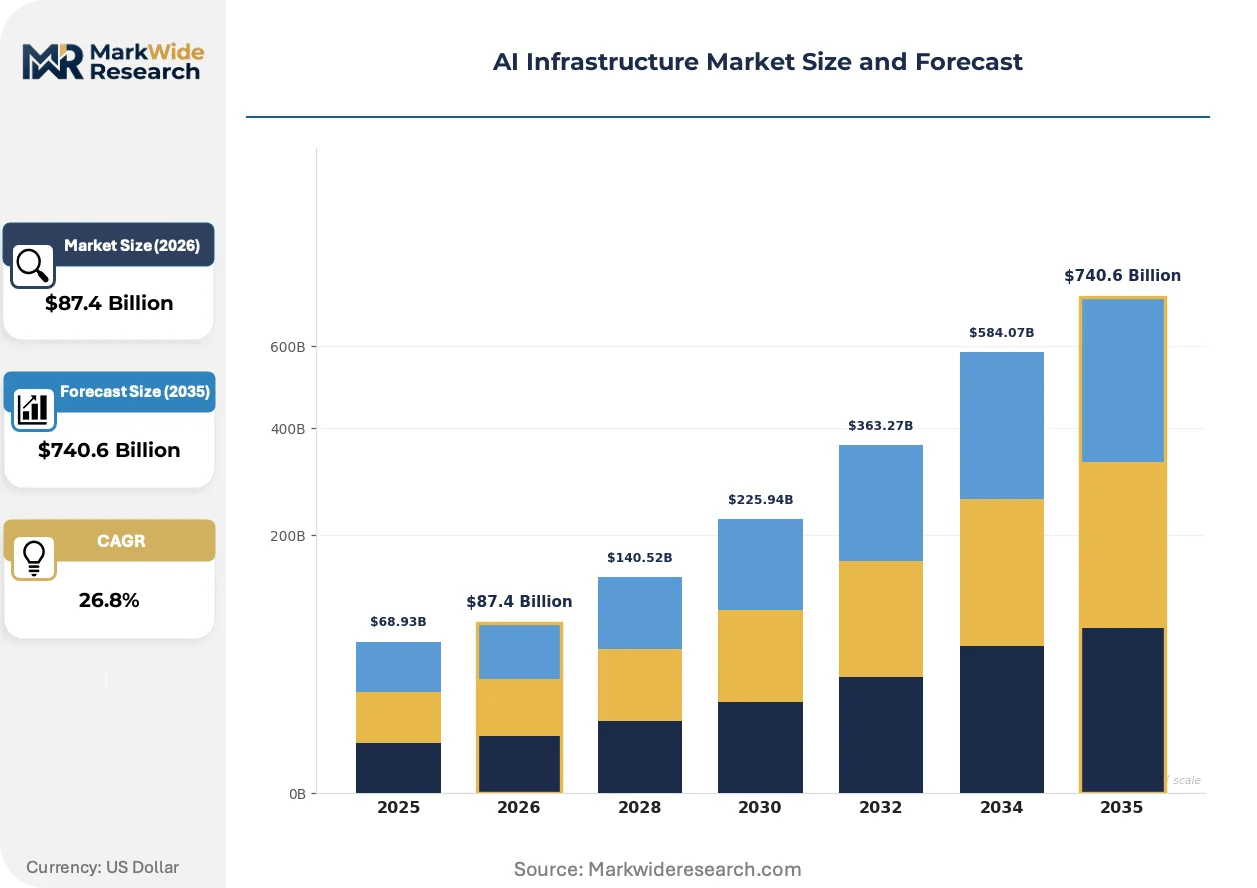
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $740.6 Billion |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Processors, Storage Systems, Networking Devices, Accelerators Deployment: On-Premises, Edge Computing, Colocation, Hybrid Cloud End User Industry: Financial Institutions, Academic Institutions, Telecommunications Firms, Media Enterprises Service Offering: Infrastructure Management, System Integration, Cloud Support, Technical Consulting |
| Companies Covered | NVIDIA Corporation, Advanced Micro Devices, Inc., Intel Corporation, Samsung Electronics Co., Ltd, Micron Technology, Inc., Amazon Web Services, Inc., Microsoft Corporation, Google LLC, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Infrastructure Market Strategic Shifts & Innovations
Concurrent pressures for higher computational performance and greater energy efficiency are defining the technology roadmap for AI infrastructure. This dynamic compels innovation across the entire stack, from silicon architecture to data center cooling systems, creating new standards for performance and sustainability.
Liquid cooling technologies, including direct-to-chip and immersion cooling, are designed to manage the extreme thermal output of high-density GPU racks. Hyperscale data center operators and specialized colocation providers are rapidly adopting these systems for next-generation deployments. This advanced thermal management is supplanting traditional air-based cooling methods that are insufficient for accelerators exceeding high thermal design power thresholds.
The EU AI Act introduces a risk-based framework that imposes strict requirements on systems used in critical sectors like finance and healthcare. This regulation directly influences infrastructure design by mandating auditable data governance, model transparency, and operational robustness. Consequently, providers targeting the European Union are embedding compliance-by-design principles into their hardware and software platforms.
A definitive shift toward hybrid and multi-cloud strategies is altering infrastructure consumption patterns among large enterprises. This model allows organizations to run proprietary model training on-premises for security and data sovereignty while using public cloud resources for elastic inference scaling. This trend is especially prominent in the financial services and public sectors across North America and Europe.
AI Infrastructure Market Segmentation
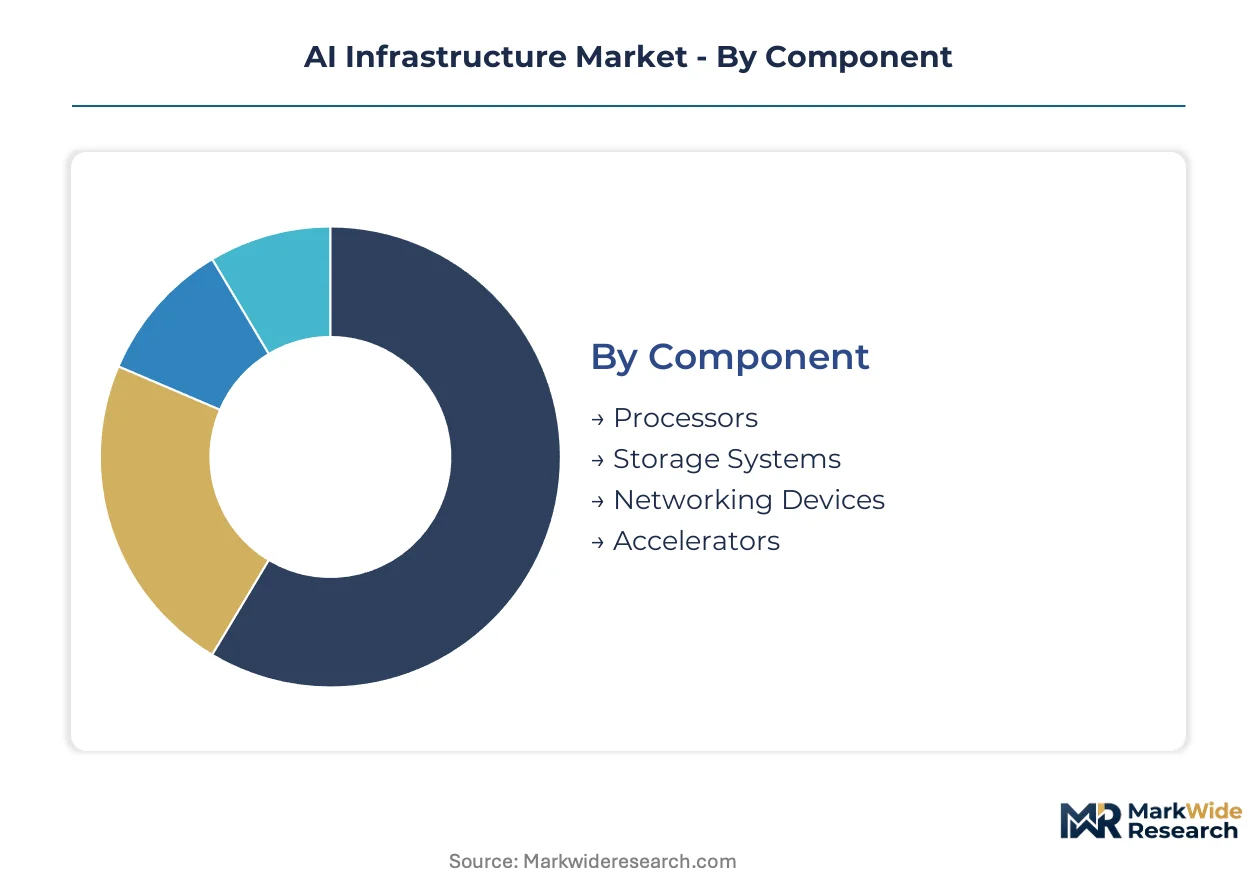
The AI infrastructure market segments across key components, deployment models, end-user industries, and service offerings. Understanding these divisions helps market participants identify where value accrues and how different operational requirements shape demand for specialized solutions.
Component:
Margin pools within the component category concentrate heavily on specialized processing units that enable high-performance AI workloads.
- Accelerators:These are specialized hardware components, such as GPUs and TPUs, designed to accelerate machine learning and deep learning computations. Demand concentrates in high-density data center clusters across the United States and parts of Europe for large-scale model training.
- Processors:General-purpose CPUs provide foundational compute power for diverse enterprise workloads, including AI inference and data preprocessing. Financial institutions and academic research facilities require robust processor architectures for their varied computational needs.
- Storage Systems:High-speed, scalable storage solutions manage the massive datasets required for AI model training and deployment. These systems ensure rapid data access for complex analytical tasks.
- Networking Devices:Low-latency networking fabrics connect compute and storage resources, ensuring efficient data flow within AI clusters. High-bandwidth connectivity is essential for distributed training environments.
The dominant share belongs to Accelerators, while Processors are closing the gap fastest.
Deployment:
The deployment models reflect differing security, control, and scalability requirements across various organizational structures.
- Hybrid Cloud:This model combines on-premises infrastructure with public cloud resources, offering flexibility and data sovereignty. Financial institutions in North America and Europe leverage hybrid cloud for proprietary model training and elastic inference scaling.
- On-Premises:Infrastructure hosted within an organization's own facilities provides maximum control, security, and data governance. Academic institutions and government agencies often prefer on-premises solutions for sensitive research and classified data.
- Edge Computing:AI processing occurs close to the data source, reducing latency and bandwidth requirements for real-time applications. Autonomous vehicles and industrial automation systems drive demand for edge AI infrastructure.
- Colocation:Organizations lease space for their servers and networking equipment in third-party data centers, benefiting from shared infrastructure and managed services. Specialized colocation providers are rapidly adopting advanced liquid cooling solutions.
Hybrid Cloud deployments command significant investment, with On-Premises solutions maintaining critical importance for specific use cases.
End User Industry:
This category highlights how specific industry demands for AI capabilities influence infrastructure design and procurement.
- Financial Institutions:These organizations utilize AI infrastructure for algorithmic trading, fraud detection, and risk management, requiring low-latency and high-throughput systems. Demand from this sector is a primary catalyst for market expansion.
- Academic Institutions:Research universities and laboratories deploy AI infrastructure for scientific discovery, particularly in genomics and drug discovery. On-premises solutions remain vital for data-sensitive academic research.
- Telecommunications Firms:Telecom providers use AI for network optimization, predictive maintenance, and enhancing customer service. Their infrastructure requires high reliability and scalability for handling vast data volumes.
- Media Enterprises:Media companies leverage AI for content creation, personalized recommendations, and audience analytics. This sector requires robust infrastructure for processing large media files and complex algorithms.
Financial Institutions represent the largest end-user segment, while Academic Institutions exhibit a strong, specialized demand profile.
Service Offering:
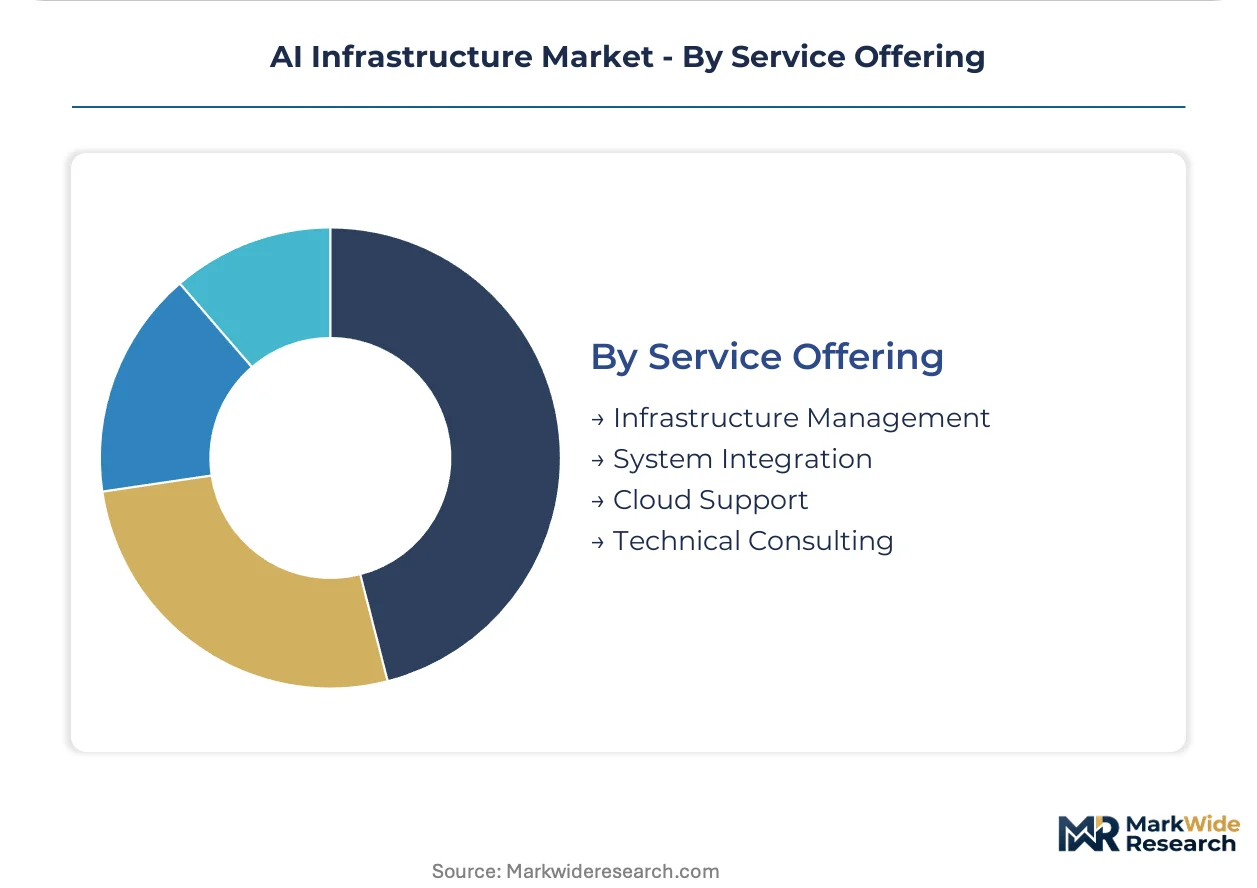
The service offerings address the operational complexities and expertise gaps associated with deploying and managing sophisticated AI infrastructure.
- Infrastructure Management:These services encompass monitoring, maintenance, and optimization of AI hardware and software systems. Effective infrastructure management ensures peak performance and operational efficiency for complex AI clusters.
- System Integration:Specialists integrate diverse hardware components, software platforms, and existing IT environments into cohesive AI infrastructure solutions. This service is crucial for overcoming system integration complexity challenges for enterprises.
- Cloud Support:Services assist organizations in leveraging public cloud resources for AI workloads, including migration, optimization, and cost management. Cloud support facilitates elastic scaling and access to advanced AI tools.
- Technical Consulting:Expert advice guides organizations through AI strategy development, technology selection, and deployment best practices. Technical consulting helps address the specialized talent scarcity in AI infrastructure.
Infrastructure Management services hold the largest market share, with System Integration experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing-power asymmetry for AI infrastructure components is evident between the United States and China. US export controls on advanced semiconductors constrain supply to China, impacting local infrastructure buildouts. This creates distinct market dynamics and investment patterns in both regions.
United States
Demand for generative AI expansion and financial sector adoption drives significant infrastructure investment. The US export controls on advanced semiconductors shape supply chain access for key components. Silicon Valley and other tech hubs concentrate hyperscale data center clusters for AI training.
China
Sovereign AI initiatives and dual carbon goals for data centers are primary demand drivers. China's national policies emphasize domestic AI capabilities and energy efficiency mandates. Beijing and Shanghai are key centers for developing AI supercomputing and cloud infrastructure.
Germany
Academic institutions and a strong industrial base generate demand for specialized AI infrastructure. The EU AI Act influences infrastructure design by mandating compliance-by-design principles. Munich and Berlin host AI research centers and specialized colocation providers.
Japan
Scientific research, particularly in life sciences, and industrial automation propel AI infrastructure needs. METI initiatives support advanced computing and data center development. Tokyo and Osaka are critical for high-density data center clusters and AI innovation.
India
Financial sector adoption and sovereign AI initiatives are accelerating infrastructure buildout. The PLI scheme encourages domestic manufacturing of IT hardware, including AI components. Bengaluru and Hyderabad are emerging as major hubs for AI development and data center expansion.
AI Infrastructure Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the AI infrastructure market. The market exhibits a tiered structure, with hyperscale cloud providers at one end and specialized component manufacturers at the other. Strategic archetypes include integrated hardware-software platform providers, pure-play accelerator manufacturers, and cloud-native infrastructure service providers. Capacity expansion through new data center builds and strategic partnerships for specialized component supply are dominant competitive moves.
Within the specialized component segment, NVIDIA Corporation exemplifies leadership in accelerator architecture with its GPU dominance. Intel Corporation occupies a position as a broad portfolio provider, offering processors and integrated solutions for diverse enterprise workloads. Amazon Web Services, Inc. represents a hyperscale cloud provider, leveraging massive capital expenditure to offer scalable, on-demand AI infrastructure services. These entities anchor distinct competitive strategies across the value chain.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Advanced Micro Devices, Inc. |
| Intel Corporation |
| Samsung Electronics Co., Ltd |
| Micron Technology, Inc. |
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
Massive capital expenditure for hyperscale data centers directly influences supply concentration for critical components and establishes high price floors for advanced AI services.
Pricing Analysis
Configured-to-order pricing for specialized AI infrastructure solutions commands a premium over standard, pre-packaged cloud services. Price differentiation drivers include the level of integration complexity, specialized hardware configurations, and dedicated after-sales support. Pricing pressure stems from increasing competition among hyperscale providers and the commoditization of basic inference services. Academic institutions and smaller enterprises exhibit higher price sensitivity compared to large financial institutions requiring bespoke solutions.
Supply Chain Analysis
Taiwan and South Korea anchor the fabrication of leading-edge semiconductors, which are critical for AI accelerators and high-bandwidth memory modules. The supply chain draws from key inputs like rare earth elements and specialized manufacturing equipment. Single-source vulnerability for advanced chip manufacturing represents a significant structural risk. Distribution runs through a concentrated network of specialized distributors and direct sales channels to hyperscale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI infrastructure market presents a defensive moat due to the high switching costs associated with migrating complex AI workloads and integrated hardware-software stacks. This structural advantage ensures long-term revenue predictability for established providers.
For Market Incumbents:Consolidate market share by deepening vertical integration into specialized component manufacturing and expanding global data center footprints. This defends against emerging chipmakers and mitigates semiconductor supply bottlenecks by securing critical inputs. Invest heavily in liquid cooling solutions and energy-efficient designs to address extreme power consumption and stringent environmental standards like China's dual carbon goals. Enhance MLOps platforms to simplify system integration for enterprise clients.
For New Entrants and Emerging Players:Lead with specialized solutions for underserved niches, such as edge AI inference for industrial automation or tailored infrastructure for life sciences research. The academic and mid-market enterprise segments represent penetrable targets due to high capital expenditure barriers for general-purpose infrastructure. Offer flexible consumption models and comprehensive system integration services to differentiate from hyperscale offerings. Focus on developing expertise in niche hardware-software optimization for specific AI workloads.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized colocation providers and managed AI infrastructure service firms due to long-term contracts and high operational complexity. These entities offer strong long-term viability over a 5-10 year window given the persistent demand for AI compute. Target acquisition profiles should favor companies with proprietary cooling technologies or advanced MLOps platforms. A signal to watch is the increasing average contract value for AI infrastructure services.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses the growing demand for high-performance AI compute resources. |
| Advanced Cooling Technology Integration | Manages extreme thermal loads of next-generation GPU clusters efficiently. |
| Strategic Partnerships for Chip Supply | Secures access to leading-edge accelerators amid semiconductor bottlenecks. |
| MLOps Platform Development | Simplifies deployment and management of complex AI workloads for enterprises. |
| Regional Compliance-by-Design | Ensures infrastructure adherence to diverse regulatory frameworks like the EU AI Act. |
Research Approach
A spread of perspectives from CTOs, IT procurement officers, data center operators, and AI solution architects converged on the working assumptions for market dynamics. This study combined primary interviews with industry stakeholders and secondary validation from SEC 10-K filings and hyperscaler capital expenditure disclosures. Bottom-up analysis of component sales was triangulated with top-down market sizing for overall AI infrastructure.
Component, deployment, end-user industry, and service offering dimensions were modeled across the analysis window. An additional industry-specific dimension, AI workload type (training vs. inference), was integrated into the framework. Compound Annual Growth Rates were derived from historical trends, projected technology adoption curves, and anticipated regulatory impacts. AI accelerator demand and data center power consumption served as key forecast inputs.
Forecasts assume regulatory continuity in US export controls and the EU AI Act; material policy shifts would require re-modeling. Geopolitical tensions impacting semiconductor supply chains also represent a significant risk factor. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
Smart Connected Assets and Operations Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Online on-Demand Home Services Market
Digital Solutions
Online Dating Application Market
Digital Solutions
Commodity Supply Chain Management Solution Market
Digital Solutions
Global Online Dating Services Market
Digital Solutions
Location-Based Services (LBS) Market
Digital Solutions
EHS Software Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Digital Workplace Technologies Market