
 Digital Intelligence Technology Market | 2026-2036
Digital Intelligence Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Intelligence Technology Market Analysis
India's semiconductor assembly capacity build-out is fragmenting as domestic chip fabrication incentives attract divergent technology strategies. NVIDIA leverages its CUDA ecosystem to sustain dominance in AI training infrastructure, while Alphabet anchors its position through vertically integrated tensor processing units for cloud inference. Microsoft competes by extending enterprise-grade copilot architectures across productivity software stacks.
Digital intelligence technology encompasses hardware, software, and services that ingest structured and unstructured data streams, apply algorithmic models with inference latencies below 50 milliseconds, and output actionable predictions for operational decision-making. Its primary commercial purpose centers on automating pattern recognition at scale across sensor networks, transaction logs, and multimodal content repositories. Cloud-based deployment now captures the dominant margin pool as hyperscalers bundle compute with pre-trained model APIs, while edge computing represents the fastest-expanding architecture as latency-sensitive applications in autonomous systems and industrial robotics proliferate. Natural language processing solutions command premium pricing in regulated sectors where explainable output generation meets audit requirements.
The EU AI Act, alongside FDA guidance on AI-enabled medical devices and China's algorithmic recommendation provisions under SAMR, collectively elevates compliance costs while creating defensible moats for vendors with pre-certified governance frameworks. These regulatory layers shape demand by mandating human-in-the-loop architectures for high-risk applications and restricting opaque model deployments in credit underwriting and criminal justice contexts. Stakeholders must monitor divergence between Brussels' risk-tiered approach and Washington's sector-specific agency guidance to anticipate which compliance investments will transfer across jurisdictions.
Market Dynamics
The EU AI Act's risk-tiered compliance architecture is forcing vendors to rebuild algorithmic transparency protocols from inference engines upward, redirecting R&D budgets toward explainability tooling and human-in-the-loop validation systems.
Growth Catalysts
- Defense procurement acceleration:NATO member states are expanding predictive analytics platform contracts for threat assessment and autonomous systems coordination, with procurement offices in Germany and France issuing multi-year framework agreements.
- Edge AI deployment in manufacturing:Industrial automation clusters in Bavaria and Baden-Württemberg are deploying sub-50-millisecond inference systems for real-time quality control, creating demand for localized compute hardware.
- EU AI Act compliance services:The regulation's mandatory audit trails for high-risk applications have spawned a specialized consulting segment where vendors pre-certify governance frameworks to accelerate customer procurement cycles.
Market Restraints
- GPU supply concentration:Advanced AI training hardware remains captive to Taiwan Semiconductor Manufacturing capacity allocation, creating 18-24 month lead time volatility for hyperscaler and enterprise buyers.
- Energy cost escalation:Data center power density requirements for large model training have exposed operators to European grid price spikes, compressing margins in cloud-based deployment segments.
- Cross-border data friction:China's SAMR algorithmic recommendation provisions and GDPR's extraterritorial reach create conflicting localization mandates, forcing redundant infrastructure deployment.
Strategic Opportunities
- India's semiconductor assembly build-out:Domestic chip fabrication incentives under the PLI scheme are attracting divergent technology strategies, creating openings for edge AI chip design partnerships with Bengaluru and Hyderabad engineering centers.
- Healthcare explainable AI:FDA guidance on AI-enabled medical devices is mandating interpretable output generation, creating premium pricing potential for natural language processing solutions that satisfy audit requirements.
- Convergence of sensor fusion and digital twin platforms:Manufacturing quality control applications are integrating multimodal sensor networks with predictive simulation, enabling outcome-based service contracting for uptime guarantees.
Industry Challenges
- Human-in-the-loop integration complexity:EU AI Act requirements for high-risk application oversight are forcing redesign of automated decision pipelines, extending deployment timelines for credit underwriting and criminal justice use cases.
- Model interpretability talent scarcity:The specialized skill set combining machine learning engineering with regulatory documentation expertise concentrates in Berlin, Paris, and London, creating recruitment bottlenecks for vendors scaling compliance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Intelligence Technology Market |
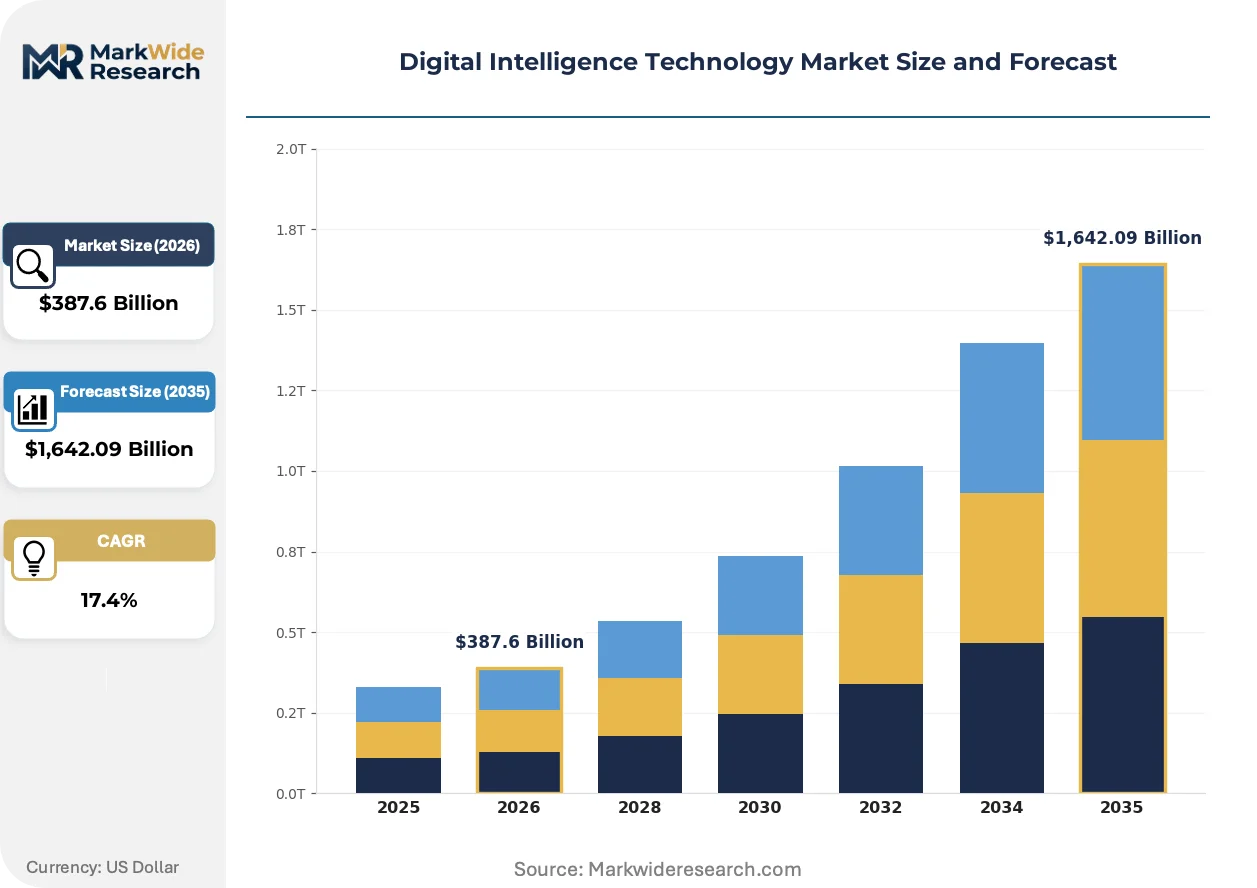
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,642.09 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
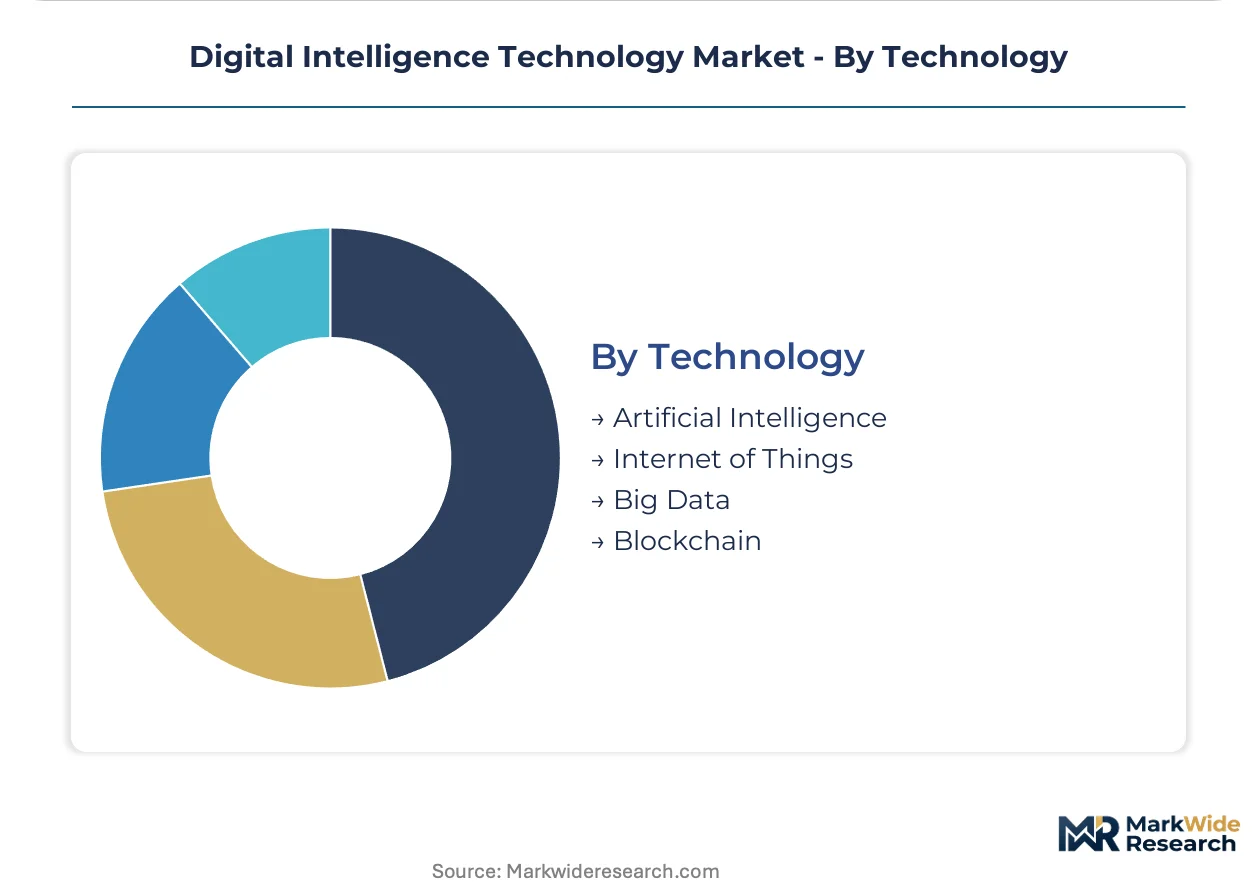
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid Model, Edge Computing Solution: Data Analytics, Machine Learning, Natural Language Processing, Computer Vision End User: Healthcare Providers, Financial Institutions, Retail Businesses, Government Agencies Technology: Artificial Intelligence, Internet of Things, Big Data, Blockchain |
| Companies Covered | NVIDIA, Alphabet, Microsoft, IBM, Oracle, OpenAI, Meta, Amazon Web Services, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Intelligence Technology Market Emerging Trajectories
Foundation model architectures are compressing development cycles for domain-specific applications, while regulatory mandates are hardening around algorithmic accountability rather than performance metrics alone.
Neuromorphic computing chips that mimic biological neural network spiking patterns are rendering obsolete traditional von Neumann architectures for ultra-low-power edge inference. Automotive Tier 1 suppliers in Stuttgart and Munich are piloting these systems for in-cabin occupancy detection. The technology is rendering obsolete the milliwatt-scale power budgets that previously constrained always-on sensor processing in battery-operated devices.
The EU AI Act's mandatory conformity assessments for high-risk AI systems are redirecting vendor roadmaps toward built-in audit logging and technical documentation automation. Industrial automation vendors serving German automotive OEMs are pre-integrating these capabilities to accelerate procurement approval. Medical device manufacturers face the steepest compliance gradient, with notified body backlogs extending certification timelines by 8-14 months for AI-enabled diagnostic tools.
Defense and intelligence agencies are consolidating vendor relationships around pre-cleared security architectures, displacing fragmented point-solution procurement. NATO procurement offices in Mons and Norfolk are establishing preferred supplier lists with embedded compliance credentials, compressing evaluation cycles for predictive analytics platforms. This concentration is most visible in Germany, where the Federal Office for Information Security is harmonizing federal and state-level security requirements for AI system accreditation.
Digital Intelligence Technology Market Segmentation

Digital intelligence technology procurement patterns diverge sharply across deployment architectures and solution types. Vendors must align pricing and service models to the distinct integration complexity and latency requirements that each segment imposes on enterprise buyers.
Deployment:
After-sales service intensity varies dramatically by deployment mode, with on-premises installations demanding perpetual engineering support while cloud-based models shift burden to vendor-operated infrastructure.
- On-Premises:Organizations retain full hardware ownership within dedicated data centers, requiring substantial internal DevOps capacity for model retraining and security patching. German automotive OEMs in Stuttgart and Munich favor this architecture for sensitive design data, though energy cost spikes across European grids are compressing total cost of ownership advantages.
- Cloud-Based:Hyperscalers bundle compute with pre-trained model APIs, capturing dominant margin pools through consumption-based pricing. NATO procurement offices in Mons are accelerating framework agreements for threat assessment platforms delivered via this model, prioritizing scalability over data sovereignty.
- Hybrid Model:Split architectures process sensitive data locally while offloading burst compute to cloud infrastructure. French financial institutions under ECB supervision deploy this pattern for fraud detection workloads.
- Edge Computing:Sub-50-millisecond inference systems deploy localized hardware for autonomous systems. Industrial automation clusters in Bavaria drive demand for quality control applications.
Cloud-Based deployments hold the largest share; momentum sits with Edge Computing as latency-sensitive manufacturing applications proliferate.
Solution:
Cost tier stratification separates premium-priced explainable AI solutions from commoditized analytics tools, with regulated sectors paying substantial premiums for audit-ready output generation.
- Data Analytics:Descriptive and diagnostic capabilities process structured transaction logs and sensor streams. Retail businesses in the Netherlands deploy these tools for demand forecasting, though margin pressure intensifies as open-source alternatives mature.
- Machine Learning:Predictive models automate pattern recognition across multimodal repositories. Healthcare providers under FDA guidance mandate interpretable architectures for clinical decision support, extending sales cycles but securing multi-year contracts.
- Natural Language Processing:Systems generating explainable output command premium pricing where audit requirements apply. Government agencies in Germany pre-certify governance frameworks to accelerate procurement.
- Computer Vision:Multimodal sensor processing enables real-time quality control and autonomous navigation. Stuttgart automotive Tier 1 suppliers pilot neuromorphic architectures for in-cabin detection.
Data Analytics maintains broadest adoption; Natural Language Processing climbs fastest on regulatory compliance premiums.
End User:
Customer type determines procurement velocity, with defense agencies moving through pre-cleared security architectures while commercial buyers negotiate complex human-in-the-loop integration.
- Healthcare Providers:AI-enabled diagnostic tools face notified body backlogs extending certification timelines by 8-14 months under EU MDR and FDA parallel review. Berlin and Paris medical centers concentrate procurement authority for enterprise-wide deployments.
- Financial Institutions:Credit underwriting applications confront EU AI Act restrictions on opaque model deployments. Frankfurt and Amsterdam banks invest heavily in explainability tooling to satisfy audit requirements.
- Retail Businesses:Demand forecasting and customer analytics drive adoption, with GDPR compliance adding infrastructure redundancy costs.
- Government Agencies:NATO member states consolidate vendor relationships around embedded security credentials. The Federal Office for Information Security harmonizes federal and state-level accreditation requirements.
Financial Institutions command highest solution premiums; Government Agencies show steepest contract acceleration through security pre-clearance.
Technology:
Supply concentration in advanced training hardware shapes competitive dynamics, with GPU allocation bottlenecks favoring vendors with captive foundry relationships.
- Artificial Intelligence:Foundation model architectures compress development cycles for domain-specific applications. EU AI Act conformity assessments redirect roadmaps toward built-in audit logging.
- Internet of Things:Sensor fusion platforms integrate with digital twin simulations for outcome-based uptime contracting. Manufacturing quality control in Baden-Württemberg drives multimodal network deployment.
- Big Data:Distributed processing frameworks handle petabyte-scale transaction logs and content repositories. Energy density requirements expose operators to European grid price volatility.
- Blockchain:Immutable audit trails support algorithmic accountability mandates in high-risk applications. Healthcare and financial sectors pilot decentralized validation for model provenance.
Artificial Intelligence anchors investment volumes; Internet of Things expands most quickly through manufacturing sensor fusion convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement patterns diverge sharply between NATO-aligned European states and Indo-Pacific industrial economies, with the former prioritizing explainable AI for threat assessment and the latter optimizing for manufacturing throughput at sub-50-millisecond latency thresholds.
United States
Pentagon predictive analytics contracts and FDA-guided medical device AI drive dual demand streams. The National Institute of Standards and Technology calibrates conformity assessment frameworks for high-risk automated systems. Boston and Austin engineering clusters concentrate talent for human-in-the-loop validation tooling.
Germany
Federal Office for Information Security harmonization of state-level AI accreditation accelerates vendor consolidation. The EU AI Act's mandatory audit trails redirect Baden-Württemberg automotive OEM procurement toward pre-certified governance frameworks. Stuttgart Tier 1 suppliers pilot neuromorphic architectures for in-cabin occupancy detection.
China
SAMR algorithmic recommendation provisions and dual carbon goals shape divergent deployment strategies. MIIT standardization efforts for industrial AI interface with GB compliance requirements for automated decision systems. Yangtze River Delta manufacturing hubs integrate sensor fusion platforms with digital twin simulations.
India
PLI scheme semiconductor assembly incentives attract edge AI chip design partnerships. CDSCO parallel track pathways for AI-enabled diagnostics create regulatory arbitrage opportunities against EU MDR timelines. Bengaluru and Hyderabad engineering centers concentrate specialized firmware development capacity.
United Kingdom
Ministry of Defence framework agreements for autonomous systems coordination mirror NATO procurement acceleration. The Information Commissioner's Office GDPR enforcement creates cross-border data friction for financial institutions deploying credit underwriting models. London financial services clusters invest in explainability tooling for audit-ready output generation.
Digital Intelligence Technology Market Vendor Landscape
Capability concentration sits with specialized AI infrastructure designers; scale advantage sits with hyperscaler cloud platforms bundling compute with pre-trained model APIs. The vendor base stratifies into three tiers: captive silicon designers with foundry relationships, vertically integrated cloud operators, and domain-specific software layer specialists. Dominant competitive moves center on security pre-clearance credentialing for defense procurement and geographic diversification of training hardware supply.
Within the hyperscaler tier, NVIDIA and Microsoft exemplify divergent strategic positioning. NVIDIA anchors the specialized AI infrastructure segment through CUDA ecosystem lock-in for training workloads. Microsoft occupies a position in enterprise productivity integration, extending copilot architectures across software stacks. Alphabet sits between these archetypes with vertically integrated tensor processing units for cloud inference.
| Leading Market Players |
|---|
| NVIDIA |
| Alphabet |
| Microsoft |
| IBM |
| Oracle |
| OpenAI |
| Meta |
| Amazon Web Services |
| Intel |
| Others |
Supply Flow & Price Mechanics
Taiwan Semiconductor Manufacturing capacity utilization above 90 percent has compressed GPU availability timelines and amplified pricing leverage for AI training hardware vendors serving hyperscaler buyers. This tightness propagates through cloud compute bundles and edge inference systems alike, forcing procurement offices to accept extended delivery schedules or migrate to alternative architectures.
Pricing Analysis
Long-term framework agreements dominate defense and intelligence procurement, while spot purchasing persists for experimental AI training workloads at financial institutions. Three-tier pricing structure across premium certified, standard compliant, and economy unvalidated levels separates vendors with EU AI Act pre-certification from commodity analytics providers. Cost compression in cloud-based deployment segments is intensifying because European grid price spikes have eroded margin buffers for hyperscaler-operated infrastructure. Government agencies show least price sensitivity given security pre-clearance requirements, whereas retail businesses face acute pressure from open-source alternative maturation.
Supply Chain Analysis
Extended payment terms from hyperscaler buyers have strained foundry cash conversion cycles, prompting supply-chain finance facilities at Taiwan Semiconductor Manufacturing and Samsung Foundry. Advanced AI training hardware concentrates in Taiwan, South Korea, and the United States, while edge inference chip assembly draws from India, Vietnam, and Malaysia under PLI-style incentives. CoWoS advanced packaging capacity, high-bandwidth memory stacks, and specialized photomask equipment represent critical input dependencies. Single-source vulnerability around Taiwan Strait logistics chokepoints threatens 18-24 month lead time stability. Distribution runs through direct OEM relationships for defense applications and hyperscaler cloud marketplaces for enterprise consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU AI Act, FDA guidance, and SAMR provisions has splintered compliance requirements, creating specialized niches for governance-framework vendors and human-in-the-loop integration specialists.
For Market Incumbents: Insulate installed base relationships by embedding EU AI Act audit logging into core product architectures before notified body backlogs extend competitive certification timelines. Pre-integrate explainability tooling for German automotive OEM procurement cycles. Acquire specialized compliance documentation talent concentrated in Berlin and Paris to accelerate customer deployment velocity.
For New Entrants and Emerging Players: Mid-market healthcare providers in India awaiting CDSCO parallel track approvals represent the most penetrable entry point against EU MDR timeline disadvantages. Bengaluru and Hyderabad engineering partnerships for edge AI chip firmware development offer low-capital technology access. Target outcome-based service contracting for manufacturing uptime guarantees as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with pre-certified governance frameworks serving NATO defense procurement offices. Long-term viability over the coming decade rests on regulatory credential transferability across jurisdictions. Monitor notified body certification timeline divergence between EU MDR and FDA parallel review pathways as the critical inflection signal for healthcare AI valuation spreads.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certified Governance Framework Development | EU AI Act conformity assessments compress procurement cycles for German automotive OEMs. |
| Neuromorphic Edge Chip Partnership | Stuttgart Tier 1 suppliers pilot spiking neural networks for sub-milliwatt in-cabin detection. |
| Human-in-the-Loop Validation Platform Launch | Boston and Austin engineering clusters concentrate scarce interpretability talent pools. |
| India Semiconductor Assembly Joint Venture | PLI scheme incentives attract divergent technology strategies for edge AI localization. |
| Defense Security Pre-Clearance Acquisition | NATO procurement offices in Mons consolidate vendor relationships around embedded credentials. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers, automotive platform engineers, healthcare regulatory affairs leads, and cloud infrastructure architects. Secondary validation drew from SEC hyperscaler capex disclosures, EU notified body certification databases, FDA 510(k) submission logs, and TSMC foundry capacity allocation reports. Bottom-up segment sizing triangulated against top-down macroeconomic calibration.
Calibration against historical deployment velocity and regulatory implementation timelines anchored projections across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type, end-user vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating GPU supply constraints and compliance cost escalations. Energy price volatility and foundry capacity allocation served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in European grid pricing, Taiwan Strait logistics stability, or EU AI Act enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization pace and training hardware supply normalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Egypt Artificial Intelligence Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Oil and Gas Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Stadium Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
Industrial AI Software Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market