
 Hot Drinks Packaging Market | 2026-2036
Hot Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Drinks Packaging Market Outlook
Vietnam is rewriting regional supply dynamics through expanded paperboard converting capacity serving ASEAN beverage exporters. Huhtamaki leverages integrated fiber sourcing across Nordic mills to sustain cost-advantaged cup stock production. Tetra Pak International S.A. anchors aseptic carton technology leadership for ambient liquid concentrates. Amcor plc dominates flexible pouch formats through barrier film innovation targeting premium instant coffee brands.
Hot Drinks Packaging encompasses primary and secondary containment systems engineered to preserve aroma, moisture stability, and thermal integrity for coffee, tea, and cocoa products, typically employing multi-layer laminates with oxygen transmission rates below 0.1 cc per square meter per day to extend shelf life. The category serves commercial roasters, foodservice operators, and retail consumers requiring portion control, brand differentiation, and logistics efficiency. Paper-based materials lead volume share due to fiber recovery mandates and consumer preference for renewable substrates in European and North American markets. Plastic formats retain growth momentum in emerging economies where cost barriers and humidity resistance priorities favor polyethylene and polypropylene constructions. Single-serving pods command premium positioning within the product type matrix, though sachet economics dominate mass-market penetration in Asia-Pacific and Latin American geographies.
The EU Green Deal and F-Gas Regulation shape material substitution timelines, with REACH compliance costs filtering smaller converters from Western European supply chains. FDA food contact notification requirements govern US import pathways for novel barrier coatings, while China's GB standards enforce migration limits on recycled content incorporation. BIS certification in India creates market access friction for unqualified foreign suppliers of metal canister formats. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional compliance investments versus portfolio rationalization.
Market Dynamics
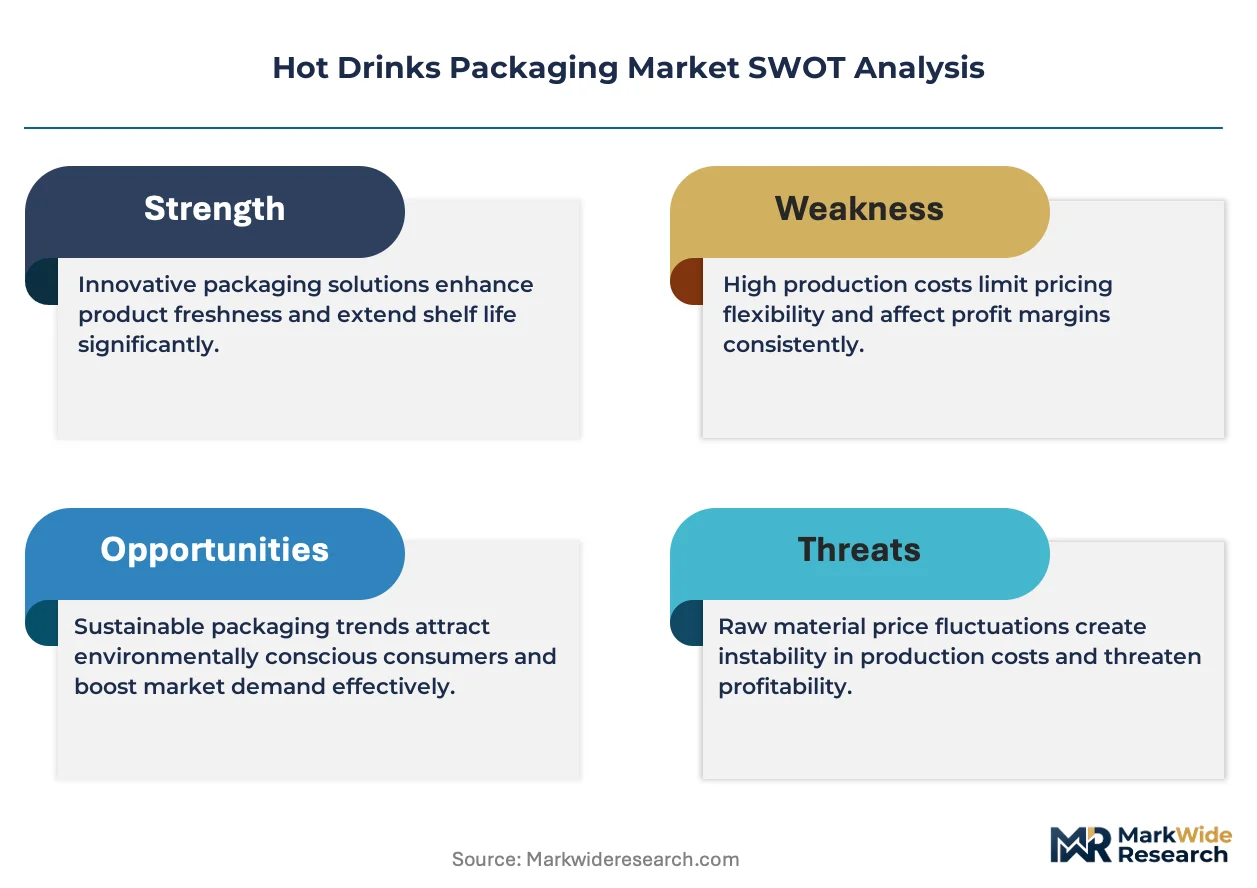
The EU Single-Use Plastics Directive is forcing material transitions across the hot drinks packaging value chain, compelling converters to abandon multi-layer laminates in favor of mono-material or fiber-based alternatives that satisfy extended producer responsibility frameworks.
Growth Catalysts
- Compostable pod mandates:Germany's specialty coffee chains are accelerating demand for certified compostable single-serve pods as municipal composting infrastructure expands.
- Fiber recovery economics:Paper-based materials lead volume share due to fiber recovery mandates and consumer preference for renewable substrates in European and North American markets.
- Aseptic carton penetration:Tetra Pak's aseptic carton technology anchors ambient liquid concentrate packaging, extending shelf life without refrigeration across tropical climates.
Market Restraints
- Aluminum foil supply concentration:High-barrier laminate production depends on concentrated aluminum foil supply from Chinese smelters, exposing converters to input cost volatility and trade policy friction.
- REACH compliance filtering:The EU's REACH regulation creates compliance cost barriers that exclude smaller converters from Western European supply chains.
- Humidity resistance trade-offs:Fiber-based formats face technical limitations in high-humidity environments where polyethylene and polypropylene constructions retain performance advantages.
Strategic Opportunities
- Brazilian coffee belt expansion:Demand is concentrating in Brazil's southern coffee belt states, creating white space for localized converting capacity serving South American exporters.
- ASEAN paperboard integration:Vietnam's expanded paperboard converting capacity serves ASEAN beverage exporters, rewriting regional supply dynamics through integrated fiber sourcing.
- Flexible pouch premiumization:Barrier film innovation targets premium instant coffee brands, displacing rigid canisters in urban retail channels.
Industry Challenges
- Migration testing bottlenecks:FDA food contact notification requirements for novel barrier coatings create extended certification timelines that delay US market entry.
- Legacy equipment retrofit costs:Converters face capex intensity from reconfiguring forming and sealing lines to handle compostable materials with different thermal profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Drinks Packaging Market |
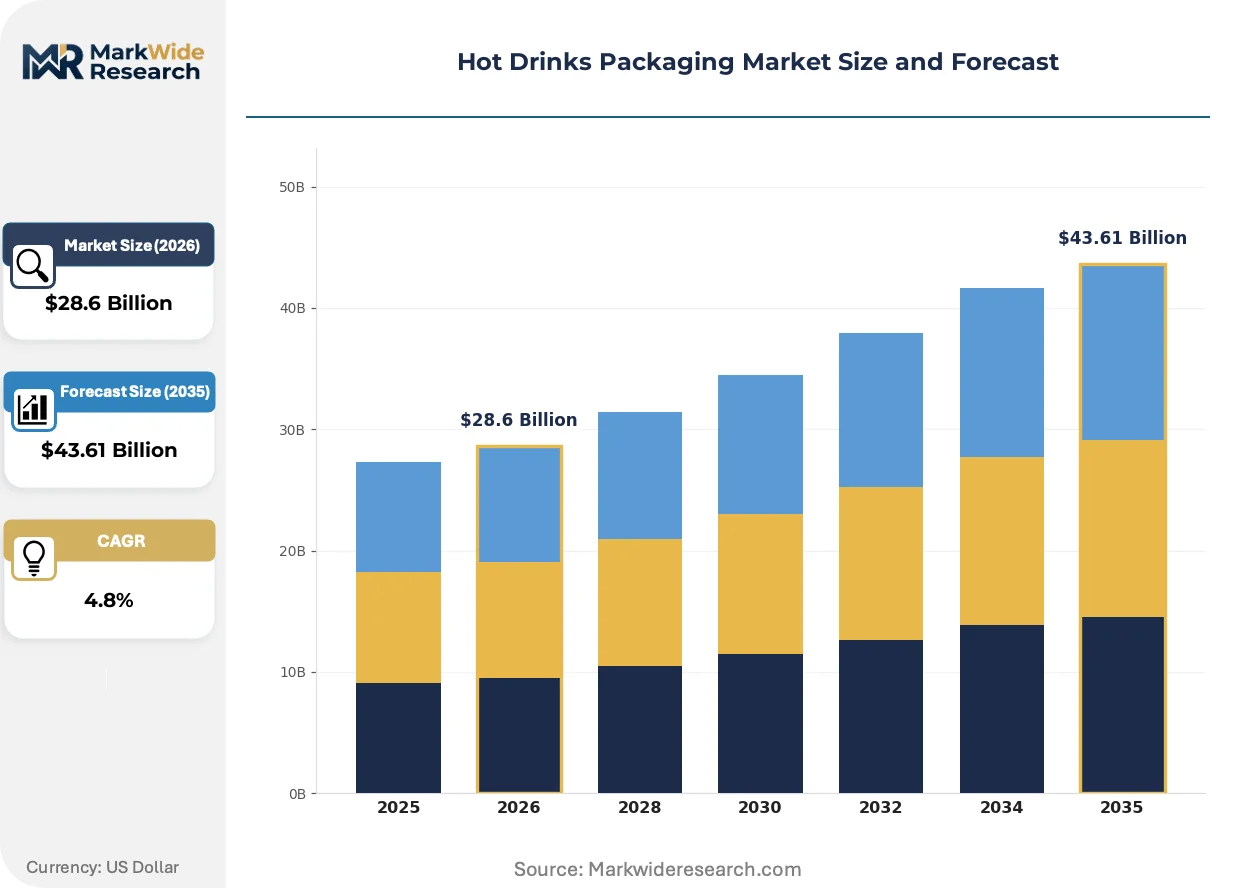
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Serving, Sachets, Pouches, Tetra Packs Material: Paper, Plastic, Glass, Metal Form: Liquid, Powder, Granulated, Concentrate End User: Cafes, Restaurants, Households, Retail Outlets |
| Companies Covered | Huhtamaki, Sealed Air, ProAmpac, Tetra Pak International S.A., Amcor plc, Sonoco, Graphic Packaging International, Stora Enso, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Drinks Packaging Market Strategic Shifts
Active packaging intelligence and material science convergence are reshaping competitive positioning in hot drinks containment, with digital traceability and regulatory compliance automation emerging as primary investment vectors.
Smart packaging incorporating printed electronics and NFC tags is digitizing supply chain visibility for premium coffee roasters. Specialty brands in Nordic markets are adopting these solutions at pilot scale. The technology is digitizing authentication and provenance verification, compressing information asymmetry between origin and retail.
REACH and the EU F-Gas Regulation are accelerating fluorochemical phase-outs in barrier coatings. Industrial consequence includes forced reformulation of oxygen barrier layers below 0.1 cc per square meter per day. Premium single-serve pod manufacturers in Germany and Benelux are responding with plasma-enhanced chemical vapor deposition alternatives.
Direct-to-roaster procurement models are compressing traditional distributor margins in specialty coffee packaging. Small-batch roasters in Melbourne and Portland are sourcing custom-printed flexible pouches through digital print platforms. This pattern is most visible in third-wave coffee verticals where batch traceability and design agility outweigh unit cost minimization.
Hot Drinks Packaging Market Segmentation
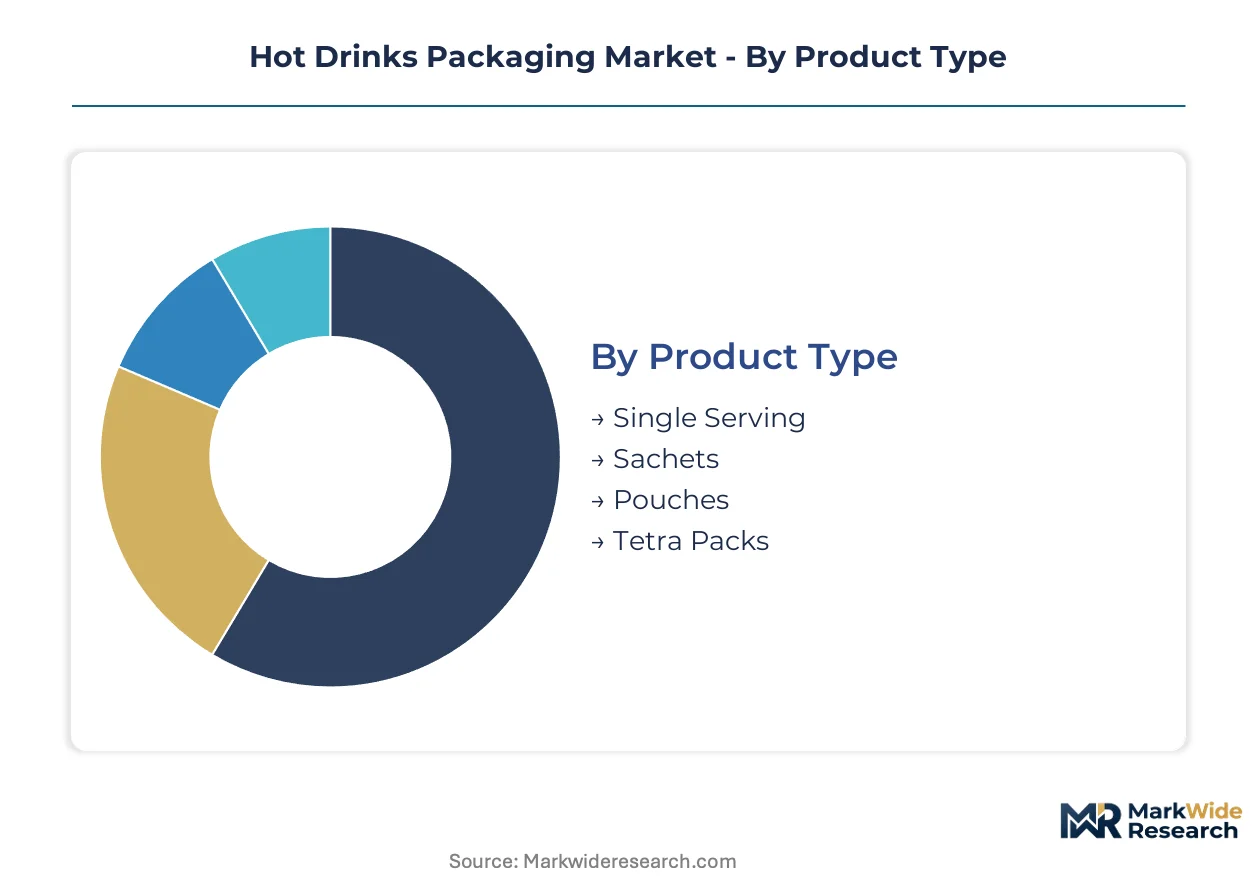
Hot drinks packaging segmentation reflects divergent technical requirements across preparation methods, shelf stability needs, and consumption contexts. Material science capabilities and regulatory compliance thresholds vary sharply by product geometry and end-use environment.
Product Type:
Use cases span from on-the-go convenience to bulk foodservice operations, with format selection driven by brewing equipment compatibility and waste infrastructure availability.
- Single Serving:Compostable pods and capsules employ multi-layer barrier films with oxygen transmission rates below 0.1 cc per square meter per day. Germany's specialty coffee chains are accelerating certified compostable adoption as municipal composting infrastructure expands.
- Sachets:Small-format laminated pouches dominate mass-market instant coffee and tea distribution in Asia-Pacific and Latin American geographies where unit economics prioritize affordability over premium positioning.
- Pouches:Flexible stand-up and flat pouches serve premium instant coffee brands through barrier film innovation, displacing rigid canisters in urban retail channels.
- Tetra Packs:Aseptic carton technology anchors ambient liquid concentrate packaging, extending shelf life without refrigeration across tropical climates.
Established volume favors sachets; emerging adoption favors single serving.
Material:
Cost tiers separate commodity substrates from performance-engineered constructions, with regulatory mandates accelerating substitution timelines.
- Paper:Fiber-based cup stock and paperboard lead volume share in European and North American markets due to fiber recovery mandates and consumer preference for renewable substrates. REACH and the EU F-Gas Regulation are accelerating fluorochemical phase-outs in barrier coatings.
- Plastic:Polyethylene and polypropylene constructions retain performance advantages in high-humidity environments where fiber-based formats face technical limitations. Growth momentum concentrates in emerging economies where cost barriers favor plastic formats.
- Glass:Premium positioning for specialty loose-leaf tea and cocoa powder leverages inert surface properties and reusability signaling, though weight and fragility constrain distribution economics.
- Metal:Tinplate and aluminum canisters serve gift-grade and bulk formats, with BIS certification in India creating market access friction for unqualified foreign suppliers.
Paper commands the steepest expansion trajectory in regulated markets; plastic retains cost advantages in price-sensitive geographies.
Form:
Application requirements dictate moisture stability, dissolution kinetics, and packaging barrier intensity.
- Liquid:Ready-to-drink concentrates and extracts require aseptic processing and oxygen-impermeable containment, with Tetra Pak's technology leadership concentrated in ambient distribution networks.
- Powder:Spray-dried and freeze-dried instant coffee demands humidity-resistant laminates, with flexible pouch formats gaining share from rigid alternatives.
- Granulated:Agglomerated instant coffee particles balance solubility and flow properties, typically packaged in composite cans or laminated pouches depending on volume tier.
- Concentrate:High-solids liquid extracts for foodservice and retail dilution require oxygen barrier performance comparable to liquid formats.
Powder maintains volume dominance; liquid concentrates are climbing fastest in foodservice penetration.
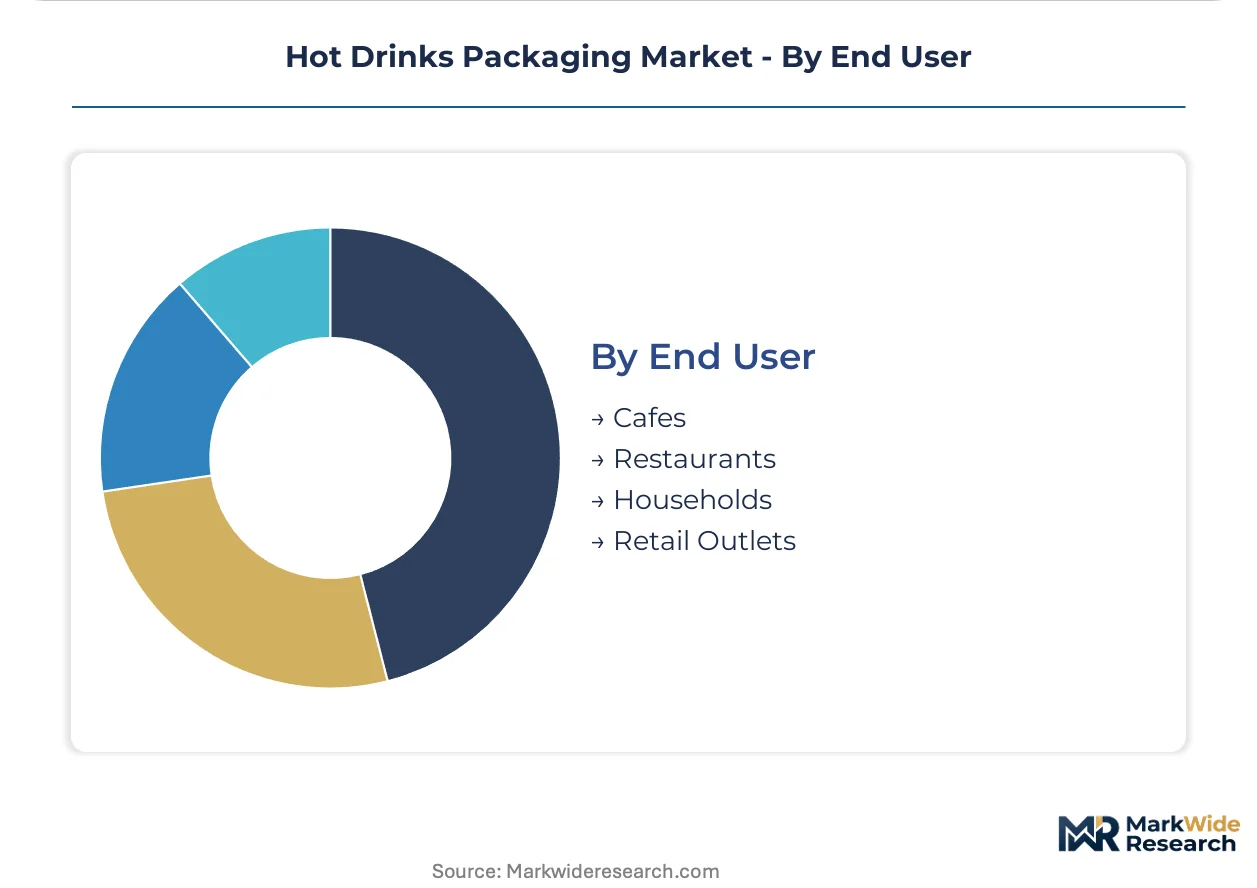
End User:
Customer type determines order scale, customization requirements, and sustainability certification intensity.
- Cafes:Specialty coffee chains in Germany and Nordic markets drive compostable pod specifications and smart packaging pilots with printed electronics and NFC tags for provenance verification.
- Restaurants:Foodservice operators prioritize portion control and operational efficiency, sourcing bulk concentrates and single-serve formats through distributor networks.
- Households:Retail consumers exhibit bifurcated demand between premium single-serve convenience and value-oriented sachet economics.
- Retail Outlets:Supermarkets and convenience stores stock shelf-stable formats with extended dating, with flexible pouches displacing rigid canisters in urban channels.
Households anchor current volume; cafes are gaining share fastest on sustainability premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese aluminum foil smelters supply the majority of high-barrier laminate substrates, creating input cost volatility that ripples through European and North American converting operations. Converter capacity clusters in Germany, Vietnam, and Brazil are reshaping regional procurement patterns for coffee roasters and tea blenders.
Germany
Specialty coffee chains in Berlin and Hamburg are accelerating certified compostable single-serve pod adoption as municipal composting infrastructure expands. The EU Single-Use Plastics Directive and F-Gas Regulation are forcing fluorochemical phase-outs in barrier coatings, compelling reformulation of oxygen barrier layers. The North Rhine-Westphalia industrial corridor hosts concentrated flexible packaging converting capacity serving Benelux roasters.
United States
Third-wave coffee roasters in Portland and Melbourne-sister cities are sourcing custom-printed flexible pouches through digital print platforms, compressing traditional distributor margins. FDA food contact notification requirements for novel barrier coatings create extended certification timelines that delay market entry for European converters. The Pacific Northwest cluster anchors specialty coffee packaging innovation with smart packaging pilots.
Vietnam
Expanded paperboard converting capacity in Ho Chi Minh City and Hanoi is serving ASEAN beverage exporters, rewriting regional supply dynamics through integrated fiber sourcing. The country's GB standards alignment for migration limits on recycled content incorporation is creating technical compliance pathways for Chinese equipment suppliers. The Mekong Delta region is emerging as a fiber sourcing hub for cup stock production.
Brazil
Demand is concentrating in São Paulo and Minas Gerais states within the southern coffee belt, creating white space for localized converting capacity serving South American exporters. ANVISA regulations govern food contact materials for instant coffee and ready-to-drink concentrates distributed through tropical climate networks. The Campinas industrial corridor is attracting flexible pouch investments targeting premium instant coffee brands.
India
BIS certification requirements for metal canister formats are creating market access friction for unqualified foreign suppliers, protecting domestic converters in Maharashtra and Gujarat. FSSAI migration limits on recycled content incorporation are shaping material specifications for tea and spice packaging. The Mumbai-Pune industrial belt hosts the majority of domestic flexible laminate capacity serving retail sachet economics.
Hot Drinks Packaging Market Competitive Environment
Integrated multinational converters and regional fiber specialists split the market into distinct capability tiers. Consolidation pressure is intensifying as REACH compliance costs and aluminum foil supply concentration filter smaller players from Western European supply chains. Three archetypes dominate: Nordic fiber-integrated giants with captive pulp sourcing, Asia-Pacific scale players leveraging equipment cost advantages, and specialty barrier film innovators targeting premium instant coffee brands. Competitive moves center on backward integration into fiber sourcing and strategic partnerships with municipal composting operators.
Within the fiber-integrated tier, Huhtamaki and Stora Enso exemplify Nordic-based players leveraging captive mill networks to sustain cost-advantaged cup stock production. Tetra Pak International S.A. occupies a distinct position anchoring aseptic carton technology leadership for ambient liquid concentrates. Amcor plc represents the barrier film innovation archetype, with flexible pouch formats targeting premium instant coffee brands in urban retail channels.
| Leading Market Players |
|---|
| Huhtamaki |
| Sealed Air |
| ProAmpac |
| Tetra Pak International S.A. |
| Amcor plc |
| Sonoco |
| Graphic Packaging International |
| Stora Enso |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
Converter undercapacity in Vietnam's paperboard sector is driving aggressive capacity expansion bids while simultaneously compressing margins for European converters facing REACH compliance cost escalation. This utilization asymmetry between ASEAN growth markets and mature regulatory jurisdictions shapes supplier pricing power and procurement migration patterns across the hot drinks packaging value chain.
Pricing Analysis
The EU Single-Use Plastics Directive dictates the pricing tier structure across the hot drinks packaging landscape, separating premium compostable pod formats from standard polyethylene constructions and economy-grade sachet laminates. Price differentiation hinges on certification grade for industrial compostability and volume scale of production runs. Pricing pressure stems from aluminum foil input cost volatility originating from Chinese smelter concentration. Mass-market sachet buyers in Asia-Pacific exhibit highest price sensitivity, while German specialty coffee chains demonstrate lowest sensitivity due to sustainability premium capture.
Supply Chain Analysis
Huhtamaki, Tetra Pak International S.A., and Amcor plc anchor contract-manufacturing capacity across Nordic, Swiss, and Asia-Pacific production networks. Geographic supply concentration centers on Germany, Vietnam, and Brazil for converting operations, with raw material dependencies on Chinese aluminum foil, Nordic pulp fibers, and Brazilian resin feedstocks. Supply chain risk rests on single-source vulnerability for high-barrier laminate substrates. Distribution runs through roaster-direct procurement models compressing traditional distributor margins in specialty coffee verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among specialty coffee chains and multinational roasters, fragmenting the downstream customer base into fewer volume-heavy accounts with sustainability specification leverage.
For Market Incumbents: Build regulatory compliance moats through REACH certification depth and municipal composting infrastructure partnerships. Defensive moves require backward integration into Nordic pulp sourcing to sustain cost-advantaged cup stock production against ASEAN scale players. Huhtamaki's integrated fiber network exemplifies this lever. Threat substitution from digital print platforms enabling direct-to-roaster procurement demands channel control reinforcement through design agility investments. For New Entrants and Emerging Players: Mid-market flexible pouch converters in Brazil's southern coffee belt states represent the most penetrable entry point for serving South American exporters with localized capacity. White space exists in ASEAN paperboard integration serving Vietnamese beverage exporters through GB standards-aligned equipment pathways. Go-to-market execution should anchor on plasma-enhanced chemical vapor deposition barrier technology as fluorochemical phase-out accelerates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across compostable material handling and legacy equipment retrofit requirements. Long-term viability favors fiber-integrated converters with captive pulp sourcing over pure-play barrier film specialists. Acquisition target archetype: regional flexible packaging converters in Vietnam or Brazil with municipal composting operator relationships. Signal to monitor: FDA food contact notification backlog duration as inflection indicator for US market entry friction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Sourcing | Nordic mill networks enable cost-advantaged cup stock production against ASEAN competitors. |
| Compostable Material Certification | OK Compost INDUSTRIAL and HOME tiers unlock German specialty coffee chain procurement specifications. |
| Plasma-Enhanced Barrier Deposition | Fluorochemical-free oxygen barriers below 0.1 cc per square meter per day satisfy REACH compliance. |
| Digital Print Platform Deployment | Direct-to-roaster procurement models compress traditional distributor margins in third-wave coffee segments. |
| Municipal Composting Partnership | Infrastructure alignment ensures end-of-life pathway validity for certified compostable pod claims. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and industry association datasets. Primary interviews engaged packaging converters, specialty coffee roasters, foodservice procurement directors, and municipal waste management operators across Germany, Vietnam, Brazil, and the United States. Secondary validation drew from ECHA REACH substance registrations, ANVISA food contact material notifications, FDA food contact substance inventories, and FAO coffee trade statistics. Bottom-up volume modeling triangulated against top-down market sizing from macroeconomic consumption indicators.
Forecast inputs incorporate material substitution timelines under EU Single-Use Plastics Directive implementation, fiber recovery mandate expansion patterns, and aseptic carton penetration curves across tropical climate distribution networks. Segmentation dimensions span product type geometry, material substrate compliance tier, preparation form stability requirements, and end-user channel concentration. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory inflection points and capacity utilization signals across the analysis window.
Practitioners should monitor aluminum foil tariff exposure, municipal composting infrastructure buildout rates, and FDA notification backlog duration for early signals of forecast revision. Assumptions underlying projections reflect current regulatory enforcement intensity and fiber sourcing cost structures. Quarterly review of REACH substance restriction proposals and ASEAN paperboard capacity commissioning announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Ready Meals Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Global Disposable Plates Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
Frozen Seafood Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Cupcake Containers Market
Food Packaging
Fast Food Containers Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Insulated Food and Beverage Carriers Market