
 Europe Food Packaging Market | 2026-2036
Europe Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Packaging Market Foresight
A capital-intensity divergence between integrated fiber-based producers and specialty flexible film converters is redrawing competitive boundaries across the continent. DS Smith leverages its recycled paperboard infrastructure to anchor supply contracts with major retail chains. Amcor plc sustains technology leadership in high-performance barrier films through dedicated European R&D centers. Smurfit Kappa Group PLC dominates corrugated fresh-produce logistics with integrated containerboard mills in Iberia and the Nordics.
Europe food packaging encompasses engineered containment systems manufactured from paper, plastic, glass, metal, or composite substrates, designed to preserve organoleptic properties, prevent contamination, and extend shelf life through controlled permeability or inert atmospheres. Flexible packaging leads volume share in snack and confectionery applications, while aseptic packaging commands premium positioning in ambient dairy and plant-based beverages where thermal stability determines distribution reach. Modified atmosphere technology is displacing conventional vacuum methods in fresh protein segments as retailers demand longer case-ready display windows.
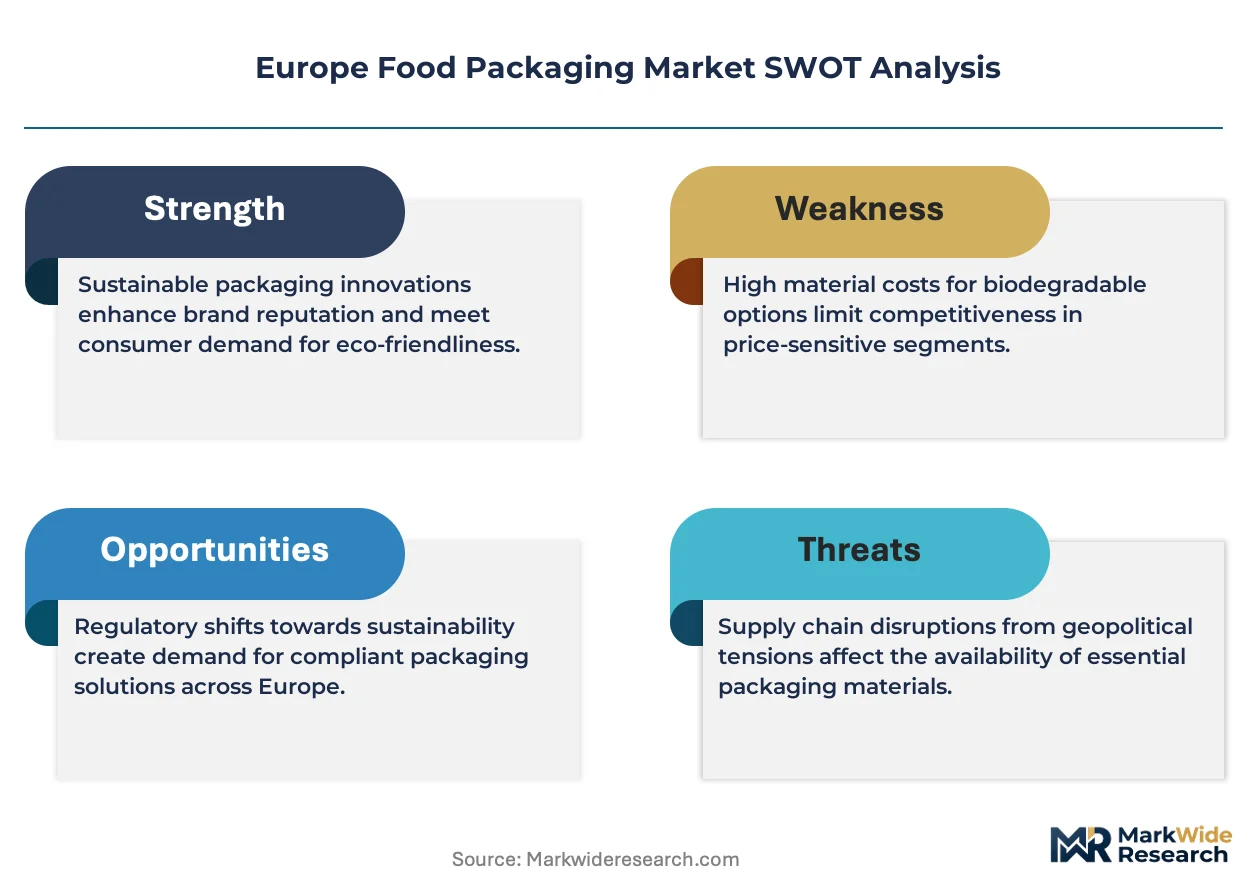
EU Green Deal targets, REACH chemical compliance, and the Packaging and Packaging Waste Regulation collectively mandate minimum recycled content thresholds and extended producer responsibility schemes that reshape material procurement decisions. EFSA safety evaluations for food-contact substances create additional compliance layers for barrier coating innovations entering the market. Stakeholders must monitor harmonized Extended Producer Responsibility fee structures and recyclability labeling requirements as these mechanisms determine cost allocation between converters and brand owners.
Market Dynamics
The EU Green Deal and Packaging and Packaging Waste Regulation are forcing material transitions across the value chain. Recycled content mandates and extended producer responsibility schemes are redrawing procurement decisions for converters and brand owners alike.
Growth Catalysts
- Ready-to-eat meal expansion:European food manufacturers are extending shelf-life specifications for prepared foods. This is pulling demand for high-performance barrier films and modified atmosphere technologies.
- EU Green Deal targets:Minimum recycled content thresholds are accelerating investment in fiber-based and mono-material packaging streams. Brand owners are locking in supply contracts with integrated paperboard producers.
- EFSA safety pathway:Streamlined food-contact substance evaluations are shortening time-to-market for novel barrier coatings. Innovation cycles in bio-based films are compressing as a result.
Market Restraints
- Recycled resin quality variance:Post-consumer plastic feedstock inconsistency is limiting high-barrier film yields. Converters face yield losses and rework costs in flexible packaging lines.
- Energy cost concentration:Containerboard and glass production remain exposed to natural gas pricing in Germany and Italy. Energy-intensive segments face margin pressure during price spikes.
- Substitution pressure from reusable systems:Loop and similar platforms are capturing premium beverage and personal care segments. Single-use formats face demand erosion in urban test markets.
Strategic Opportunities
- Central and Eastern Europe underpenetration:Poland and Romania show gap versus Western European packaging intensity. Local production capacity in barrier films remains limited relative to food processing growth.
- Smart packaging convergence:Integration of time-temperature indicators with RFID tracking is opening premium cold-chain segments. Pharmaceutical-grade traceability is migrating into fresh protein logistics.
- Retailer private-label consolidation:Aldi and Lidl are centralizing packaging specification authority. Approved supplier lists are narrowing, favoring scale players with pan-European service capability.
Industry Challenges
- Barrier coating R&D talent scarcity:Formulation chemists with food-contact compliance expertise command premium compensation. Smaller converters struggle to retain technical staff against multinational R&D centers.
- Legacy equipment retrofit complexity:Mono-material film transitions require extruder and sealing jaw modifications. Capital deployment timelines stretch 18-24 months for mid-scale flexible packaging lines.
- Harmonized EPR fee uncertainty:Pending fee structure decisions across member states are freezing long-term contract pricing. Brand owners are delaying multi-year packaging redesign commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Packaging Market |
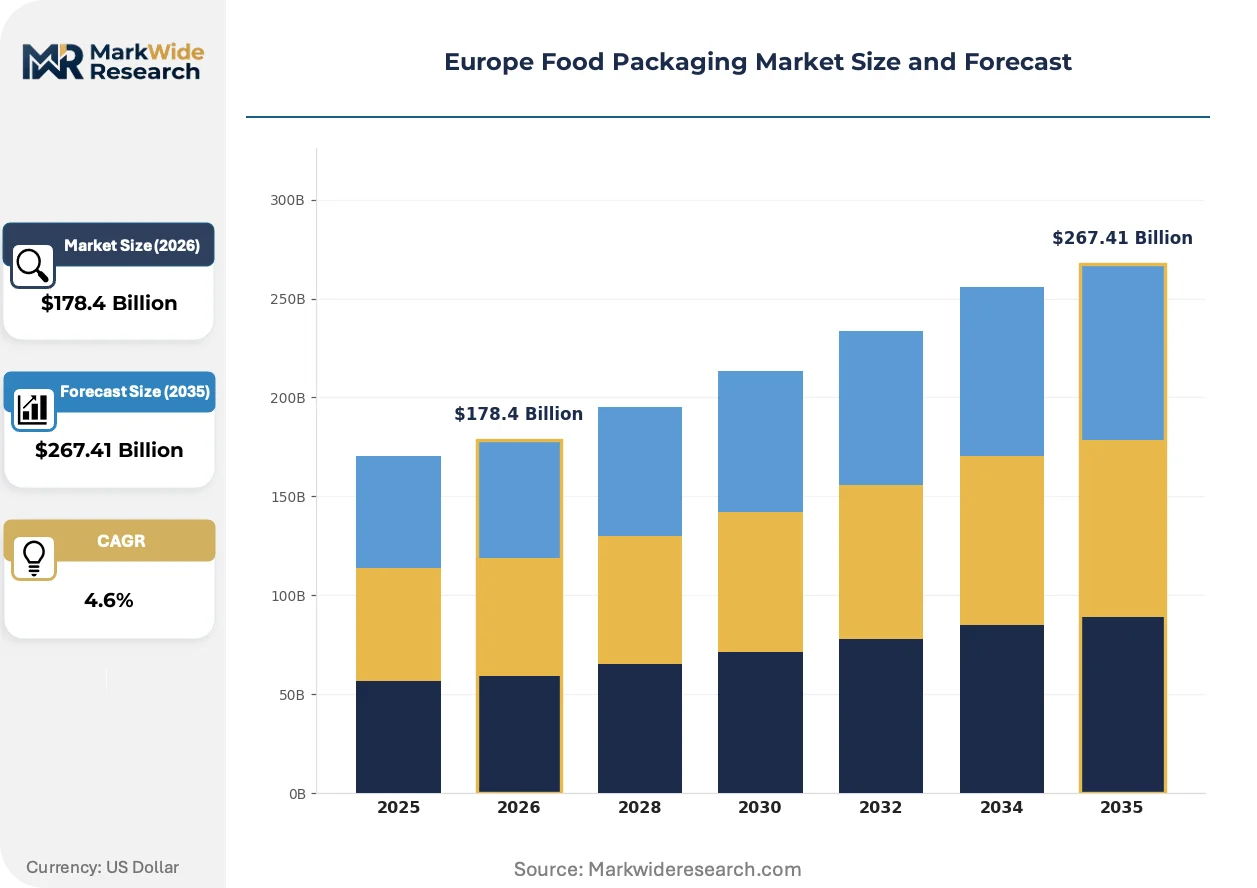
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $267.41 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Rigid Packaging, Semi-Rigid Packaging, Aseptic Packaging Material: Plastic, Glass, Metal, Paper End User: Food Manufacturers, Retailers, Food Service, Consumer Goods Technology: Barrier Coatings, Vacuum Packaging, Modified Atmosphere Packaging, Smart Packaging |
| Companies Covered | Tetra Laval International S.A., DS Smith, Amcor plc, ALPLA, Smurfit Kappa Group PLC, Mondi plc, Huhtamäki Oyj, Greiner Packaging GmbH, Smurfit WestRock, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory compliance automation are converging to reshape competitive positioning. Digital tooling and bio-based chemistry are unlocking performance thresholds previously reserved for conventional plastics.
Mono-material polyethylene barrier films are displacing multi-layer laminates in snack and frozen food applications. Retailers in France and Germany are specifying these structures to meet recyclability labeling requirements. The shift is compressing demand for ethylene vinyl alcohol and polyamide interlayers.
REACH chemical compliance automation is reducing formulation approval timelines for food-contact coatings. ECHA database integration is enabling real-time substance screening during R&D. Small and mid-sized converters in Italy and Spain are adopting these platforms fastest to offset limited in-house regulatory staff.
Direct-store-delivery networks are shortening order cycles for fresh-produce packaging. Regional supermarket chains are bypassing central distribution to reduce handling damage. Corrugated tray specifications are fragmenting as a result, with Iberian retailers driving demand for smaller batch sizes and faster design turnaround.
Europe Food Packaging Market Segmentation
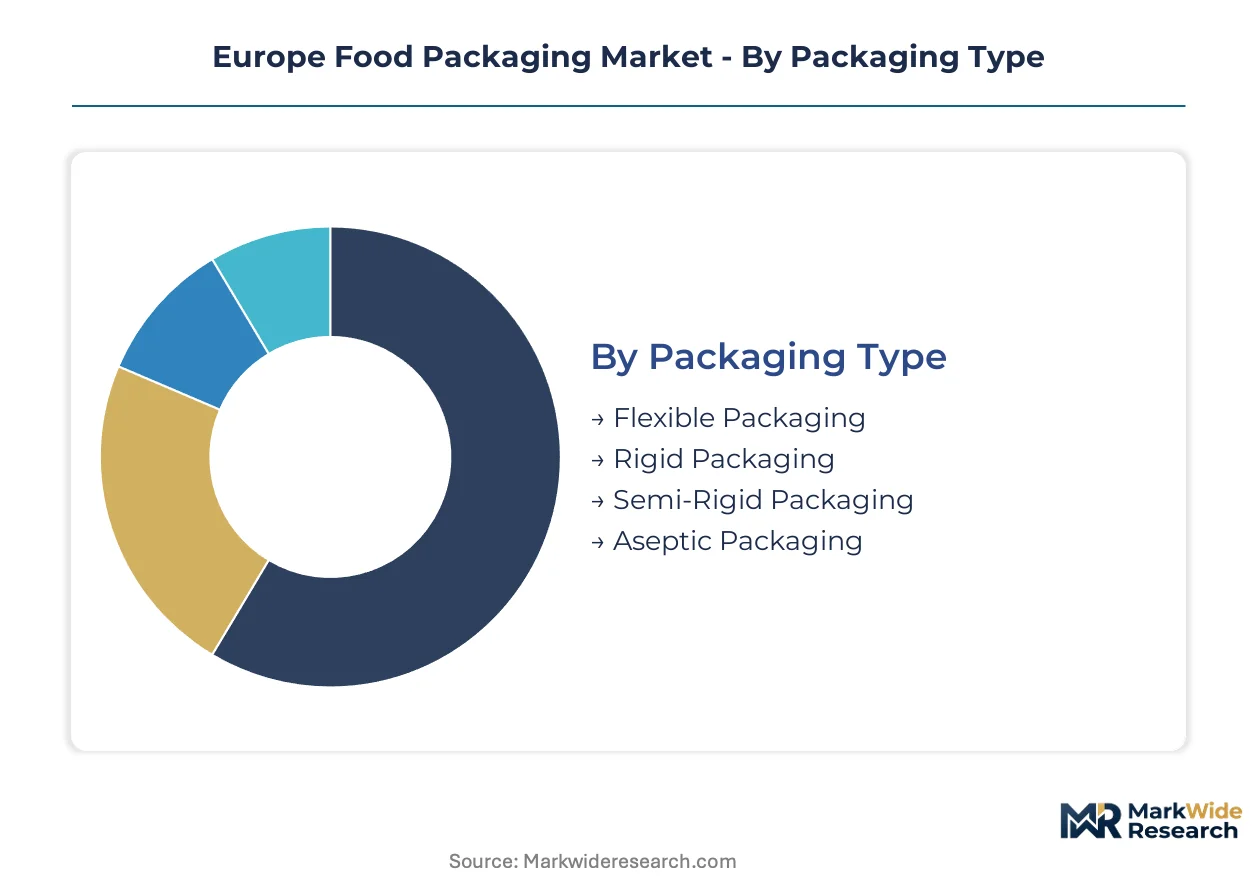
Material substitution pressures and regulatory thresholds reshape segment boundaries across European food packaging. Converters must align portfolio composition with EFSA compliance pathways and EU Green Deal recycled content mandates.
Packaging Type:
Substitution pressure from fiber-based alternatives hits rigid formats hardest while flexible structures defend share through mono-material innovation.
- Flexible Packaging:Multi-layer films and pouches deliver oxygen and moisture barriers for snack, confectionery, and frozen food applications. Demand concentrates in Germany and France where retailers mandate recyclability labeling for private-label ranges.
- Rigid Packaging:Thermoformed trays, bottles, and containers provide structural protection for dairy, ready meals, and beverages. Substitution threat from molded fiber intensifies in Nordic markets with advanced collection infrastructure.
- Semi-Rigid Packaging:Combines dimensional stability with reduced material weight for fresh produce and deli applications. Italian converters lead format development for premium charcuterie and cheese segments.
- Aseptic Packaging:Sterilized carton and bottle systems enable ambient distribution for plant-based beverages and extended-shelf-life dairy. Technology licensing from Swedish and Swiss equipment suppliers constrains local production scale-up.
Flexible formats anchor the volume base while aseptic packaging gains share at the steepest rate.
Material:
Cost tier stratification separates premium-positioned substrates from commodity alternatives facing margin compression.
- Plastic:Polyethylene, polypropylene, and polyester films dominate barrier applications through controlled permeability engineering. Post-consumer recycled resin quality variance limits high-performance film yields in French and Spanish converter operations.
- Paper:Recycled paperboard and kraft grades capture demand from EU Green Deal recycled content mandates. DS Smith and Smurfit Kappa anchor supply contracts with major retail chains across Iberia and the Nordics.
- Glass:Inert containment for premium sauces, preserves, and beverages retains position in traditional format segments. Energy cost exposure from natural gas pricing in Italy and Germany pressures container economics.
- Metal:Tinplate and aluminum cans deliver hermetic sealing for ambient shelf-stable proteins and vegetables. Eastern European food manufacturers sustain demand for three-piece can formats in processed meat categories.
Paper materials climb the fastest on regulatory tailwinds while plastic retains the largest installed base.
End User:
Application complexity determines specification authority and contract duration across customer categories.
- Food Manufacturers:Industrial buyers of primary and secondary packaging for branded and private-label production. Ready-to-eat meal expansion in German and Benelux processing facilities pulls demand for modified atmosphere technologies.
- Retailers:Centralized packaging specification authority at Aldi and Lidl narrows approved supplier lists. Pan-European service capability becomes a threshold requirement for converter participation.
- Food Service:Disposable containment for takeaway and delivery applications faces reusable system substitution in urban test markets. Loop and similar platforms capture premium beverage segments in Paris and Amsterdam.
- Consumer Goods:Branded food producers with direct distribution relationships demand shorter design turnaround and smaller batch sizes. Direct-store-delivery networks in Iberia fragment corrugated tray specifications.
Food manufacturers represent the deepest contract value while retailers reshape competitive access fastest.
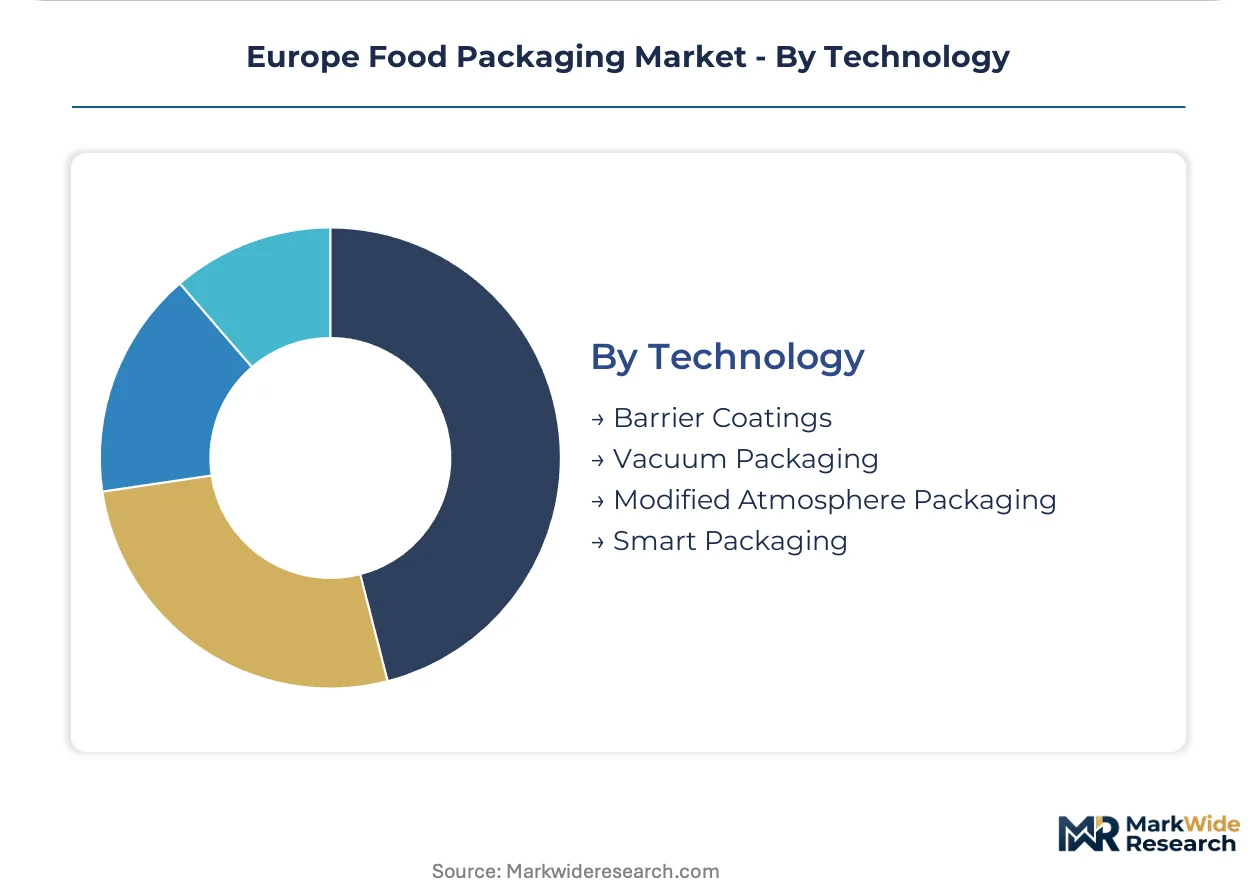
Technology:
Margin concentration follows patent-protected barrier performance and regulatory approval timelines.
- Barrier Coatings:Thin-film deposition and bio-based chemistry replace ethylene vinyl alcohol interlayers in mono-material structures. REACH compliance automation accelerates formulation approval for Italian and Spanish converters.
- Modified Atmosphere Packaging:Gas-flush systems extend case-ready display windows for fresh protein segments. Retailer demand for longer shelf life displaces conventional vacuum methods in UK and French supermarket chains.
- Vacuum Packaging:Negative-pressure sealing for cured meats and hard cheeses faces technology displacement. Legacy equipment retrofit complexity stretches capital deployment timelines for mid-scale flexible lines.
- Smart Packaging:Time-temperature indicators and RFID tracking converge for pharmaceutical-grade traceability in cold-chain logistics. Fresh protein segments in German distribution networks adopt sensor integration fastest.
Barrier coatings defend the technology revenue base while smart packaging expands most quickly at the premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics across the continent reveal a structural surplus in fiber-based packaging from Nordic and Iberian production clusters, while barrier film demand in Central Europe outpaces local converter capacity. Trade flows in food-contact materials increasingly reflect regulatory divergence between EU member states implementing Packaging and Packaging Waste Regulation fee structures.
Germany
Modified atmosphere packaging demand from ready-to-eat meal processors in Baden-Württemberg and North Rhine-Westphalia anchors domestic flexible film consumption. The country's EPR fee structure under EU Green Deal implementation creates pricing uncertainty for brand owners committing to multi-year supply contracts. Berlin-based packaging specification authorities at major retail chains are consolidating approved supplier lists for private-label ranges.
France
Recyclability labeling mandates for supermarket private-label products drive mono-material polyethylene film specifications in the Île-de-France retail corridor. ANSM oversight of food-contact substance approvals intersects with REACH compliance automation adopted fastest by converters in the Lyon industrial basin. The country's dairy and plant-based beverage sectors sustain demand for aseptic carton technology licensed from Swiss equipment suppliers.
Italy
Energy cost exposure from natural gas pricing pressures container glass economics in the Veneto and Emilia-Romagna preserves clusters. EFSA safety evaluation pathways for novel barrier coatings accelerate formulation approval timelines for converters near Bologna. The country's premium charcuterie and cheese segments drive format development in semi-rigid packaging applications.
United Kingdom
Fresh protein retailers in the Midlands and Southeast displace conventional vacuum methods with gas-flush modified atmosphere systems for extended case-ready display windows. Post-Brexit regulatory divergence from EU Green Deal timelines creates compliance complexity for converters serving both UK and continental markets. Smart packaging sensor integration advances fastest in German distribution networks serving British cold-chain logistics.
Poland
Food processing growth in the Warsaw and Łódź manufacturing corridors outpaces local barrier film production capacity, creating import dependency from German and Czech converters. Underpenetration relative to Western European packaging intensity attracts investment interest from integrated paperboard producers. The country's position as a logistics hub for Eastern European distribution amplifies demand for corrugated fresh-produce packaging specifications.
Europe Food Packaging Market Competitive Landscape
Concentration sits with integrated fiber-based producers and multinational flexible film specialists that command pan-European service capability. The vendor base stratifies across three tiers: scale players with captive containerboard mills, technology-licensed aseptic packaging specialists, and regional converters serving fragmented fresh-produce specifications. Strategic moves center on backward integration into recycled pulp supply and geographic expansion into Central European underpenetrated markets.
Within the integrated paperboard tier, DS Smith and Smurfit Kappa Group PLC exemplify scale-driven positioning anchored by mill networks across Iberia and the Nordics. Amcor plc occupies a position representing technology leadership in high-performance barrier films through dedicated European R&D infrastructure. These three entities collectively illustrate the capital-intensity divergence redrawing competitive boundaries between fiber-based and flexible film formats.
| Leading Market Players |
|---|
| Tetra Laval International S.A. |
| DS Smith |
| Amcor plc |
| ALPLA |
| Smurfit Kappa Group PLC |
| Mondi plc |
| Huhtamäki Oyj |
| Greiner Packaging GmbH |
| Smurfit WestRock |
| Others |
Supply & Pricing Matrix
Containerboard mill scale economies in Iberia and the Nordics anchor supply concentration for fiber-based formats, compressing price floors for corrugated fresh-produce logistics while elevating barriers for mid-scale flexible film converters competing on barrier performance.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale and certification-level differentiation separating integrated paperboard producers from specialty converters. Price differentiation stems from EU Green Deal recycled content compliance tiers and pan-European service capability. Cost compression in commodity polyethylene films is intensifying because post-consumer recycled resin quality variance limits high-barrier yields. Private-label retailers at Aldi and Lidl exhibit lowest price sensitivity due to specification authority concentration, while regional fresh-produce distributors face highest sensitivity to corrugated tray batch-size minimums.
Supply Chain Analysis
Baltic Sea containerboard transit underwrites raw material flows for Nordic and Iberian integrated mills serving Western European retail chains. Geographic supply concentrates in Germany, France, and Italy for barrier film conversion, with Sweden and Switzerland anchoring aseptic equipment technology licensing. The chain draws from post-consumer paper pulp, virgin polyethylene resins, and natural gas feedstocks. Single-source vulnerability sits with Swiss and Swedish aseptic technology licensors constraining local production scale-up. Distribution runs through pan-European logistics hubs with direct-store-delivery networks fragmenting specifications in Iberia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier coating formulation services and EFSA compliance consulting expand faster than commodity substrate sales, creating attach-rate opportunities for converters embedding regulatory navigation into long-term supply contracts.
For Market Incumbents: Secure backward integration into recycled pulp supply to defend margin position against fiber-based substitution pressure from DS Smith and Smurfit Kappa. Lock in multi-year EPR fee structures with German and French brand owners before harmonized Extended Producer Responsibility decisions freeze contract pricing. Prioritize R&D retention through dedicated European centers as formulation chemist scarcity intensifies talent competition.
For New Entrants and Emerging Players: Smart packaging sensor integration for fresh protein cold-chain logistics represents the most penetrable service-layer gap where incumbents under-serve mid-scale German distributors. Target Poland and Romania for barrier film production capacity given underpenetration relative to food processing growth. Pursue go-to-market partnerships with regional supermarket chains bypassing central distribution for faster design turnaround.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with REACH compliance automation platforms and bio-based barrier coating pipelines over legacy multi-layer laminate specialists. Long-term viability across the analysis window hinges on mono-material film transition readiness and EFSA approval pathway velocity. Watch for inflection when harmonized EPR fee structures unlock multi-year packaging redesign commitments from frozen brand owners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp Supply | DS Smith and Smurfit Kappa anchor retail contracts through captive Iberian and Nordic mill networks. |
| REACH Compliance Automation Platform Deployment | Italian and Spanish converters offset limited regulatory staff through ECHA database integration. |
| Mono-Material Film Extruder Retrofit | Sealing jaw modifications stretch capital deployment timelines for mid-scale flexible packaging lines. |
| Smart Packaging Sensor Integration | Time-temperature indicators with RFID tracking open premium German fresh protein cold-chain segments. |
| Central and Eastern European Capacity Expansion | Poland and Romania show gap versus Western European packaging intensity relative to food processing growth. |
Research Methodology
A spread of perspectives from packaging procurement managers at major retail chains, formulation chemists at barrier coating specialists, EFSA regulatory affairs leads, and corrugated plant engineers converged on the working assumptions driving fiber-based versus flexible film substitution trajectories. Primary interview insights combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, ECHA substance registration databases, Cefic industry reports, and customs trade data for containerboard and polyethylene resin flows. Bottom-up demand modeling for ready-to-eat meal and fresh protein packaging specifications triangulated against top-down market sizing from integrated producer capacity disclosures.
Segmentation dimensions modeled span packaging type, material substrate, end-user category, and barrier technology tier across the projection horizon. Analytical framework approaches derived CAGRs through installed base attrition rates for vacuum packaging displacement by modified atmosphere systems, EU Green Deal recycled content mandate compliance timelines, and Central European food processing capacity expansion trajectories. Forecast inputs incorporated natural gas price volatility exposure for Italian and German glass container economics and post-consumer recycled resin quality variance impacts on flexible film yields.
Forecasts assume regulatory continuity in EU Green Deal implementation timelines and EFSA food-contact substance evaluation pathways; material policy shifts in Packaging and Packaging Waste Regulation fee structures or REACH substance restrictions would require re-modeling. Specific risk factors include harmonized Extended Producer Responsibility decision delays freezing long-term contract commitments and energy price spikes compressing margins in containerboard and glass production. Practitioners should keep alternative scenarios live as mono-material film transition capex cycles and smart packaging sensor cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Fresh Produce Trays Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
North America PET Food Packaging Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
Cake Box Market
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
Probiotics Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Cornstarch Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Disposable Cups Market
Food Packaging
Transparent Food Packaging Market