
 Ready Meals Packaging Market | 2026-2036
Ready Meals Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Ready Meals Packaging Market Outlook
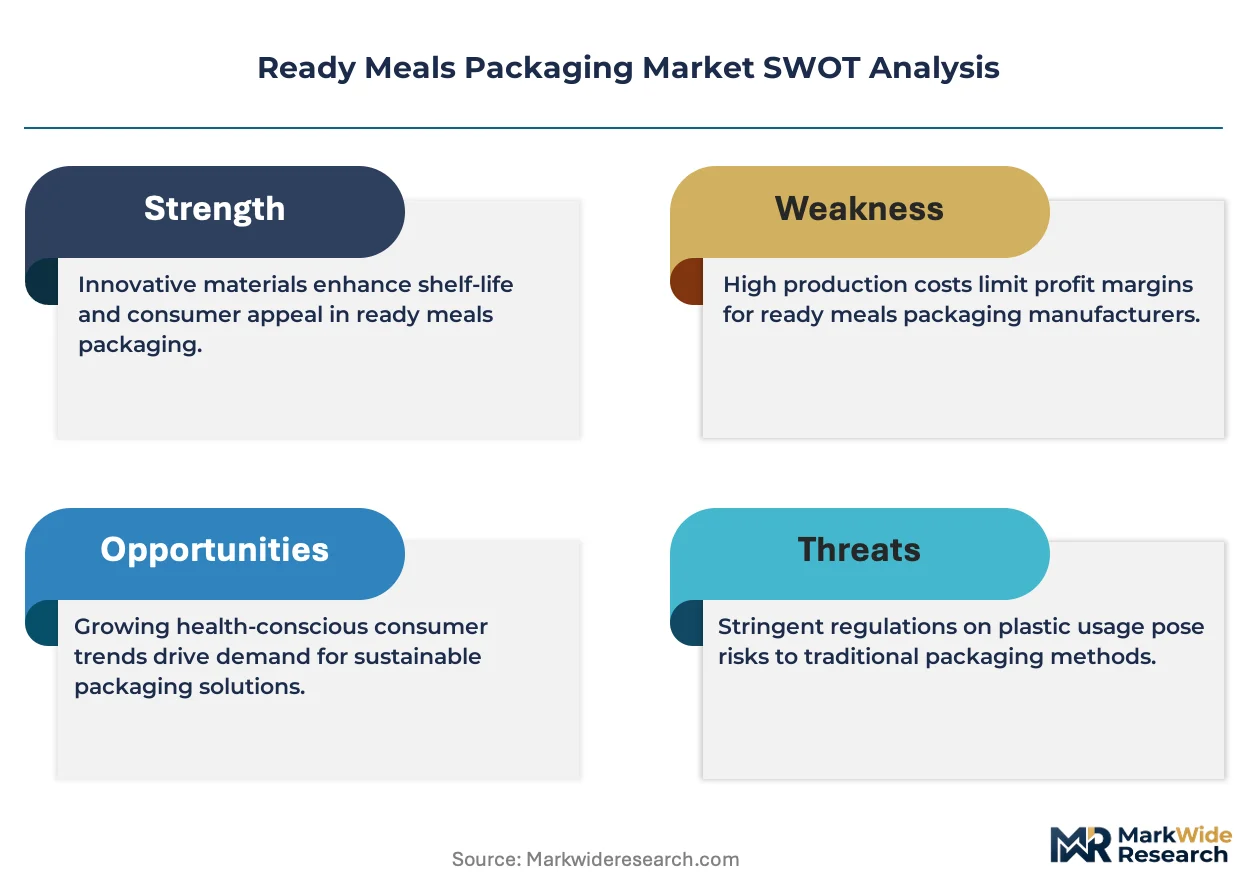
Subscription-based packaging redesign services is broadening what converters sell beyond commodity containers. Amcor Plc leverages its global film manufacturing network to sustain supply security for multinational food brands. Huhtamaki Oyj anchors European tray production through specialized molded fiber operations. Sonoco Products Company competes in rigid paperboard formats with heat-sealable barrier coatings.
Ready meals packaging encompasses thermoformed containers, flexible retort pouches, and lidded trays engineered to withstand pasteurization temperatures while preserving sensory quality. Polypropylene dominates tray applications for its microwave transparency and dimensional stability under thermal stress. Vacuum Bags command premium margins in premium chilled ready meal lines where extended shelf life justifies material cost. Microwaveable Tubs are gaining structural share as retailers demand dual-ovenable convenience formats that shift consumer preparation habits.
EU REACH restricts certain phthalates in food-contact plastics, forcing reformulation of sealant layers across European supply chains. FDA migration testing protocols govern U.S. market entry for any laminate containing recycled content. BIS certification requirements in India are tightening for imported aluminum barrier films used in retort applications. Stakeholders must decide whether to prioritize mono-material recyclability or multi-layer performance as EPR schemes expand across OECD markets.
Market Dynamics
EU REACH phthalate restrictions are forcing sealant layer reformulations across European supply chains, while EPR expansion across OECD markets demands that converters choose between mono-material recyclability and multi-layer performance integrity.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening material compliance requirements across member states are accelerating adoption of certified recyclable formats and driving investment in compliant substrate technologies.
- Online grocery platforms:E-commerce fulfillment networks are mandating tamper-evident and microwave-safe packaging specifications that legacy formats cannot satisfy, expanding addressable demand for engineered solutions.
- Polypropylene tray technology:Superior microwave transparency and dimensional stability under thermal stress are displacing alternative polymers in chilled and frozen ready meal applications.
Market Restraints
- Aluminum barrier film supply concentration:BIS certification tightening in India for imported retort-grade films is creating input bottlenecks for converters dependent on Asian metallized substrate sources.
- Multi-layer lamination technical lock-in:Current high-barrier structures cannot achieve mechanical recyclability without sacrificing oxygen and moisture protection, constraining circular economy transitions.
- FDA migration testing protocols:Extended approval timelines for recycled-content laminates are delaying U.S. market entry for sustainable format innovations developed in European R&D centers.
Strategic Opportunities
- Germany private-label expansion:Discounter ready meal portfolio growth is creating demand for customized tray formats with shorter run economics and rapid graphic changeover capabilities.
- Molded fiber tray convergence:Integration of heat-sealable barrier coatings with molded fiber structures is opening dual-ovenable applications previously reserved for plastic formats.
- Subscription-based packaging redesign services:Converters are capturing recurring revenue streams by selling structural engineering and format optimization as ongoing services rather than one-time container sales.
Industry Challenges
- Migration testing laboratory capacity:Bottlenecks at certified facilities for FDA and EFSA compliance verification are extending product launch timelines by six to twelve months for reformulated sealant layers.
- Retrofitting thermoforming lines:Capital requirements for tool modifications to handle thinner-gauge mono-material webs are straining mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready Meals Packaging Market |
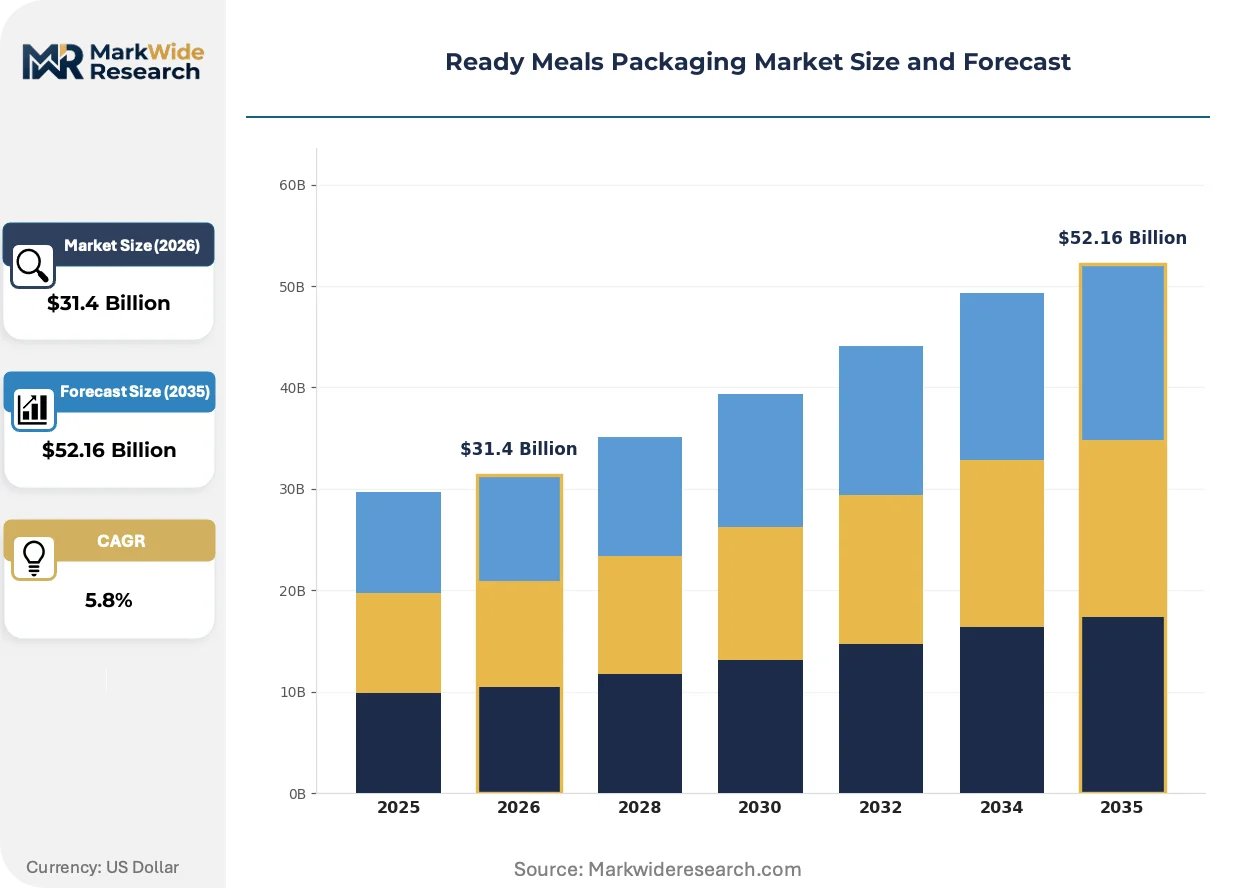
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $52.16 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Plastic Containers, Vacuum Bags, Cardboard Trays, Microwaveable Tubs Material: Polypropylene, Polyester, Aluminum, Paperboard End User: Food Service, Retail, Online Grocery, Catering Feature: Recyclable, Microwave Safe, Tamper Evident, Biodegradable |
| Companies Covered | Mondi Group, Huhtamaki Oyj, Amcor Plc, DS Smith Plc, Coveris Holdings S.A., Sealed Air Corporation, Sonoco Products Company, ProAmpac Intermediate Inc., Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready Meals Packaging Market Strategic Shifts
Automation of quality assurance and format changeover processes is compressing production economics for short-run customized packaging, while regulatory fragmentation between jurisdictions multiplies compliance architecture costs.
High-speed vision inspection systems are automating defect detection in thermoformed tray production. Major chilled ready meal manufacturers in France and the United Kingdom are deploying these systems at line speeds exceeding 400 units per minute. This automation is automating the elimination of manual sorting stations and reducing labor intensity in high-volume facilities.
REACH restrictions on phthalates in food-contact plastics are compelling sealant layer reformulations across European converter networks. Industrial consequence includes accelerated qualification of bio-based and non-phthalate adhesive systems with equivalent heat-seal performance. Flexible retort pouch producers in Germany and Italy are most affected, responding with two-year material validation programs to maintain EFSA compliance.
Retailers are consolidating ready meal procurement around dual-ovenable format specifications that shift consumer preparation habits toward microwave-primary usage. Discounter and premium supermarket channels in the United Kingdom are displacing conventional oven-only formats with tubs rated for both microwave and conventional oven exposure. This specification compression is most visible in private-label development cycles, where packaging briefs now mandate multi-modal heating compatibility as a baseline requirement.
Ready Meals Packaging Market Segmentation
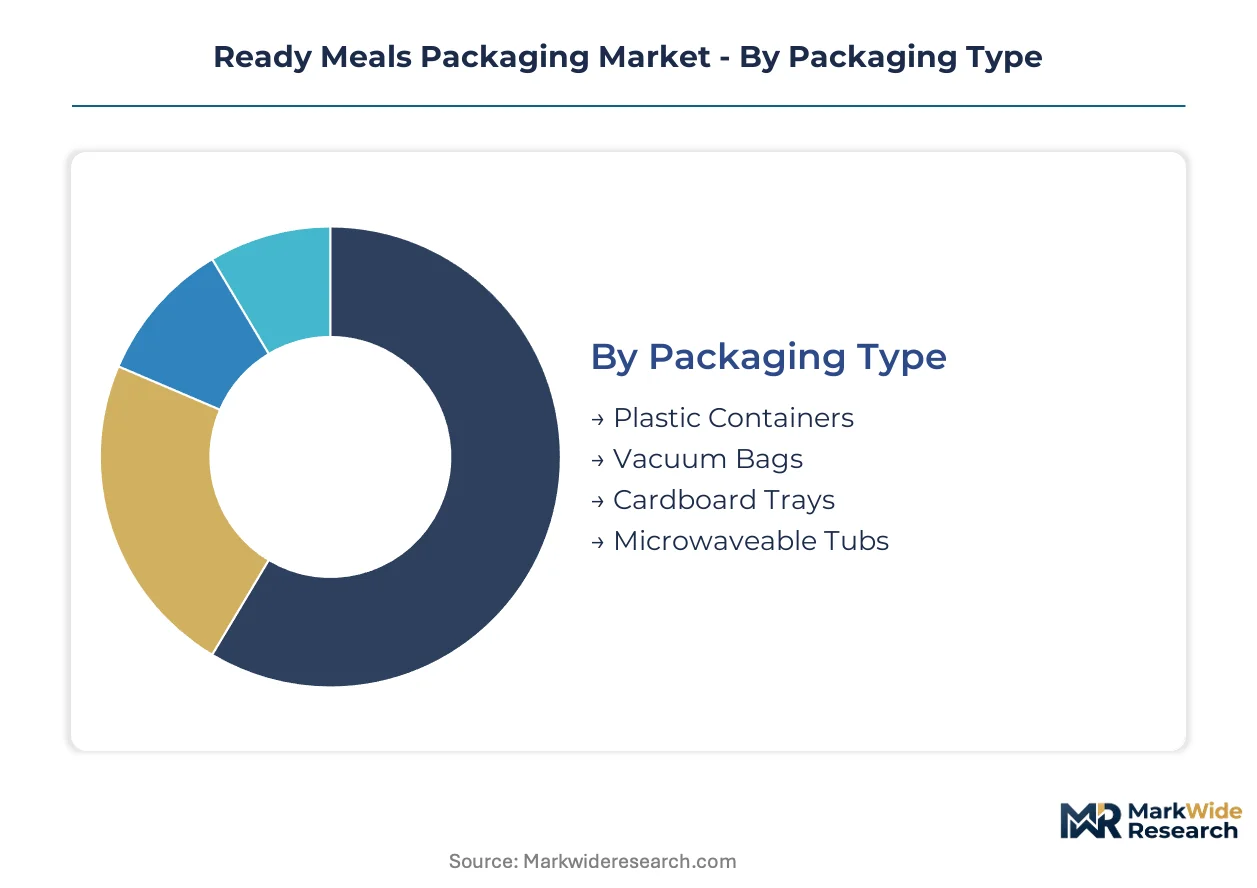
Packaging format selection in ready meals directly determines shelf-life extension, heating performance, and regulatory compliance pathways. Material and feature specifications cascade through supply chain configuration, end-use channel requirements, and circular economy obligations. Each segmentation dimension carries distinct technical lock-ins that constrain converter flexibility and customer switching costs.
Packaging Type:
Standalone formats operate independently in consumer-facing applications, while embedded systems integrate with retail display infrastructure or automated fulfillment equipment.
- Plastic Containers:Thermoformed polypropylene structures dominate chilled ready meal lines across German and French retail channels. Discounter procurement specifications in the United Kingdom now mandate mono-material recyclability for all new container introductions, forcing gauge reduction and structural redesign investments.
- Vacuum Bags:Multi-layer flexible laminates with aluminum oxide or metallized barriers achieve 45-60 day shelf life in premium chilled segments. French sous-vide meal manufacturers specify these formats for their oxygen transmission rate performance below 0.1 cc/m²/day, though EPR fee structures in the Netherlands and Belgium penalize non-recyclable constructions.
- Cardboard Trays:Paperboard-based formats with heat-sealable barrier coatings serve oven-only applications in institutional catering contracts across Italy and Spain.
- Microwaveable Tubs:Dual-ovenable specifications are displacing conventional oven-only formats in United Kingdom private-label development cycles.
Volume placements concentrate in Plastic Containers; the faster expansion belongs to Microwaveable Tubs.
Material:
Cost tier stratification separates commodity substrates from performance-engineered alternatives with specialized barrier or thermal properties.
- Polypropylene:Homopolymer and random copolymer grades provide microwave transparency and dimensional stability under thermal stress. German tray thermoformers specify high-clarity grades for refrigerated display visibility, while impact copolymers address frozen distribution durability requirements in Nordic markets.
- Polyester:PET and CPET structures enable dual-ovenable performance with crystallinity levels engineered for thermal resistance above 200°C. Italian converters favor APET/CPET laminates for their compatibility with existing thermoforming tooling and established recycling stream access.
- Aluminum:Metallized films and foil laminates deliver oxygen and moisture barriers essential for retort pouch applications. BIS certification tightening in India for imported retort-grade substrates is creating supply bottlenecks for European converters dependent on Asian metallized film sources.
- Paperboard:Solid bleached sulfate and coated unbleached kraft grades form the structural substrate for lidded tray formats in organic and premium positioning segments across Scandinavian retail channels.
Polypropylene captures the highest placement volumes; Polyester is climbing fastest on dual-ovenable specification adoption.
End User:
Channel-specific requirements diverge sharply in run length economics, graphic complexity, and distribution temperature control.
- Food Service:Institutional catering contracts in France and Germany specify standardized tray formats with minimal graphic content and bulk packaging configurations optimized for automated rethermalization equipment.
- Retail:Supermarket and discounter channels drive the majority of format innovation investment, with private-label briefs mandating rapid graphic changeover capabilities and shorter run economics. United Kingdom retailers are consolidating procurement around dual-ovenable specifications that shift consumer preparation habits.
- Online Grocery:E-commerce fulfillment networks impose tamper-evident and microwave-safe requirements that legacy formats cannot satisfy, expanding addressable demand for engineered solutions with drop-test durability specifications.
- Catering:Event and contract catering segments prioritize portion consistency and holding temperature performance over shelf-life extension, favoring rigid formats with resealable lid systems.
Retail channels dominate current placements; Online Grocery is expanding most quickly on fulfillment infrastructure buildout.
Feature:
Maturity stage separates established compliance baselines from emerging specifications still navigating standardization and certification pathways.
- Recyclable:Mono-material polypropylene and PET constructions with compatible lid systems qualify for existing mechanical recycling streams. EU Packaging and Packaging Waste Regulation implementation is accelerating certified recyclable format adoption across member states.
- Microwave Safe:Temperature resistance and dimensional stability specifications have become baseline requirements rather than differentiators in United Kingdom and German retail channels. Migration testing protocols for recycled-content laminates are extending approval timelines for sustainable format innovations.
- Tamper Evident:Peelable film lidding with visible breach indicators addresses e-commerce fulfillment security requirements. Online grocery platforms in France and the Netherlands mandate these features for ready meal categories.
- Biodegradable:PLA and PHA-based formats remain confined to premium organic positioning with limited industrial composting infrastructure access. Industrial composting certification gaps across European member states constrain volume scalability.
Recyclable specifications anchor current volumes; Tamper Evident features are gaining share fastest on e-commerce channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European converter activity, with the Rhine-Ruhr corridor hosting specialized thermoforming operations supplying discounter private-label networks across the continent.
Germany
Discounter ready meal portfolio expansion drives demand for customized tray formats with rapid graphic changeover capabilities. ECHA REACH enforcement restricts phthalates in food-contact sealant layers, compelling two-year material validation programs. The Rhine-Ruhr industrial corridor hosts specialized thermoforming operations supplying Aldi and Lidl private-label networks.
United Kingdom
Retail procurement consolidation around dual-ovenable specifications is displacing conventional oven-only formats. The UK Environment Agency implements extended producer responsibility fee structures that penalize non-recyclable multi-layer constructions. Greater Manchester hosts automated tray production facilities serving Tesco and Sainsbury's chilled meal lines.
France
Premium sous-vide meal manufacturers specify high-barrier vacuum bag formats for extended shelf-life positioning. ANSM food-contact material notifications govern bio-based adhesive system approvals. The Lyon-Grenoble corridor concentrates flexible retort pouch production for export-ready chilled meal brands.
United States
FDA migration testing protocols extend approval timelines for recycled-content laminate innovations developed in European R&D centers. EPA food packaging sustainability guidelines pressure converters toward mono-material recyclability. Chicago-area thermoformers supply national retail chains with microwave-transparent polypropylene structures.
India
BIS certification tightening for imported aluminum barrier films creates supply bottlenecks for converters dependent on Asian metallized substrate sources. FSSAI food packaging safety standards intensify scrutiny of retort-grade material imports. Mumbai-Pune industrial corridor hosts emerging tray thermoforming capacity serving domestic ready meal brands.
Ready Meals Packaging Market Competitive Environment
Capital-heavy producers compete with asset-light designers across substrate engineering and format specification tiers. The vendor base concentrates around integrated film-to-container converters with captive polymer supply, while specialist coating houses capture premium barrier technology niches. Three archetypes dominate: multinational integrated packaging groups with global film networks, regional tray specialists with molded fiber capabilities, and flexible packaging houses with retort pouch expertise. Competitive dynamics center on backward integration into polymer compounding and strategic partnerships with private-label retailers for exclusive format development.
Among European-based converters, Huhtamaki Oyj and Sonoco Products Company exemplify divergent specialization vectors. Amcor Plc represents the scale-driven multinational archetype with global manufacturing footprints. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning within substrate-specific segments.
| Leading Market Players |
|---|
| Mondi Group |
| Huhtamaki Oyj |
| Amcor Plc |
| DS Smith Plc |
| Coveris Holdings S.A. |
| Sealed Air Corporation |
| Sonoco Products Company |
| ProAmpac Intermediate Inc. |
| Berry Global Inc. |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin price indices cascading from Rotterdam and Singapore benchmarks stratify converter margins across three distinct pricing tiers. EPR fee differentials between mono-material and multi-layer formats now exceed raw material deltas in several EU member states, reshaping procurement economics for discounter private-label networks.
Pricing Analysis
Margin tightening in standard-grade polypropylene trays reflects gauge reduction mandates from United Kingdom retailers pursuing mono-material recyclability. Three-tier pricing structure across premium, standard, and economy levels separates certified compostable formats from conventional plastics from virgin-grade barrier laminates. Cost-down pressure on economy-tier converters accelerates because Aldi and Lidl procurement teams now specify sub-400-micron wall thicknesses as baseline requirements. Food service channels exhibit highest price sensitivity; premium sous-vide manufacturers in France show least sensitivity due to shelf-life performance premiums.
Supply Chain Analysis
BIS certification requirements in India are reshaping sourcing patterns for European converters dependent on Asian metallized substrate sources. Raw material supply concentrates in Germany, Italy, and China for polypropylene compounding, barrier coating chemicals, and metallized film production respectively. Converter networks draw from single-source vulnerability in aluminum oxide deposition capacity, with only three qualified suppliers serving retort-grade specifications. Distribution runs through Rhine-Ruhr corridor consolidation hubs serving discounter private-label networks across the continent.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polymer compounding and captive barrier coating capacity has become the decisive competitive race in ready meals packaging. Players securing upstream control over sealant layer formulations are capturing margin pools previously absorbed by specialty chemical suppliers.
For Market Incumbents: Cement format exclusivity with Aldi and Lidl through dedicated production lines with sub-24-hour graphic changeover capabilities. Lock in multi-year offtake agreements with Rhine-Ruhr polymer compounders before EPR scheme expansion tightens virgin resin access. The threat is emerging molded fiber specialists with heat-sealable barrier patents displacing plastic trays in premium organic segments. For New Entrants and Emerging Players: EU Packaging and Packaging Waste Regulation implementation opens a window for certified recyclable mono-material specialists to capture share from legacy multi-layer converters. Target United Kingdom online grocery fulfillment networks with tamper-evident lidding systems that legacy thermoformers cannot engineer. The penetrable segment is private-label discounter supply where rapid format iteration outranks scale economies. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier thermoformers with underutilized tool libraries in Greater Manchester and Lyon-Grenoble corridors. The long-term viability window favors converters with demonstrated EFSA compliance pathways for bio-based adhesive systems. Watch for BIS certification resolution in India as the inflection signal for aluminum barrier film supply normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply secures margin pools and EPR compliance flexibility for converters serving discounter networks. |
| Heat-Sealable Barrier Coating Development | Molded fiber tray convergence with plastic-grade performance opens dual-ovenable applications previously inaccessible to paperboard formats. |
| Subscription-Based Packaging Redesign Services | Recurring revenue streams from structural engineering contracts reduce dependence on commodity container price cycles. |
| Thermoforming Line Automation Investment | High-speed vision inspection deployment at 400+ units per minute compresses labor intensity for short-run customized production. |
| EFSA-Compliant Bio-Based Adhesive Qualification | Two-year validation programs for phthalate-free sealant layers preempt REACH enforcement displacement of incumbent formulations. |
Study Parameters
Document review covered EU Packaging and Packaging Waste Regulation implementation guidance, EFSA food-contact material notifications, and BIS certification protocols for aluminum barrier films, complemented by interviews with thermoforming operations managers, private-label category buyers at German discounters, flexible packaging R&D directors, and polymer procurement leads. Secondary validation drew from customs trade data, ECHA REACH substance restriction updates, and SEC filings of listed packaging converters. Bottom-up capacity assessments across Rhine-Ruhr and Lyon-Grenoble production clusters were triangulated against top-down demand modeling from retail channel procurement data.
Segmented volume and value estimates across the projection horizon reflect packaging format, material substrate, end-user channel, and feature specification dimensions. The analytical framework modeled polypropylene tray adoption against polyester dual-ovenable displacement, online grocery channel expansion rates, and EPR fee structure implementation timelines. CAGRs were derived from regression analysis of historical format penetration curves adjusted for regulatory acceleration effects and substitution elasticity between plastic and fiber-based alternatives.
The model assumes gradual molded fiber barrier coating maturation; alternative pathways involving accelerated crystallinity breakthroughs in bio-based polymers would alter the substrate mix outlook. Forecasts reflect assumptions about BIS certification resolution timelines, EPR scheme harmonization across EU member states, and sustained discounter private-label expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Desserts Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
Seafood Packaging Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
Egg Packaging Market
Food Packaging
Pie Packaging Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Global Disposable Plates Market
Food Packaging
Food Punnets Market
Food Packaging
Food and Drink Packaging Market