
 Disposable Cups Market | 2026-2036
Disposable Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Cups Market Intelligence
The rise of online distribution channels for food service supplies is reshaping how independent cafes and small restaurant chains procure products. Huhtamäki Oyj leverages its extensive global manufacturing footprint and diverse material portfolio to serve large multinational clients. In contrast, Dart Container Corporation sustains a dominant position in specific material segments like foam within the North American market. Berry Global Group Inc. differentiates through its significant R&D investment in sustainable plastic packaging solutions.
Disposable cups are single-use vessels specifically engineered for holding hot or cold beverages for a limited duration. They are typically manufactured from materials like polyethylene-coated paperboard, polypropylene (PP), or bio-based polylactic acid (PLA) to ensure liquid containment and thermal insulation. Paper cups command the largest market share, a position reinforced by regulatory pressures against single-use plastic alternatives. While cafes and restaurants constitute the primary end-user segment, biodegradable options represent the fastest-growing product category across all applications.
Regulations like the EU's Single-Use Plastics Directive and China's national GB standards for food contact materials directly dictate allowable material compositions and product labeling. In the United States, the FDA sets stringent safety standards for all polymers, adhesives, and coatings used in cup manufacturing. Future profitability for manufacturers depends on their ability to navigate the complex trade-offs between material performance, unit cost, and evolving environmental compliance mandates.
Market Dynamics
The disposable cups market is defined by a fundamental conflict between convenience-driven consumption, particularly in the quick-service restaurant sector, and intensifying environmental regulations. Policies like the EU's Single-Use Plastics Directive are forcing material innovation away from legacy plastics toward sustainable alternatives.
Growth Catalysts
- QSR and Cafe Expansion:The continued global proliferation of quick-service restaurants and coffee shop chains provides a consistent and large-volume demand base for both hot and cold disposable cups, particularly in urban and suburban areas.
- Convenience-Oriented Lifestyles:Rapid urbanization and busier consumer schedules, especially in developing economies such as India and Brazil, are fueling demand for on-the-go food and beverage products that rely on single-use packaging.
- Regulatory Push for Bio-Plastics:Government mandates and corporate sustainability goals are actively promoting the adoption of biodegradable materials like polylactic acid (PLA), creating a fast-growing segment for compostable cups and lids.
Market Restraints
- Raw Material Price Volatility:Manufacturers face significant margin pressure from fluctuating costs of key inputs, including paperboard pulp, polyethylene (PE) resins, and bio-based polymers like PLA, which are tied to volatile commodity markets.
- Substitution from Reusables:The increasing consumer and corporate adoption of reusable cup programs, heavily promoted by major coffee chains as part of their sustainability initiatives, presents a direct substitution threat that can erode single-use volume.
- Fragmented Regulatory Landscape:A patchwork of differing national and municipal regulations on single-use items, such as varying bans on foam or specific plastics, creates significant compliance complexity and operational inefficiencies for manufacturers.
Strategic Opportunities
- Advanced Barrier Coatings:There is a significant opportunity in developing and commercializing next-generation, water-based barrier coatings that enable paper cups to be fully repulpable and recyclable within existing paper waste streams.
- Expansion into Institutional Channels:Untapped growth exists in supplying specialized disposable cups to institutional end-users like hospitals, schools, and corporate cafeterias, where hygiene, portion control, and convenience are critical purchasing factors.
- Direct-to-SME E-commerce:Building out B2B e-commerce platforms allows manufacturers to bypass traditional distribution tiers and sell directly to the fragmented market of independent cafes, bakeries, and small restaurants.
Industry Challenges
- Inadequate Disposal Infrastructure:The limited availability of commercial composting facilities capable of processing PLA and other bioplastics means that many "eco-friendly" cups end up in landfills, undermining their environmental value proposition.
- Capital-Intensive Material Transition:Re-tooling manufacturing lines to handle new materials, such as moving from PE-coated paper to PLA or other biopolymers, requires substantial capital investment and can disrupt production during the changeover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Cups Market |
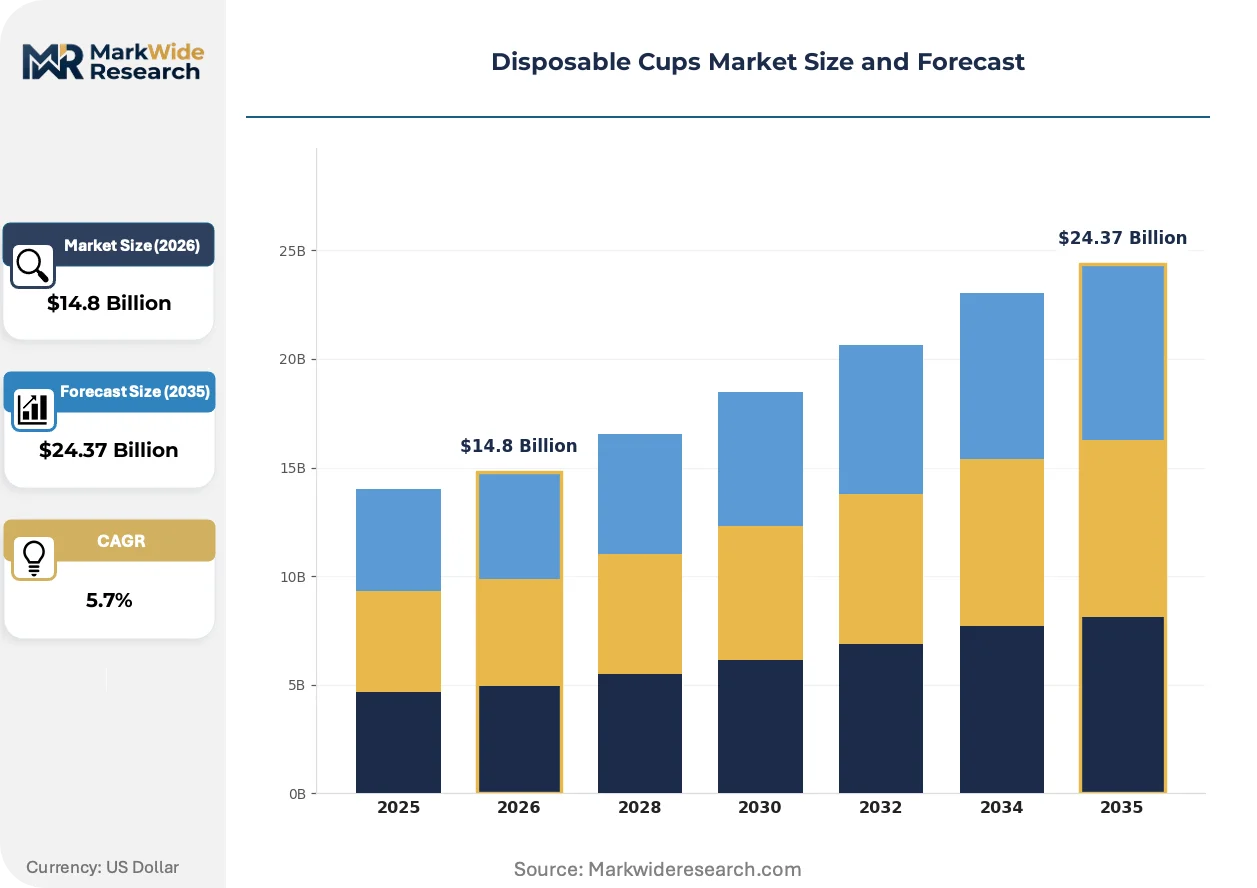
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper, Plastic, Foam, Biodegradable Size: Small, Medium, Large, Extra Large End User: Cafes, Restaurants, Events, Households Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Huhtamäki Oyj, Dart Container Corporation, Berry Global Group Inc., Pactiv Evergreen Inc., WestRock Company, Genpak LLC, Duni AB, Georgia-Pacific LLC, Greiner Packaging International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Cups Market Strategic Shifts & Innovations
Material science innovation and regulatory mandates are fundamentally altering the disposable cup's lifecycle. The industry is moving from a linear, single-use model toward solutions that integrate better with circular economy principles, driven by both compliance requirements and shifting consumer expectations.
Advanced barrier technologies, particularly aqueous or dispersion coatings, provide liquid resistance without using polyethylene liners. Paper cup converters are adopting these solutions to create products that are fully repulpable in standard recycling facilities. This development is hybridizing the product, combining the functional performance of a lined cup with the environmental credentials of a recyclable paper-based item.
The European Union's Single-Use Plastics Directive imposes strict market restrictions and extended producer responsibility (EPR) schemes on certain disposable products. This regulation forces manufacturers to accelerate innovation away from conventional plastic-lined and foam cups to avoid penalties and maintain market access. The paper cup segment is most impacted, responding with heavy investment in alternative materials and fiber-based designs compliant with EU rules.
Online B2B marketplaces for foodservice supplies are enabling direct procurement by independent cafes and small restaurant chains. This model disrupts the traditional hold of large-scale distributors, offering smaller operators greater price transparency and more flexible order volumes. This shift is most visible in the dense, fragmented urban markets of North America and Western Europe, where independent businesses are numerous.
Disposable Cups Market Segmentation
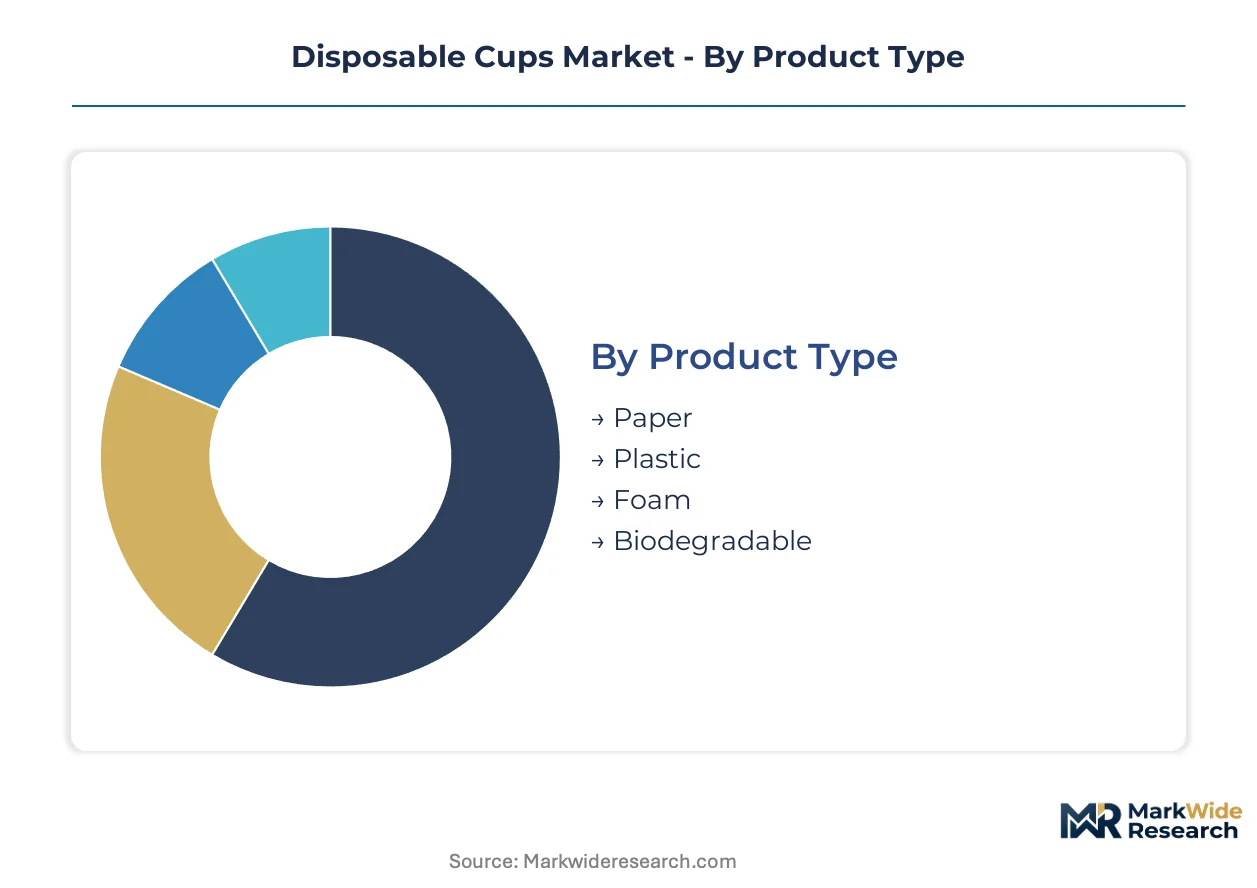
The disposable cups market exhibits varied segmentation, reflecting diverse material science, end-user applications, and procurement strategies. Understanding these segments is critical for manufacturers to align product development with evolving regulatory demands and consumer preferences. Each category reveals distinct consumption patterns and operational requirements.
Product Type:
Segments within product type exhibit varied consumption cycle times, from rapid daily turnover in paper to longer-term use cases for certain plastics.
- Paper:These cups are typically manufactured from polyethylene-coated paperboard, engineered to ensure liquid containment and thermal insulation. Demand is concentrating in cafes and restaurants, particularly in urban centers of India, driven by regulatory pressures against single-use plastic alternatives.
- Biodegradable:Composed of bio-based polylactic acid (PLA) or other compostable materials, these options offer an environmentally friendlier alternative. This category represents the fastest-growing product segment, propelled by government mandates like the EU's Single-Use Plastics Directive and corporate sustainability goals.
- Plastic:Made from polypropylene (PP) or other polymers, these cups offer durability and versatility for both hot and cold beverages. Dart Container Corporation sustains a dominant position in specific material segments like foam within the North American market.
- Foam:Typically constructed from polystyrene, foam cups provide superior thermal insulation at a lower cost point. This product type faces significant regulatory restrictions and bans in numerous regions globally due to environmental concerns.
Paper cups dominate the installed base. Biodegradable options are where expansion concentrates.
Size:
Cup sizes cater to a diverse range of beverage volumes and end-user preferences across various food service settings.
- Medium:Representing the standard 12-16 oz capacity, these cups are versatile for a wide array of hot and cold beverages. Quick-service restaurants and coffee shops drive significant demand for this size, supporting daily convenience consumption.
- Large:Typically ranging from 16-24 oz, these cups accommodate higher volume drinks and are often part of combo meal offerings. Fast-food chains and entertainment venues frequently utilize large cups for extended consumption periods.
- Small:Designed for espresso shots, sample portions, or children's beverages, these cups fulfill specific niche requirements. Cafes and tasting events are primary users of smaller cup formats.
- Extra Large:These oversized cups are used for promotional beverages or specialized high-volume drink options. Their use is less frequent but caters to specific marketing and consumer value propositions.
Medium and Large sizes drive significant volume. Extra Large and Small sizes serve specialized beverage requirements.
End User:
End-user segments vary significantly in their procurement volumes and frequency of disposable cup usage.
- Cafes:This segment requires cups with strong thermal properties for hot beverages and often prioritizes aesthetic appeal and branding opportunities. High daily turnover in urban centers fuels consistent demand for cafe-specific disposable cups.
- Restaurants:Catering to both hot and cold beverages, restaurants demand a diverse range of cup types, frequently bundled with meals for takeaway. The continued global proliferation of quick-service restaurants provides a consistent and large-volume demand base.
- Events:Large-scale gatherings, concerts, and sports venues generate temporary but substantial demand for disposable cups. Hygiene and rapid service are critical purchasing factors for event organizers.
- Households:Consumers purchase disposable cups for personal convenience, parties, or picnics, representing lower volume but broad market penetration. Supermarkets and convenience stores serve this segment.
Cafes and Restaurants form the foundational consumption base. Events and Households represent more episodic or lower-volume demand.
Distribution Channel:
Distribution channels dictate market reach and procurement efficiency for various customer types.
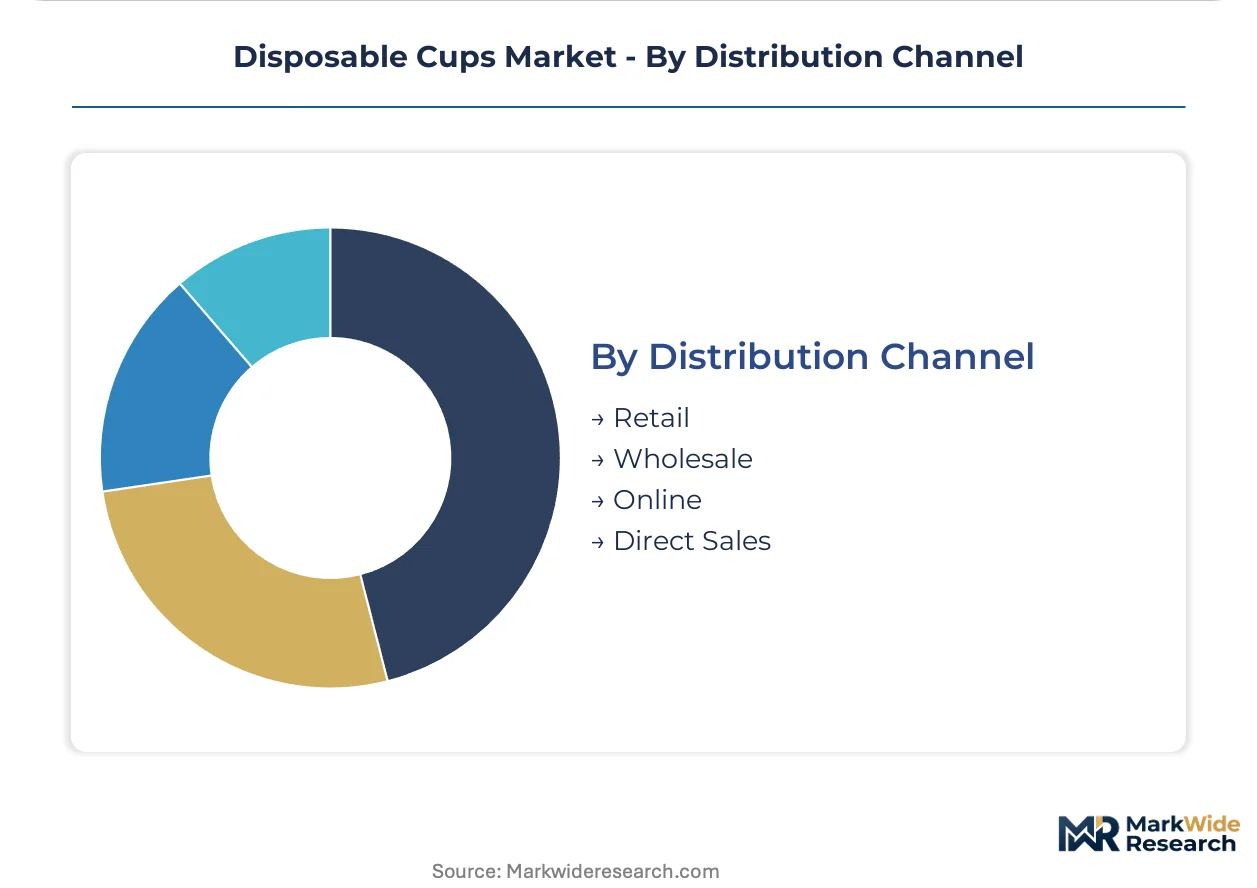
- Wholesale:This channel involves bulk purchasing and inventory management, serving large quick-service restaurant chains and institutional buyers. Traditional distributors maintain significant market share by supplying established food service operations.
- Online:B2B e-commerce platforms enable direct procurement for independent cafes and small restaurant chains, offering greater price transparency. This model disrupts traditional distribution tiers, particularly in dense urban markets of North America and Western Europe.
- Retail:Supermarkets, hypermarkets, and convenience stores sell disposable cups directly to individual consumers and small businesses. This channel caters primarily to household consumption and smaller, ad-hoc commercial needs.
- Direct Sales:Manufacturers engage in direct sales to very large multinational clients, often involving customized solutions and specialized logistical arrangements. Huhtamäki Oyj leverages its extensive global manufacturing footprint for such clients.
Wholesale channels move the largest volumes. Online platforms and Direct Sales are reshaping procurement for specific customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government mandates and corporate sustainability goals are actively promoting the adoption of biodegradable materials, shaping regional market dynamics for disposable cups. These policies influence material innovation and procurement strategies across diverse geographies. Regional consumption patterns reflect a blend of convenience-driven lifestyles and evolving environmental consciousness among consumers.
India
Rapid urbanization and busier consumer schedules are fueling demand for on-the-go food and beverage products. The Food Safety and Standards Authority of India (FSSAI) sets standards for food contact materials, influencing local manufacturing. Demand is concentrating in the urban centers of Mumbai and Delhi, where convenience-oriented consumer habits are forming.
Germany
The EU's Single-Use Plastics Directive significantly impacts material innovation, pushing development of biodegradable options. German manufacturers are investing in advanced barrier coatings to create fully repulpable paper cups. Production hubs in North Rhine-Westphalia and Bavaria are focusing on compliant fiber-based designs.
United States
The continued proliferation of quick-service restaurants and coffee shop chains provides a consistent demand base for disposable cups. The U.S. Food and Drug Administration (FDA) sets stringent safety standards for all polymers and coatings in cup manufacturing. Regional bans on foam products in cities like Seattle and San Francisco drive demand for alternative materials.
China
National GB standards for food contact materials directly dictate allowable material compositions and product labeling. Convenience-oriented lifestyles in major cities like Shanghai and Beijing contribute to high consumption volumes. Local manufacturers are adapting to stricter environmental regulations and promoting bio-based alternatives.
Brazil
Developing economies in Latin America, including Brazil, show a growing demand for on-the-go food and beverage products. The Brazilian National Health Surveillance Agency (ANVISA) regulates food packaging materials to ensure consumer safety. Metropolitan areas such as São Paulo and Rio de Janeiro exhibit high daily turnover in cafes and restaurants.
Disposable Cups Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing large multinational corporations and specialized regional players. Large manufacturers leverage extensive global footprints and diverse material portfolios. Key strategic archetypes include global diversified packaging giants, specialized sustainable solution providers, and regional material-specific leaders. Capacity expansion in bio-based materials and strategic partnerships with quick-service restaurant chains represent dominant competitive moves.
Global diversified packaging giants, such as Huhtamäki Oyj, exemplify companies with broad geographical reach and comprehensive product offerings. Dart Container Corporation occupies a position as a specialized material leader, sustaining a dominant presence in specific segments like foam within the North American market. Berry Global Group Inc. anchors the sustainable solutions archetype through its significant research and development investment in advanced plastic packaging technologies.
| Leading Market Players |
|---|
| Huhtamäki Oyj |
| Dart Container Corporation |
| Berry Global Group Inc. |
| Pactiv Evergreen Inc. |
| WestRock Company |
| Genpak LLC |
| Duni AB |
| Georgia-Pacific LLC |
| Greiner Packaging International GmbH |
| Others |
Cost & Logistics Intelligence
Under-capacity in specialized bio-plastic manufacturing drives both supplier behavior and pricing posture, particularly for sustainable disposable cup options. This dynamic influences material availability and cost structures across the value chain.
Pricing Analysis
Volume-discount tiering structures characterize disposable cup pricing, favoring large quick-service restaurant chains and institutional buyers. Price differentiation stems from material composition, such as PLA versus PE-coated paper, and certifications like compostability standards. Pricing pressure stems from fluctuating raw material costs, including paper pulp and bio-polymers, which are tied to volatile commodity markets. Independent cafes and small restaurants exhibit the highest price sensitivity, while large multinational clients prioritize consistent supply and customized solutions.
Supply Chain Analysis
Contract manufacturing capacity for disposable cups concentrates in China, India, and parts of Southeast Asia, leveraging lower labor costs and established infrastructure. The supply chain relies on key inputs like paperboard pulp, polyethylene resins, and polylactic acid granules. Commodity price volatility represents a significant structural risk, directly impacting manufacturing margins. Distribution runs through a hybrid model, combining large-scale wholesale for major clients with direct-to-SME e-commerce platforms for smaller operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable cups market is experiencing a buyer-power shift, driven by the consolidation of purchasing among large quick-service restaurant chains seeking sustainable and cost-effective solutions.
For Market Incumbents:
Build a technological moat through continuous investment in advanced barrier coatings that enable full repulpability. This innovation counters the threat of reusable cup programs and strengthens compliance with evolving EU regulations. Leverage global manufacturing footprints to optimize material sourcing and mitigate raw material price volatility, ensuring stable supply for multinational clients.
For New Entrants and Emerging Players:
Establish a beachhead in the biodegradable product segment, focusing on compostable PLA cups and lids. The most penetrable segment is independent cafes and small restaurants in urban centers, particularly in India, where convenience-oriented habits are forming. A direct-to-SME e-commerce angle offers a cost-effective go-to-market strategy, bypassing traditional distribution tiers.
For Investors and Strategic Acquirers:
Recurring-revenue conversion is highest among manufacturers with proprietary sustainable material technologies or strong long-term contracts with major quick-service restaurant chains. The long-term viability of this market hinges on the ability to navigate complex regulatory landscapes and material transitions. Target acquisition archetypes include specialized biopolymer producers or paper cup converters with patented barrier solutions. The signal to watch is the adoption rate of fully recyclable paper cups by major coffee chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Aqueous Barrier Coatings | This enhances product recyclability, aligning with circular economy principles and regulatory mandates. |
| Expand Bio-Plastic Production Capacity | This addresses the growing demand for compostable options, particularly in environmentally conscious markets. |
| Develop B2B E-commerce Platforms | This allows direct access to independent cafes and small restaurants, expanding market reach. |
| Form Strategic Partnerships with QSRs | This secures large-volume, long-term contracts and provides stability in demand. |
| Optimize Global Supply Chain Logistics | This mitigates raw material price volatility and ensures consistent product delivery across regions. |
Research Approach
Initial hypotheses were tested against primary input from procurement managers, R&D directors, sustainability officers, and distribution channel partners, and refined through iterative feedback. Secondary validation drew from FDA safety standards, EU Single-Use Plastics Directive documentation, FSSAI regulations, and national GB standards for food contact materials. The analysis employed bottom-up and top-down triangulation to ensure comprehensive market sizing.
Demand-supply-balance framing informed the analytical framework across the analysis window, integrating market drivers and restraints. Segmentation dimensions modeled included product type, size, end-user, and distribution channel, along with regional regulatory compliance requirements. Compound annual growth rates were derived from historical data trends and projected future adoption patterns, with quick-service restaurant expansion serving as a key forecast input.
Stress conditions across raw material price volatility and regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding material science advancements and consumer preference shifts. Quarterly review of regulatory changes and key commodity prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Sugar Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Produce Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Cupcake Containers Market
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Fast Food Containers Market