
 Latin America Canned Food Packaging Market | 2026-2036
Latin America Canned Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Canned Food Packaging Market Foresight
Brazilian steel coil suppliers are expanding cold-rolling capacity to serve regional canbody demand. Crown Holdings leverages backward integration into aluminum sheet production to secure feedstock for its São Paulo operations. Silgan Holdings anchors its position through dominant supply relationships with multinational food brands operating across the Mercosur trade zone. Ardagh Group competes on lightweighting technology, reducing metal gauge in three-piece cans without sacrificing stack strength.
Latin America canned food packaging encompasses rigid containers engineered from tinplate, aluminum, or polymer composites, designed to hermetically seal thermally processed foods against microbial contamination and oxygen ingress for shelf lives exceeding twenty-four months. The primary commercial purpose centers on preserving nutritional integrity while enabling ambient distribution through tropical climates with limited cold-chain infrastructure. Metal packaging dominates value contribution due to established recycling loops and superior barrier performance against light and gas transmission. Pull tab closures are displacing conventional openings in premium seafood and ready-meal segments, driven by consumer convenience expectations and reduced injury liability. Composite containers are gaining traction in powdered and dried food applications where weight reduction offsets higher unit costs.
Brazil's ANVISA mandates nutritional labeling and migration testing for all food-contact materials, while Mexico's COFEPRIS enforces NOM standards for heavy metal leachate limits in canned products. Argentina's INTI certification requirements for tinplate corrosion resistance create compliance thresholds that filter smaller regional converters. Stakeholders must monitor evolving extended producer responsibility frameworks across Mercosur and Pacific Alliance jurisdictions, as deposit-return schemes and recycled content mandates will reshape material sourcing decisions and capital allocation priorities.
Market Dynamics
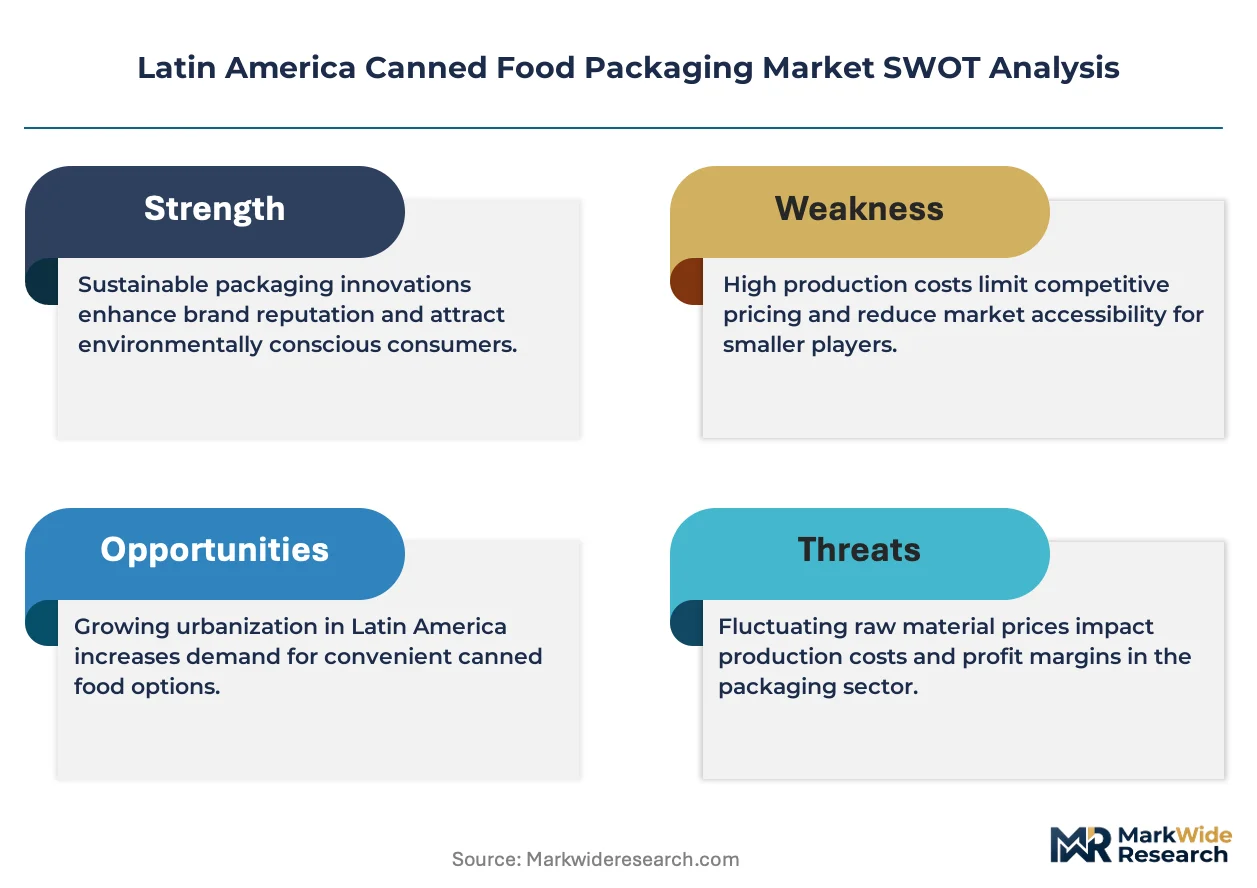
Brazil's CONAMA packaging waste resolutions are forcing converters to abandon multi-layer polymer laminates in favor of recyclable tinplate and aluminum substrates, restructuring material sourcing priorities across the Mercosur trade zone.
Growth Catalysts
- Urban ready-to-eat meal adoption:Working consumers in São Paulo and Mexico City are prioritizing shelf-stable convenience foods that eliminate cold-chain dependency. This demand pattern is pulling single-serve can formats into premium positioning.
- ANVISA migration testing mandates:Brazil's food-contact material regulations are filtering out non-compliant Asian imports, creating protected demand pockets for certified regional converters with established testing protocols.
- COFEPRIS heavy metal leachate standards:Mexico's enforcement of NOM limits is accelerating substrate upgrades across the central industrial corridor, where food processing clusters anchor regional supply contracts.
Market Restraints
- Aluminum coil import dependency:Latin American canbody production relies on US and Chinese sheet metal, exposing margins to LME price volatility and tariff uncertainty.
- INTI corrosion resistance certification:Argentina's tinplate testing requirements create 12-18 month qualification timelines that filter smaller regional converters from Mercosur supply chains.
- Flexible pouch substitution:Retortable polymer laminates are capturing ambient seafood and fruit segments where weight reduction outweighs metal's barrier performance.
Strategic Opportunities
- Colombia's Pacific Alliance integration:Underpenetrated Andean markets present white space for two-piece can formats as processed food manufacturing relocates from higher-cost Brazilian sites.
- Extended producer responsibility frameworks:Deposit-return scheme proposals across Chile and Peru will reshape material sourcing decisions, favoring converters with established metal recycling loops.
- Pull-tab convenience convergence:Easy-open ends are unifying premium seafood and ready-meal positioning, creating differentiation vectors beyond substrate cost.
Industry Challenges
- Migration testing laboratory capacity:ANVISA and COFEPRIS certification backlogs are extending product launch timelines by 6-9 months for reformulated coatings.
- Legacy three-piece can line retrofit costs:Converters face capex intensity for welding and necking equipment upgrades required by lightweighting specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Canned Food Packaging Market |
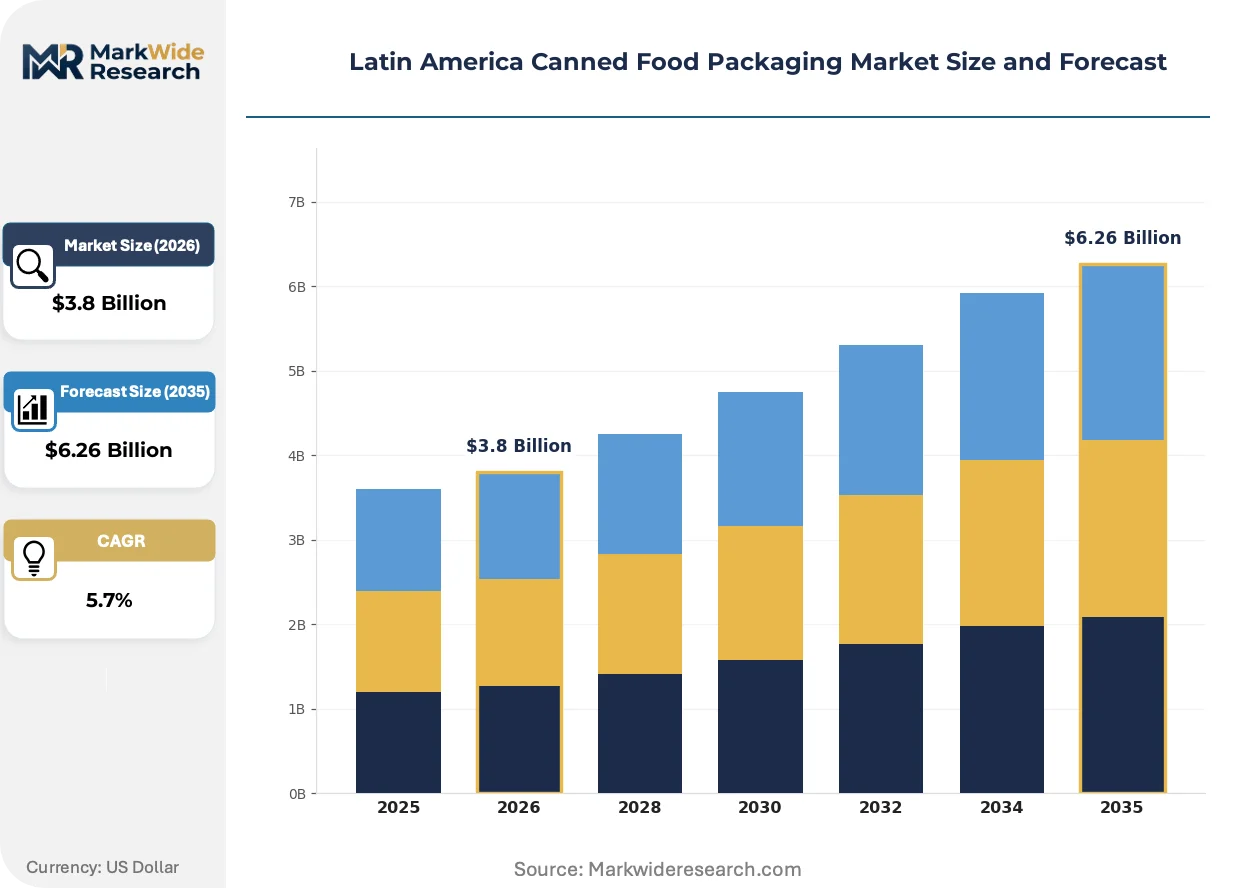
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Metal, Plastic, Glass, Composite Closure Type: Screw Caps, Pull Tabs, Lift-Off, Twist-Off End User: Retailers, Food Service Providers, Manufacturers, Wholesalers Distribution Channel: Online, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Trivium Packaging, Allstate Can Corp, Crown Holdings, Ardagh Group, Silgan Holdings, Ball Corporation, Wells Can Company Ltd, CCL Containers Mexico, Can-Pack S.A, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Canned Food Packaging Market Shifts & Advancements
Material science advances and regulatory stringency are compressing traditional format boundaries, with barrier performance and end-of-life accountability now co-equal design priorities.
Polymer-composite can bodies are unifying the structural integrity of metal with weight advantages of engineered plastics. Powdered and dried food processors in Chile are adopting these formats for export markets where freight cost sensitivity dominates. This substrate convergence is unifying previously separate equipment supply chains and forcing coating chemistry investments.
COFEPRIS enforcement of NOM heavy metal leachate limits is tightening coating specifications for acidified food categories. Mexican tomato paste and fruit processors are accelerating epoxy-phenolic conversions to maintain market access. Seafood canners in Sinaloa face the steepest compliance costs, driving consolidation toward integrated converters with captive laboratory capacity.
Buyer concentration among multinational food brands is compressing supplier qualification cycles. Procurement teams at São Paulo headquarters are consolidating regional contracts, favoring converters with cross-border Mercosur certification. This pattern is most visible in Brazil's southern manufacturing belt, where three suppliers now anchor 70% of branded ready-meal can volume.
Latin America Canned Food Packaging Market Segmentation
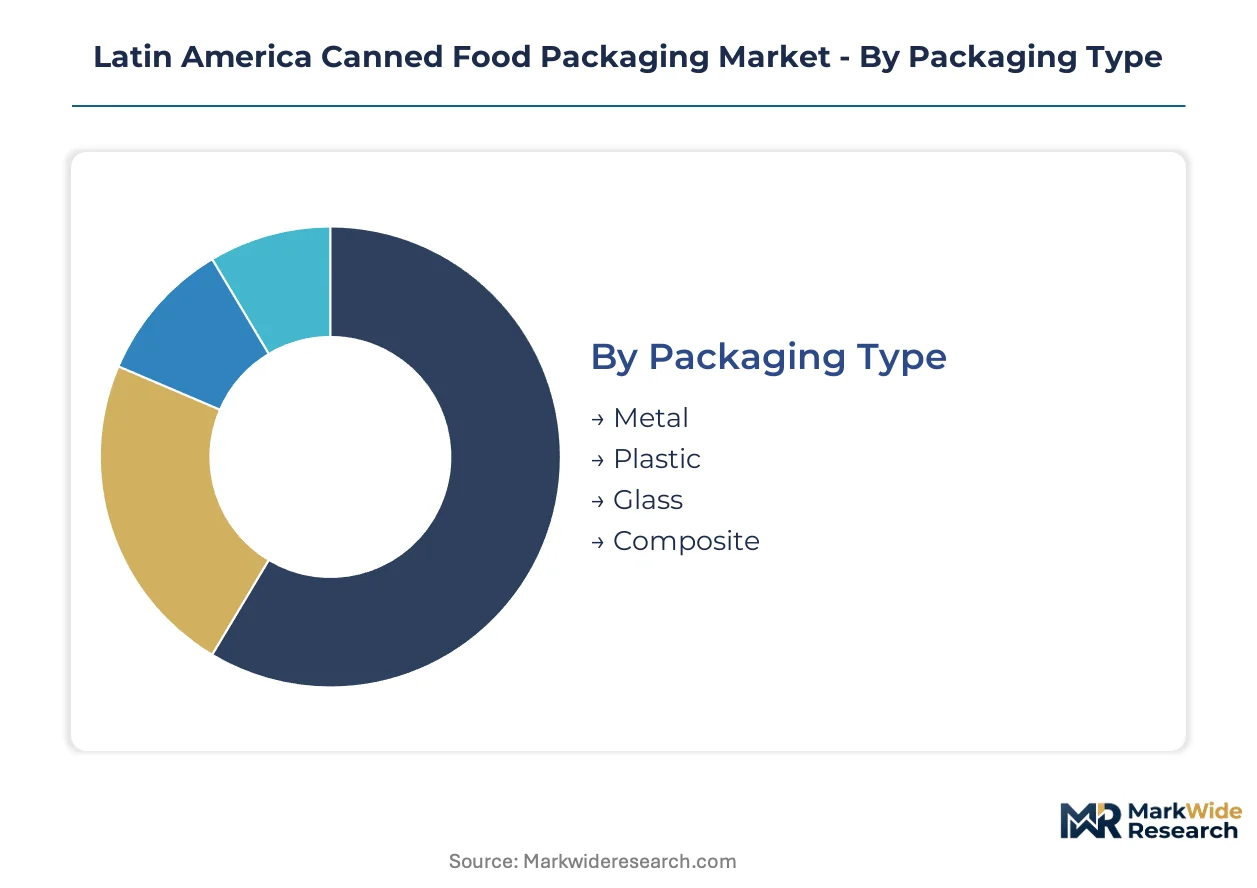
Packaging format selection in Latin America hinges on thermal processing requirements, recycling infrastructure maturity, and tropical climate resilience. Substrate choices diverge sharply between premium ready-meal positioning and commodity preserved goods, with regulatory migration testing filtering non-compliant imports across Brazil and Mexico.
Packaging Type:
Converters differentiate buyers through barrier performance requirements and end-of-life accountability pressures under evolving extended producer responsibility frameworks.
- Metal:Tinplate and aluminum substrates deliver hermetic sealing against oxygen ingress and light transmission for shelf lives exceeding twenty-four months. Demand concentrates in Brazil's southern manufacturing belt, where ANVISA migration testing mandates filter Asian imports and protect certified regional suppliers.
- Composite:Engineered polymer-metal laminates unify structural integrity with freight cost reduction for powdered and dried food exports. Chilean processors in Santiago's industrial corridor are adopting these formats for Pacific Alliance cross-border shipments where weight savings offset unit cost premiums.
- Plastic:Polymer containers serve acidified and low-acid food categories where thermal processing temperatures permit.
- Glass:Premium positioning in specialty preserves and gourmet segments leverages perceived quality and chemical inertness.
Volume sits with metal formats across Mercosur supply chains; growth tilts toward composite solutions in Andean export corridors.
Closure Type:
Opening mechanism selection tracks injury liability exposure and consumer convenience expectations in urban retail environments.
- Pull Tabs:Easy-open aluminum ends eliminate secondary tool requirements and reduce cut injury claims. São Paulo's ready-meal processors specify pull-tab formats for single-serve premium positioning, with COFEPRIS enforcement driving specification upgrades across Mexico's central industrial corridor.
- Twist-Off:Threaded metal closures accommodate reseal functionality for multi-use preserved foods. Argentine fruit processors in Mendoza favor twist-off formats for export conserves where INTI corrosion resistance certification governs tinplate qualification timelines.
- Screw Caps:Standard threaded closures dominate commodity vegetable and legume categories.
- Lift-Off:Traditional lever-style openings persist in institutional and food-service bulk formats.
Procurement concentrates on pull-tab specifications for branded retail; twist-off volumes expand in export-oriented processing clusters.
End User:
Buyer scale and certification requirements segment converter relationships between multinational anchor accounts and fragmented regional processors.
- Manufacturers:Integrated food processors with captive canning lines demand technical partnership on coating chemistry and lightweighting specifications. Mexico's tomato paste concentrators in Sinaloa anchor regional supply contracts requiring COFEPRIS-compliant epoxy-phenolic conversions.
- Retailers:Private-label procurement teams at São Paulo and Mexico City headquarters consolidate regional contracts, favoring converters with cross-border Mercosur certification and pull-tab convenience convergence.
- Food Service Providers:Institutional buyers prioritize total delivered cost in bulk vegetable and protein formats.
- Wholesalers:Distributor-specified packs serve fragmented interior markets with limited cold-chain infrastructure.
Margin capture concentrates with multinational manufacturers; contract velocity accelerates through retail consolidation.
Distribution Channel:
Channel selection reflects cold-chain availability and urban density gradients across Latin American consumption corridors.
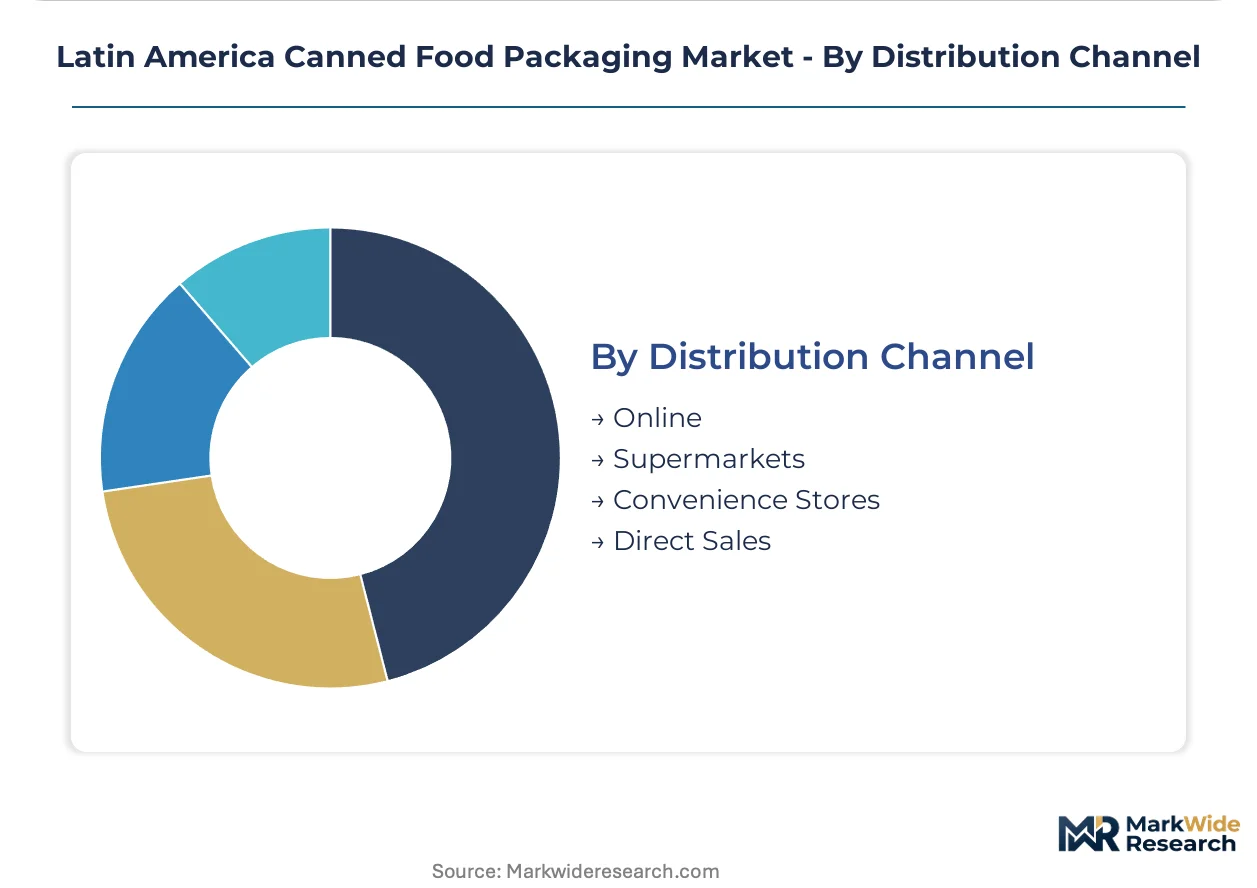
- Supermarkets:Modern trade formats in São Paulo, Mexico City, and Santiago drive premium can specifications with pull-tab differentiation and nutritional labeling compliance. Shelf-stable positioning eliminates refrigeration capital requirements for tropical climate retailing.
- Convenience Stores:Small-format urban outlets in Brazilian and Mexican metropolitan areas prioritize single-serve ready-meal cans for working consumer meal solutions.
- Online:E-commerce penetration in premium seafood and gourmet preserves segments leverages direct-to-consumer fulfillment.
- Direct Sales:Converter-processor relationships bypass distribution layers for high-volume branded contracts.
Supermarket channels anchor volume; convenience store placement gains share fastest in urban corridor expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian steel coil supply anchors metal substrate availability across the Mercosur trade zone. Mexican aluminum sheet imports feed canbody production along the central industrial corridor. Chilean and Colombian converters exploit Pacific Alliance tariff advantages for cross-border shipments.
Brazil
ANVISA migration testing mandates for food-contact materials protect certified regional converters from Asian import competition. São Paulo's southern manufacturing belt concentrates three suppliers anchoring seventy percent of branded ready-meal can volume. Crown Holdings leverages backward integration into aluminum sheet production to secure feedstock for its São Paulo operations.
Mexico
COFEPRIS enforcement of NOM heavy metal leachate standards accelerates epoxy-phenolic coating conversions for tomato paste and fruit processors. The central industrial corridor anchors regional supply contracts where food processing clusters demand compliant substrates. Sinaloa seafood canners face consolidation pressure toward integrated converters with captive laboratory capacity.
Argentina
INTI certification requirements for tinplate corrosion resistance create twelve-to-eighteen month qualification timelines filtering smaller regional converters. Mendoza fruit processors favor twist-off closure formats for export conserves governed by INTI standards. Buenos Aires-based procurement teams prioritize Mercosur-crossing certification for supply security.
Chile
Santiago's industrial corridor adopts polymer-composite can bodies for powdered and dried food exports to Pacific Alliance markets. Proposed deposit-return schemes reshape material sourcing decisions toward converters with established metal recycling loops. Valparaíso port logistics favor lightweight formats for freight-cost-sensitive shipments.
Colombia
Underpenetrated Andean markets present white space for two-piece can formats as processed food manufacturing relocates from higher-cost Brazilian sites. Bogotá procurement teams exploit Pacific Alliance integration for tariff-advantaged substrate sourcing. Medellín converters invest in pull-tab specification capability for premium seafood positioning.
Latin America Canned Food Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite substrate specialization and lightweighting technology licensing. The market structure consolidates around multinational converters with cross-border Mercosur certification and captive laboratory capacity for migration testing compliance. Three archetypes dominate: integrated metal producers with upstream feedstock control, regional specialists with regulatory compliance depth, and technology licensors with lightweighting IP. Competitive moves center on backward integration into aluminum sheet production and strategic partnerships with food processors for coating chemistry co-development.
Within the integrated multinational tier, Crown Holdings, Ardagh Group, and Silgan Holdings exemplify scale-driven positioning with Mercosur-spanning supply relationships. Crown Holdings anchors Brazilian operations through feedstock security. Ardagh Group occupies the lightweighting technology vector. Silgan Holdings represents the regulatory compliance archetype with dominant multinational brand relationships. Trivium Packaging and Ball Corporation sit within the metal substrate specialist tier, while CCL Containers Mexico and Can-Pack S.A. exemplify regional fabrication focus.
| Leading Market Players |
|---|
| Trivium Packaging |
| Allstate Can Corp |
| Crown Holdings |
| Ardagh Group |
| Silgan Holdings |
| Ball Corporation |
| Wells Can Company Ltd |
| CCL Containers Mexico |
| Can-Pack S.A |
| Others |
Supply & Pricing Matrix
Skilled coating chemists concentrated in São Paulo's southern manufacturing belt widen pricing-tier spreads between certified regional converters and unqualified imports. Labor-cost differentials between Brazil's industrial corridor and lower-wage Andean sites feed into three-tier pricing stratification across premium ANVISA-compliant, standard Mercosur-certified, and economy non-certified supply tiers.
Pricing Analysis
Service bundling separates converters offering captive laboratory migration testing from bare-metal suppliers. Pricing stratifies across premium, standard, and economy tiers based on ANVISA certification grade and volume scale. Cost compression in the economy tier intensifies because Asian imports undercut regional labor costs. Multinational food brands show least price sensitivity; fragmented regional processors in Brazil's interior exhibit highest.
Supply Chain Analysis
ANVISA and COFEPRIS certification timelines gate supply relationships, filtering twelve-to-eighteen month qualification periods. Raw material flows draw from Brazilian steel coil production, US aluminum sheet imports, and Chinese tinplate feedstock. Single-source vulnerability concentrates in aluminum coil dependency on US and Chinese suppliers. Distribution runs through food processing clusters anchoring regional supply contracts in São Paulo and Mexico City's central industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around converters with cross-border Mercosur certification and captive laboratory capacity, as ANVISA migration testing mandates force smaller regional players out of branded supply chains.
For Market Incumbents: Anchor feedstock security through backward integration into aluminum sheet production or long-term steel coil offtake agreements. Deepen certification moats by investing in ANVISA and COFEPRIS laboratory capacity to capture Sinaloa seafood canner consolidation. Threat substitution from retortable polymer laminates demands coating chemistry co-development partnerships with tomato paste processors. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels offer low-friction entry into premium seafood and gourmet preserves segments. White space concentrates in Colombia's underpenetrated Andean markets for two-piece can formats. Target Pacific Alliance tariff advantages for cross-border substrate sourcing from Chilean polymer-composite specialists. For Investors and Strategic Acquirers: Re-rating potential sits with regional converters possessing INTI corrosion resistance certification given Argentina's twelve-to-eighteen month qualification timelines filtering supply chains. Long-term viability favors integrated metal producers with upstream feedstock control and established recycling loops. Watch deposit-return scheme proposals across Chile and Peru as inflection signals for material sourcing priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Sheet Production | Crown Holdings secures feedstock for São Paulo operations against LME price volatility. |
| ANVISA Laboratory Capacity Expansion | Captive migration testing capability captures protected demand pockets from Asian import filtration. |
| Epoxy-Phenolic Coating Conversion | Mexican tomato paste processors maintain COFEPRIS market access under tightened NOM enforcement. |
| Pacific Alliance Cross-Border Certification | Chilean converters exploit tariff advantages for Santiago-to-Bogotá composite can shipments. |
| Pull-Tab Specification Investment | Medellín converters capture premium seafood positioning through convenience differentiation. |
Research Methodology
Trade association filings, customs import records, and regulatory agency certification databases formed the secondary backbone for this analysis. Primary interviews with coating chemistry directors at Brazilian converters, procurement leads at multinational food brands, COFEPRIS compliance officers, and aluminum sheet traders validated secondary findings. Bottom-up volume estimates from canbody production lines triangulated against top-down food processing capacity data.
Bottom-up modeling tracked substrate demand by packaging format, closure type, and end-user segment across the projection horizon. Segmentation dimensions included metal versus composite versus plastic substrates, pull-tab versus twist-off versus screw cap mechanisms, and manufacturer versus retailer versus food service buyer archetypes. CAGRs derived from historical production trends, regulatory enforcement intensity trajectories, and ready-meal adoption elasticities in urban corridors.
The model holds under stable ANVISA and COFEPRIS enforcement regimes; deviation in extended producer responsibility implementation timelines or aluminum tariff structures would shift material substitution patterns. Forecasts reflect assumptions about migration testing laboratory capacity expansion and Pacific Alliance trade integration momentum. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Global Disposable Plates Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Food Can Market
Food Packaging
Egg Cartons Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Canned Food Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Wooden Cutlery Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
Europe Frozen Food Packaging Market