

Meat, Poultry, and Seafood Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Meat, Poultry, and Seafood Packaging Market Insights
Asset-light leasing models for high-barrier film extrusion lines are reshaping competitive entry in meat, poultry, and seafood packaging, allowing mid-scale processors to access oxygen-scavenging and ethylene-vinyl alcohol coextrusion capacity without capital-heavy balance sheets. Amcor leverages its global resin procurement network to sustain margin stability across volatile polymer feedstock cycles. Sealed Air anchors North American protein processor relationships through integrated vacuum packaging system deployments. Mondi Group differentiates via kraft-paper-based barrier solutions that navigate rising European single-use plastic restrictions.
Meat, poultry, and seafood packaging encompasses engineered multilayer structures—typically incorporating polyethylene sealant layers, polyamide or ethylene-vinyl alcohol oxygen barriers, and polyester or oriented polypropylene exterior plies—fabricated through coextrusion, lamination, or thermoforming to extend shelf life and prevent microbial contamination in temperature-controlled distribution. Modified atmosphere packaging dominates fresh red meat applications where residual oxygen below 0.5 percent preserves myoglobin color stability, while vacuum skin packaging represents the fastest-growing format for premium seafood portions as retail delis and e-commerce fulfillment channels expand. Biodegradable films remain structurally marginal but capture disproportionate R&D investment as food processing plants face Scope 3 emissions accounting pressure from European supermarket chains.
The European Commission's Packaging and Packaging Waste Regulation alongside EFSA migration limits for recycled content in food-contact layers are forcing material redesign across polyethylene and polyester supply chains serving the sector. FDA's food-contact substance notification requirements and USDA FSIS label approval protocols govern U.S. market access for novel barrier technologies. Stakeholders must monitor how divergent EU-U.S. recyclability definitions reshape investment allocation between mechanical recycling-compatible mono-materials and chemically recycled feedstocks.
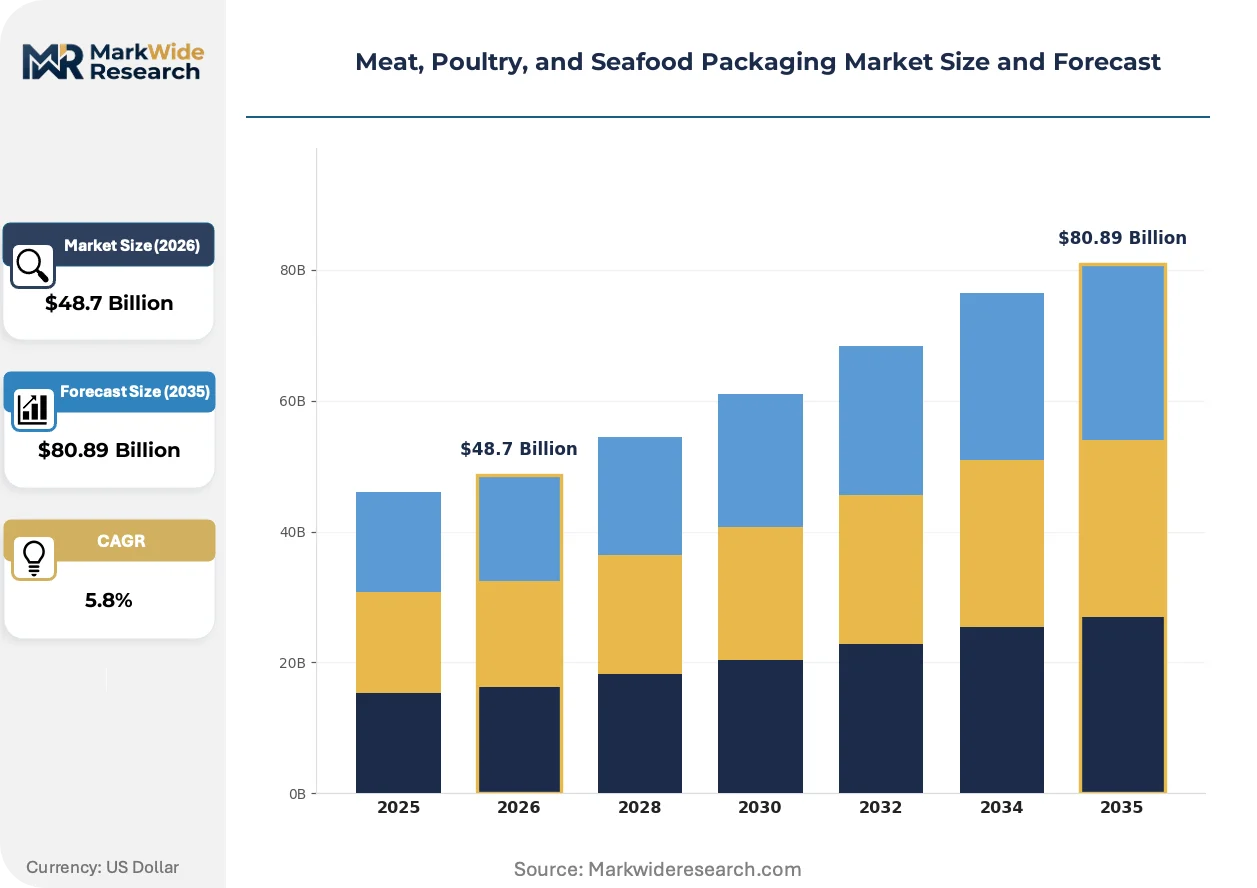
Market Dynamics
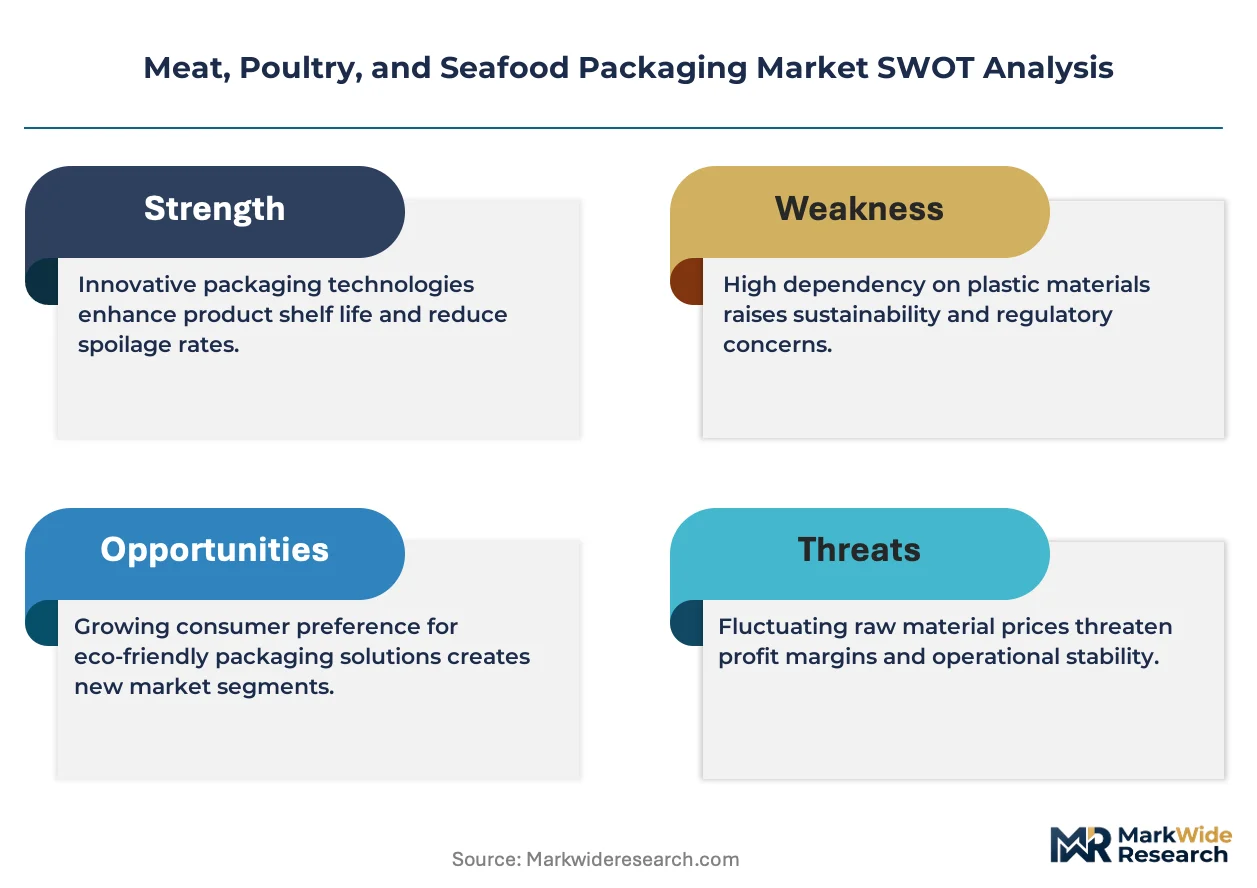
EU Green Deal material compliance mandates and F-Gas Regulation phase-down schedules are forcing simultaneous redesign of barrier films and cold-chain logistics across European protein supply chains. Asset-light leasing models for high-barrier extrusion capacity allow mid-scale processors to access oxygen-scavenging technologies without capital-heavy balance sheets.
Growth Catalysts
- EU Green Deal packaging mandates:Tightening recyclability requirements accelerate mono-material adoption in German and French retail channels.
- Supermarket private-label expansion:Chains in Italy and Spain are scaling shelf-ready fresh meat programs that demand standardized barrier formats.
- EVOH coextrusion leasing:Mid-tier processors access oxygen-barrier capacity through equipment-as-a-service models.
Market Restraints
- Polyamide feedstock volatility:Caprolactam price swings compress margins for multi-layer barrier film producers.
- Recycled-content migration limits:EFSA thresholds for post-consumer content in food-contact layers constrain circular material sourcing.
- Mechanical recycling incompatibility:Legacy multi-material laminates face sorting infrastructure gaps in Italian and Polish waste streams.
Strategic Opportunities
- E-commerce fulfillment channels:Vacuum skin packaging formats capture premium seafood portions in direct-to-consumer logistics.
- Kraft-paper barrier convergence:Fiber-based solutions navigate single-use plastic restrictions in Nordic retail markets.
- Scope 3 emissions accounting:Biodegradable film R&D attracts investment from European supermarket sustainability procurement teams.
Industry Challenges
- Multilayer delamination expertise:Shortage of technicians skilled in coextrusion die geometry and layer adhesion optimization.
- USDA FSIS label approval timelines:Novel barrier technologies face extended regulatory clearance for direct food contact.
- Legacy thermoformer retrofit costs:Capital requirements for vacuum skin packaging line upgrades strain mid-scale processor budgets.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat, Poultry, and Seafood Packaging Market Trends and Innovations
Active material science and regulatory chemistry are converging to redefine barrier performance standards. Three developments dominate investment allocation across European and North American protein packaging supply chains.
Mono-material polyethylene structures with plasma-deposited silicon oxide coatings are hybridizing conventional multi-layer barrier economics. Premium red meat processors in Germany and France are piloting these formats to meet EU Packaging and Packaging Waste Regulation recyclability targets. The technology is hybridizing competitive positioning between mechanical recycling-compatible suppliers and legacy laminate incumbents.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from paper-based seafood trays. Danish and Dutch converters are accelerating fluorine-free barrier chemistry development to maintain export compliance. Fresh salmon and whitefish portion packs face the most acute reformulation pressure ahead of substance sunset dates.
Retail deli departments are consolidating purchasing around integrated vacuum packaging system contracts. North American supermarket chains are unbundling equipment maintenance from film supply agreements to reduce total cost of ownership. This reconfiguration is most visible in US coastal markets where seafood counter automation investments preceded protein department centralization.
Meat, Poultry, and Seafood Packaging Market Segmentation
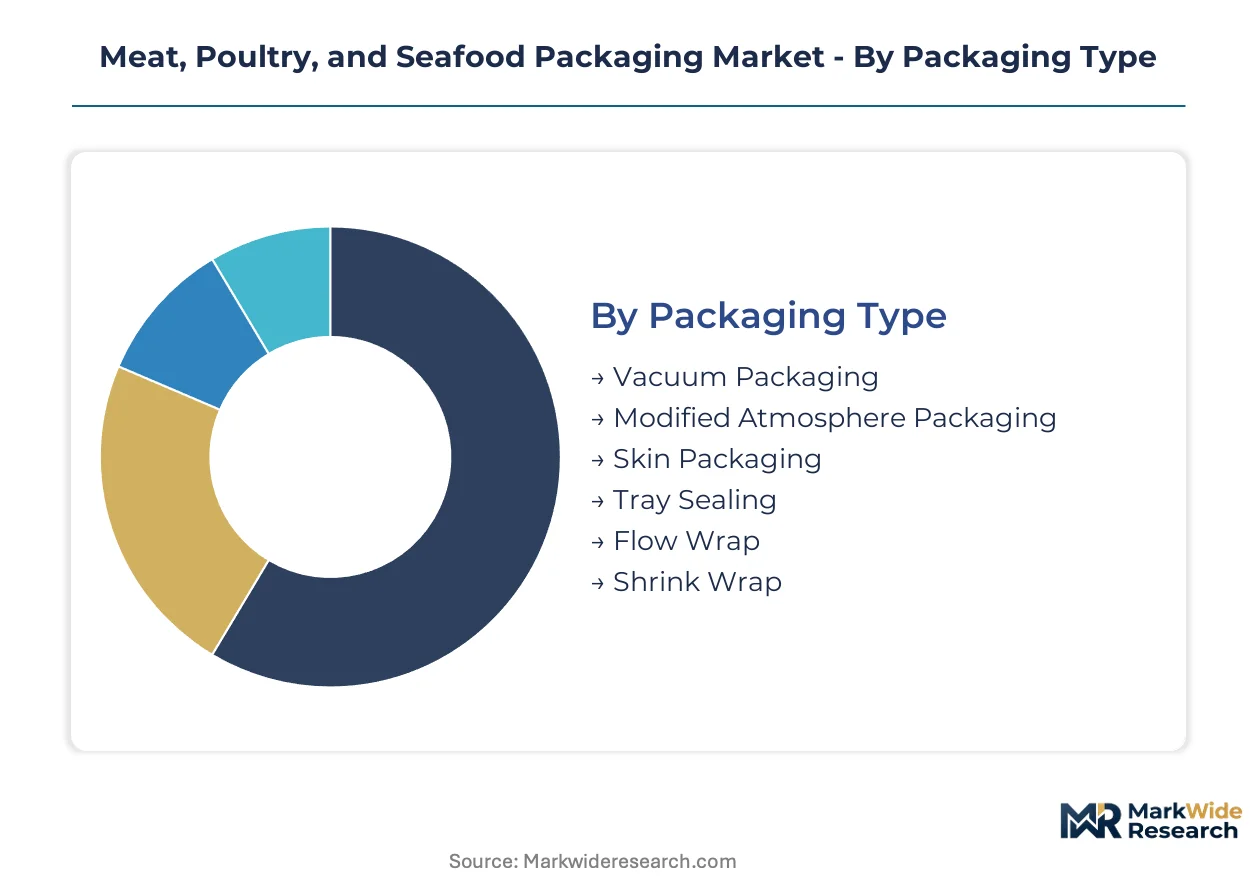
Protein packaging segmentation reveals how shelf-life requirements, regulatory constraints, and retail format specifications fragment demand across incompatible technical specifications. Each dimension—packaging type, material, application, and end user—operates on distinct procurement cycles and margin structures that reshape supplier positioning.
Packaging Type:
Mature vacuum formats dominate volume, while emerging active-barrier technologies capture premium repositioning opportunities in European retail channels.
- Vacuum Packaging:Multi-layer coextruded structures with polyamide or EVOH barriers extract oxygen to inhibit aerobic spoilage organisms. German and French supermarket chains specify this format for private-label fresh beef programs where myoglobin color stability determines purchase decisions. Equipment leasing models now allow mid-tier processors to access high-barrier capacity without capital-heavy balance sheets.
- Modified Atmosphere Packaging:Gas-flushed headspaces with tailored nitrogen-carbon dioxide-oxygen ratios extend retail display life for case-ready meat. Italian retail consolidation accelerates standardized barrier format adoption across centralized protein processing facilities. EU Green Deal recyclability mandates force simultaneous redesign of gas-barrier films and tray structures.
- Skin Packaging:Thermoformed film conforms tightly to product contours, eliminating headspace and reducing purge loss in premium seafood portions.
- Tray Sealing:Heat-sealed lidding films over rigid or semi-rigid bases serve portion-controlled deli and foodservice channels.
- Flow Wrap:Continuous horizontal wrapping accommodates high-speed bacon, sausage, and marinated poultry production lines.
- Shrink Wrap:Heat-activated film contraction provides secondary bundling and retail-ready presentation for multi-pack protein cases.
Vacuum packaging handles the majority of throughput; skin packaging is the fastest mover on share.
Material Type:
Cost tiers separate commodity polyolefins from engineered barrier structures and emerging circular alternatives.
- Polyethylene:Sealant layers and mono-material structures dominate mechanical recycling-compatible redesigns. Plasma-deposited silicon oxide coatings on PE substrates hybridize barrier performance with EU Packaging and Packaging Waste Regulation targets. German red meat processors pilot these formats to maintain shelf life while satisfying extended producer responsibility schemes.
- Polypropylene:Oriented films provide clarity and moisture resistance in poultry and fresh seafood display applications. Biaxially oriented PP competes with polyester on cost in Mediterranean retail channels where price-sensitive procurement dominates private-label development.
- Polyester:High-tensile strength and printability anchor lidding and thermoforming applications across temperature ranges.
- Paperboard:Fiber-based trays and cartons navigate Nordic single-use plastic restrictions in fresh fish retail.
- Biodegradable Films:PLA and starch-based structures attract R&D investment from European supermarket sustainability procurement teams facing Scope 3 emissions accounting pressure.
- Aluminum Foil:Absolute barrier properties preserve shelf-stable canned fish and retort pouch applications.
Polyethylene commands the largest installed base; biodegradable films are climbing the fastest on sustainability-linked procurement criteria.
Application:
Volume concentrates in fresh formats, while margin accrues to value-added processing and temperature-differentiated distribution.
- Fresh Meat:Color stability and purge control drive barrier specification for retail case-ready beef, pork, and lamb. Modified atmosphere and vacuum formats compete on total cost of ownership across German, French, and Italian supermarket supply chains. Residual oxygen below 0.5 percent preserves myoglobin chemistry that consumers associate with freshness.
- Processed Meat:Cured, smoked, and emulsified products require moisture and fat barrier compatibility with slicing and portioning equipment. Shelf-stable and refrigerated processed categories split procurement between high-barrier laminates and cost-optimized coextrusions.
- Fresh Poultry:High respiration rates and Campylobacter control priorities favor permeability-tuned films with antimicrobial additives.
- Frozen Seafood:Ice-glaze protection and freezer-burn prevention dominate specification for whitefish and shrimp bulk packs.
- Canned Fish:Retort pouch migration from rigid metal formats drives flexible barrier development for tuna and salmon shelf-stable segments.
Fresh meat absorbs the greatest packaging tonnage; processed meat offers the steepest expansion trajectory in portion-controlled convenience formats.
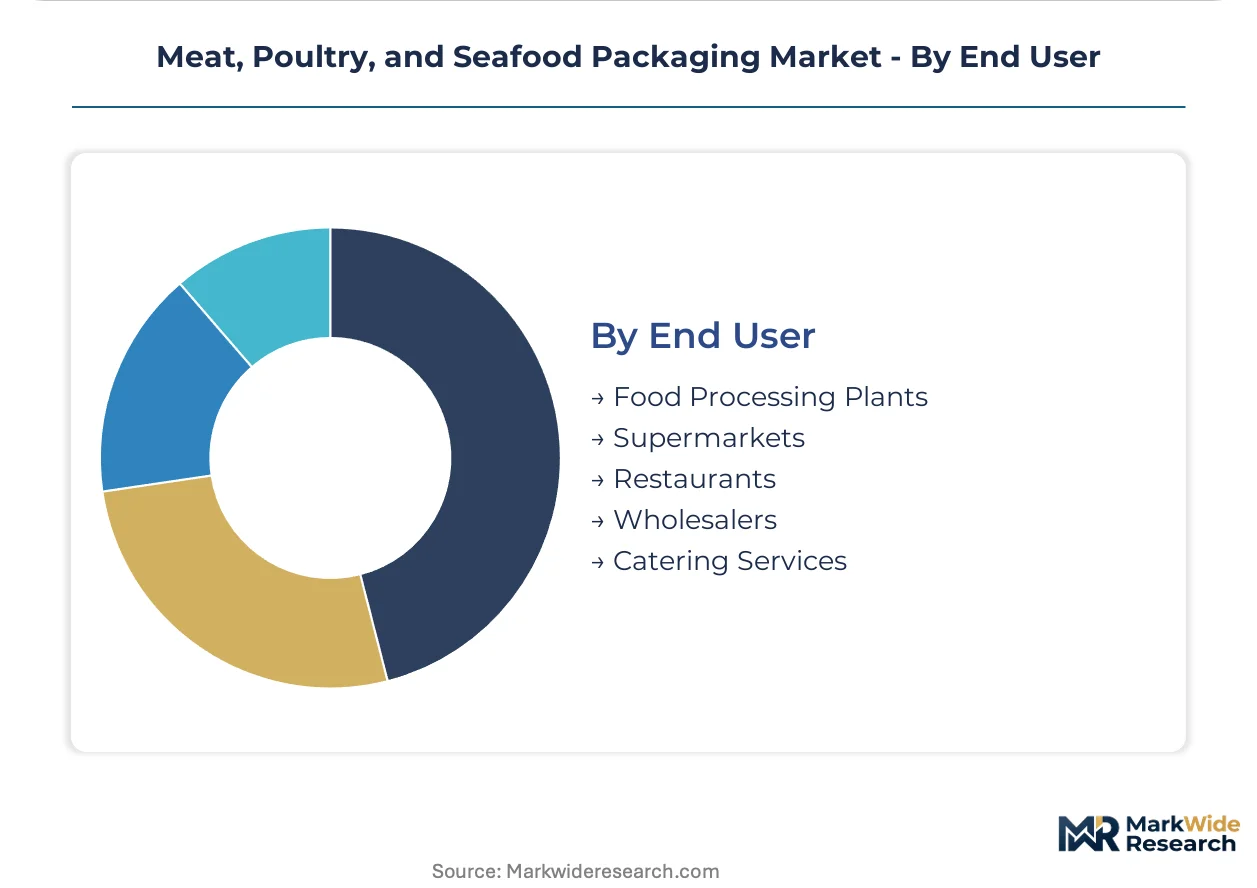
End User:
Customer type determines specification authority, with retail chains consolidating format standards while foodservice fragments across regional preferences.
- Food Processing Plants:Integrated protein packers specify barrier films concurrent with forming and sealing equipment investments. North American coastal processors anchor vacuum packaging system deployments through bundled maintenance and supply agreements. Capital constraints at mid-scale facilities accelerate equipment-as-a-service model adoption.
- Supermarkets:Private-label fresh meat program expansion in Spain and Italy demands standardized shelf-ready formats from centralized suppliers. Sustainability procurement teams impose Scope 3 emissions accounting that redirects film sourcing toward mechanically recyclable or bio-based alternatives.
- Restaurants:Foodservice distributors specify portion-controlled, labor-saving formats for back-of-house protein handling.
- Wholesalers:Break-bulk and redistribution channels prioritize case efficiency and pallet stability over retail presentation.
- Catering Services:Event and institutional feeding operations demand extended hold-time performance in variable temperature exposure.
Food processing plants represent the largest contract value; supermarkets are gaining specification authority fastest through retail consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket procurement teams in Germany, France, and Italy exercise outsized influence over barrier film specifications as retail consolidation accelerates shelf-ready format standardization across European protein supply chains.
Germany
Private-label fresh meat programs at Rewe and Edeka centralize purchasing power for modified atmosphere packaging formats. The EU Packaging and Packaging Waste Regulation forces simultaneous redesign of gas-barrier films and tray structures to satisfy extended producer responsibility schemes. Bavarian protein processors pilot mono-material polyethylene structures with plasma-deposited silicon oxide coatings.
France
Carrefour and Intermarché sustainability procurement teams impose Scope 3 emissions accounting that redirects film sourcing toward mechanically recyclable alternatives. REACH restrictions on per- and polyfluoroalkyl substances eliminate grease-resistant coatings from paper-based seafood trays ahead of substance sunset dates. Breton salmon processors accelerate fluorine-free barrier chemistry development.
Italy
Retail consolidation at Conad and Coop scales shelf-ready fresh meat programs demanding standardized barrier formats from centralized suppliers. EFSA migration limits for recycled content in food-contact layers constrain circular material sourcing across polyethylene supply chains. Emilia-Romagna cured meat producers navigate mechanical recycling incompatibility for legacy multi-material laminates.
United States
North American supermarket chains unbundle equipment maintenance from film supply agreements to reduce total cost of ownership in protein department centralization. FDA food-contact substance notification requirements and USDA FSIS label approval protocols govern market access for novel barrier technologies. Coastal processors from Seattle to Boston anchor vacuum packaging system deployments through bundled maintenance contracts.
Spain
Mercadona and Carrefour España expand private-label fresh meat programs that demand standardized barrier formats at scale. F-Gas Regulation phase-down schedules force redesign of cold-chain logistics alongside barrier film specifications. Catalan converters develop kraft-paper barrier solutions to navigate single-use plastic restrictions in retail channels.
Meat, Poultry, and Seafood Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: integrated multinational resin converters, regional equipment-film bundlers, and fiber-based barrier innovators. Consolidation pressure intensifies as supermarket chains centralize procurement around fewer approved supplier lists. Competitive moves concentrate on equipment-as-a-service leasing models and mono-material portfolio diversification.
Among integrated multinational converters, Amcor and Sealed Air occupy positions spanning resin procurement networks through downstream equipment integration. Mondi Group exemplifies the fiber-based barrier archetype navigating European single-use plastic restrictions. These three anchors represent divergent strategic responses to regulatory chemistry mandates and retail sustainability procurement pressure.
| Leading Market Players |
|---|
| Amcor |
| Sealed Air |
| Berry Global |
| Mondi Group |
| Sonoco |
| Coveris |
| Winpak |
| Multivac |
| DuPont |
| Others |
Pricing and Supply Chain Analysis
Emilia-Romagna's cured meat processing cluster concentrates barrier film demand, translating upstream resin volatility into asymmetric pricing power for converters with EVOH coextrusion capabilities. German supermarket chains leverage this concentration through consolidated procurement tenders that compress margins for mid-tier processors lacking vertical integration into sealant layer production.
Pricing Analysis
Certification level (EU food-contact compliance/EFSA migration-grade) creates the primary spread between premium and standard tiers. Contract-based long-term offtake agreements dominate volume procurement, with pricing stratifying across premium, standard, and economy tiers based on oxygen-barrier performance and recyclability certification. Cost compression in standard-grade polyethylene structures is intensifying because of caprolactam feedstock swings and mechanical recycling infrastructure gaps. Private-label supermarket buyers exhibit highest price sensitivity, while premium seafood processors prioritize shelf-life extension over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration rests with specialized converters in Germany, Italy, and the Netherlands holding high-barrier extrusion capacity. Raw material dependencies center on polyethylene resin, polyamide feedstock, and ethylene-vinyl alcohol copolymers sourced from petrochemical hubs. Single-source vulnerability in EVOH supply chains exposes processors to force majeure disruptions at European polymer plants. Distribution runs through centralized protein packing facilities serving consolidated retail chains, with cold-chain logistics bundling film supply alongside temperature-controlled transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service leasing models represent a service-attach opportunity expanding faster than commodity film sales, as mid-scale processors prioritize operational expenditure flexibility over capital deployment.
For Market Incumbents:Pre-empt displacement from mono-material competitors by accelerating plasma-deposited silicon oxide coating capacity in Bavaria and Baden-Württemberg. Deepen backward integration into sealant layer resin production to defend margin position against polyolefin price volatility. Secure exclusive maintenance contracts for vacuum packaging system deployments before supermarket chains complete procurement centralization.
For New Entrants and Emerging Players:Pursue white-space opportunities in fluorine-free barrier chemistry for Danish and Dutch seafood processors facing REACH substance sunset dates. Target Spanish and Italian mid-tier cured meat producers underserved by integrated equipment-film bundlers. Lead with kraft-paper barrier convergence positioned for Nordic single-use plastic restrictions.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among converters offering integrated vacuum packaging system leases with bundled maintenance and film supply agreements. Long-term viability favors asset-light business models with equipment-as-a-service penetration exceeding commodity film exposure. Monitor F-Gas Regulation phase-down schedules as inflection indicator for cold-chain packaging redesign demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Expansion | Mid-tier processors in Italy and Spain access oxygen-barrier capacity without capital-heavy balance sheets. |
| Mono-Material Portfolio Diversification | German red meat processors pilot plasma-coated polyethylene to satisfy EU Packaging and Packaging Waste Regulation targets. |
| Fluorine-Free Barrier Chemistry Development | Breton salmon processors accelerate reformulation ahead of REACH per- and polyfluoroalkyl substance restrictions. |
| Cold-Chain Logistics Integration | F-Gas Regulation phase-down forces simultaneous redesign of barrier films and temperature-controlled distribution. |
| Scope 3 Emissions Accounting Alignment | European supermarket sustainability procurement teams redirect film sourcing toward mechanically recyclable alternatives. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with protein packaging procurement managers, coextrusion equipment engineers, and supermarket sustainability directors; and secondary validation through EU Packaging and Packaging Waste Regulation filings, EFSA migration limit documentation, and customs data on polyethylene and polyamide trade flows. Bottom-up and top-down triangulation cross-checked converter capacity announcements against retail chain procurement tender volumes.
Forecast inputs considered packaging type, material grade, protein application, and end-user procurement authority across the modeling period. CAGRs were derived from segment-level volume trajectories weighted by EVOH coextrusion capacity expansion and supermarket private-label program scaling. Industry-specific inputs included F-Gas Regulation phase-down schedules and EFSA recycled-content threshold evolution.
Macroeconomic conditions sit as an overlay; deviation in polymer feedstock pricing, energy costs, and European retail consolidation velocity would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timing and equipment leasing adoption curves. Quarterly review of converter capacity utilization rates and supermarket sustainability procurement tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.