
 Testing, Inspection, and Certification (TIC) in the Energy and Power Market | 2026-2036
Testing, Inspection, and Certification (TIC) in the Energy and Power Market Size, Share, and Industry Trends Forecast 2026-2036
Testing, Inspection, and Certification (TIC) in the Energy and Power Market Insights
Utility buyer concentration is expanding as regulated monopolies and large independent power producers consolidate procurement of testing services under long-term framework agreements. SGS SA leverages its global laboratory network to compete for multi-site utility contracts across generation and grid infrastructure. Bureau Veritas SA anchors its position in offshore wind through specialized marine corrosion and structural fatigue protocols. Intertek Group PLC differentiates via integrated safety and performance verification for battery energy storage systems.
Testing, Inspection, and Certification in the Energy and Power sector encompasses the independent evaluation of electrical infrastructure, fossil fuel installations, and renewable assets against technical standards for safety, reliability, and environmental performance. Core activities include non-destructive evaluation of turbine blades, transformer oil analysis, and grid code compliance testing for inverter-connected generation. Quality Assurance commands the largest share of service revenue due to recurring statutory obligations, while Remote Monitoring represents the fastest-expanding delivery model as IoT sensor networks enable continuous asset surveillance. Ultrasonic Testing dominates the technology mix for pipeline and pressure vessel inspection, though Infrared Thermography gains traction in predictive maintenance programs for solar photovoltaic arrays.
FDA guidelines for battery safety in grid-scale storage, EPA emissions monitoring mandates for coal and gas facilities, and ISO 50001 energy management standards collectively shape compliance expenditure patterns across the value chain. The EU AI Act introduces new algorithmic transparency requirements for automated grid management systems, creating adjacent certification demand. Stakeholders must monitor how overlapping national and supranational standards evolve, as divergence between jurisdictions fragments accreditation pathways and inflates compliance costs for cross-border operators.
Market Dynamics
Grid modernization and renewable energy integration are compressing testing cycles while expanding the scope of mandatory verification across battery storage, hydrogen infrastructure, and offshore wind assets.
Growth Catalysts
- EU Green Deal compliance deadlines:Member states are accelerating certification for offshore wind farms and hydrogen pipeline networks ahead of binding carbon neutrality targets.
- Battery storage deployment:Grid-scale lithium-ion installations require thermal runaway testing and fire safety validation under evolving national electrical codes.
- United States:IRA tax credits for clean energy projects mandate third-party performance verification, expanding accredited body workloads across solar and storage assets.
Market Restraints
- Accredited laboratory scarcity:Specialized hydrogen embrittlement testing capacity concentrates in Germany and the Netherlands, creating bottlenecks for pipeline projects.
- Input cost volatility:Helium prices for leak detection in high-pressure systems have fluctuated sharply, pressuring margins for gas infrastructure inspection contracts.
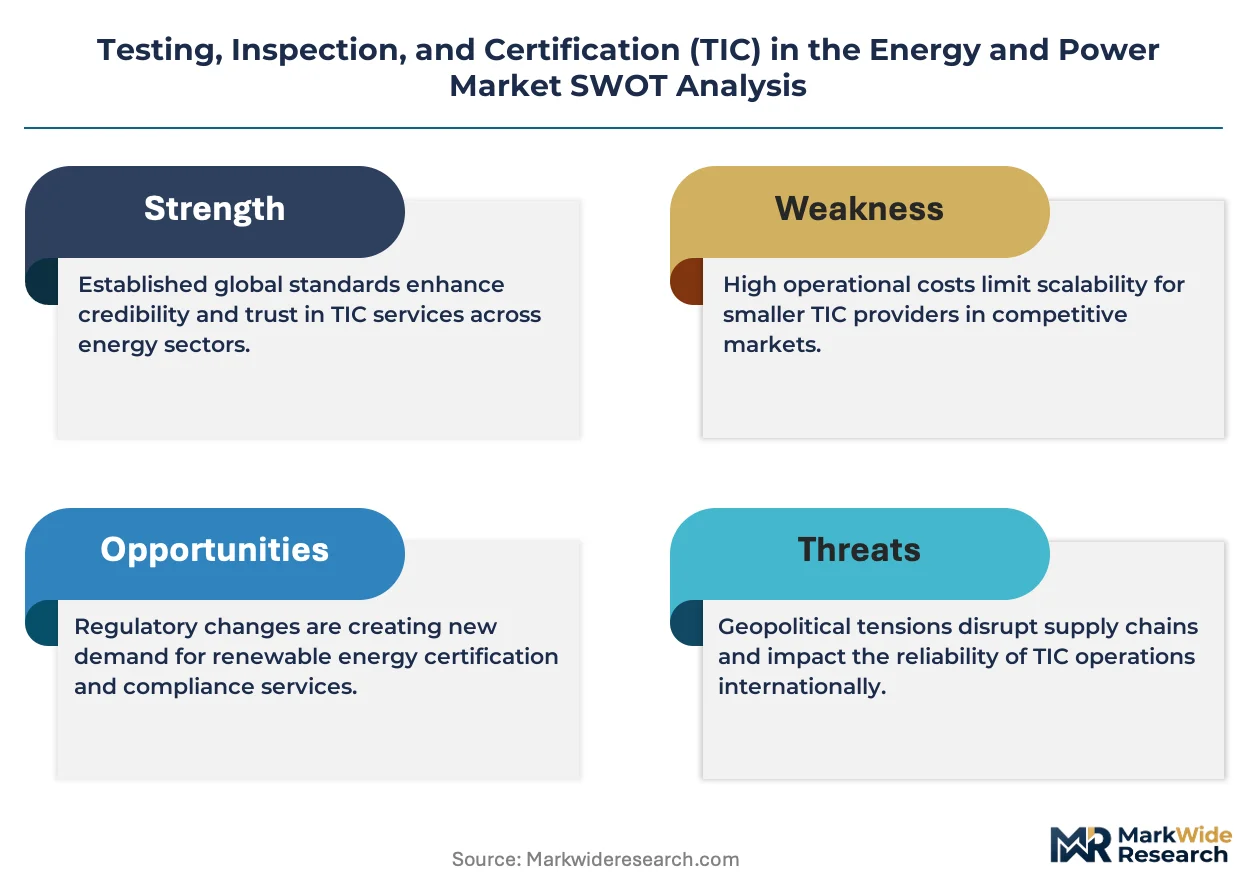
- Regulatory fragmentation:Divergent national interpretations of IEC 61400 for wind turbine certification inflate compliance costs for cross-border operators.
Strategic Opportunities
- India:Central Electricity Authority mandates for renewable integration testing create unmet demand for grid code compliance verification as solar capacity expands.
- Digital twin convergence:Integration of IoT sensor networks with predictive analytics platforms enables continuous remote monitoring contracts replacing periodic inspection.
- Green hydrogen certification:Guarantee of origin schemes under EU delegated acts require new verification protocols for electrolyzer output and transport infrastructure.
Industry Challenges
- Non-destructive testing technician shortage:Specialized ultrasonic and radiographic inspection skills for offshore wind foundations face generational replacement gaps across European markets.
- Certification timeline compression:Accelerated project finance deadlines for utility-scale solar force parallel-track testing that strains laboratory scheduling capacity.
- Legacy asset integration:Retrofitting predictive maintenance systems onto decades-old transformer fleets requires custom sensor configurations that lack standardized validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testing, Inspection, and Certification (TIC) in the Energy and Power Market |
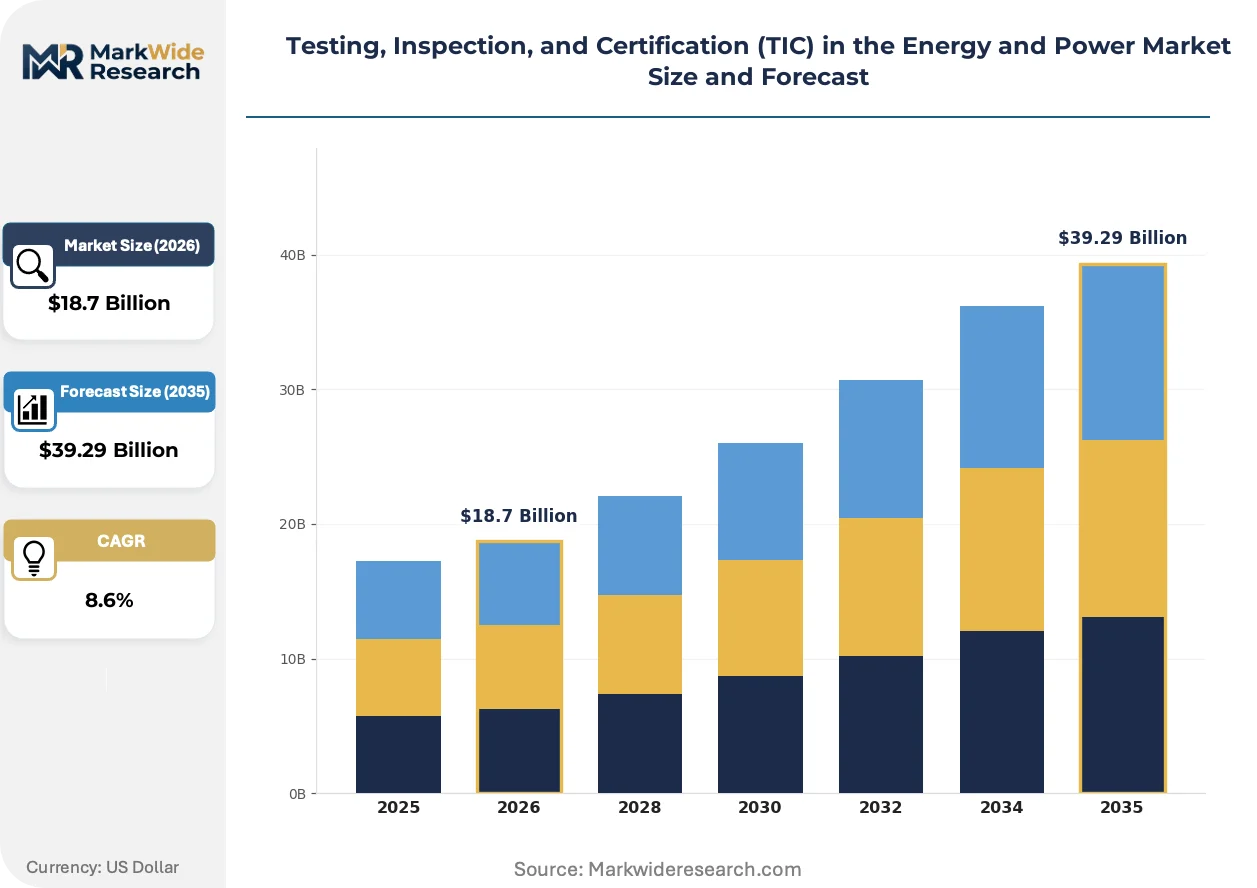
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quality Assurance, Compliance Testing, Performance Verification, Safety Inspection Technology: Ultrasonic Testing, Infrared Thermography, Radiographic Testing, Vibration Analysis Delivery Model: On-site Services, Remote Monitoring, Laboratory Testing, Consultancy Client Type: Utilities, Renewable Energy Providers, Oil & Gas Companies, EPC Contractors |
| Companies Covered | TÜV SÜD AG, UL Solutions, SGS SA, DNV, DEKRA SE, Bureau Veritas SA, TÜV Rheinland AG, Applus+, Intertek Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testing, Inspection, and Certification (TIC) in the Energy and Power Market Trends and Innovations
Digitalization of asset monitoring and algorithmic compliance verification are restructuring how testing services are delivered, priced, and consumed across the energy value chain.
Drone-mounted thermography combined with machine learning defect recognition is electrifying solar farm inspection protocols. Independent power producers in Spain and Australia are replacing manual string-level testing with automated aerial surveys that compress inspection cycles from weeks to days. This convergence is compressing pricing for traditional ground-based thermal imaging services while expanding total addressable monitoring volume.
The EU AI Act's risk classification framework for automated grid management systems is mandating algorithmic transparency documentation. Transmission system operators in Germany and France must now submit conformity assessments for load forecasting models and automated switching protocols. Certification bodies are building new technical competencies in software validation and bias auditing to capture this adjacent demand.
Long-term framework agreements are displacing transactional procurement for utility testing services. Large independent power producers in Texas and California are consolidating multi-site contracts under single-source accreditation arrangements that bundle generation, storage, and grid asset verification. This concentration is visible most acutely in offshore wind, where developers pre-qualify inspection partners for decade-long project lifecycles spanning construction through decommissioning.
Testing, Inspection, and Certification (TIC) in the Energy and Power Market Segmentation
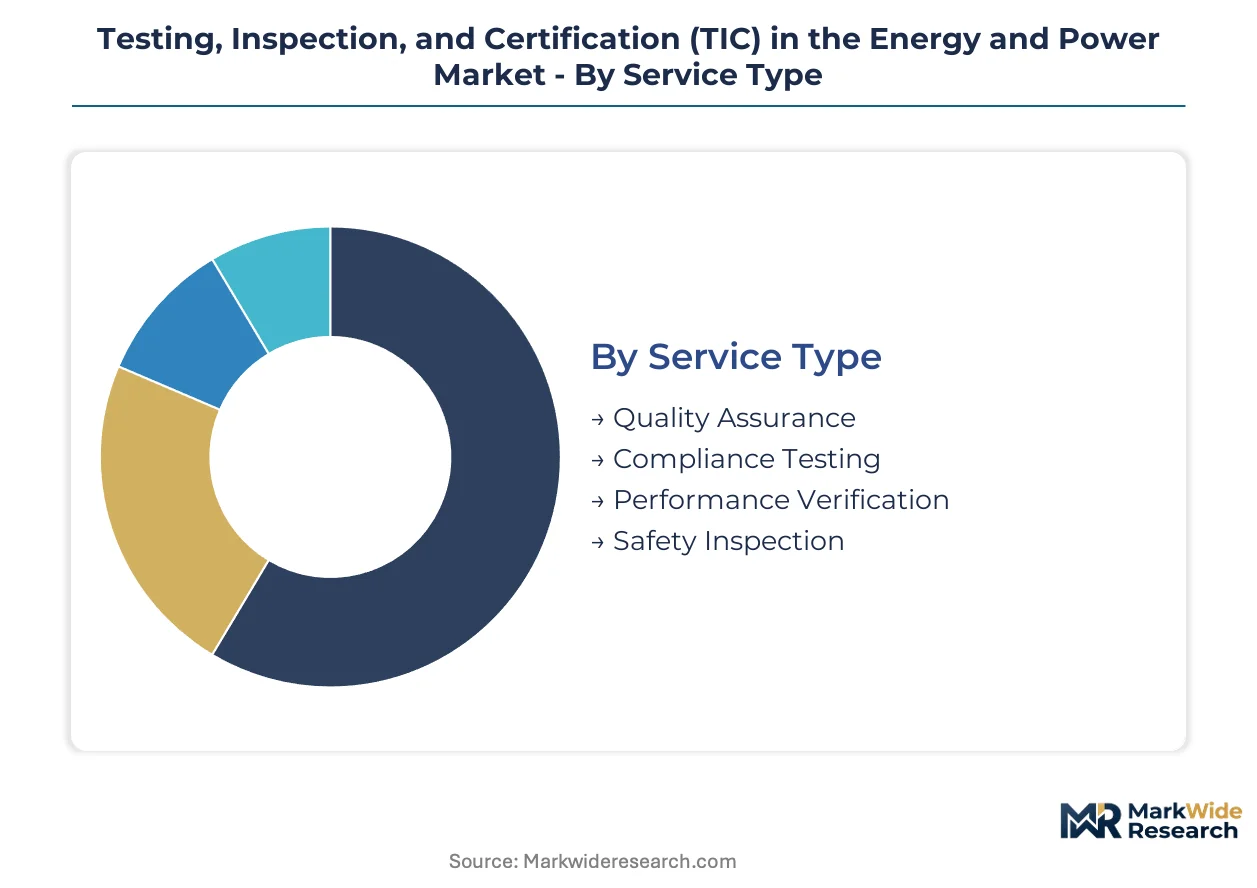
TIC providers in energy and power must align service architectures with divergent buyer capabilities and risk profiles. Procurement patterns split between capital-intensive utilities demanding long-term frameworks and project developers seeking transactional verification for construction milestones.
Service Type:
Buyers differentiate by regulatory exposure depth and recurring obligation intensity rather than asset scale alone.
- Quality Assurance:Systematic process audits and management system certification against ISO 50001 and grid code standards. German transmission operators and French nuclear utilities anchor volume through mandatory recurring audits under national energy efficiency regulations.
- Compliance Testing:Statutory verification of emissions, safety systems, and electrical code adherence. IRA tax credit eligibility requirements in the United States and EU Green Deal deadlines are compressing procurement timelines for battery storage and hydrogen infrastructure developers.
- Performance Verification:Output validation for renewable assets against contracted specifications.
- Safety Inspection:Hazard assessment for high-voltage equipment and pressure systems.
Volume sits with Quality Assurance; growth tilts toward Compliance Testing.
Technology:
Technology selection tracks asset material composition and defect detection precision requirements across generation and grid infrastructure.
- Ultrasonic Testing:High-frequency acoustic wave propagation detects subsurface cracks in turbine blades and pipeline welds without material destruction. Offshore wind foundations in the North Sea and hydrogen transmission networks in Germany concentrate demand as wall thickness and defect tolerance specifications tighten.
- Infrared Thermography:Thermal imaging identifies electrical hotspots and insulation degradation. Spanish solar farms and Australian utility-scale photovoltaic installations are displacing manual string testing with drone-mounted thermal surveys.
- Radiographic Testing:Gamma and X-ray penetration for weld integrity verification in pressure vessels.
- Vibration Analysis:Rotating machinery condition monitoring for turbines and generators.
Ultrasonic Testing commands the largest installed base; Infrared Thermography is climbing the fastest as predictive maintenance programs expand.
Delivery Model:
Delivery configuration depends on asset mobility, data infrastructure maturity, and the economic trade-off between continuous surveillance and periodic inspection.
- On-site Services:Technician-deployed testing at generation facilities and substations.
- Remote Monitoring:IoT sensor networks enabling continuous asset surveillance and algorithmic anomaly detection. German transmission system operators under EU AI Act requirements are procuring integrated monitoring platforms that bundle hardware installation with compliance documentation.
- Laboratory Testing:Controlled environment analysis of oil samples, battery cells, and material specimens.
- Consultancy:Advisory services for certification strategy and regulatory navigation.
Laboratory Testing retains the revenue base; Remote Monitoring is gaining share fastest as grid digitalization accelerates.
Client Type:
Client procurement sophistication varies by ownership structure and regulatory jurisdiction complexity.
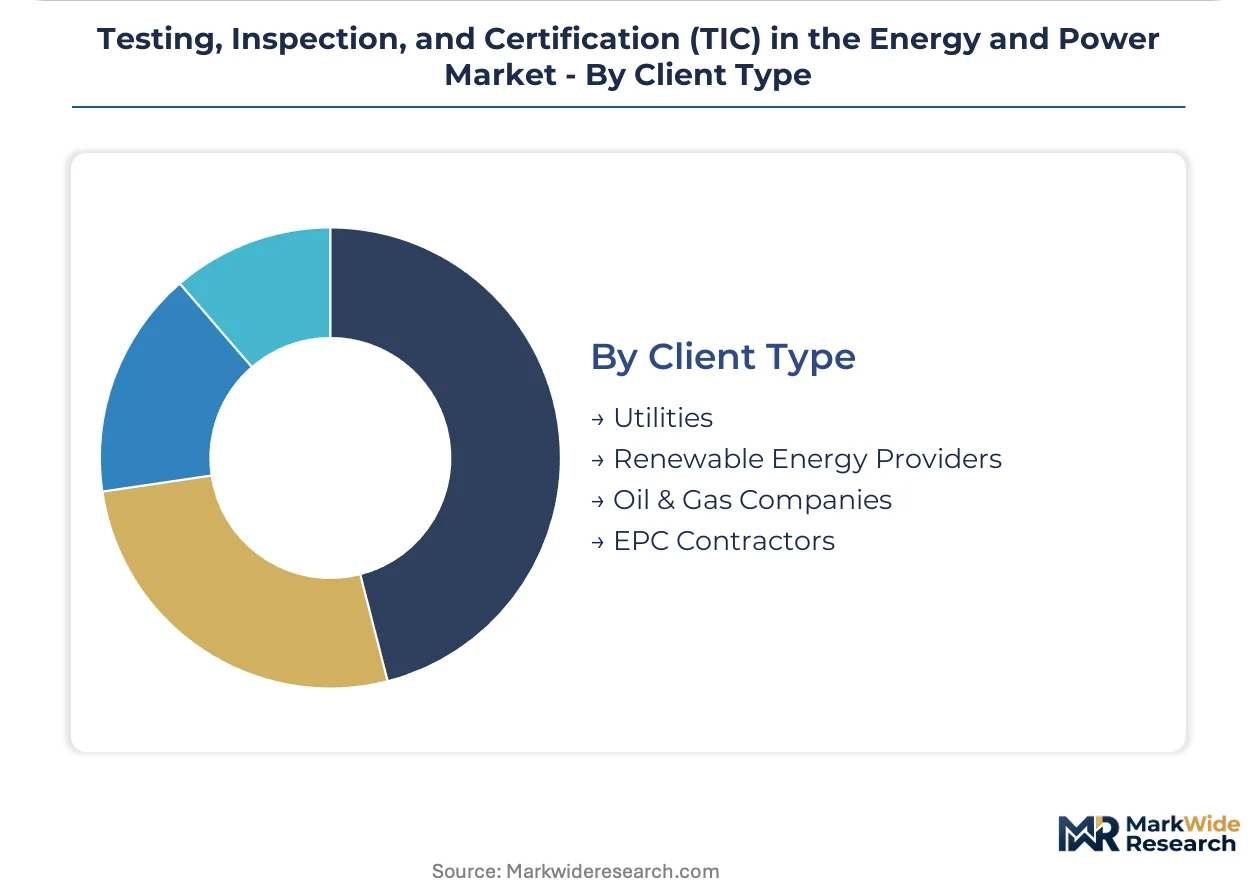
- Utilities:Regulated monopolies and vertically integrated generators with multi-decade asset horizons. Long-term framework agreements predominate, with SGS SA and Bureau Veritas SA competing for multi-site contracts spanning generation, transmission, and storage verification.
- Renewable Energy Providers:Independent power producers and project developers with construction-to-operations transition requirements. IRA tax credit mandates in the United States and EU delegated acts for green hydrogen certification are expanding third-party verification procurement.
- Oil & Gas Companies:Legacy fossil fuel operators facing emissions monitoring obligations.
- EPC Contractors:Engineering-procurement-construction firms requiring stage-gate certification for project handover.
Utilities dominate current spend; Renewable Energy Providers show the steepest expansion trajectory as capacity deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium extraction in the United States and hydrogen pipeline corridors in Germany anchor geographic demand for specialized testing infrastructure. Offshore wind fabrication clusters in Denmark and battery cell manufacturing in South Korea concentrate accreditation workloads. Regulatory divergence between jurisdictions fragments certification pathways for cross-border energy assets.
United States
IRA tax credit eligibility mandates third-party performance verification for solar and storage installations. EPA emissions monitoring requirements for coal and gas facilities sustain demand for continuous emissions monitoring systems. Texas and California utilities consolidate multi-site framework agreements spanning generation, transmission, and battery storage assets.
Germany
Offshore wind certification and hydrogen pipeline testing create specialized workload pools for accredited bodies. EU Green Deal compliance deadlines accelerate certification for North Sea wind farms and hydrogen backbone networks. The Ruhr industrial corridor and Hamburg port cluster concentrate laboratory capacity for high-pressure gas infrastructure validation.
China
Dual carbon goals drive grid-scale battery deployment requiring thermal runaway testing under evolving national electrical codes. MIIT standards for inverter-connected generation expand grid code compliance verification demand. Yangtze River Delta manufacturing clusters anchor domestic certification capacity for export-oriented solar module producers.
India
Central Electricity Authority mandates for renewable integration testing create unmet demand as solar capacity expands. BIS standards for electrical infrastructure safety reshape procurement patterns for transmission and distribution equipment. Gujarat and Rajasthan solar parks concentrate construction-phase verification workloads for independent power producers.
United Kingdom
Offshore wind lease rounds in the North Sea require decade-long certification partnerships spanning construction through decommissioning. Ofgem grid code compliance obligations for battery storage interconnectors expand third-party verification procurement. Scottish floating wind projects and Humber hydrogen hub development concentrate specialized marine corrosion testing demand.
Testing, Inspection, and Certification (TIC) in the Energy and Power Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital remote monitoring and AI-driven predictive analytics. The vendor base stratifies across three tiers: global multi-service conglomerates with laboratory networks, regional specialists in offshore wind or hydrogen infrastructure, and technology-focused entrants offering IoT-enabled continuous surveillance. Consolidation pressure intensifies as utilities favor long-term framework agreements over transactional procurement. Dominant competitive moves include strategic partnerships for digital twin integration and geographic expansion into underpenetrated hydrogen certification markets.
Within the global multi-service tier, SGS SA, Bureau Veritas SA, and Intertek Group PLC exemplify scale-driven positioning. SGS SA leverages its laboratory network footprint to compete for multi-site utility contracts. Bureau Veritas SA anchors its market presence through specialized marine and structural protocols for offshore wind. Intertek Group PLC occupies a position emphasizing integrated safety and performance verification for battery energy storage systems. These three entities represent divergent strategic archetypes within the consolidated upper tier.
| Leading Market Players |
|---|
| TÜV SÜD AG |
| UL Solutions |
| SGS SA |
| DNV |
| DEKRA SE |
| Bureau Veritas SA |
| TÜV Rheinland AG |
| Applus+ |
| Intertek Group PLC |
| Others |
Pricing and Supply Chain Analysis
Specialized ultrasonic and radiographic inspection technicians in Germany and the Netherlands command wage premiums that widen spreads between premium-tier accredited laboratories and economy-grade regional competitors. Labor-cost differentials across European testing hubs feed directly into three-tier pricing structures that segment buyers by certification urgency and compliance risk tolerance.
Pricing Analysis
Volume concentrates in recurring Quality Assurance audits while margins accrue to specialized hydrogen embrittlement and battery thermal runaway testing. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61400 wind turbine certification from routine transformer oil analysis. Cost compression in standard-tier laboratory services is intensifying because drone-mounted thermography is displacing manual ground-based inspection. Project developers seeking IRA tax credit eligibility show highest price sensitivity; utilities under mandatory EU Green Deal deadlines exhibit lowest.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and the United States' Buy America provisions for grid infrastructure are reshaping equipment sourcing patterns for testing apparatus. Supply concentrates in Germany, the United States, and China for high-pressure gas testing equipment, radiographic inspection systems, and IoT sensor networks. Raw material dependencies include helium for leak detection, rare-earth elements for magnetic particle inspection, and lithium compounds for battery cell validation. Single-source vulnerability sits with German hydrogen embrittlement testing capacity. Distribution runs through accredited body laboratory networks and certified third-party service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term framework agreements from consolidated utilities are squeezing transactional providers, forcing sub-scale competitors toward exit or acquisition. Procurement concentration favors multi-service conglomerates with geographic coverage depth.
For Market Incumbents: Acquire specialized hydrogen pipeline testing laboratories in Germany and the Netherlands to lock in scarce accredited capacity before EU Green Deal deadlines compress availability. Build captive drone-mounted thermography fleets to offset margin erosion from automated inspection entrants. Defensive positioning requires preemptive certification investment in EU AI Act algorithmic transparency protocols before transmission operators finalize vendor panels. For New Entrants and Emerging Players: AI-driven predictive analytics platforms for transformer fleet monitoring offer the most penetrable wedge against legacy periodic inspection incumbents. Target India's unmet grid code compliance verification demand as solar capacity expands under Central Electricity Authority mandates. Go-to-market angle: bundle IoT sensor installation with continuous remote monitoring subscriptions to displace transactional on-site contracts. For Investors and Strategic Acquirers: Re-rating potential sits with regional hydrogen infrastructure specialists given EU delegated acts for green hydrogen certification of origin schemes. Five-to-ten year viability hinges on electrolyzer deployment trajectories and pipeline network buildout. Watch German hydrogen backbone project FID announcements as inflection indicator for accredited body utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Network Expansion | Captures multi-site utility framework contracts under EU Green Deal compliance deadlines. |
| Drone-Mounted Thermography Deployment | Compresses solar farm inspection cycles from weeks to days against manual competitors. |
| Hydrogen Certification Protocol Development | Positions for EU delegated acts on green hydrogen guarantee of origin verification. |
| AI Act Algorithmic Validation Capability | Enables conformity assessment submissions for German transmission operator load forecasting models. |
| India Grid Code Compliance Entry | Addresses unmet demand from Central Electricity Authority renewable integration mandates. |
Research Methodology
Multi-period observation of accredited body utilization rates, helium price volatility, and utility procurement contract structures anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from EIA capacity data, IEA renewable deployment reports, FERC interconnection filings, and EU Green Deal implementation tracking. Bottom-up segment sizing triangulated against top-down market envelope checks.
Segment-weighting across service type, technology, delivery model, and client type dimensions shaped the analytical framework. Modeled projections incorporate fuel source transitions, generation capacity tier deployment patterns, and regional grid modernization spending trajectories. CAGRs derive from regression analysis of historical accredited body revenue patterns against announced project pipelines. Forecast inputs include IRA tax credit uptake velocity and EU hydrogen backbone construction timelines.
Several conditions sit outside the modeled scope, including abrupt regulatory divergence between national interpretations of IEC standards, supply chain disruptions in helium extraction, and unanticipated battery chemistry shifts altering thermal runaway testing protocols. Forecasts reflect documented assumptions about policy continuity and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Europe Energy Management Systems Market
Energy Management
Energy Harvesting System Market
Energy Management
Heat Meter Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
Smart Power Management Market
Energy Management
Microgrid Control System Market
Energy Management
Electric Sub-Meter Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Thermostat Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Power SCADA Market
Energy Management
Smart Power Technologies Market
Energy Management
Industrial Energy Management System Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Smart Energy Solutions Market