
 Heat Meter Market | 2026-2036
Heat Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Meter Market Analysis
Ultrasonic sensing paired with IoT connectivity is tilting how heat meters capture and transmit thermal energy data. Siemens leverages its building automation ecosystem to bundle metering with HVAC controls. Kamstrup anchors its position through deep specialization in ultrasonic flow measurement for district heating networks. Diehl Stiftung & Co. KG competes on manufacturing scale across mechanical and electronic meter variants.
A heat meter measures thermal energy transfer in hydronic heating or cooling systems, typically employing paired temperature sensors and a flow calculator rated for pipe diameters from DN15 to DN1000, with accuracy classes spanning EN 1434 categories. Its primary commercial purpose is to enable fair cost allocation in multi-tenant buildings and optimize district heating network efficiency. Ultrasonic and smart product types now lead replacement demand as utilities phase out mechanical impeller designs with higher maintenance burdens. IoT-based and wireless technology segments are expanding fastest where remote readout eliminates manual meter reading labor.
EMA and national implementations of the EU Energy Efficiency Directive shape product certification and data interoperability requirements across Europe. Germany's MessEG and Denmark's heat supply regulations mandate periodic calibration intervals that sustain recurring service revenue for meter suppliers. Stakeholders must weigh the capital cost of full smart meter deployment against the operational savings from automated billing and leak detection analytics.
Market Dynamics
The EU F-Gas Regulation is compressing replacement cycles across Northern European district heating networks, forcing utilities to retire mechanical impeller meters ahead of schedule and recalibrate procurement priorities toward ultrasonic and IoT-enabled measurement systems.
Growth Catalysts
- Denmark's heat supply regulations:Mandatory periodic calibration intervals sustain recurring service revenue streams for meter suppliers while locking in long-term customer relationships through compliance-driven maintenance contracts.
- Ultrasonic flow measurement:This technology eliminates moving parts, cutting maintenance burdens and enabling remote diagnostics that reduce field service dispatch frequency for district heating operators.
- Multi-tenant building retrofit mandates:Germany's MessEG and parallel national frameworks require individual billing systems in legacy residential stock, creating installed base expansion across Poland, the Czech Republic, and Austria.
Market Restraints
- Copper and semiconductor input volatility:Temperature sensor assemblies and flow calculator chipsets face price instability that compresses gross margins on electronic meter variants.
- Mechanical meter supplier concentration:Eastern European manufacturing clusters retain legacy impeller production capacity, creating oversupply pressure in price-sensitive replacement segments.
- Accuracy class ceiling:EN 1434 Category 3 meters cannot satisfy sub-1% error requirements for large-scale industrial heat exchange monitoring, limiting addressable market scope.
Strategic Opportunities
- Poland's building efficiency renovation wave:EU Recovery and Resilience Facility funding channels toward district heating modernization in Warsaw, Kraków, and Łódź, accelerating meter deployment timelines.
- LoRaWAN and NB-IoT protocol convergence:Wireless communication stacks paired with cloud analytics platforms enable predictive maintenance offerings that differentiate hardware suppliers.
- Heat pump integration monitoring:Emerging hybrid heating systems require bidirectional thermal energy measurement, opening specification opportunities in Scandinavian residential new-build segments.
Industry Challenges
- Metrology certification backlog:National notified bodies in Germany and Denmark face testing queue delays that extend product launch timelines by 8-14 months.
- Legacy M-Bus infrastructure interoperability:Smart meter rollouts must bridge proprietary communication protocols from 1990s-era building automation systems without full system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Meter Market |
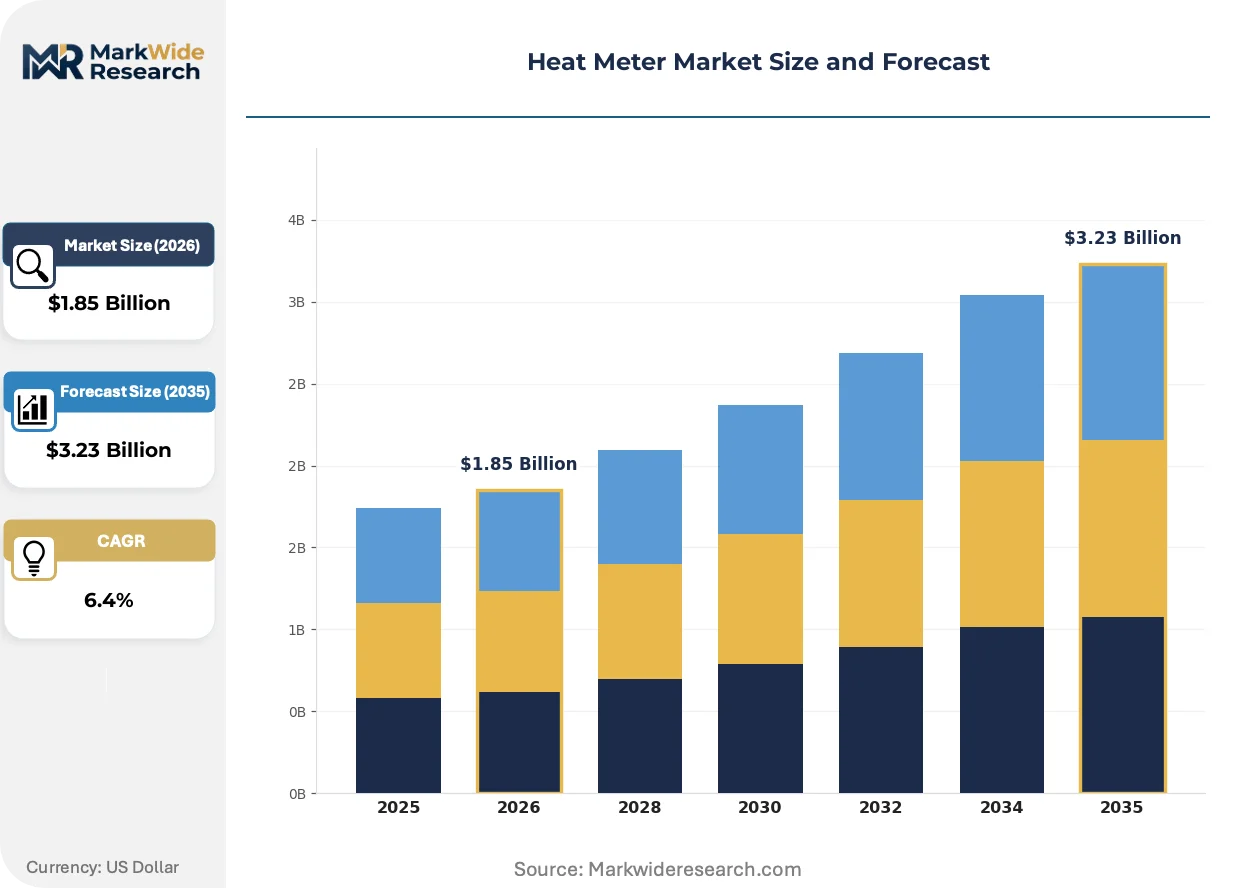
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Ultrasonic, Smart, Steam Installation Type: Wall-Mounted, Floor-Standing, Portable, Integrated End User: Residential, Commercial, Industrial, Municipal Technology: Wireless, Wired, Hybrid, IoT-Based |
| Companies Covered | Siemens, Itron, Diehl Stiftung & Co. KG, Apator, Landis+Gyr, Kamstrup, ZENNER International, Bmeters, Danfoss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Meter Market Emerging Trajectories
Digital measurement architectures are displacing electromechanical sensing cores across the installed base, compressing the technical lifespan of traditional meter designs while opening service revenue models anchored on data analytics rather than hardware replacement.
Ultrasonic transit-time sensing is virtualizing the physical measurement layer in district heating substations. Danish utilities now specify solid-state flow sensors for 90% of new connections above DN50. This shift eliminates wear-prone impellers and enables continuous diagnostic telemetry that transforms maintenance from reactive field visits to remote condition monitoring.
The EU F-Gas Regulation tightens measurement accuracy requirements for refrigerant-based heat recovery systems, forcing recalibration of certification standards. Industrial cogeneration plants in Germany and the Netherlands face compliance deadlines that accelerate meter refresh cycles. Manufacturers respond by pre-certifying ultrasonic variants to EN 1434 Category 1 across the full DN15-DN1000 range.
Building operators now bundle heat metering procurement with HVAC controls and energy management software, collapsing the traditional specification chain. Siemens and Schneider Electric leverage building automation platforms to capture meter decisions upstream of utility procurement. This consolidation concentrates buying power among facilities management consortia in Sweden and Finland, squeezing standalone meter suppliers into subsystem vendor roles.
Heat Meter Market Segmentation
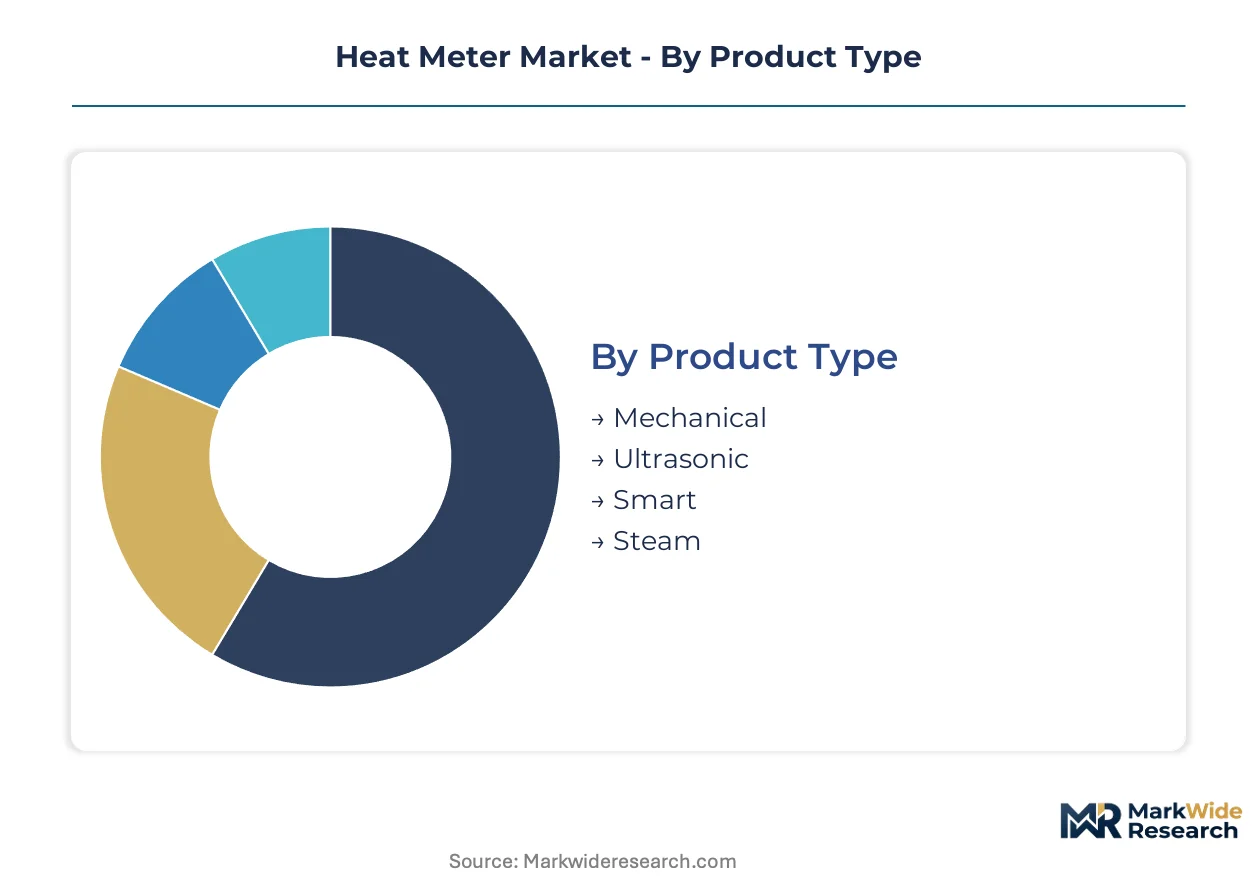
Heat meter procurement splits across four critical dimensions that determine specification priorities and margin structures. Product type defines the core sensing architecture and service revenue potential. Installation type shapes deployment economics in retrofit versus new-build contexts. End-user segmentation governs accuracy requirements and billing complexity. Technology selection determines data infrastructure investment and remote operational capabilities.
Product Type:
Mature mechanical designs coexist with emerging solid-state alternatives, creating a bifurcated procurement landscape where replacement cycles and first-install specifications diverge sharply.
- Mechanical:Impeller-based flow sensors with rotating components dominate legacy installed bases across Eastern European district heating networks. Poland and Czech Republic utilities face compressed replacement timelines as calibration intervals tighten under national implementations of the EU Energy Efficiency Directive.
- Ultrasonic:Transit-time flow measurement eliminates moving parts entirely, enabling continuous diagnostic telemetry that transforms maintenance from reactive field visits to remote condition monitoring. Danish utilities now specify solid-state sensors for 90% of new connections above DN50, driven by Denmark's heat supply regulations mandating extended calibration intervals only achievable through drift-resistant designs.
- Smart:Integrated communication modules supporting M-Bus, LoRaWAN, or NB-IoT protocols enable automated billing and leak detection analytics. German MessEG compliance requirements for individual billing in multi-tenant buildings accelerate deployment across retrofit residential stock.
- Steam:Specialized variants for industrial cogeneration and district heating plants handle saturated steam applications with paired pressure-temperature compensation. German and Dutch industrial cogeneration facilities face EU F-Gas Regulation compliance deadlines that accelerate refresh cycles.
Mechanical meters retain volume leadership in replacement markets; ultrasonic variants hold the steepest expansion curve.
Installation Type:
Deployment configuration determines labor intensity, spatial constraints, and integration complexity with existing building infrastructure.
- Wall-Mounted:Compact enclosures designed for vertical surface attachment dominate residential and light commercial retrofits where mechanical room space is constrained. German apartment buildings built 1960-1990 represent concentrated demand as MessEG mandates individual billing system installation.
- Floor-Standing:Freestanding cabinets accommodate larger flow calculators and battery assemblies for DN80-DN1000 district heating substations. Danish utility specifications favor floor-standing configurations for centralized meter rooms in multi-building developments.
- Portable:Temporary clamp-on ultrasonic sensors enable verification metering and dispute resolution without pipe interruption. Polish district heating operators deploy portable units for seasonal calibration audits under national metrology requirements.
- Integrated:Pre-fabricated substation skits combining heat exchanger, pump, and metering in single enclosures reduce field installation labor. Swedish and Finnish HVAC contractors specify integrated packages to compress construction schedules in residential new-build segments.
Wall-mounted configurations dominate residential retrofit volume; integrated solutions are gaining share fastest in Scandinavian new construction.
End User:
Accuracy requirements, billing granularity, and data analytics sophistication scale sharply across customer categories.
- Residential:Individual apartment billing drives demand for compact DN15-DN40 meters with monthly readout cycles. Germany's building efficiency renovation wave channels EU Recovery and Resilience Facility funding toward multi-tenant retrofit projects.
- Commercial:Office and retail buildings require sub-metering granularity for tenant cost allocation and HVAC optimization. Finnish facilities management consortia bundle metering procurement with building automation platforms.
- Industrial:Process heat monitoring demands EN 1434 Category 1 accuracy for large-scale heat exchange applications. German chemical and food processing plants face tightened measurement requirements under industrial emissions frameworks.
- Municipal:District heating network operators specify bulk metering at substation boundaries for network balancing and loss detection. Warsaw, Kraków, and Łódź modernization programs accelerate deployment timelines.
Residential segment retains installed base dominance; industrial applications show the most rapid specification upgrading.
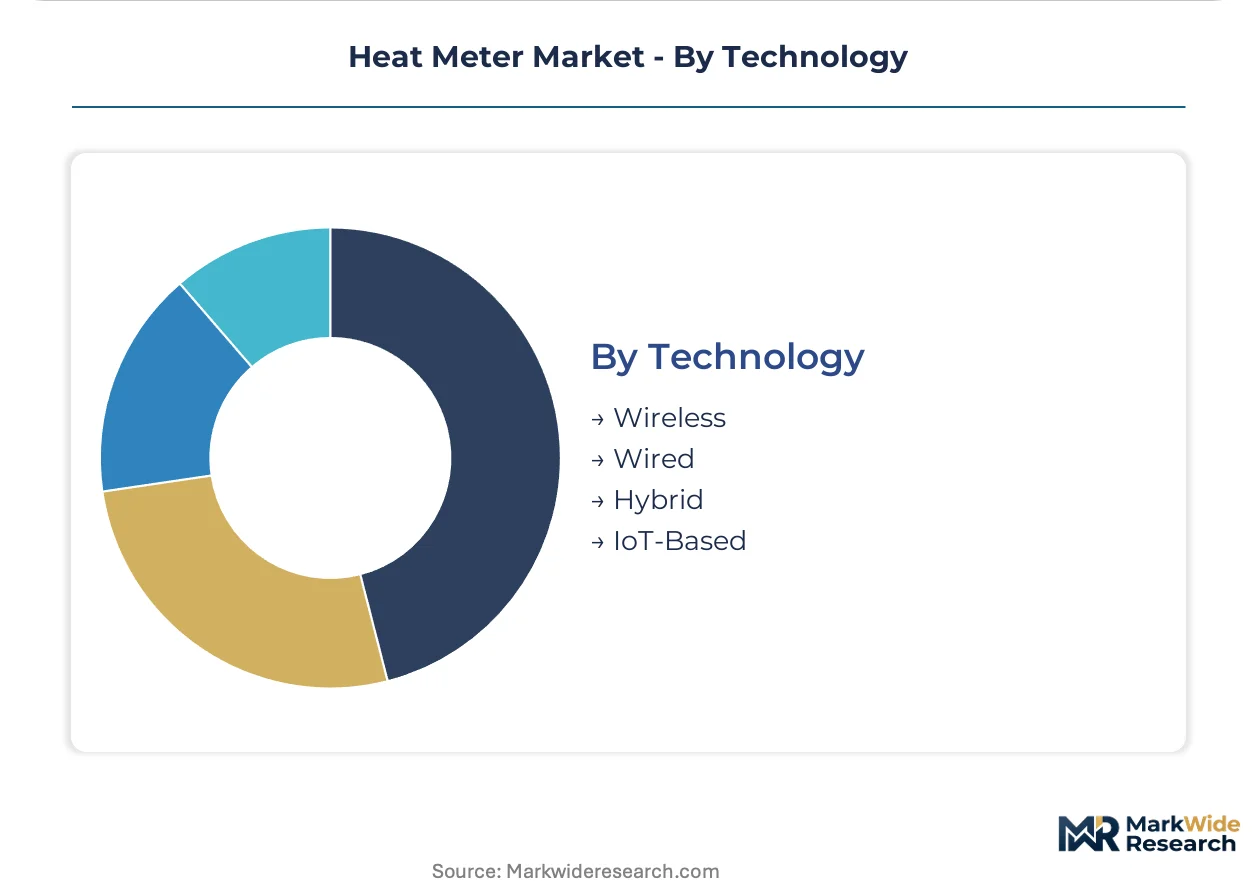
Technology:
Communication architecture selection determines operational cost structure and value-added service potential.
- Wireless:LoRaWAN and NB-IoT protocols eliminate cabling infrastructure in retrofit environments. Danish utilities specify wireless for 80% of residential deployments to avoid M-Bus wiring disruption in occupied buildings.
- Wired:M-Bus and Modbus connections persist in new construction and industrial settings where cable installation is cost-effective. German new-build regulations mandate wired infrastructure readiness for future smart grid integration.
- Hybrid:Dual-path meters with both wired and wireless capability enable phased infrastructure migration. Polish operators deploy hybrid designs to bridge proprietary 1990s-era building automation protocols.
- IoT-Based:Cloud-connected architectures with edge analytics enable predictive maintenance and demand forecasting. Swedish district heating networks pilot IoT platforms for network optimization and customer engagement services.
Wired technology retains share in new construction; IoT-based systems are climbing the fastest as cloud analytics platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German meter manufacturers supply ultrasonic and smart metering systems to district heating operators across Northern and Eastern Europe, with Denmark and Poland representing the largest export destinations for high-accuracy substation equipment.
Germany
MessEG mandates drive multi-tenant building retrofits in Berlin, Hamburg, and Munich. The Federal Office for Metrology and Accreditation enforces EN 1434 calibration intervals that sustain recurring service contracts. Industrial cogeneration clusters in North Rhine-Westphalia accelerate meter refresh cycles under tightened emissions frameworks.
Denmark
Heat supply regulations mandate extended calibration intervals achievable only through drift-resistant ultrasonic designs. Copenhagen, Aarhus, and Odense utilities specify solid-state sensors for 90% of new connections above DN50. District heating network operators pilot IoT platforms for predictive maintenance and customer engagement.
Poland
EU Recovery and Resilience Facility funding channels toward district heating modernization in Warsaw, Kraków, and Łódź. The national metrology authority enforces periodic calibration audits that sustain meter replacement demand. Eastern European manufacturing clusters retain legacy impeller production capacity for price-sensitive segments.
Netherlands
Industrial cogeneration facilities in Rotterdam and Eindhoven face EU F-Gas Regulation compliance deadlines that accelerate refresh cycles. The Dutch Emissions Authority tightens measurement accuracy requirements for refrigerant-based heat recovery systems. Port-based logistics clusters facilitate re-export of German and Danish meter systems to Belgian and French utilities.
Sweden
Facilities management consortia bundle metering procurement with building automation platforms in Stockholm, Gothenburg, and Malmö. The Swedish National Board of Housing, Building and Planning mandates individual billing readiness in new residential construction. Scandinavian residential new-build segments specify bidirectional thermal energy measurement for emerging hybrid heating systems.
Heat Meter Market Vendor Landscape
On the supply side, the industry is consolidating around specialized ultrasonic flow measurement specialists and diversified building automation conglomerates. Tiered competitive positioning separates premium-tier metrology specialists from scale-driven mechanical meter fabricators and subsystem-integrated platform vendors. Strategic archetypes include deep-specialization pure-plays, building-automation ecosystem bundlers, and volume-manufacturing conglomerates. Dominant competitive moves encompass technology licensing partnerships for IoT protocol stacks and backward integration into temperature sensor assembly production.
Among German industrial conglomerates, Siemens anchors the building-automation-bundler archetype through its integration of metering with HVAC controls and energy management software. Diehl Stiftung & Co. KG exemplifies the scale-driven manufacturing archetype across mechanical and electronic meter variants. Kamstrup occupies a specialist position within ultrasonic flow measurement for district heating networks, representing the deep-specialization pure-play model that Danish utilities favor for substation-grade accuracy requirements.
| Leading Market Players |
|---|
| Siemens |
| Itron |
| Diehl Stiftung & Co. KG |
| Apator |
| Landis+Gyr |
| Kamstrup |
| ZENNER International |
| Bmeters |
| Danfoss |
| Others |
Supply Flow & Price Mechanics
German and Danish temperature sensor assembly clusters anchor upstream supply, concentrating margin capture with metrology-certified meter manufacturers while Eastern European mechanical component fabricators compete on volume at compressed price points. This geographic split between precision sensing inputs and commodity mechanical parts creates divergent pricing power across product tiers.
Pricing Analysis
Mechanical impeller designs, ultrasonic solid-state systems, and emerging IoT-integrated smart meters occupy distinct price bands shaped by EN 1434 certification tier and after-sales service bundling. Price differentiation centers on accuracy class and calibration interval guarantees, with Category 1 certified units commanding substantial premiums over Category 3 equivalents. Cost compression in mechanical segments is intensifying because Eastern European manufacturing clusters retain excess legacy production capacity. Municipal district heating operators exhibit the highest price sensitivity due to bulk procurement volumes, while industrial cogeneration facilities prioritize measurement precision over unit economics.
Supply Chain Analysis
Copper feedstock from Chile and Zambia, semiconductor chipsets from Taiwan and South Korea, and precision temperature sensors from Germany and Denmark constitute critical upstream dependencies. Raw material volatility in copper and semiconductor inputs compresses gross margins on electronic meter variants. Single-source vulnerability concentrates in advanced flow calculator chipsets sourced from Taiwanese foundries. Distribution runs through authorized meter distributors serving district heating utilities and HVAC contractor networks across Northern and Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward facilities management consortia in Sweden and Finland, where bundled procurement of metering with building automation platforms concentrates specification influence among fewer decision-makers.
For Market Incumbents: Harden defensible positions through backward integration into temperature sensor assembly production, reducing exposure to copper and semiconductor price volatility. Deepen certification investments across the full EN 1434 Category 1 range to preempt regulatory tightening under the EU F-Gas Regulation. Channel control through long-term service contracts with Danish utilities locks in recurring revenue against emerging ultrasonic specialists. For New Entrants and Emerging Players: Establish a beachhead in Poland's EU Recovery and Resilience Facility-funded district heating modernization wave, where specification standards remain fluid and local manufacturing partnerships lower market entry barriers. Target portable and clamp-on verification metering segments, which face less entrenched competition from incumbent substation suppliers. Pursue a technical partnership route with Scandinavian HVAC contractors seeking bidirectional measurement capabilities for hybrid heat pump systems. For Investors and Strategic Acquirers: Capital is best deployed toward deep-specialization pure-plays with captive ultrasonic flow measurement IP and established utility relationships in Denmark and Germany. Long-term viability favors assets with installed base density that sustains recurring calibration and maintenance revenue. Monitor metrology certification queue lengths at German and Danish notified bodies as an inflection indicator for product launch velocity and competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Assembly | Captive temperature sensor production insulates margins from copper volatility and secures supply continuity for EN 1434 Category 1 certification. |
| IoT Protocol Licensing Partnership | LoRaWAN and NB-IoT stack integration enables predictive maintenance offerings that differentiate hardware suppliers in Danish utility tenders. |
| Metrology Certification Pre-Investment | Pre-certifying ultrasonic variants across DN15-DN1000 ranges captures EU F-Gas Regulation compliance demand from German industrial cogeneration facilities. |
| Building Automation Platform Bundling | HVAC control integration captures meter specification decisions upstream of utility procurement in Swedish facilities management consortia. |
| Polish Manufacturing Partnership | Local assembly capacity positions suppliers for EU Recovery and Resilience Facility-funded modernization programs in Warsaw and Kraków. |
Methodological Framework
Cross-validation between primary interviews with district heating network operators, HVAC contractor procurement leads, and national metrology authority officials anchors the qualitative findings against secondary data from EU Energy Efficiency Directive implementation reports, EN 1434 certification databases, and district heating association statistics. Bottom-up installed base estimates triangulate with top-down market sizing derived from utility capital expenditure disclosures and building retrofit program allocations across Germany, Denmark, and Poland.
Calibration against historical replacement cycle data and regulatory compliance deadline schedules shapes the projection framework across product type, installation configuration, end-user segment, and communication technology dimensions. CAGRs derive from segment-level growth rate convergence analysis incorporating meter deployment timelines tied to MessEG mandates, Denmark's heat supply regulations, and Poland's EU Recovery and Resilience Facility funding absorption rates. Industrial heat exchange monitoring specification upgrading and residential smart meter penetration curves constitute key forecast inputs.
Sensitivities concentrate around metrology certification queue delays at German and Danish notified bodies, copper and semiconductor input price trajectories, and the pace of facilities management consortia consolidation in Scandinavia. Forecasts reflect assumptions regarding regulatory enforcement consistency and utility procurement budget continuity. Cross-checking against district heating association deployment surveys and national energy agency building stock renovation tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Solar Panel Monitoring System Market
Energy Management
Distributed Energy Resource Management System (DERMS) Market
Energy Management
Connected Energy Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
Smart Power Management Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
Electric Sub-Meter Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Demand Response Management System Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Global Utility Asset Management Market
Energy Management
Energy Harvesting System Market
Energy Management
Thermostat Market
Energy Management
Smart Energy Solutions Market