
 APAC Energy Management Systems (EMS) Market | 2026-2036
APAC Energy Management Systems (EMS) Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Energy Management Systems (EMS) Market Outlook
Multi-source procurement of EMS components is expanding across APAC industrial zones as facility operators diversify away from single-vendor dependencies. Schneider Electric SE leverages its integrated software-hardware stack to anchor large-scale deployments across Southeast Asian manufacturing hubs. Siemens AG competes through deep specialization in AI-driven analytics layers for process industries. Honeywell International Inc. sustains channel control via its established building automation distribution networks across the region.
Energy Management Systems encompass software platforms, sensor networks, and control hardware that monitor, analyze, and optimize electricity, thermal, and mechanical energy flows within facilities, typically operating through real-time data acquisition at sub-15-minute intervals and automated load dispatch algorithms. Their primary commercial purpose is to reduce kilowatt-hour consumption, flatten demand peaks, and align operational schedules with tariff structures or grid signals. Software Solutions command the dominant share of value pools as recurring license and SaaS margins outpace hardware commoditization, while Cloud Platforms represent the fastest-expanding delivery mode as APAC enterprises shed on-premise infrastructure burdens. Industrial Processes applications lead absolute spending due to continuous-load facilities seeking measurable efficiency gains, though Data Centers is displacing traditional building automation as the most contested vertical given hyperscaler expansion across Singapore, Sydney, and Tokyo.
China's MEE enforces escalating energy intensity audits for designated industrial consumers, while India's BEE mandates consumption disclosure thresholds that directly stimulate EMS procurement for compliance filing. Japan's METI subsidizes factory energy diagnostics that embed EMS vendors into manufacturing upgrade cycles. Stakeholders must monitor how ASEAN member states transpose national building codes into mandatory efficiency standards, as this regulatory wave will determine which technology architectures achieve regional scale.
Market Dynamics
China's dual carbon goals and India's Perform Achieve and Trade scheme are tightening compliance thresholds, forcing industrial facilities across the APAC region to accelerate EMS deployment or face operational penalties and restricted market access.
Growth Catalysts
- China's MEE energy intensity audits:Designated industrial consumers must install monitoring infrastructure to meet escalating audit requirements, directly stimulating hardware and software procurement.
- Japan's METI factory diagnostics subsidies:Manufacturing upgrade cycles embed EMS vendors into facility assessments, creating a pipeline of integrated retrofit projects.
- Data center hyperscaler expansion:Singapore, Sydney, and Tokyo facilities demand sub-15-minute interval monitoring to manage thermal loads and electricity tariffs.
Market Restraints
- Sensor network hardware commoditization:Margins on edge devices compress as Chinese component suppliers flood regional markets with undifferentiated IoT hardware.
- Legacy SCADA integration friction:Brownfield industrial sites face protocol incompatibilities between 1990s-era control systems and modern cloud-native EMS platforms.
- Semiconductor supply concentration:Taiwan and South Korea foundry bottlenecks delay delivery of specialized industrial control chips required for real-time load dispatch.
Strategic Opportunities
- ASEAN building code transposition:Member states converting voluntary efficiency guidelines into mandatory standards will unlock greenfield EMS installations across commercial real estate.
- AI-driven predictive maintenance convergence:Machine learning analytics layers integrated with thermal monitoring create premium service tiers for process industries.
- Vietnam and Indonesia industrial zones:Underpenetrated manufacturing corridors offer first-mover positioning before regulatory mandates replicate Chinese compliance models.
Industry Challenges
- Industrial IoT cybersecurity certification:Facilities struggle to achieve IEC 62443 compliance for networked energy control systems, extending sales cycles by 6-12 months.
- Cloud-to-edge integration complexity:Engineering teams lack expertise in harmonizing SaaS analytics platforms with on-premise legacy control hardware.
- Cross-border data residency requirements:China's data localization laws and India's draft data protection rules fragment cloud platform architectures across national boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Energy Management Systems (EMS) Market |
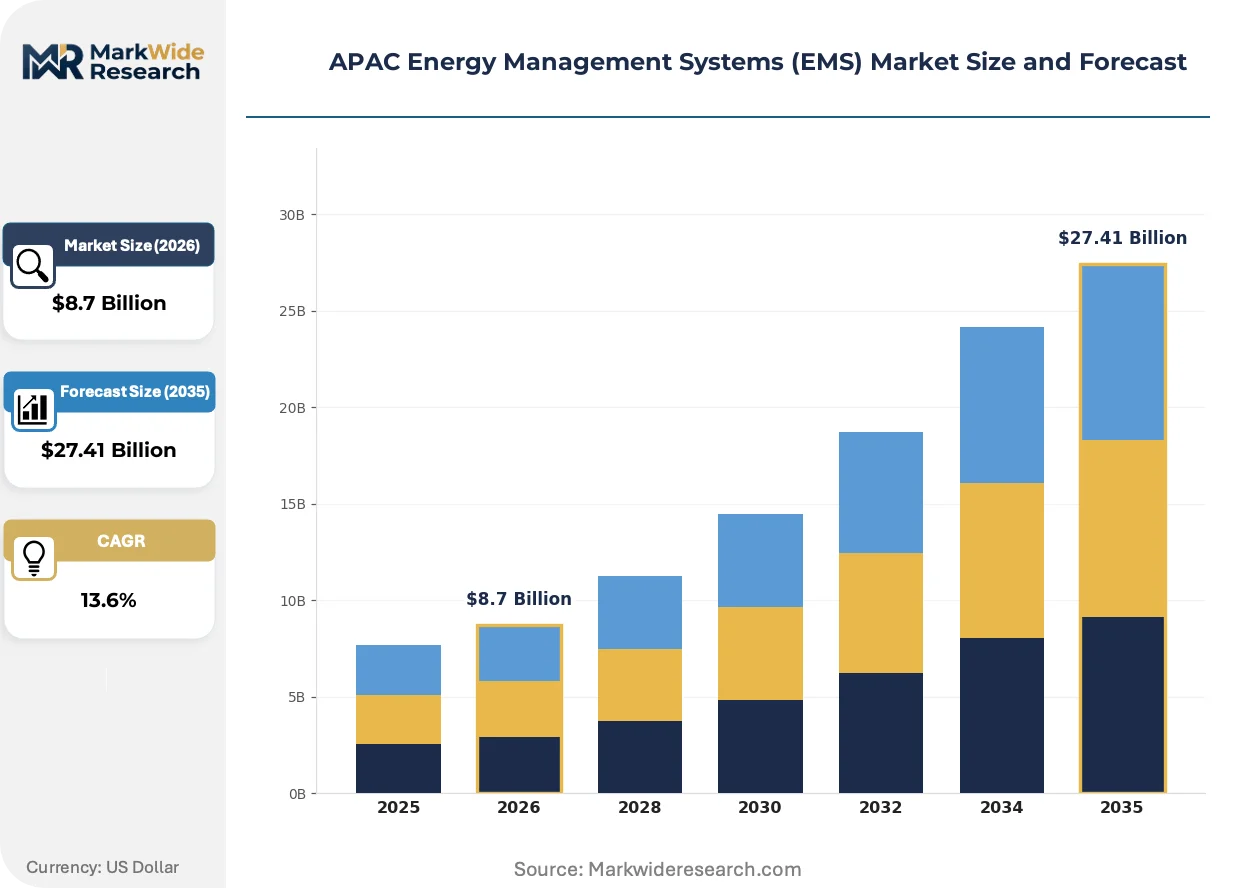
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Devices, Integrated Systems, Cloud Platforms Application: Building Automation, Industrial Processes, Data Centers, Utilities Management End User: Commercial Facilities, Manufacturing Plants, Residential Units, Government Institutions Technology: IoT Integration, AI Analytics, Big Data Processing, Renewable Energy Interfaces |
| Companies Covered | Schneider Electric SE, Siemens AG, Honeywell International Inc., ABB Ltd., General Electric Company, Johnson Controls International PLC, Rockwell Automation Inc., Eaton Corporation PLC, IBM Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Energy Management Systems (EMS) Market Strategic Shifts
Digital twin technology is reshaping how APAC industrial operators simulate energy flows before physical deployment, compressing commissioning timelines and reducing retrofit risk.
Edge AI inference engines embedded directly within sensor networks are automating millisecond-level load balancing decisions without cloud latency. Semiconductor foundries in Taiwan and South Korea prioritize these chips for data center and process industry buyers. Real-time optimization is automating demand response participation that previously required manual operator intervention.
India's BEE consumption disclosure mandates now require designated industries to file verified energy intensity reports, creating audit-trail requirements that only integrated EMS platforms satisfy. Steel and cement producers face the steepest compliance burdens. Facility managers are responding by consolidating previously siloed metering systems into unified software architectures.
Subscription-based SaaS pricing is displacing perpetual license models across mid-market manufacturing facilities. Channel partners in Southeast Asia now lead with recurring revenue structures rather than upfront hardware sales. Procurement teams in Thailand and Malaysia increasingly evaluate total cost of ownership over five-year horizons rather than initial capital expenditure.
APAC Energy Management Systems (EMS) Market Segmentation
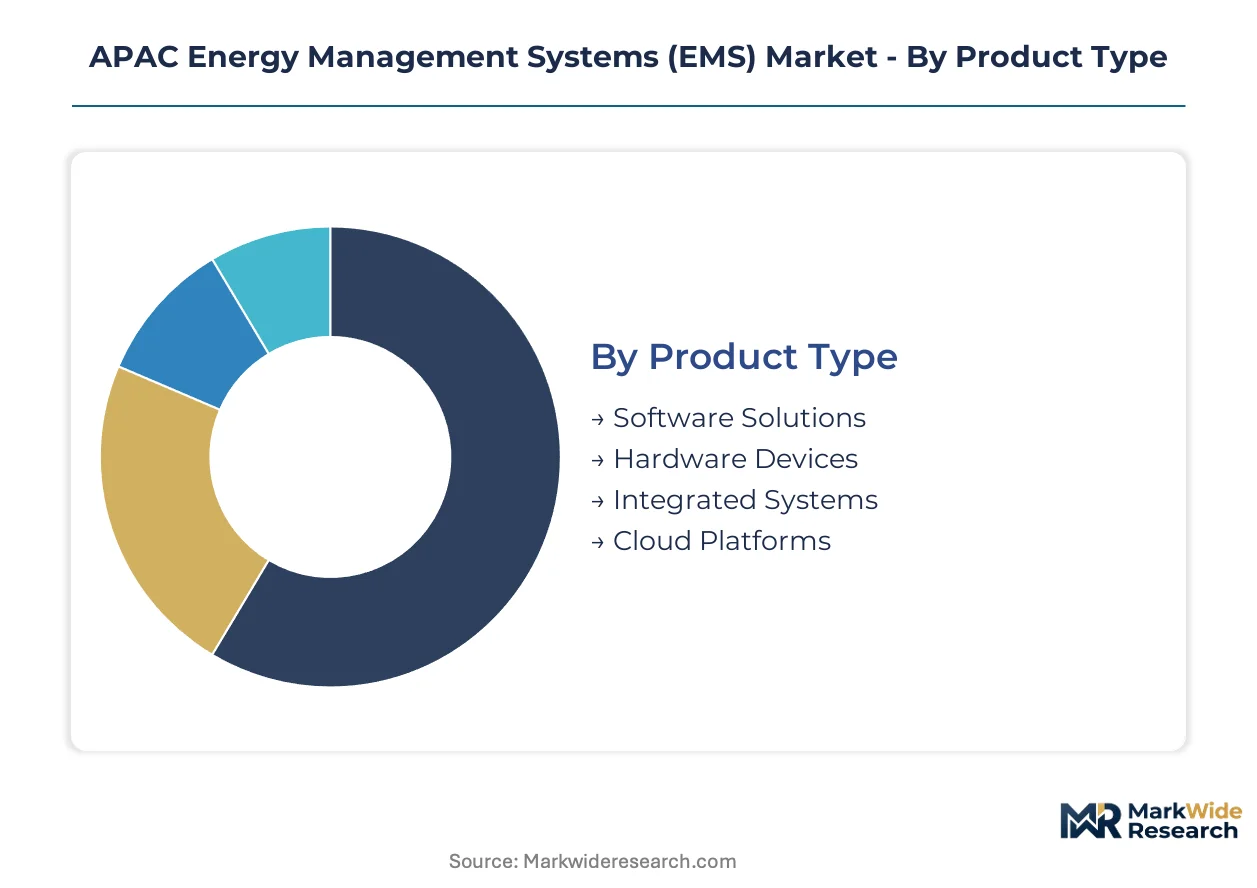
APAC Energy Management Systems fragment across four critical dimensions that determine procurement patterns and vendor positioning. Product architecture choices between software-heavy and integrated hardware stacks dictate margin structures. Application focus separates compliance-driven industrial deployments from optimization-seeking commercial facilities.
Product Type:
Volume concentrates in commoditized hardware while premium value pools accrue to software and cloud delivery modes.
- Software Solutions:Platforms delivering real-time analytics, automated load dispatch algorithms, and SaaS licensing models capture recurring revenue streams. Manufacturing plants across China's Jiangsu and Zhejiang provinces prioritize these for MEE audit compliance and carbon intensity reporting.
- Cloud Platforms:Browser-accessible architectures with API integrations to utility tariff systems and grid demand response programs. Data center operators in Singapore and Tokyo drive procurement here to shed on-premise infrastructure burdens while maintaining sub-15-minute interval monitoring.
- Hardware Devices:Sensor networks, edge controllers, and metering infrastructure with compressed margins from Chinese component supplier competition.
- Integrated Systems:Bundled software-hardware deployments requiring specialized commissioning for brownfield industrial retrofits.
Mature deployment sits with Hardware Devices. Newer deployment is concentrated in Cloud Platforms.
Application:
End-use differentiation separates continuous-load process industries from intermittent-load commercial buildings.
- Industrial Processes:Steel, cement, and chemical facilities with 24/7 thermal and electrical load profiles. India's BEE consumption disclosure mandates force steel producers in Odisha and cement plants in Rajasthan toward unified metering architectures.
- Data Centers:Hyperscaler facilities managing PUE optimization and thermal load balancing. Singapore's capacity-constrained grid drives sub-15-minute monitoring adoption here.
- Building Automation:Commercial real estate EMS for HVAC and lighting control with slower upgrade cycles.
- Utilities Management:Grid-edge EMS for distribution network optimization and demand response aggregation.
Industrial Processes carry the deepest installed base. Data Centers are climbing the fastest as hyperscaler expansion accelerates.
End User:
Procurement sophistication varies sharply between compliance-driven institutional buyers and cost-focused commercial operators.
- Manufacturing Plants:Continuous-process facilities with dedicated energy managers and direct regulatory exposure. China's designated industrial consumers under MEE audits anchor hardware and software procurement volumes.
- Commercial Facilities:Office towers and retail complexes seeking tariff optimization and green building certifications. Bangkok and Kuala Lumpur channel partners lead with SaaS-first pitches here.
- Government Institutions:Public buildings with procurement constrained by fiscal year budgeting and tender processes.
- Residential Units:Smart home EMS with limited penetration outside premium developments in Tokyo and Sydney.
Manufacturing Plants dominate absolute spending. Commercial Facilities represent the steepest expansion trajectory as ASEAN building codes harden.
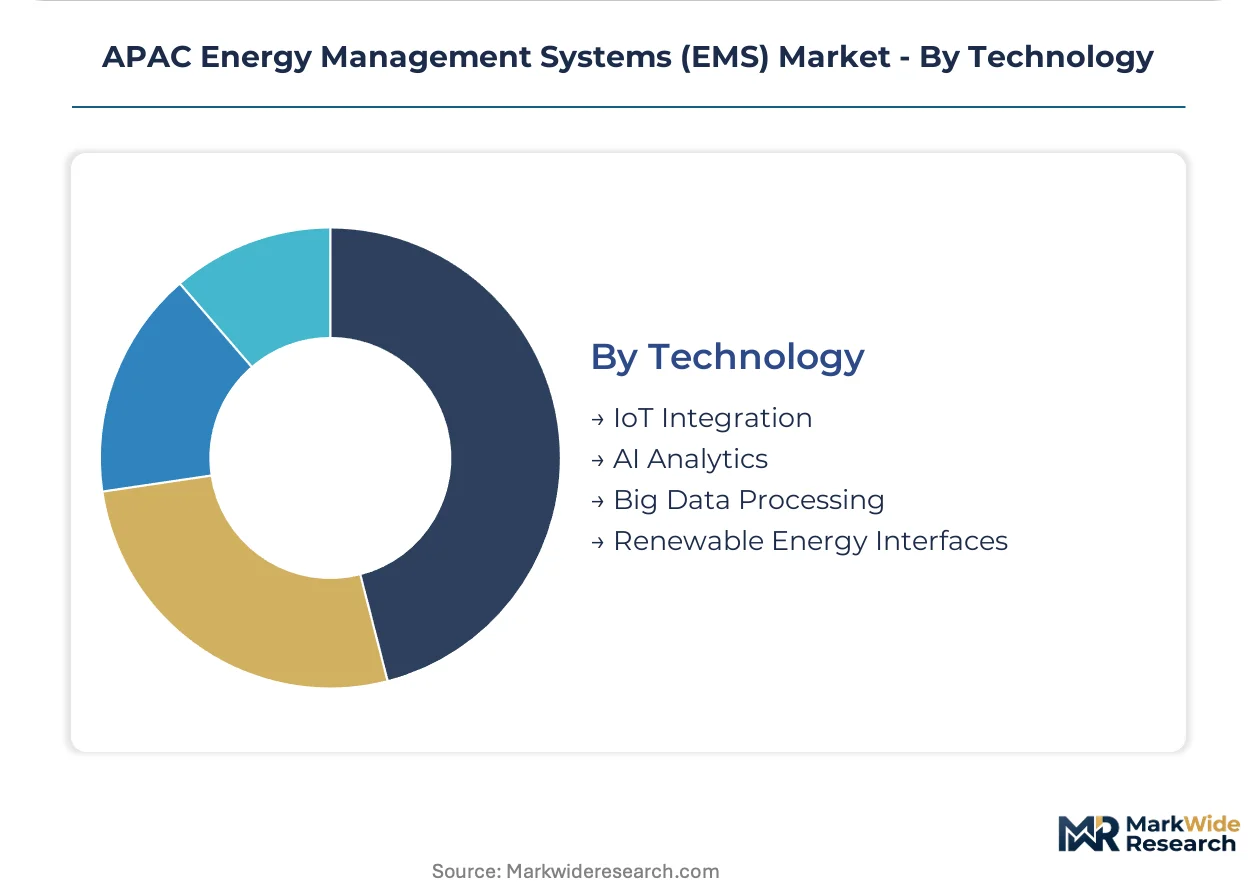
Technology:
Capability layering separates baseline connectivity from predictive optimization functions.
- AI Analytics:Machine learning models for predictive maintenance, anomaly detection, and load forecasting. Process industries in Japan's METI-subsidized diagnostic programs embed these for premium service tiers.
- IoT Integration:Sensor-to-cloud connectivity protocols enabling real-time data acquisition. Vietnamese and Indonesian industrial zones deploy these as first-wave infrastructure.
- Big Data Processing:Historical consumption pattern analysis for tariff structure optimization and capital planning.
- Renewable Energy Interfaces:EMS-to-solar and EMS-to-storage control for behind-the-meter asset dispatch.
IoT Integration commands the broadest deployment. AI Analytics is gaining share fastest as semiconductor supply for edge inference chips stabilizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Energy Management Systems concentrates in China's eastern manufacturing corridor, where Jiangsu, Zhejiang, and Guangdong provinces anchor procurement volumes for MEE compliance. India's designated industrial consumers and Japan's subsidized factory diagnostics create parallel growth vectors across the region.
China
Designated industrial consumers under MEE energy intensity audits drive hardware and software procurement across steel, cement, and chemical facilities. The country's dual carbon goals mandate escalating compliance thresholds for energy consumption disclosure. Manufacturing clusters in Jiangsu and Zhejiang provinces lead deployment as facility operators unify previously siloed metering systems.
India
Steel producers in Odisha and cement plants in Rajasthan face the steepest BEE consumption disclosure burdens, forcing unified metering architectures. The Perform Achieve and Trade scheme tightens compliance thresholds for industrial energy intensity. Facility managers in these states consolidate legacy systems to satisfy audit-trail requirements for verified reporting.
Japan
METI factory energy diagnostics embed EMS vendors into manufacturing upgrade cycles through subsidized assessments. Process industries leverage these programs for AI-driven predictive maintenance integration. Industrial zones around Nagoya and Osaka anchor procurement as semiconductor and automotive facilities prioritize thermal load optimization.
Singapore
Hyperscaler data center expansion drives sub-15-minute interval monitoring adoption for PUE optimization and grid demand response. The city-state's capacity-constrained electricity infrastructure forces thermal load balancing precision. Operators prioritize cloud-native platforms to shed on-premise infrastructure burdens while maintaining real-time visibility.
Vietnam
Underpenetrated industrial zones in northern and southern manufacturing corridors offer first-mover positioning before regulatory mandates replicate Chinese compliance models. IoT integration deployments serve as first-wave infrastructure for foreign-invested electronics and textile facilities. Provinces surrounding Hanoi and Ho Chi Minh City concentrate early EMS adoption.
APAC Energy Management Systems (EMS) Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors integrate AI analytics layers with legacy control hardware to overcome brownfield friction. The vendor base splits between integrated software-hardware stacks and specialized analytics providers, creating tiered positioning across process industries and commercial facilities. Three archetypes anchor competition: diversified industrial conglomerates with building automation heritage, pure-play software vendors with cloud-native architectures, and component suppliers pushing upstream into system integration. Geographic expansion into Vietnam and Indonesia accompanies portfolio diversification into predictive maintenance services.
Within the integrated systems tier, Schneider Electric SE and Siemens AG exemplify divergent approaches to APAC market penetration. Schneider leverages its software-hardware stack to anchor large-scale deployments across Southeast Asian manufacturing hubs. Siemens competes through deep specialization in AI-driven analytics layers for process industries. Honeywell International Inc. occupies a distinct position via established building automation distribution networks that sustain channel control across the region.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| Honeywell International Inc. |
| ABB Ltd. |
| General Electric Company |
| Johnson Controls International PLC |
| Rockwell Automation Inc. |
| Eaton Corporation PLC |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Semiconductor foundry capacity for industrial control chips flows from Taiwan and South Korea through tiered EMS pricing structures, where edge AI inference engines command premium positioning against commoditized sensor hardware from Chinese component suppliers.
Pricing Analysis
Volume concentrates in hardware devices with compressed margins, while software solutions and cloud platforms capture premium recurring revenue through SaaS licensing models. Price differentiation separates AI-enabled predictive analytics tiers from baseline monitoring packages, with certification levels for IEC 62443 cybersecurity compliance adding further stratification. Pricing pressure stems from Chinese IoT hardware suppliers flooding regional markets with undifferentiated edge devices. Manufacturing plants in China's Jiangsu province show lowest price sensitivity due to MEE compliance mandates, while commercial facilities in Bangkok and Kuala Lumpur prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea foundries producing specialized industrial control chips for real-time load dispatch algorithms. The EMS supply chain draws from Chinese component suppliers for sensor networks and edge controllers, Japanese manufacturers for precision metering infrastructure, and German engineering houses for SCADA integration modules. Tariff exposure on semiconductor imports from Taiwan creates procurement risk for vendors serving data center operators in Singapore. Distribution runs through established building automation channel partners in Southeast Asia and direct enterprise sales teams for large industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry bottlenecks in Taiwan and South Korea constrain specialized chip supply, propping pricing power for vendors with secured semiconductor allocation while compressing margins for hardware-dependent competitors.
For Market Incumbents: To counter cloud-native software vendors displacing traditional integrated stacks, incumbents should deepen backward integration into edge AI chip design partnerships with Taiwan foundries and reinforce channel control through certified installer networks across Vietnam's northern industrial zones. For New Entrants and Emerging Players: The price-point gap between premium AI-analytics tiers and economy IoT-monitoring packages opens entry paths for mid-market SaaS vendors targeting Thailand and Malaysia commercial facilities with subscription-first positioning and rapid-deployment commissioning models. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed industrial software assets in Japan's METI-subsidized diagnostic ecosystem, where factory upgrade program dependencies create sticky revenue streams. Long-term viability hinges on cloud-to-edge integration capabilities that transcend national data residency fragmentation. The signal to watch is ASEAN member state transposition of voluntary building codes into mandatory efficiency standards.| Strategic Initiative | Industry Significance |
|---|---|
| AI Analytics Layer Integration | Machine learning predictive maintenance creates premium service tiers for Japan's METI-subsidized steel and cement facilities. |
| Cloud Platform Localization | Data residency-compliant architectures unlock procurement from China's designated industrial consumers under MEE audit mandates. |
| Edge AI Chip Partnership | Taiwan foundry allocation agreements secure supply for sub-15-minute interval monitoring in Singapore data centers. |
| Cybersecurity Certification Investment | IEC 62443 compliance accelerates sales cycles for networked energy control systems in brownfield industrial retrofits. |
| Vietnam Industrial Zone Expansion | First-mover positioning in underpenetrated manufacturing corridors before regulatory mandates replicate Chinese compliance models. |
Study Parameters
Independent corroboration across energy management software vendors, industrial facility operators, and semiconductor component suppliers underwrites the qualitative findings. Primary interviews engaged plant engineers at steel and cement facilities in Odisha and Rajasthan, procurement leads at hyperscaler data centers in Singapore and Tokyo, channel partners across Bangkok and Kuala Lumpur, and grid planning officers at ASEAN utilities. Secondary validation drew from China's MEE audit disclosure databases, India's BEE consumption reporting filings, Japan's METI subsidy program records, and customs data on industrial control chip imports. Bottom-up facility-level deployment estimates triangulated against top-down vendor revenue aggregation.
Rate-of-change decomposition separates baseline energy intensity trends from regulatory shock effects and technology substitution patterns across the projection horizon. Segmentation dimensions modeled include product architecture, application vertical, end-user procurement sophistication, and technology capability layering. CAGRs derive from installed base evolution, replacement cycle compression, and greenfield penetration rates in underpenetrated manufacturing corridors. Forecast inputs incorporate China's dual carbon goal compliance trajectories, India's Perform Achieve and Trade scheme expansion scope, and hyperscaler data center capex pipelines across Sydney, Singapore, and Tokyo.
Underlying measurement precision varies by segment; cloud platform deployments carry tighter precision than hardware device volumes due to disclosed vendor recurring revenue streams. Forecasts reflect assumptions on regulatory enforcement intensity, semiconductor supply normalization, and cross-border data flow policy stability. Deviation in ASEAN building code transposition timing or Taiwan foundry capacity allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Microgrid Control System Market
Energy Management
Energy Harvesting System Market
Energy Management
Brazil Energy Sector Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Heat Meter Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Smart Energy Solutions Market
Energy Management
Connected Energy Market
Energy Management
Global Utility Asset Management Market
Energy Management
Germany Demand Response Management Systems Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Energy Management Market
Energy Management
Energy ESO Market
Energy Management
Thermostat Market
Energy Management
Energy Security Market