
 Residential Demand Response Management Systems Market | 2026-2036
Residential Demand Response Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Demand Response Management Systems Market Analytics
Utility-direct-to-homeowner channel strategy is fragmenting as competitive retail energy providers and technology vendors build parallel access routes to residential endpoints. Schneider Electric leverages its EcoStruxure platform to anchor comprehensive home energy orchestration across multiple continents. Siemens competes through hardware-software integration in grid-edge automation, while Honeywell International specializes in thermostat-centric demand response with deep HVAC system connectivity.
Residential Demand Response Management Systems coordinate distributed energy assets through automated control signals to modulate household electricity consumption during grid stress events, typically operating via 15-minute to 1-hour dispatch intervals with telemetry refresh rates under 5 seconds. These systems primarily serve peak load reduction and frequency regulation objectives for grid operators and utilities seeking alternatives to capital-intensive generation capacity. Smart Thermostats dominate residential enrollment due to low installation friction and consumer familiarity, while Energy Management Systems capture expanding margin pools as whole-home electrification raises complexity. Zigbee technology leads device-level communication for its mesh reliability, though Wi-Fi direct connections gain ground where broadband infrastructure already exists.
FERC Order 2222 in the United States restructures market access rules for aggregated residential resources, while state-level public utility commissions in California, Texas, and New York set interconnection standards and compensation frameworks that directly shape platform economics. The EPA's ENERGY STAR certification requirements for smart thermostats influence product design specifications and consumer eligibility for utility rebate programs. Stakeholders must monitor evolving state regulatory proceedings on data privacy and cybersecurity standards for home energy devices, as compliance thresholds will determine market access for new entrants.
Market Dynamics
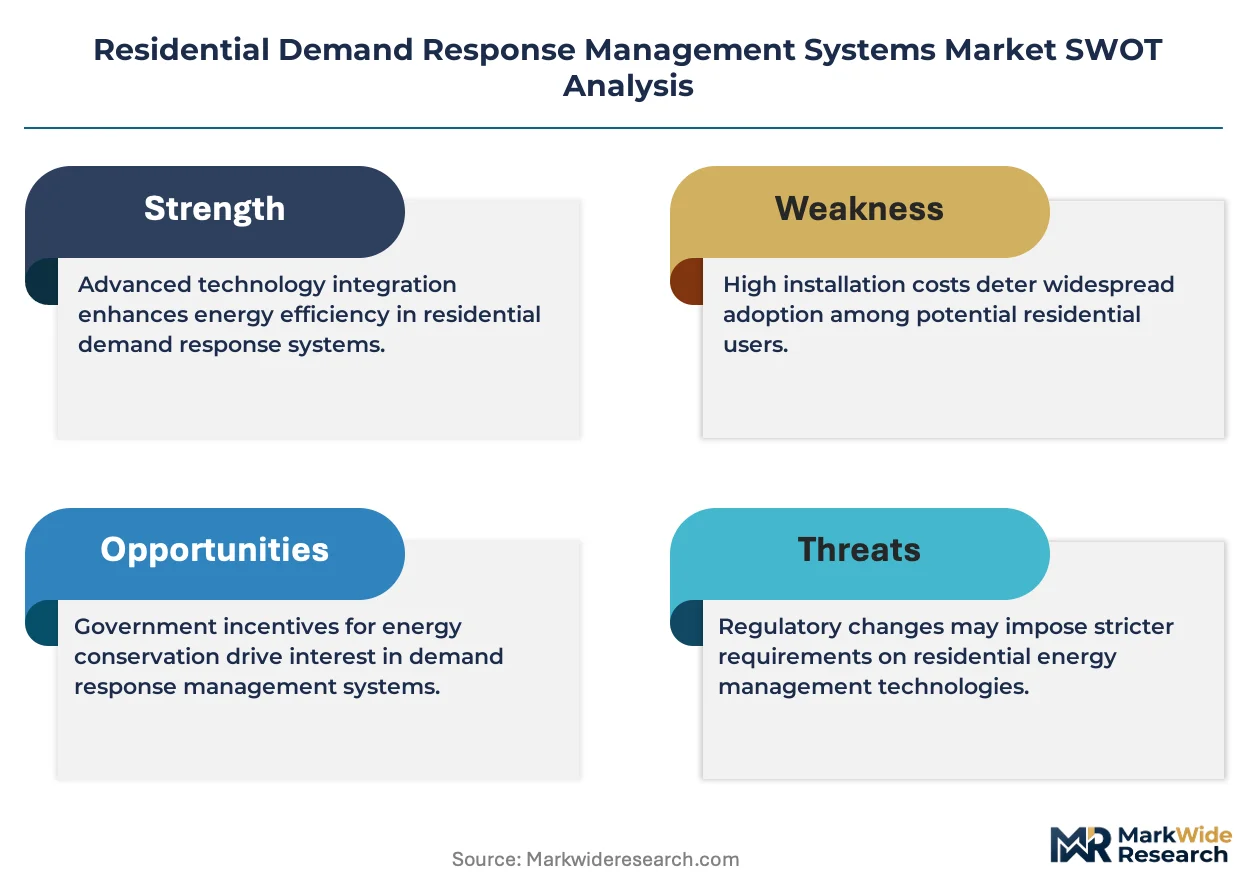
FERC Order 2222 is restructuring wholesale market access rules for aggregated residential energy resources, forcing platform providers to rebuild their technical architectures around dispatchable asset pools rather than simple load curtailment.
Growth Catalysts
- Grid Modernization Mandates:State public utility commissions in California, Texas, and New York require utilities to meet peak reduction targets through automated demand response, creating procurement quotas for residential platforms.
- Whole-Home Electrification:Heat pump and EV charger penetration is expanding the controllable load footprint per household, raising the economic value of coordinated energy management systems.
- Wholesale Market Participation:ISOs and RTOs are opening frequency regulation markets to aggregated distributed energy resources, enabling new revenue streams beyond traditional peak shaving.
Market Restraints
- Interoperability Friction:Fragmented communication protocols between Zigbee, Wi-Fi, and proprietary utility networks force vendors to maintain multiple hardware SKUs, raising production complexity.
- Consumer Acquisition Costs:Utility rebate programs vary by state jurisdiction, requiring parallel enrollment workflows that lengthen sales cycles and inflate customer acquisition spend.
- Cybersecurity Compliance Burden:Emerging state-level data privacy standards for home energy devices impose certification timelines that delay product launches by 6-12 months.
Strategic Opportunities
- Virtual Power Plant Aggregation:Battery storage plus solar PV plus flexible load orchestration creates higher-value resource stacks than thermostat-only programs, capturing margin pools in wholesale capacity markets.
- Retail Energy Provider Channel:Competitive electricity retailers in deregulated states seek white-label demand response platforms to differentiate commodity offerings and improve customer retention metrics.
- Time-of-Use Rate Alignment:Dynamic pricing pilots by utilities create immediate payback visibility for homeowners, accelerating voluntary enrollment compared to traditional incentive structures.
Industry Challenges
- Telemetry Latency Requirements:Grid operators now mandate sub-5-second signal response times for frequency regulation participation, forcing hardware refreshes across installed thermostat bases.
- Installer Network Scaling:Whole-home energy management systems require certified electrical contractor deployment, creating bottlenecks as electrification timelines compress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Demand Response Management Systems Market |
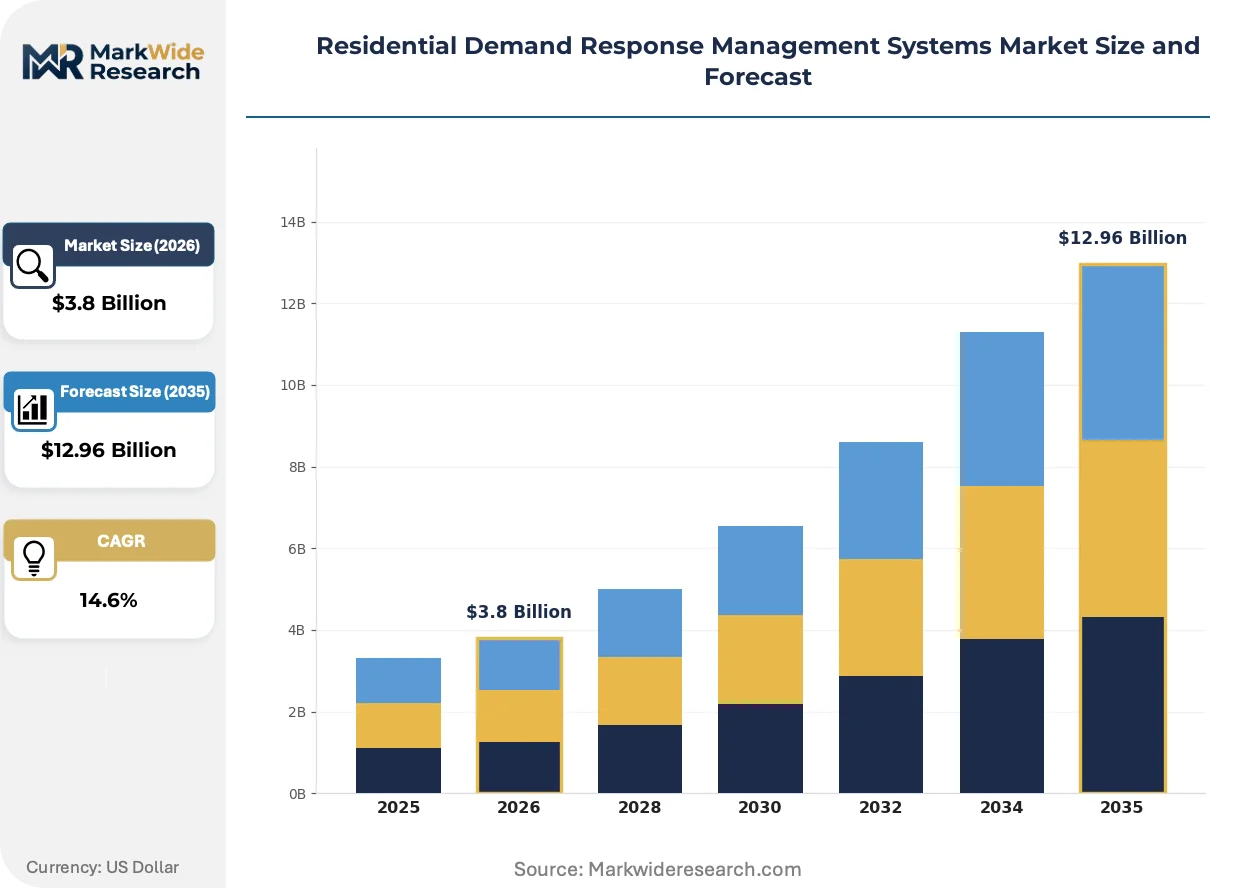
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostats, Energy Management Systems, Home Automation Devices, Load Control Switches Technology: Wireless Communication, Zigbee, Z-Wave, Wi-Fi End User: Homeowners, Property Managers, Utility Providers, Energy Consultants Application: Peak Load Shaving, Energy Usage Optimization, Real-Time Monitoring, Ancillary Services |
| Companies Covered | Schneider Electric, Siemens, ABB, Honeywell International, General Electric, Eaton, Johnson Controls, Itron, Alarm.com Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Demand Response Management Systems Market Evolving Landscape
Edge computing architectures are migrating control logic from cloud data centers into home energy gateways, reducing latency and enabling real-time optimization of multiple asset classes simultaneously.
Artificial intelligence-driven load forecasting is digitizing how platforms predict household consumption patterns, enabling predictive pre-cooling and pre-heating strategies that maximize comfort during demand response events. Utilities in California and Texas are deploying these algorithms across enrolled populations, compressing the operational gap between manual thermostat programs and fully automated home energy orchestration.
The EPA's ENERGY STAR certification requirements for smart thermostats are tightening product specifications around connectivity standards and data reporting granularity. Manufacturers must now demonstrate interoperability with utility back-end systems to qualify for rebate eligibility, forcing hardware redesigns that prioritize open APIs over proprietary ecosystems. This regulatory pressure is most acute in California, where investor-owned utilities have made ENERGY STAR compliance a mandatory procurement filter.
Homeowners are consolidating energy decisions under single-platform dashboards rather than managing discrete utility programs, channel apps, and manufacturer portals separately. This behavioral shift is disrupting the traditional utility-direct enrollment model, with technology vendors capturing customer relationships that previously resided with electricity providers. Texas retail energy markets show this pattern most clearly, where competitive providers now license white-label platforms rather than building proprietary demand response infrastructure.
Residential Demand Response Management Systems Market Segmentation
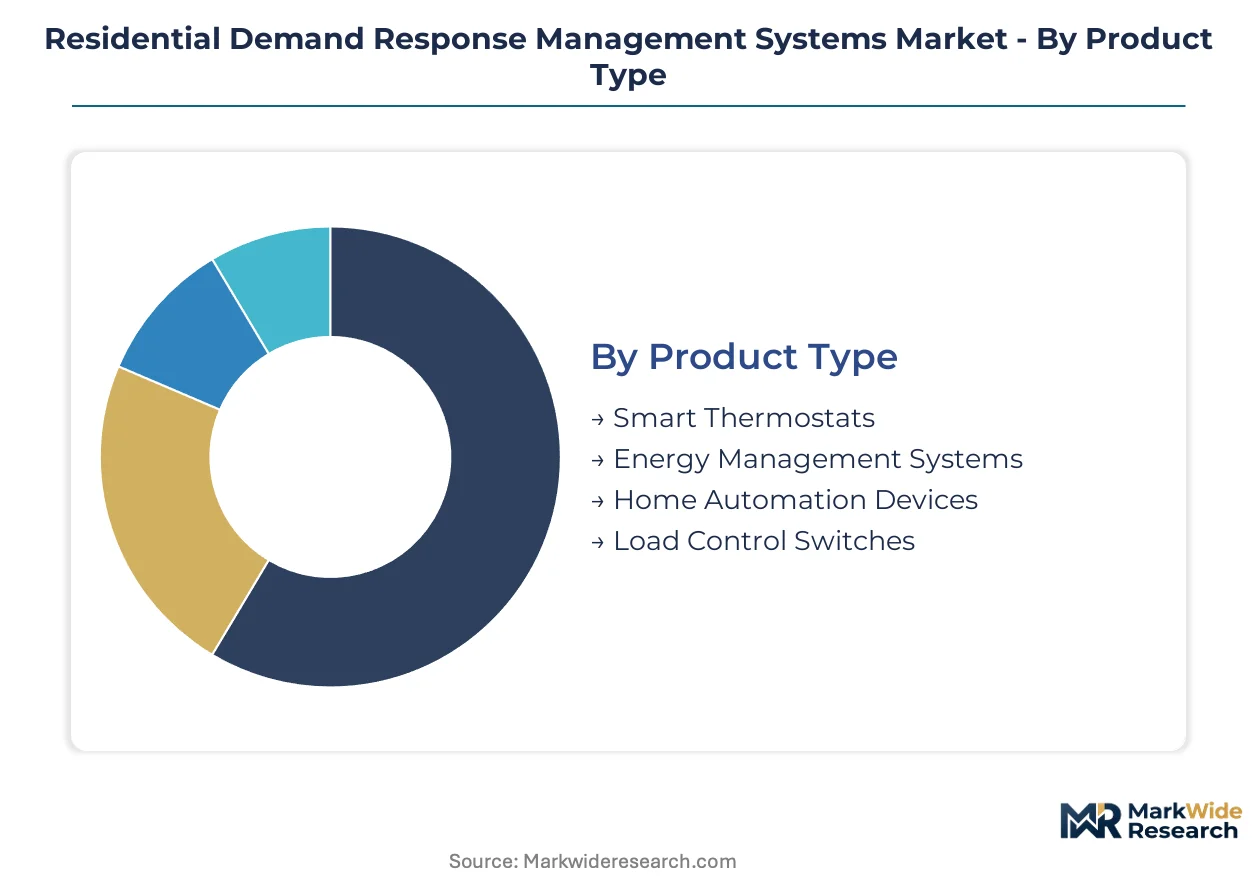
Segmentation in residential demand response reveals how hardware form factors, communication protocols, and customer access routes determine platform economics. Each dimension carries distinct margin profiles and deployment friction that shape vendor strategy and utility procurement priorities.
Product Type:
Cost tier differentiation separates mass-market hardware from integrated orchestration platforms, with installation complexity and revenue per endpoint varying by an order of magnitude.
- Smart Thermostats:Standalone temperature control units with embedded communication modules enable rapid enrollment through retail channels. Demand concentrates in California, Texas, and New York where utility rebate programs lower consumer acquisition costs. Low installation friction drives the highest enrollment volumes despite thinner margins per endpoint.
- Energy Management Systems:Whole-home orchestration platforms coordinate multiple asset classes through centralized gateways. Property managers in multifamily housing portfolios represent the fastest-expanding customer base as electrification raises operational complexity. These systems capture premium pricing through HVAC, EV charger, and battery storage integration.
- Home Automation Devices:Lighting and appliance controllers extend demand response into discretionary loads.
- Load Control Switches:Direct relay devices interrupt power to water heaters and pool pumps during grid events.
Smart Thermostats command the established base. The steepest expansion runs through Energy Management Systems.
Technology:
Communication protocol selection determines mesh reliability, latency performance, and interoperability with legacy utility infrastructure across deployment contexts.
- Wireless Communication:Broad category encompassing radio-frequency and cellular backhaul for remote telemetry. Utility providers in Texas deploy cellular-enabled switches where broadband penetration remains uneven.
- Zigbee:Mesh networking standard with self-healing topology and sub-100ms local response times. Zigbee dominates thermostat-to-gateway connections in California investor-owned utility territories where grid operators mandate sub-5-second telemetry refresh rates.
- Z-Wave:Sub-GHz proprietary protocol optimized for residential device density and low power consumption. Z-Wave captures share in home automation ecosystems where interoperability with security systems drives purchasing decisions.
- Wi-Fi:Direct IP connectivity leveraging existing residential broadband infrastructure. Wi-Fi gains ground in urban deployments where router density eliminates mesh latency concerns and cloud-based optimization reduces gateway hardware costs.
Zigbee holds the installed base advantage. Wi-Fi is climbing the fastest as broadband infrastructure deepens.
End User:
Customer type segmentation maps to decision-making authority, contract scale, and technical sophistication requirements that shape sales motion design.
- Homeowners:Individual retail purchasers responding to rebate incentives and time-of-use rate signals. Enrollment friction varies by state jurisdiction, with California's streamlined utility-direct programs achieving highest conversion rates.
- Property Managers:Multifamily housing operators managing centralized building systems across unit portfolios. Property managers in Texas deregulated markets seek white-label platforms to differentiate rental offerings and reduce operating expense volatility.
- Utility Providers:Regulated and competitive electricity retailers procuring demand response capacity to meet resource adequacy requirements.
- Energy Consultants:Third-party advisors designing custom load management strategies for high-consumption residential clients.
Utility Providers anchor procurement volume. Property Managers are gaining share fastest as multifamily electrification accelerates.
Application:
Use case segmentation distinguishes between grid services revenue streams and consumer-facing value propositions that determine platform architecture priorities.
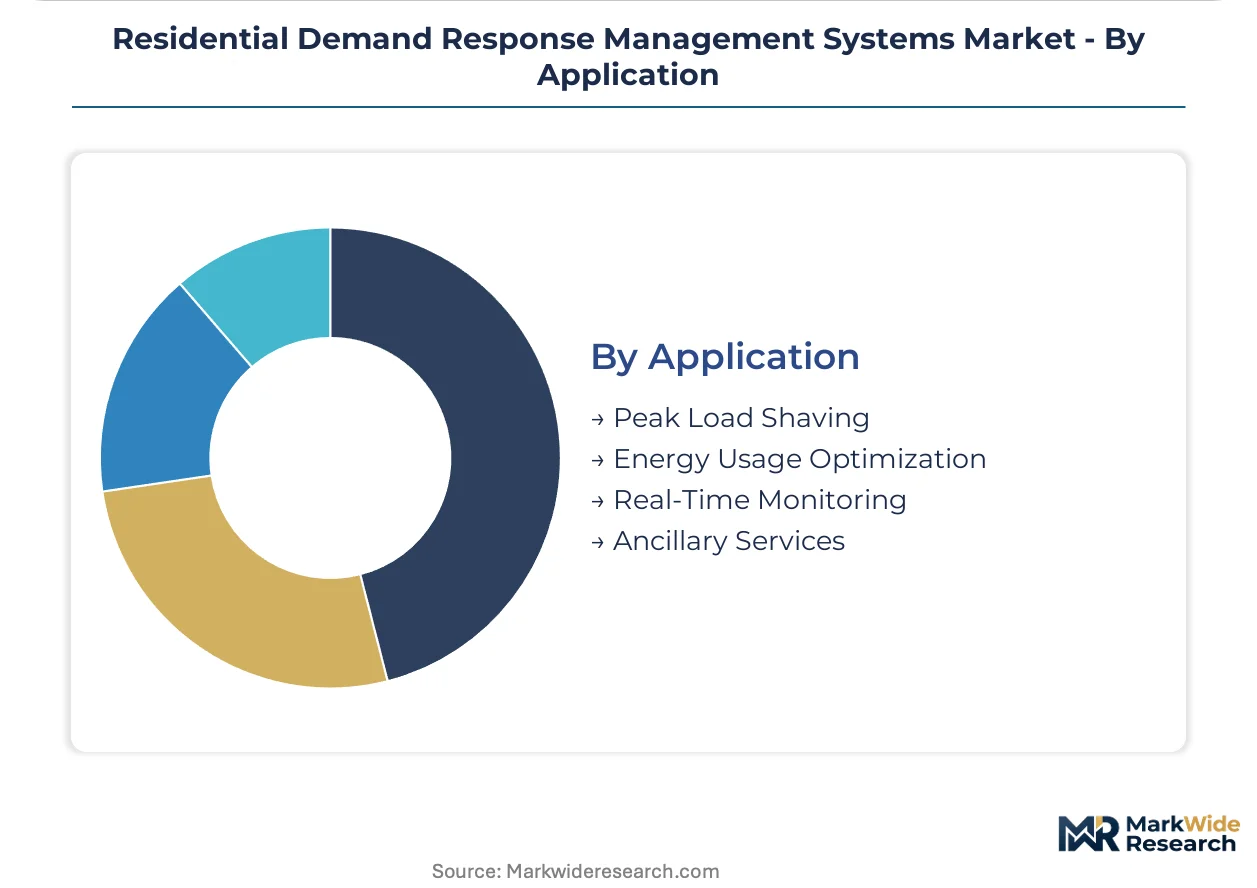
- Peak Load Shaving:Dispatchable load curtailment during system peak hours to defer generation capacity investment. California ISO procurement markets concentrate demand for automated peak reduction with 15-minute to 1-hour dispatch intervals.
- Energy Usage Optimization:Continuous algorithmic adjustment of consumption patterns against time-varying rates. Homeowners in Texas competitive retail markets deploy optimization engines that respond to real-time pricing signals.
- Real-Time Monitoring:Telemetry dashboards providing visibility into household consumption patterns and device status.
- Ancillary Services:Frequency regulation and spinning reserve participation through aggregated distributed resources. FERC Order 2222 enables this revenue stream, with Texas ERCOT and California ISO markets opening to residential resource stacks combining batteries, solar, and flexible loads.
Peak Load Shaving commands the mature revenue base. Ancillary Services represents the fastest-growing trajectory as wholesale market access rules restructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC anchors the regulatory framework reshaping wholesale market participation for aggregated residential resources across the United States, while parallel developments in Europe and Asia-Pacific create differentiated deployment corridors for demand response platforms.
United States
California, Texas, and New York concentrate platform deployment through mature utility programs and ISO-managed wholesale markets. FERC Order 2222 enables aggregated distributed energy resources to bid into frequency regulation markets, restructuring revenue architectures beyond traditional peak shaving. The California ISO territory leads enrollment density, with investor-owned utilities procuring automated load control to meet state-mandated resource adequacy targets.
Germany
Grid operators in Baden-Württemberg and Bavaria pilot residential demand response to manage distributed solar intermittency and heat pump load growth. The EU Green Deal and national building energy efficiency regulations accelerate smart meter rollout, creating telemetry infrastructure for automated load modulation. E.ON and EnBW deploy virtual power plant aggregation across the Rhine-Neckar and Munich metropolitan clusters.
China
Provincial grid companies in Jiangsu and Guangdong implement demand response pilots to address summer peak capacity constraints in manufacturing-intensive load centers. MIIT smart home standards and dual carbon policy targets drive interoperability requirements for home energy gateways. The Yangtze River Delta shows highest platform penetration, with State Grid Shanghai integrating residential resources into dispatchable capacity pools.
Australia
AEMO opens frequency control ancillary services markets to aggregated residential batteries and flexible loads, creating new revenue pathways for demand response providers. Victoria and New South Wales lead deployment through state-level energy efficiency schemes and time-of-use tariff structures. The Australian Energy Regulator sets data exchange standards shaping platform compliance requirements.
Japan
Tokyo Electric Power and regional utilities expand demand response enrollment to manage nuclear fleet retirement and renewable integration challenges. METI's electricity system reform creates retail competition that drives competitive energy providers to bundle demand response with commodity offerings. The Kanto and Kansai metropolitan areas concentrate smart home platform deployment.
Residential Demand Response Management Systems Market Competitive Landscape
Industrial conglomerates and specialized energy technology providers split the market through divergent platform architectures. The vendor base organizes around three strategic archetypes: diversified electrical equipment manufacturers with grid-edge automation portfolios, building technology specialists with HVAC-centric control systems, and pure-play software vendors with cloud-native aggregation platforms. Consolidation pressure intensifies as utilities consolidate procurement around end-to-end orchestration capabilities rather than point solutions. Strategic partnerships between hardware manufacturers and retail energy providers reshape channel economics.
Within the diversified industrial tier, Schneider Electric and Siemens exemplify platform breadth spanning multiple continents and regulatory jurisdictions. Honeywell International occupies a position anchoring thermostat-centric demand response with deep building system connectivity. These three companies represent contrasting architectural bets on whether residential energy management converges toward whole-home orchestration or remains segmented by device category.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| ABB |
| Honeywell International |
| General Electric |
| Eaton |
| Johnson Controls |
| Itron |
| Alarm.com Holdings |
| Others |
Value Network & Pricing Analysis
Undercapacity in Zigbee module fabrication across Taiwan and South Korea is compressing lead times for thermostat manufacturers while simultaneously hardening component pricing power, forcing platform vendors to absorb cost increases or accelerate Wi-Fi alternative qualification programs.
Pricing Analysis
California-Texas price spreads for Energy Management Systems exceed those for Smart Thermostats by a factor reflecting installation labor arbitrage and utility rebate differential. Three-tier pricing structure across premium orchestration platforms, standard gateway systems, and economy thermostat-only tiers stratifies by certification depth and after-sales service bundling. Cost compression in the economy tier is intensifying because Chinese Wi-Fi module suppliers are capturing thermostat socket share from Zigbee incumbents. Property managers in multifamily housing show highest price sensitivity; utility providers demonstrate lowest sensitivity due to pass-through rate mechanisms.
Supply Chain Analysis
Semiconductor feedstock for mesh networking chipsets draws from Taiwan, South Korea, and China's Yangtze River Delta fabrication clusters. Residential demand response hardware rests on lithium-ion battery cells for gateway backup power, silicon carbide power semiconductors for load control switches, and cellular modem chipsets for Texas rural deployments. Single-source vulnerability concentrates in Zigbee protocol stack licensing held by Netherlands-based semiconductor houses. Distribution runs through certified electrical contractor networks for Energy Management Systems and retail big-box channels for Smart Thermostats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FERC Order 2222 is restructuring wholesale market participation rules, creating a regulatory inflection that rewards platform providers capable of sub-5-second telemetry compliance and punishes thermostat-only architectures.
For Market Incumbents: Pre-empt pure-play software aggregators by acquiring edge computing gateway specialists with proven frequency regulation telemetry stacks. Consolidate installer network capacity in Texas and California before electrification timelines compress qualified electrical contractor availability. Vertical integration into silicon carbide power semiconductor sourcing hedges against Taiwan fab concentration risk. For New Entrants and Emerging Players: Australia's AEMO frequency control ancillary services markets represent the most penetrable geography for virtual power plant aggregation plays given recent market opening and limited incumbent platform saturation. White-label Energy Management Systems for competitive retail energy providers in Texas deregulated markets offer faster customer acquisition than utility-direct channels. Pursue cellular-enabled load control switch deployment where broadband infrastructure gaps persist in rural ERCOT territories. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across whole-home orchestration platforms as edge computing hardware requirements and cybersecurity certification burdens compound. Target acquisition candidates with demonstrated FERC Order 2222 compliance architecture and existing wholesale market interconnection agreements. Monitor California ISO procurement auction clearing prices as the signal indicating when ancillary services revenue pools justify platform migration investments.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Power Plant Aggregation | Combines battery storage, solar PV, and flexible loads into higher-value wholesale capacity market bids. |
| Edge Computing Gateway Deployment | Migrates control logic from cloud to home gateways, achieving sub-5-second telemetry for frequency regulation compliance. |
| Cellular-Enabled Rural Expansion | Extends platform reach into Texas ERCOT territories where broadband gaps exclude Wi-Fi-dependent architectures. |
| Cybersecurity Certification Investment | Accelerates product launches by preempting state-level data privacy standards that delay market access. |
| White-Label Platform Licensing | Captures retail energy provider channel economics in Texas competitive markets without proprietary infrastructure buildout. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility demand response program managers, competitive retail energy provider executives, certified electrical contractor network heads, and smart home platform engineering leads. Secondary validation drew from FERC Order 2222 implementation filings, California ISO market participation reports, EPA ENERGY STAR certification databases, and state public utility commission procurement records. Bottom-up enrollment projections by device category were triangulated against top-down utility procurement quota analysis.
Calibration against historical enrollment velocity in California investor-owned utility territories anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, communication protocol, end-user decision authority, and application revenue stream. CAGRs were derived from S-curve adoption modeling against electrification penetration benchmarks. Forecast inputs incorporated heat pump and EV charger deployment trajectories as controllable load expansion drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler cloud providers entering home energy aggregation would shift outcomes materially. Regulatory delays in state-level data privacy standard finalization or cybersecurity certification reciprocity agreements represent specific revision risks. Cross-checking against AEMO and California ISO market clearing price disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Global Utility Asset Management Market
Energy Management
Smart Energy Solutions Market
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
Microgrid Control System Market
Energy Management
Solar Panel Monitoring System Market
Energy Management
Industrial Energy Management System Market
Energy Management
Thermostat Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Energy Management Market
Energy Management
Distributed Energy Resource Management System (DERMS) Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Connected Energy Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Smart Power Management Market
Energy Management
European Building Energy Management Systems Market