
 Electric Service Companies (Escos) Market | 2026-2036
Electric Service Companies (Escos) Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Service Companies (Escos) Market Foresight
Grid-edge digitization is reshaping how ESCOs design, finance, and guarantee energy savings contracts. Ameresco leverages its federal sector footprint to capture large-scale infrastructure retrofits across military and civilian facilities. ENGIE SA anchors its competitive position through integrated renewable development bundled with efficiency services. Schneider Electric SE differentiates via proprietary EcoStruxure platforms that unify metering, analytics, and building control into single accountability frameworks.
Electric Service Companies deliver outsourced energy optimization through performance-based contracts that guarantee measurable reductions in consumption, demand, or operating cost, typically validated via IPMVP-compliant measurement and verification protocols. The primary commercial purpose is to transfer technical and financial risk from building owners to specialized service providers while capturing efficiency gains that internal capital budgets often fail to fund. Energy Management services dominate current revenue pools as baseline metering and optimization retain the widest addressable base. Demand Response is accelerating fastest as wholesale market reforms and capacity constraints expand remunerated load flexibility programs. Performance Contracting captures the deepest margin pools due to long-duration revenue recognition and shared-savings structures that align ESCO incentives with client outcomes.
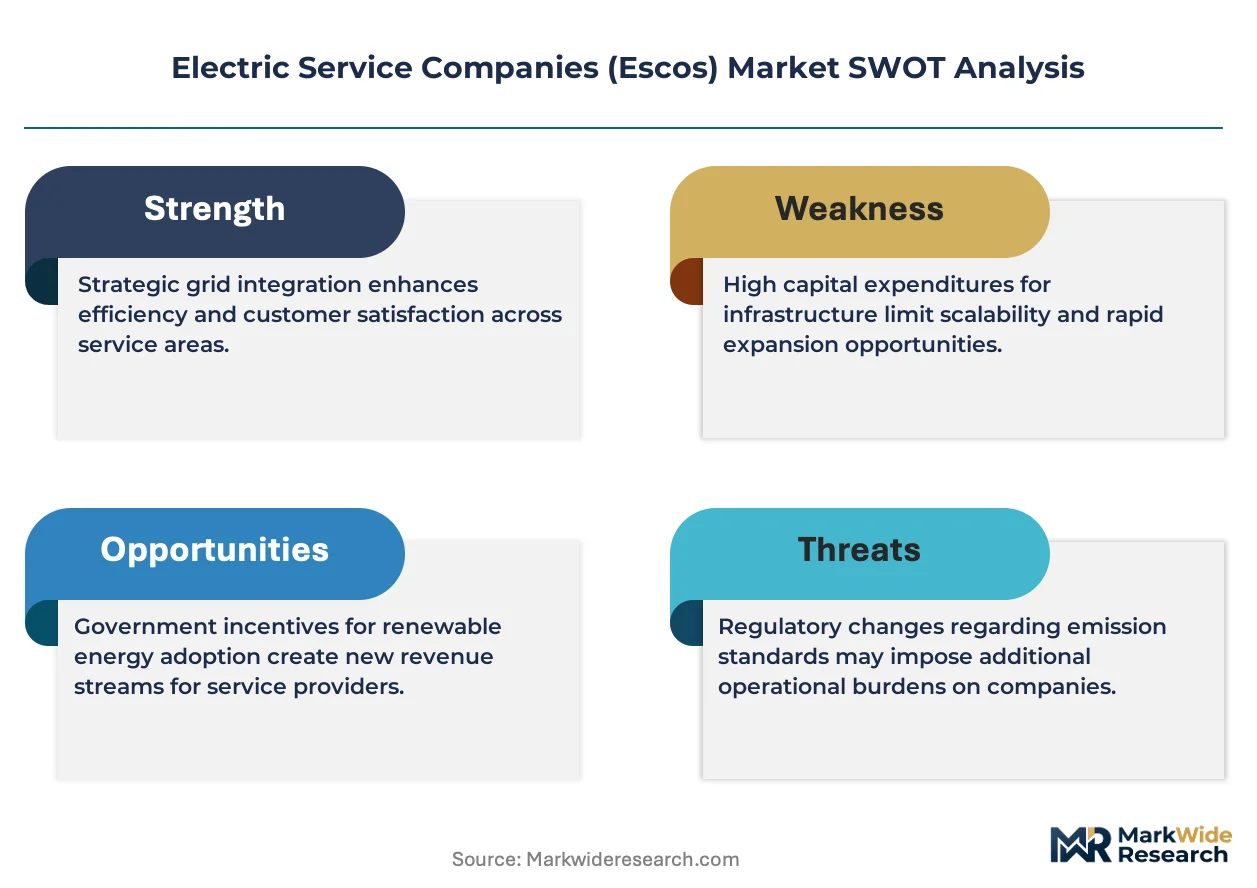
The US Inflation Reduction Act and accompanying Department of Energy loan authority reshape project economics by reducing capital costs and expanding eligible technology sets for federal and commercial clients. State-level public utility commissions in California, New York, and Massachusetts enforce building performance standards that mandate either retrofits or verified efficiency pathways, effectively compelling ESCO engagement. Stakeholders must monitor how FERC Order 2222 implementation at regional transmission organizations alters the competitive boundary between traditional ESCOs and distributed energy resource aggregators.
Market Dynamics
FERC Order 2222 implementation is compressing the competitive boundary between traditional ESCOs and distributed energy resource aggregators, forcing incumbents to restructure service architectures around grid-edge participation.
Growth Catalysts
- US Inflation Reduction Act:Direct pay mechanisms and expanded tax credit eligibility lower capital barriers for federal and commercial building retrofits, accelerating project origination velocity.
- Data center load growth:Hyperscale facility operators are contracting ESCOs for behind-the-meter generation and efficiency guarantees to manage power density constraints and carbon commitments.
- State building performance standards:California's Title 24 and New York Local Law 97 mandate verified efficiency pathways or retrofits, compelling commercial real estate engagement with performance contractors.
Market Restraints
- Interest rate sensitivity:Rising cost of capital compresses project IRRs and narrows the shared-savings margin pool that underpins performance contracting economics.
- Measurement and verification complexity:IPMVP protocol compliance requires specialized engineering talent that concentrates in mature markets, limiting geographic scalability.
- Utility incentive program volatility:State-level demand-side management budget fluctuations create pipeline uncertainty for ESCOs dependent on ratepayer-funded rebates.
Strategic Opportunities
- Grid-interactive efficient buildings:Convergence of building automation systems with wholesale market participation software creates new revenue streams from frequency regulation and capacity markets.
- Industrial microgrids:Heavy manufacturing and chemical processing facilities represent underpenetrated demand for resilient on-site generation bundled with efficiency services.
- EU Green Deal renovation wave:The European Commission's building renovation targets and ETS2 carbon pricing create mandated demand for performance contracting across commercial and residential stock.
Industry Challenges
- Cybersecurity certification timelines:NERC CIP and IEC 62443 compliance requirements for grid-connected building systems extend project delivery schedules and raise integration costs.
- Interconnection queue delays:Utility study backlogs for behind-the-meter generation stretch project commissioning timelines and erode savings guarantee credibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Service Companies (Escos) Market |
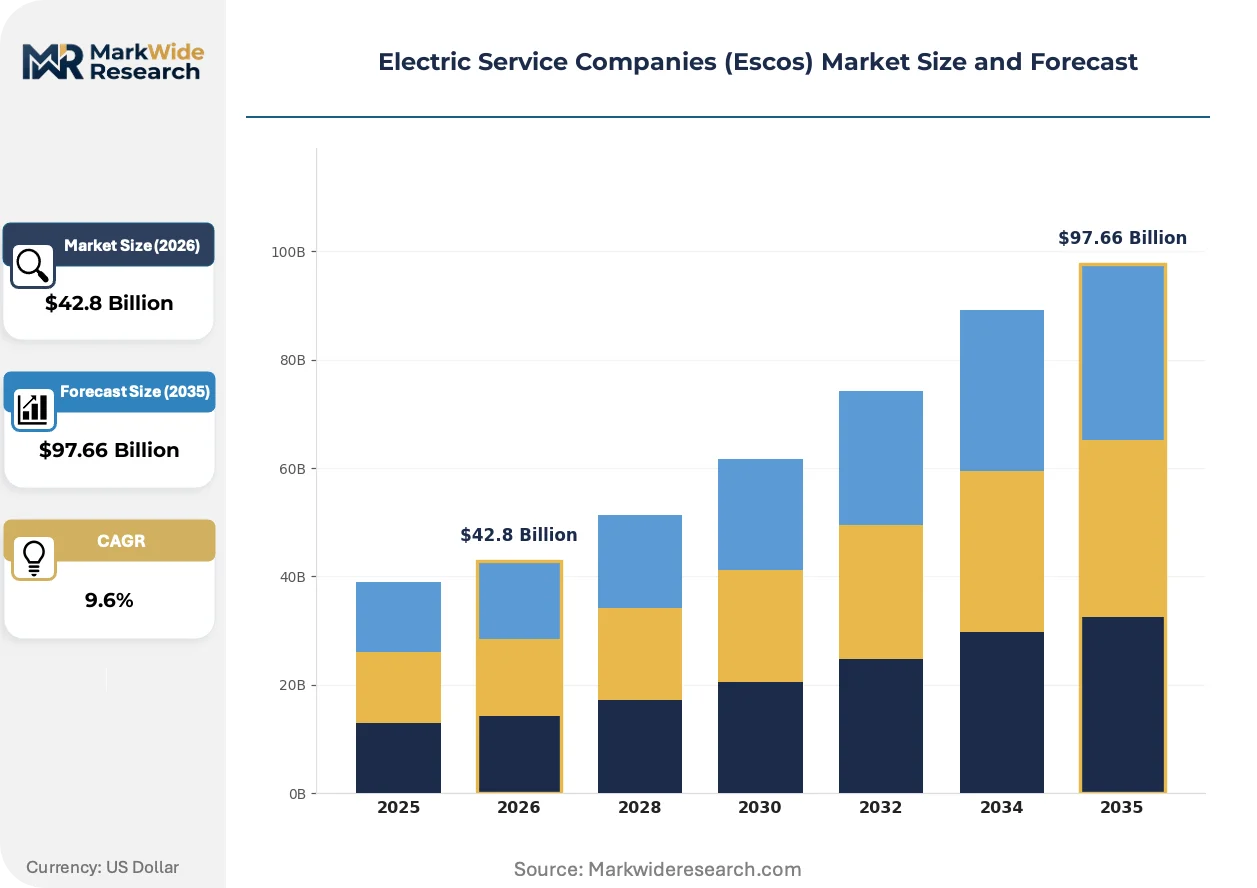
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $97.66 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Energy Management, Demand Response, Renewable Integration, Efficiency Services Client Type: Commercial, Industrial, Residential, Institutional Technology: Smart Meters, Analytics Tools, Control Systems, Machine Learning Offering: Performance Contracting, Consulting, Auditing, Training |
| Companies Covered | Ameresco Inc., ENGIE SA, Siemens Smart Infrastructure, Johnson Controls International plc, Schneider Electric SE, Honeywell International Inc., Noresco LLC, Trane Technologies plc, Energy Systems Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Service Companies (Escos) Market Shifts & Advancements
Digital twin technology is virtualizing how ESCOs model, guarantee, and verify energy savings, compressing the gap between projected and realized performance. Three convergent developments are restructuring competitive positioning.
Digital twin platforms are virtualizing building energy modeling by creating real-time calibrated simulations that replace static baseline assumptions. Large commercial real estate investment trusts are deploying these tools across portfolio-wide retrofits to reduce performance risk and tighten savings guarantee bands. This technology is virtualizing the traditional M&V workflow, shifting accountability from post-hoc measurement to continuous model validation.
The EU F-Gas Regulation phase-down is accelerating refrigerant transition mandates across commercial HVAC retrofit specifications. ESCOs must now bundle low-GWP equipment upgrades with efficiency contracting to maintain project eligibility under EU Green Deal financing mechanisms. European commercial building operators are responding by prioritizing integrated mechanical-electrical contractors with refrigerant handling certifications.
Corporate renewable energy buyers are unbundling energy attribute certificates from physical efficiency services, compressing the traditional bundled ESCO value proposition. Fortune 500 sustainability procurement teams now separately contract virtual PPAs for Scope 2 claims while engaging specialists for demand reduction. This bifurcation is most visible in US technology and financial services verticals where sustainability reporting granularity exceeds regulatory minimums.
Electric Service Companies (Escos) Market Segmentation
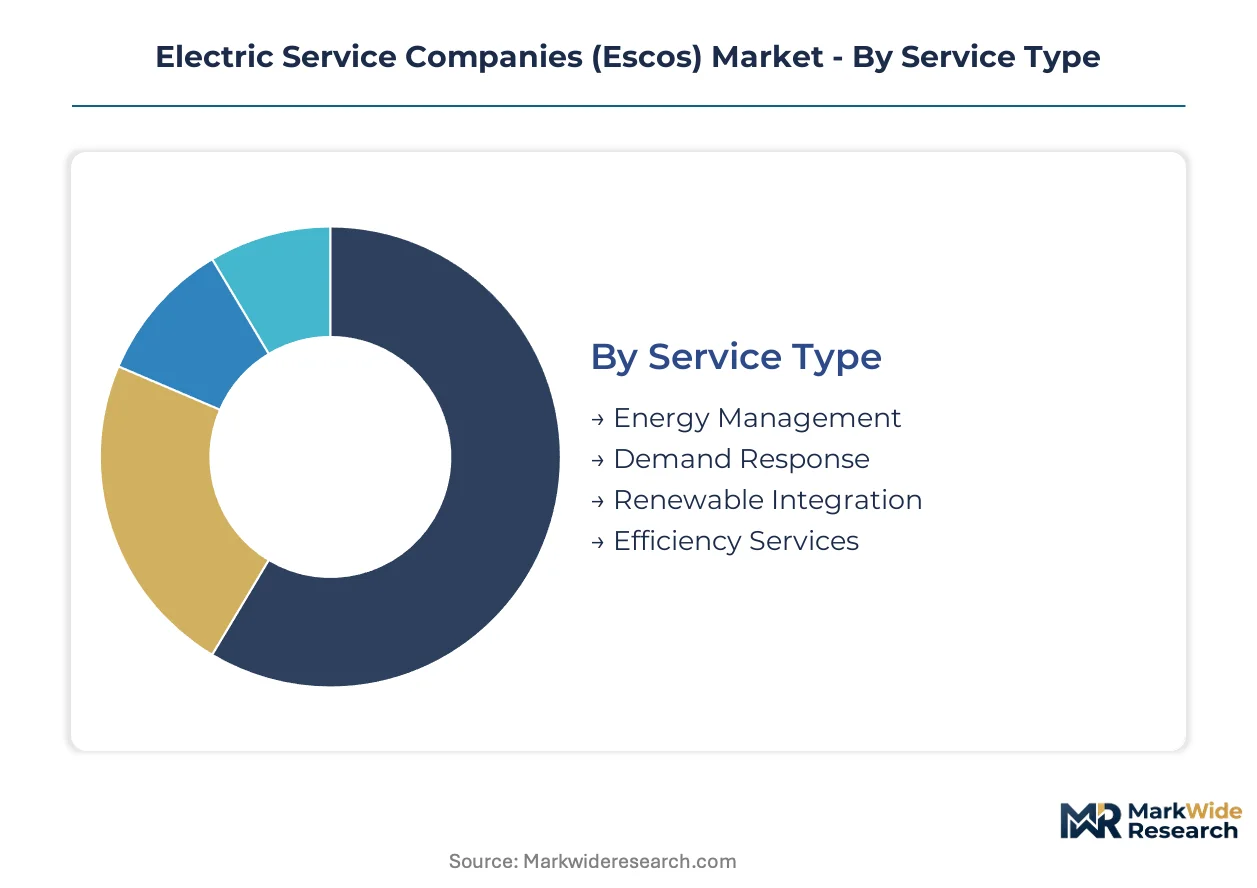
ESCO market segmentation reveals distinct service architectures, each demanding specialized technical capabilities and capital deployment models. Understanding these boundaries clarifies where margin pools concentrate and which client relationships sustain long-term revenue recognition.
Service Type:
After-sales service intensity varies sharply across service types, with continuous monitoring and verification obligations driving recurring revenue attachment rates.
- Energy Management:Baseline metering, consumption analytics, and ongoing optimization protocols form the foundational ESCO engagement layer. Demand concentrates in United States federal facilities and large commercial real estate portfolios where persistent utility cost pressure meets available capital for sensor infrastructure.
- Demand Response:Load curtailment and flexibility services remunerated through wholesale market participation or utility programs. United States regional transmission organizations under FERC Order 2222 implementation are expanding remunerated capacity markets, pulling industrial and data center loads into active participation.
- Renewable Integration:Behind-the-meter solar, storage, and microgrid development bundled with efficiency guarantees.
- Efficiency Services:Equipment upgrades, HVAC retrofits, and building envelope improvements with verified savings protocols.
Energy Management holds the largest share; momentum sits with Demand Response.
Client Type:
Cost tier differentiation separates clients by project scale, with institutional and industrial engagements commanding premium pricing for complexity absorption.
- Commercial:Office buildings, retail chains, and hospitality properties seeking utility cost reduction without capital deployment. United States commercial real estate investment trusts under California Title 24 and New York Local Law 97 mandates are accelerating performance contracting origination to avoid carbon penalties.
- Industrial:Heavy manufacturing, chemical processing, and logistics facilities with high load factors and resilience requirements. United States Department of Defense installations and civilian agency facilities represent concentrated demand for long-duration contracts with federal appropriations security.
- Residential:Single-family and multifamily efficiency programs, typically utility-administered or state-funded.
- Institutional:Universities, hospitals, and government facilities with stable occupancy and extended asset holding periods.
Commercial captures the deepest contract backlog; Industrial posts the steepest expansion trajectory.
Technology:
Application specificity determines technology deployment patterns, with control systems and analytics tools commanding integration premiums.
- Smart Meters:Interval metering infrastructure enabling granular consumption visibility and time-of-use optimization. United States utility smart grid deployments and EU member state metering mandates are saturating baseline measurement capabilities in mature markets.
- Analytics Tools:Cloud-based platforms processing meter data into actionable efficiency recommendations. Schneider Electric's EcoStruxure and competing building operating systems are consolidating vendor positions through unified data architecture.
- Control Systems:Building automation and energy management system integration for real-time load modulation.
- Machine Learning:Predictive algorithms for fault detection, demand forecasting, and automated setpoint optimization.
Analytics Tools anchor current platform investments; Machine Learning gains share fastest.
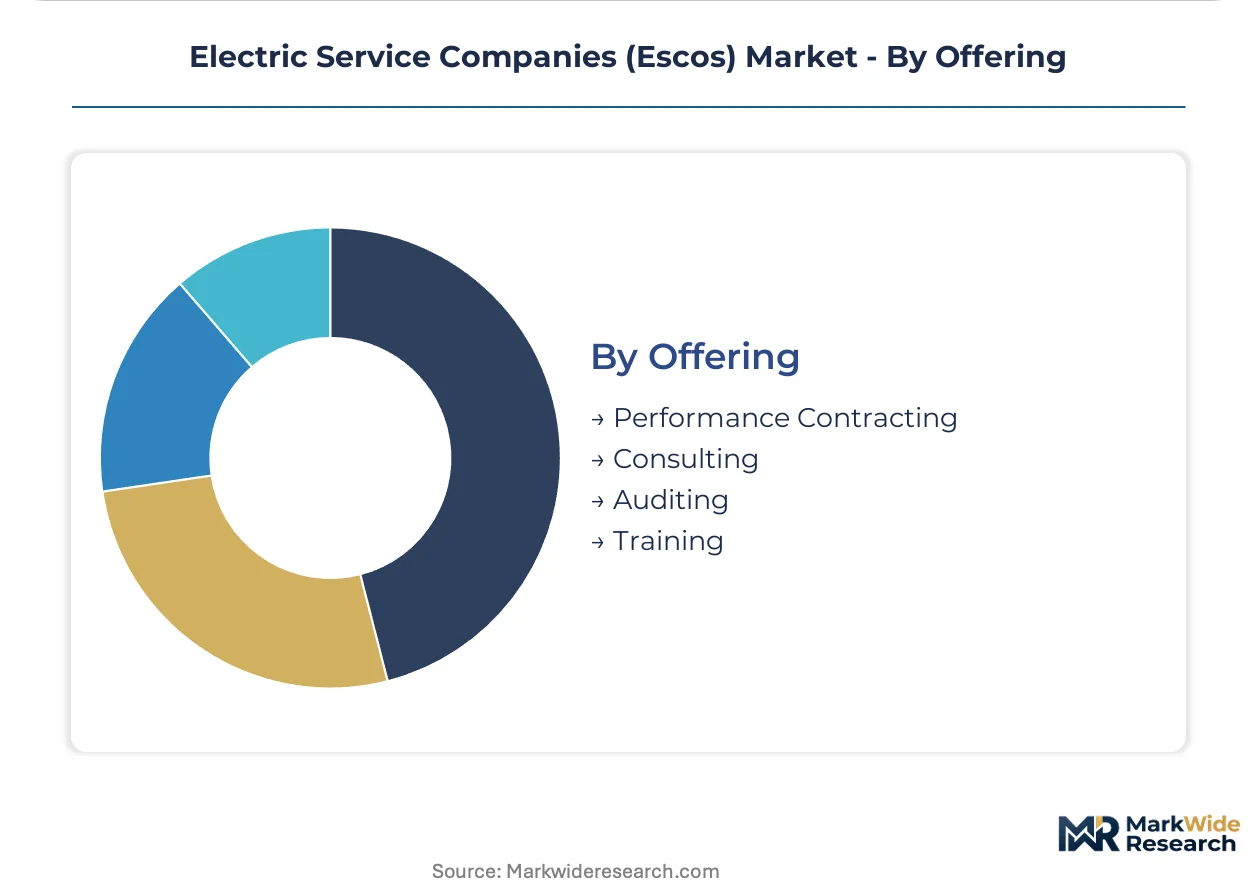
Offering:
Maturity stratification separates established contract mechanisms from advisory services with shorter revenue cycles and lower capital intensity.
- Performance Contracting:Multi-year agreements guaranteeing measurable energy savings with shared-risk financing structures. United States federal agencies utilize Department of Energy loan authority and Inflation Reduction Act direct pay mechanisms to reduce capital barriers and expand eligible technology sets.
- Consulting:Strategic energy planning, utility procurement advisory, and sustainability roadmap development. Corporate renewable energy buyers in United States technology and financial services verticals are unbundling advisory from implementation, compressing traditional bundled value propositions.
- Auditing:ASHRAE Level I-III assessments and investment-grade analyses supporting capital planning.
- Training:Operator education and workforce development for sustained efficiency performance.
Performance Contracting dominates revenue recognition; Consulting expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering consultancies export performance contracting methodologies to United States federal agencies, while Japanese trading houses channel capital into Southeast Asian building retrofit markets.
United States
Data center load growth and military facility modernization drive contract origination. The Inflation Reduction Act's direct pay mechanisms reduce capital barriers for federal building retrofits. Project pipelines concentrate in Northern Virginia's data center corridor and California's Title 24 enforcement zones.
Germany
Industrial microgrid demand from chemical processing clusters accelerates integrated efficiency contracting. The EU Green Deal renovation wave mandates building performance standards through 2030. Engineering services concentrate in the Ruhr industrial region and Bavaria's manufacturing belt.
China
State-owned enterprise efficiency mandates and smart city infrastructure programs expand addressable market. Dual carbon goals under the 14th Five-Year Plan compel provincial energy intensity reductions. Activity clusters in the Yangtze River Delta and Pearl River Delta manufacturing hubs.
Japan
Corporate renewable energy procurement unbundling creates specialized efficiency service demand. METI's building energy efficiency standards tighten compliance thresholds for commercial stock. Tokyo and Osaka metropolitan areas host concentrated ESCO advisory engagements.
India
State-level energy conservation building codes and DISCOM efficiency obligations drive municipal contracting. Bureau of Energy Efficiency mandates expand to commercial real estate above specified consumption thresholds. Maharashtra and Gujarat industrial corridors attract performance-based retrofit financing.
Electric Service Companies (Escos) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across differentiated contract origination pathways. The vendor base organizes around three strategic archetypes: integrated engineering conglomerates with captive equipment manufacturing, pure-play performance contractors with federal sector specialization, and building technology platforms with analytics-driven optimization. Dominant competitive moves include portfolio diversification into grid-edge services and strategic partnerships with distributed energy resource aggregators.
Within the integrated engineering tier, Siemens Smart Infrastructure and Schneider Electric SE exemplify platform-centric positioning through unified building control architectures. Johnson Controls International plc occupies a distinct position at the intersection of HVAC equipment manufacturing and long-duration performance contracting. Ameresco Inc. represents the federal-specialist archetype with concentrated exposure to military and civilian agency retrofit mandates.
| Leading Market Players |
|---|
| Ameresco Inc. |
| ENGIE SA |
| Siemens Smart Infrastructure |
| Johnson Controls International plc |
| Schneider Electric SE |
| Honeywell International Inc. |
| Noresco LLC |
| Trane Technologies plc |
| Energy Systems Group |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese smart meter manufacturing is compressing hardware margins and forcing ESCOs to rebundle equipment procurement into higher-margin analytics subscriptions. This utilization dynamic shifts supplier bargaining power toward software-integrated service providers while squeezing standalone equipment vendors.
Pricing Analysis
The technology-generation pricing gap separates legacy building automation systems from cloud-native analytics platforms and emerging AI-driven optimization tools. Project-based performance contracting with shared-savings structures dominates commercial engagements, while SaaS-tiered subscriptions gain traction in federal facilities. Price differentiation hinges on IPMVP certification tier and geographic delivery cost, with California and New York commanding premiums due to stringent Title 24 and Local Law 97 compliance requirements. Cost compression in legacy HVAC retrofit tiers is intensifying because interest rate sensitivity narrows shared-savings margin pools. Federal agencies exhibit lowest price sensitivity due to DOE loan authority backing, while small commercial real estate operators face acute capital constraint pressure.
Supply Chain Analysis
Upstream feedstock for building control systems draws from semiconductor fabrication concentrated in Taiwan, South Korea, and the United States. Critical component dependencies include power electronics, sensor arrays, and edge computing modules. Single-source vulnerability around specialized metering chipsets creates procurement risk for ESCOs deploying at scale. Distribution runs through integrated engineering conglomerates with captive manufacturing, direct OEM relationships for large federal contracts, and regional mechanical-electrical contractors for commercial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from distributed energy resource aggregators leveraging FERC Order 2222 market participation rights. This threat demands structural repositioning around grid-edge service integration.
For Market Incumbents: Entrench federal sector relationships through deeper DOE loan authority utilization and expanded direct pay mechanism advisory. Capture grid-interactive building automation capabilities through certification investment in NERC CIP and IEC 62443 cybersecurity standards. These moves counter distributed energy resource aggregators eroding traditional performance contracting boundaries.
For New Entrants and Emerging Players: Pursue industrial microgrid white space in underpenetrated chemical processing and heavy manufacturing corridors. Target data center behind-the-meter generation demand in Northern Virginia and Phoenix markets where power density constraints create urgent efficiency procurement. Lead with subscription-based continuous M&V services rather than capital-intensive shared-savings structures to reduce balance sheet barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among analytics-platform ESCOs with federal appropriations security and long-duration measurement and verification contracts. Five-to-ten year viability favors providers with proprietary building control architectures and integrated refrigerant handling capabilities under EU F-Gas Regulation compliance. Monitor FERC Order 2222 implementation velocity at regional transmission organizations as inflection signal for competitive boundary shifts between traditional ESCOs and distributed energy resource aggregators.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Edge Platform Integration | Unifies building automation with wholesale market participation software under FERC Order 2222. |
| Cybersecurity Certification Investment | Accelerates NERC CIP and IEC 62443 compliance to secure federal and utility-facing contracts. |
| Refrigerant Transition Bundling | Combines low-GWP equipment upgrades with efficiency contracting to maintain EU Green Deal eligibility. |
| Digital Twin Deployment | Virtualizes M&V workflows through real-time calibrated simulations that tighten savings guarantee bands. |
| Federal Sector Capacity Expansion | Captures Inflation Reduction Act direct pay mechanisms across military and civilian agency retrofit pipelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with performance contracting officers, federal energy managers, utility demand-side management leads, and commercial real estate sustainability directors; and secondary validation against FERC filings, DOE project development databases, EIA building energy consumption surveys, and state public utility commission regulatory dockets. Bottom-up project pipeline enumeration triangulated against top-down market sizing from equipment shipment data and contract award announcements.
Forecast inputs considered service type segmentation across energy management, demand response, renewable integration, and efficiency services; client type tiering across commercial, industrial, institutional, and residential categories; and technology deployment patterns spanning smart meters, analytics platforms, control systems, and machine learning optimization. CAGRs were derived from trajectory fitting across historical contract origination velocity and projected incentive program expansion. Key inputs included Inflation Reduction Act direct pay uptake rates and state building performance standard enforcement timelines.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and utility incentive program budget allocations would shift the trajectory. Cross-checking against DOE Energy Service Company industry reports and FERC demand response market participation data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Germany Demand Response Management Systems Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Europe Energy Management Systems Market
Energy Management
Electric Sub-Meter Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Heat Meter Market
Energy Management
Power SCADA Market
Energy Management
Smart Energy Solutions Market
Energy Management
Smart Power Technologies Market
Energy Management
Industrial Energy Management System Market
Energy Management
Energy Management Market
Energy Management
Thermostat Market
Energy Management
Brazil Energy Sector Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
APAC Energy Management Systems (EMS) Market