
 Global Utility Asset Management Market | 2026-2036
Global Utility Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Utility Asset Management Market Foresight
Multi-sourced vendor ecosystems for utility asset software is consolidating around platform providers with deep energy domain expertise. Siemens leverages its digital grid portfolio to anchor European utility modernization programs. IBM competes through AI-driven predictive maintenance modules that extend its enterprise software footprint into transmission operators. Schneider Electric differentiates via integrated edge-to-cloud architectures that control distributed energy resource fleets.
Utility asset management encompasses the systematic lifecycle oversight of physical infrastructure including transformers, pipelines, treatment facilities, and generation assets through condition-based monitoring, risk scoring algorithms, and work-order optimization protocols. Its primary purpose centers on maximizing capital efficiency while ensuring regulatory-mandated reliability thresholds across critical service networks. Condition monitoring services command premium pricing due to sensor hardware bundling and real-time analytics subscriptions. Cloud deployment architectures represent the fastest-expanding segment as municipal utilities abandon on-premise server maintenance. Power distribution applications absorb the largest share of sector spending given circuit-level visibility requirements and outage cost exposure.
The US FERC Order 2222 compels grid operators to accommodate distributed resource participation, forcing asset management platforms to track bidirectional flow equipment. The EU Green Deal's Renovation Wave and CSRD reporting obligations require European utilities to document embodied carbon in infrastructure replacements, tightening software specification standards. Japan's METI grid codes for renewable interconnection impose similar data granularity demands on domestic operators. Stakeholders must weigh captive development against platform partnerships as regulatory data requirements diverge across jurisdictions.
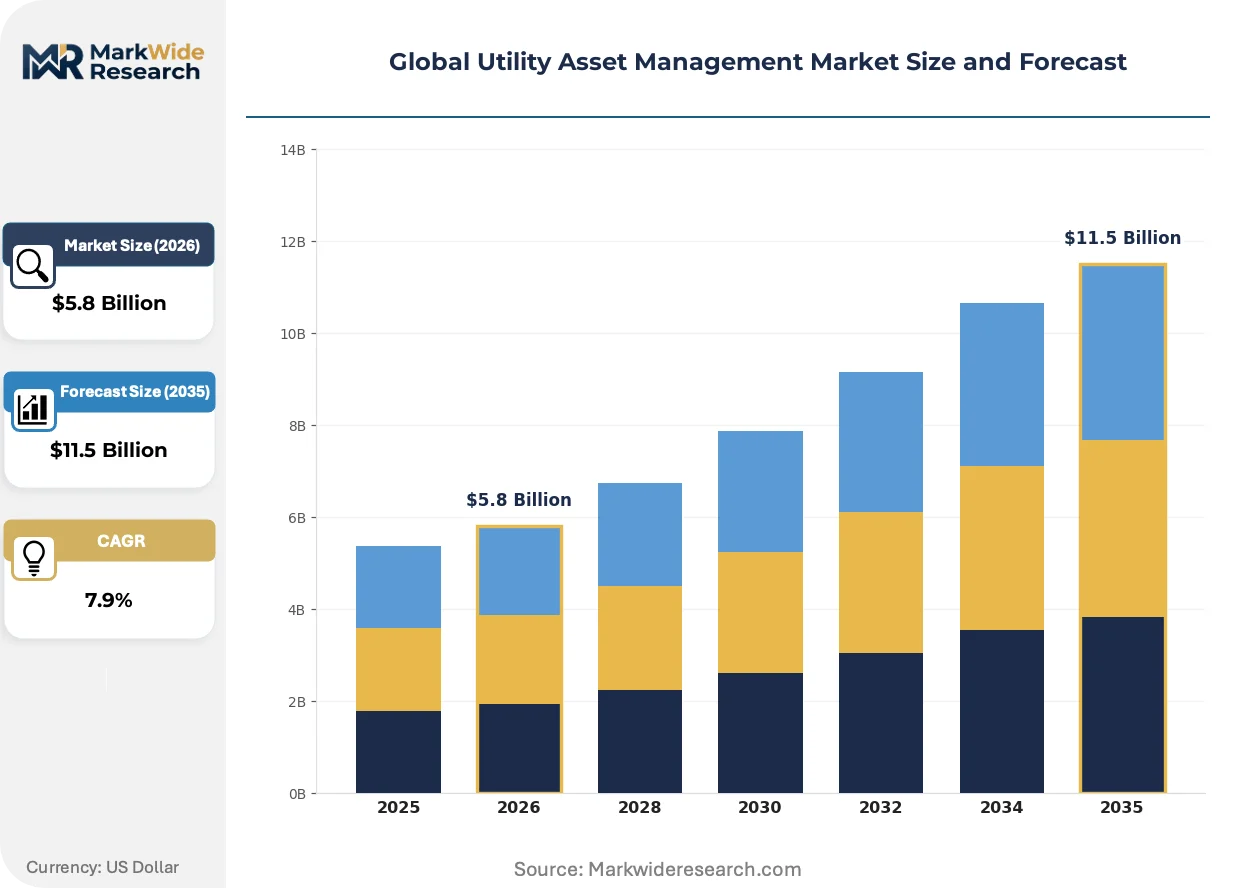
Market Dynamics
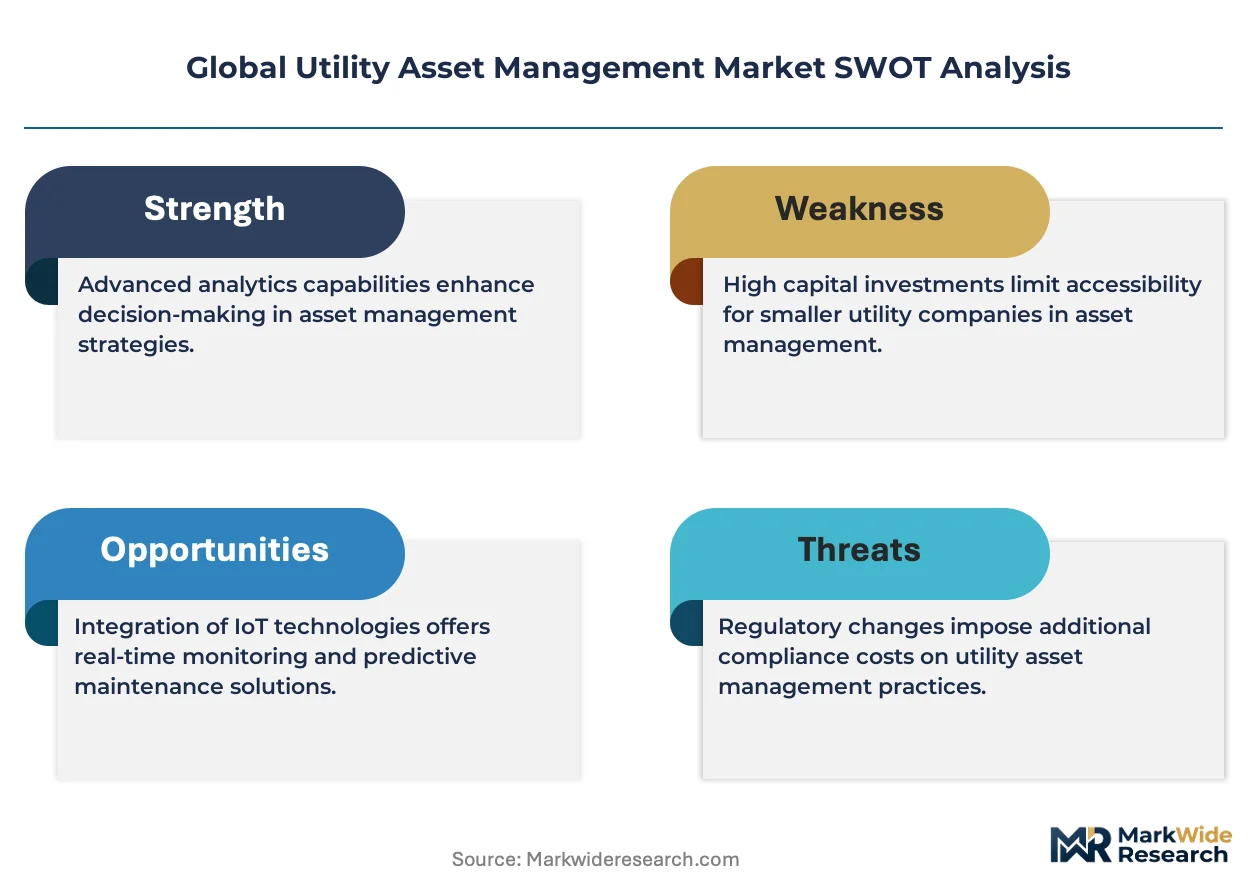
Grid operators face mounting pressure to reconcile aging infrastructure with bidirectional power flows from distributed solar and storage assets. FERC Order 2222 and the EU Green Deal's CSRD reporting obligations are forcing software procurement toward platforms that unify real-time operations with carbon accounting.
Growth Catalysts
- US FERC Order 2222:Mandates grid operators to integrate distributed energy resources, compelling asset management platforms to track bidirectional transformers and smart inverters.
- EU Green Deal CSRD:Requires European utilities to document embodied carbon in infrastructure replacements, tightening software specification standards for lifecycle tracking.
- Japan METI grid codes:Imposes granular data requirements for renewable interconnection, driving domestic operators toward advanced monitoring subscriptions.
Market Restraints
- Sensor hardware cost volatility:Industrial-grade IoT sensors for transformer monitoring face pricing pressure from semiconductor supply concentration in East Asian foundries.
- Legacy system integration friction:Municipal utilities operate SCADA systems with proprietary protocols that resist cloud-native platform connectivity.
- Cybersecurity certification delays:NERC CIP compliance timelines for critical infrastructure software extend procurement cycles by 18-24 months.
Strategic Opportunities
- India's smart grid mission:State electricity boards seek cloud-based asset platforms to manage rural distribution losses and renewable integration targets.
- Digital twin convergence:Combining physics-based simulation with AI-driven failure prediction opens premium service tiers for transmission operators.
- Edge-to-cloud architecture:Schneider Electric and Siemens are bundling on-premise analytics with centralized dashboards, capturing municipal utility budgets.
Industry Challenges
- OT-IT skill convergence:Utilities struggle to hire engineers fluent in both power systems operations and cloud architecture deployment.
- Data sovereignty fragmentation:Divergent national cloud storage mandates across Germany, the United States, and Japan complicate platform standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Utility Asset Management Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance Management, Risk Assessment, Asset Tracking, Condition Monitoring, Regulatory Compliance Application: Power Distribution, Water Treatment, Gas Supply, Renewable Energy, Waste Management Deployment: Cloud, On-premise, Hybrid, Edge Computing End User: Electric Companies, Water Authorities, Natural Gas Providers, Waste Services |
| Companies Covered | IBM, Schneider Electric, Siemens, General Electric, ABB, Eaton, Emerson Electric, Hitachi Energy, Black & Veatch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Utility Asset Management Market Shifts & Advancements
Software architectures are fragmenting as utilities reject monolithic enterprise suites in favor of modular platforms that embed domain-specific physics. Vendors now compete on API interoperability and pre-trained failure models rather than feature breadth.
Edge computing nodes with embedded machine learning inference are decentralizing condition monitoring from centralized control rooms to substation cabinets. Distribution utilities in Germany and Japan are deploying these units to reduce latency for fault detection. The shift is decentralizing vendor competitive advantage toward firmware optimization and ruggedized hardware design.
The EU CSRD and FERC reliability standards are tightening data granularity requirements for infrastructure replacement decisions. European transmission operators must now correlate asset health with embodied carbon calculations. This regulatory layering is compressing procurement timelines for integrated environmental-accounting modules.
Subscription pricing for predictive analytics is displacing perpetual licenses across municipal utilities in the United States and Germany. Finance departments favor operational expenditure treatment for software costs amid rate-case pressures. This purchasing shift favors platform vendors with proven uptime guarantees and usage-based billing infrastructure.
Global Utility Asset Management Market Segmentation
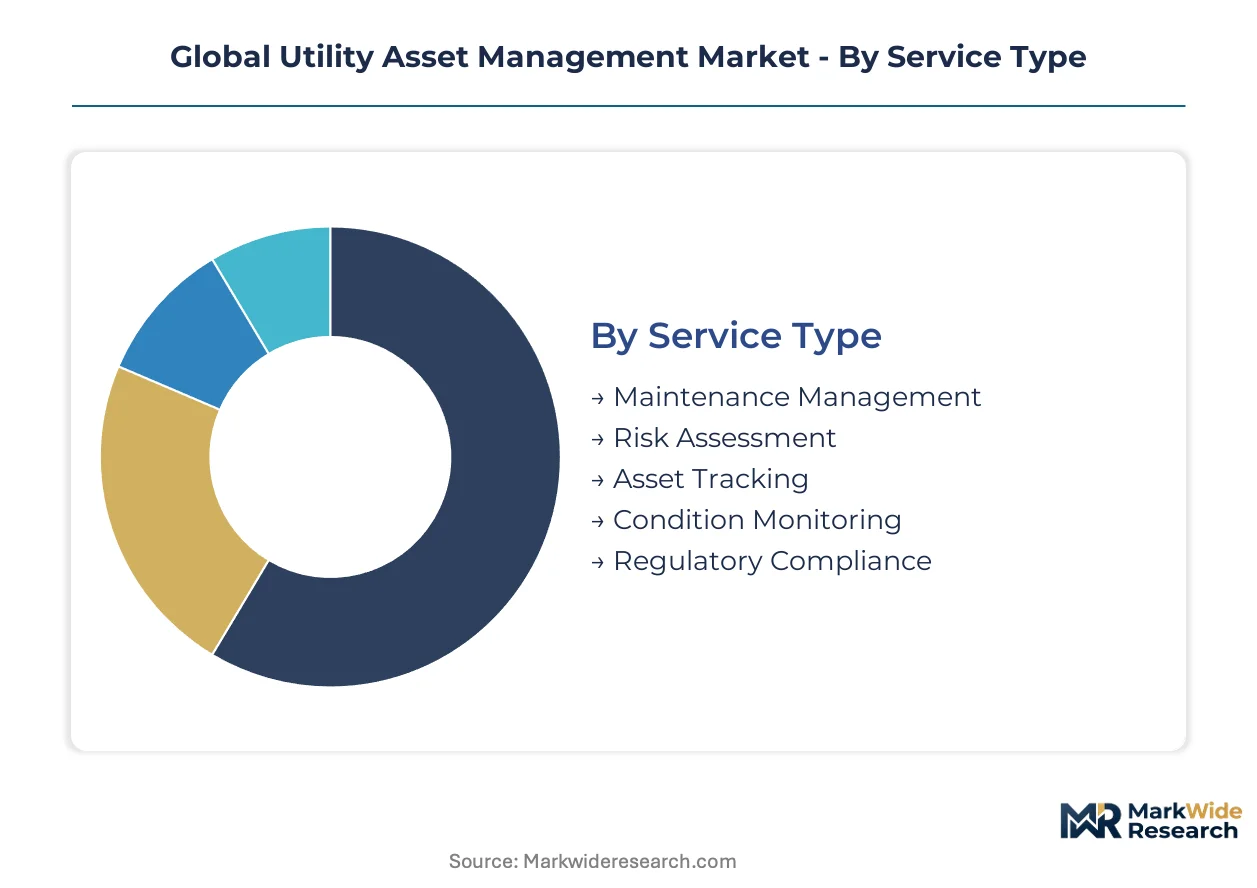
Utility asset management platforms fragment across service layers, physical infrastructure types, and computing architectures. Procurement patterns diverge sharply between integrated suites and point solutions, with cost tiers and regulatory exposure driving selection criteria.
Service Type:
Standalone modules for specialized functions compete against embedded capabilities within broader enterprise platforms, with integration depth determining total cost of ownership.
- Condition Monitoring:Sensor-integrated platforms track transformer health, pipeline corrosion, and turbine vibration through real-time telemetry streams. German transmission operators and Japanese utilities embed these systems directly into SCADA replacements, paying premium subscriptions for predictive failure algorithms.
- Maintenance Management:Work-order optimization engines schedule crew dispatch and inventory procurement against reliability targets. US municipal utilities favor cloud-native deployments here to convert capital expenditure into operational expenditure for rate-case filings.
- Risk Assessment:Quantitative models score asset failure probability against consequence matrices for regulatory filings.
- Asset Tracking:Geospatial databases locate mobile and fixed infrastructure across dispersed service territories.
- Regulatory Compliance:Automated documentation modules generate audit trails for FERC, EU CSRD, and METI reporting obligations.
Maintenance management leads volumes today; condition monitoring is gaining share fastest.
Application:
Physical infrastructure characteristics dictate software specification requirements, with voltage levels and fluid dynamics demanding domain-specific physics engines.
- Power Distribution:Circuit-level visibility platforms track bidirectional power flows from rooftop solar and battery storage assets. US investor-owned utilities deploy these systems to comply with FERC Order 2222 interconnection mandates.
- Renewable Energy:Fleet management systems optimize turbine availability and solar inverter performance across geographically dispersed generation assets.
- Water Treatment:Pressure monitoring and chemical dosing optimization for pipeline networks and treatment facilities.
- Gas Supply:Leak detection algorithms and pressure regulation for distribution pipeline integrity.
- Waste Management:Collection route optimization and landfill capacity planning for municipal service contracts.
Power distribution absorbs the largest procurement budgets; renewable energy applications are expanding most quickly.
Deployment:
Computing architecture selection reflects data sovereignty constraints, latency requirements, and legacy system coexistence strategies.
- Cloud:Centralized SaaS platforms eliminate on-premise server maintenance burdens. German municipal utilities and US cooperative utilities migrate here to access AI-driven analytics without internal IT infrastructure.
- Edge Computing:Embedded inference nodes process sensor data at substation cabinets, reducing transmission latency for fault detection. Japanese distribution utilities deploy these units to meet METI grid code response time requirements.
- On-premise:Air-gapped installations for critical infrastructure operators with stringent cybersecurity mandates.
- Hybrid:Tiered architectures keeping sensitive operational data local while pushing analytics to centralized clouds.
Cloud deployments dominate new procurement; edge computing is climbing the fastest among architecture transitions.
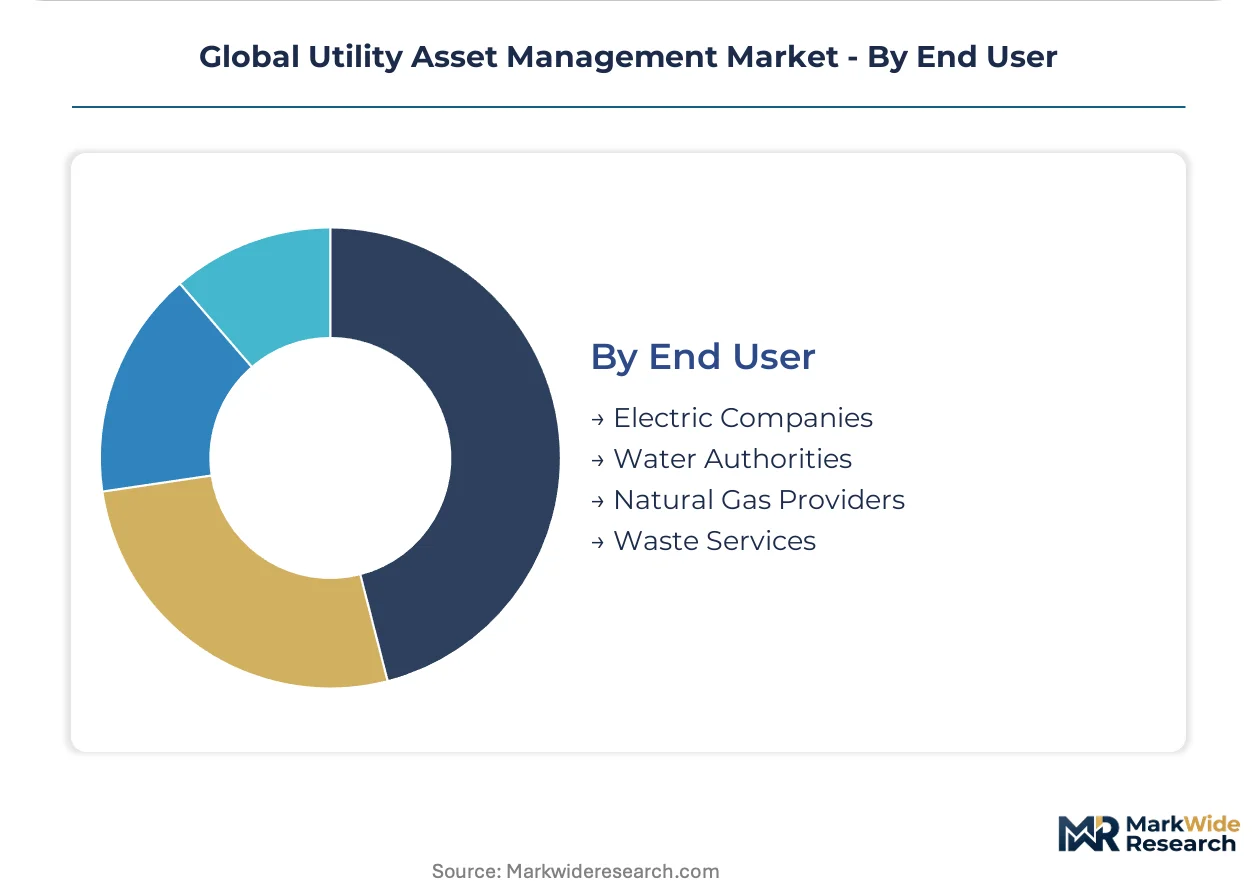
End User:
Organizational scale and regulatory exposure create distinct purchasing patterns across utility ownership structures.
- Electric Companies:Investor-owned utilities, municipal utilities, and cooperative operators with circuit-level monitoring requirements and NERC CIP compliance obligations.
- Water Authorities:Municipal and regional operators managing treatment facilities and distribution networks under EPA or local environmental mandates.
- Natural Gas Providers:Pipeline operators and local distribution companies with leak detection and pressure regulation priorities.
- Waste Services:Municipal collection departments and private landfill operators with route optimization and capacity planning needs.
Electric companies command the deepest software budgets; water authorities are adopting platform solutions at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European demand for utility asset management platforms as aging coal-to-gas infrastructure transitions strain regional grid operators. German transmission utilities deploy condition monitoring systems at substations across North Rhine-Westphalia. The EU Green Deal's CSRD reporting obligations force asset health data integration with carbon accounting modules.
United States
Investor-owned utilities in Texas and California drive procurement volumes for bidirectional power flow tracking systems. FERC Order 2222 mandates distributed resource participation in wholesale markets, compelling software upgrades across ERCOT and CAISO territories. The Pacific Northwest National Laboratory validates edge computing architectures for municipal cooperative deployments.
Germany
Transmission operators in Bavaria and Baden-Württemberg replace SCADA systems with cloud-native platforms integrating renewable forecast data. The country's national energy regulator enforces grid code compliance requiring granular asset documentation for wind and solar interconnection. Siemens anchors European modernization programs from its Munich digital grid headquarters.
Japan
Tokyo Electric and regional utilities in Kansai deploy substation-edge inference nodes to meet METI response time requirements for fault isolation. The Ministry of Economy, Trade and Industry imposes data granularity standards for renewable interconnection that exceed legacy monitoring capabilities. Chubu Electric pilots digital twin convergence for transmission corridor maintenance in the Nagoya industrial zone.
India
Maharashtra and Gujarat state electricity boards procure cloud-based asset platforms to manage rural distribution losses exceeding 15 percent. The Central Electricity Authority mandates smart grid mission compliance with renewable integration targets. Bangalore technology clusters host vendor development centers for AI-driven predictive maintenance modules tailored to tropical climate degradation patterns.
United Kingdom
National Grid and regional distribution network operators in Scotland deploy hybrid cloud architectures balancing data sovereignty with analytics performance. Ofgem price control mechanisms incentivize asset replacement decisions tied to reliability metrics. The Net Zero Strategy compiles embodied carbon documentation for transmission tower replacements across the Pennine corridor.
Global Utility Asset Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-to-cloud convergence and AI-native predictive modules. The vendor ecosystem consolidates around platform providers with deep energy domain expertise rather than horizontal enterprise software suites. Three archetypes dominate: integrated industrial conglomerates with captive grid hardware portfolios, enterprise software vendors extending AI capabilities into operational technology, and specialized asset analytics pure-plays. Dominant competitive moves include strategic partnerships with sensor hardware manufacturers and geographic expansion through municipal utility channel relationships.
Within the integrated industrial tier, Siemens and Schneider Electric exemplify platform providers bundling physical infrastructure with software subscriptions. IBM occupies a distinct position as an enterprise software vendor leveraging AI-driven modules to extend into transmission operator accounts. Hitachi Energy represents the hardware-anchored archetype with deep substation equipment integration capabilities. These three companies illustrate the competitive tension between domain-specific physics engines and general-purpose cloud architectures reshaping procurement criteria.
| Leading Market Players |
|---|
| IBM |
| Schneider Electric |
| Siemens |
| General Electric |
| ABB |
| Eaton |
| Emerson Electric |
| Hitachi Energy |
| Black & Veatch |
| Others |
Supply & Pricing Matrix
Edge computing hardware migration from centralized data centers to substation cabinets simultaneously compresses software delivery costs and concentrates semiconductor sourcing leverage among East Asian foundries serving industrial IoT sensor manufacturers.
Pricing Analysis
Input-cost pass-through from industrial-grade sensor hardware dominates pricing dynamics for condition monitoring subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates predictive analytics bundles with embedded machine learning from basic telemetry dashboards. Cost compression in municipal utility segments is intensifying because finance departments demand operational expenditure treatment for rate-case filings. State electricity boards in India exhibit highest price sensitivity; German transmission operators show least sensitivity due to regulatory-mandated reliability thresholds.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for industrial sensor microcontrollers, while cloud infrastructure concentrates in United States and Germany data center clusters. Raw material dependencies span silicon wafers, rare earth magnets for transformer monitoring equipment, and lithium for substation battery backup systems. Tariff exposure on semiconductor imports from East Asia presents structural risk for European platform vendors. Distribution runs through direct enterprise sales teams for investor-owned utilities and systems integrator channels for municipal cooperative deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European CSRD compliance costs exceed Indian smart grid mission procurement budgets by multiples, creating divergent margin pools for platform localization strategies.
For Market Incumbents: Anchor defensive positioning through backward integration into sensor hardware manufacturing to offset semiconductor cost volatility threatening subscription margins. Siemens and Schneider Electric should deepen firmware optimization capabilities for substation-edge inference nodes before IBM's AI-driven modules capture transmission operator accounts. Priority lever: captive supply of ruggedized industrial sensors.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in predictive analytics subscriptions creates white-space entry at mid-tier functionality for India's state electricity boards. Target cloud-native maintenance management modules for US municipal utilities converting capital expenditure to operational expenditure. Go-to-market angle: usage-based billing infrastructure with proven uptime guarantees.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized asset analytics pure-plays lacking edge-to-cloud architecture bundling. Long-term viability favors vendors with deep energy domain expertise over horizontal enterprise software suites. Acquisition target archetype: AI-native predictive maintenance modules with pre-trained failure models. Signal to watch: NERC CIP certification completion rates as inflection indicator for procurement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies SCADA replacement cycles with renewable forecast data for German transmission operators. |
| Strategic Partnership | Sensor hardware bundling secures condition monitoring subscription pricing power against semiconductor volatility. |
| Geographic Expansion | Municipal utility channel relationships capture India's smart grid mission procurement budgets. |
| Acquisition of Specialist Firm | AI-native predictive modules accelerate failure prediction capabilities for transmission corridor maintenance. |
| Product Launch | Digital twin convergence opens premium service tiers combining physics-based simulation with edge inference. |
Research Methodology
Direct dialogue with utility planning officers, grid operators, EPC contractors, and IPP project developers grounded primary intelligence, validated against FERC filings, EIA data, IEA reports, and project development databases. Secondary sources included SEC disclosures from platform vendors and EU regulatory implementation guidance. Bottom-up and top-down triangulation reconciled segment-level procurement patterns with aggregate market sizing.
Segmentation outputs across deployment model, infrastructure type, utility ownership structure, and regional regulatory framework populated the analytical architecture throughout the projection horizon. CAGRs derived from weighted average of historical procurement trajectories and policy-mandated replacement schedules. Forecast inputs incorporated FERC Order 2222 implementation timelines and EU CSRD reporting obligation phase-ins.
Caveats apply where NERC CIP certification delays, semiconductor supply disruptions, or divergent national cloud storage mandates could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement intensity and utility capital allocation priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Electric Sub-Meter Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Connected Energy Market
Energy Management
Smart Power Technologies Market
Energy Management
Energy Management Market
Energy Management
Industrial Energy Management System Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Heat Meter Market
Energy Management
Distributed Energy Resource Management System (DERMS) Market
Energy Management
Demand Response Management System Market
Energy Management
Thermostat Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Middle East and Africa Energy Management Systems Market