
 South Korea Residential Heat Pump Market | 2026-2036
South Korea Residential Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Residential Heat Pump Market Insights
Premium-efficiency tier certification is bifurcating the competitive landscape as households prioritize operating cost reduction over upfront price. Daikin Industries leverages its inverter compressor R&D intensity to sustain technology leadership in cold-climate performance. KD Navien anchors its position through backward integration into gas-to-electric hybrid systems. LG Electronics differentiates via smart-home ecosystem integration and channel control across Korean retail networks.
A residential heat pump extracts ambient thermal energy from air, ground, or water sources and transfers it indoors using vapor-compression refrigeration cycles with coefficient-of-performance ratings typically exceeding three under standard test conditions. Air source systems dominate unit volume due to lower installation complexity, though ground source configurations capture disproportionate margin pools from villa and townhouse segments seeking year-round efficiency. The 4-6 kW capacity band leads apartment installations, while above 10 kW units concentrate in premium villa developments where space conditioning loads exceed standard thresholds.
MFDS energy labeling requirements and KEMCO efficiency standards shape product certification pathways, while the Green New Deal's building retrofit mandates accelerate replacement cycles for aging heating infrastructure. Municipal building codes in Seoul and Busan increasingly restrict fossil-fuel-only heating in new construction, compressing market access for conventional boiler systems. Stakeholders must monitor evolving refrigerant phase-down schedules under Korea's national carbon neutrality roadmap and calibrate R&D portfolios toward low-global-warming-potential alternatives before regulatory deadlines tighten supply chain compliance requirements.
Market Dynamics
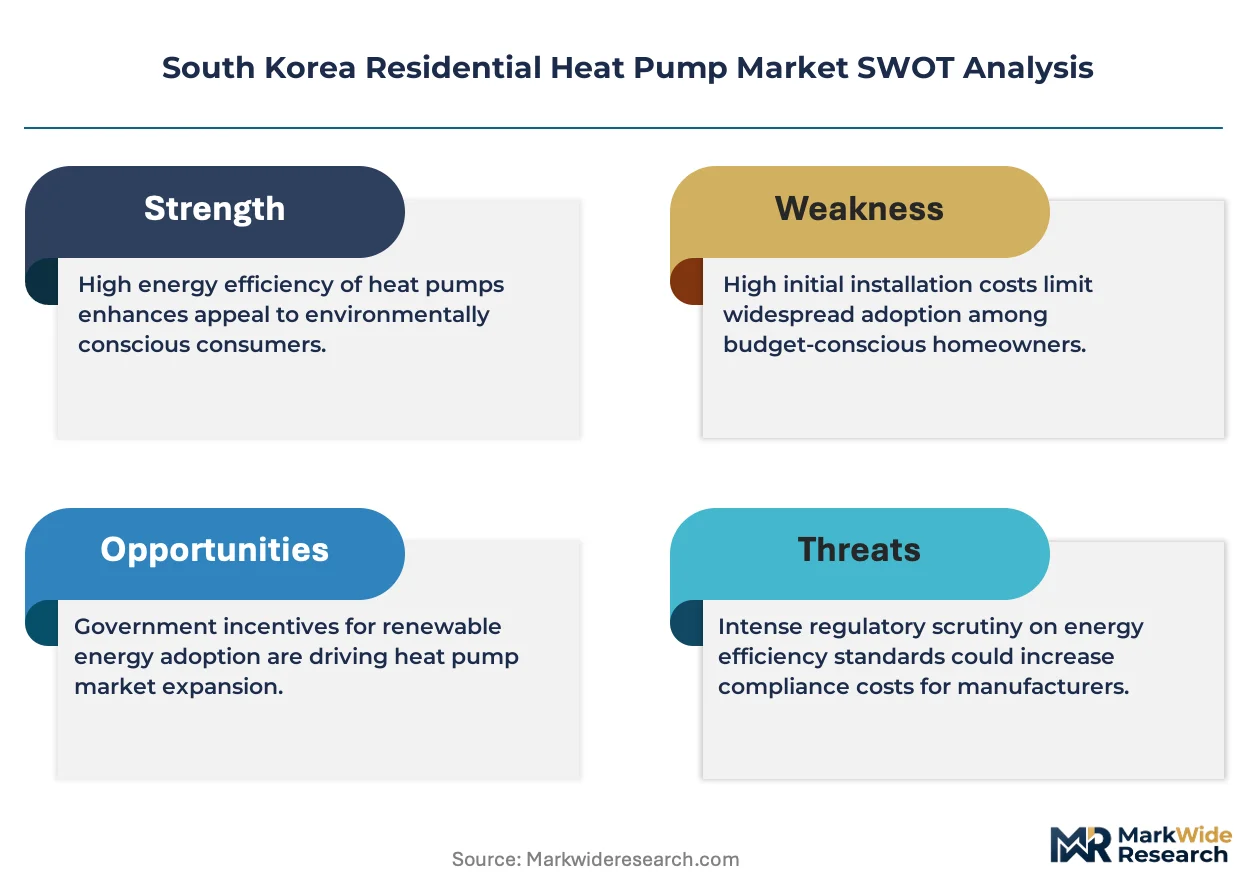
The Green New Deal's building retrofit mandates are compressing replacement cycles for aging heating infrastructure while MFDS energy labeling requirements bifurcate product tiers based on certified efficiency performance.
Growth Catalysts
- Seoul Metropolitan Area Density:Multi-family apartment complexes in Seoul and Gyeonggi Province generate concentrated demand as urban population density rises and municipal codes restrict fossil-fuel-only heating in new construction.
- KEMCO Efficiency Standards:Mandatory certification pathways accelerate premium-tier product penetration by creating transparent operating cost comparisons that household buyers prioritize over upfront price.
- Refrigerant Transition Mandates:Korea's national carbon neutrality roadmap forces R&D investment into low-global-warming-potential alternatives, positioning early adopters for compliance advantage as regulatory deadlines tighten.
Market Restraints
- Copper and Rare Earth Input Volatility:Inverter compressor manufacturing depends on concentrated copper supply chains and neodymium magnet availability, exposing margin structures to commodity price swings.
- Cold-Climate Performance Limitations:Air source systems experience coefficient-of-performance degradation below minus 15 degrees Celsius, constraining deployment in Gangwon Province highland zones without auxiliary heating.
- Ground Source Installation Complexity:Geothermal loop deployment requires property-specific geological assessment and drilling permits that extend project timelines beyond typical apartment renovation windows.
Strategic Opportunities
- Busan Metropolitan Expansion:Municipal building codes in Korea's second-largest city increasingly mirror Seoul's fossil-fuel restrictions, opening underpenetrated demand in new coastal residential developments.
- Smart-Home Ecosystem Convergence:Integration between heat pump controls and residential energy management systems creates differentiation value for buyers seeking unified appliance command through single platforms.
- Hybrid Gas-to-Electric Retrofit Channel:Existing gas boiler infrastructure in aging apartment complexes presents conversion opportunity through dual-fuel systems that bridge regulatory transition periods.
Industry Challenges
- Refrigerant Handling Certification Bottlenecks:Technician licensing requirements for low-global-warming-potential refrigerants lag equipment availability, constraining installation capacity during peak replacement seasons.
- Legacy Control System Integration:Apartment complex central heating management platforms require protocol adaptation to communicate with distributed heat pump units, complicating building-wide efficiency optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Residential Heat Pump Market |
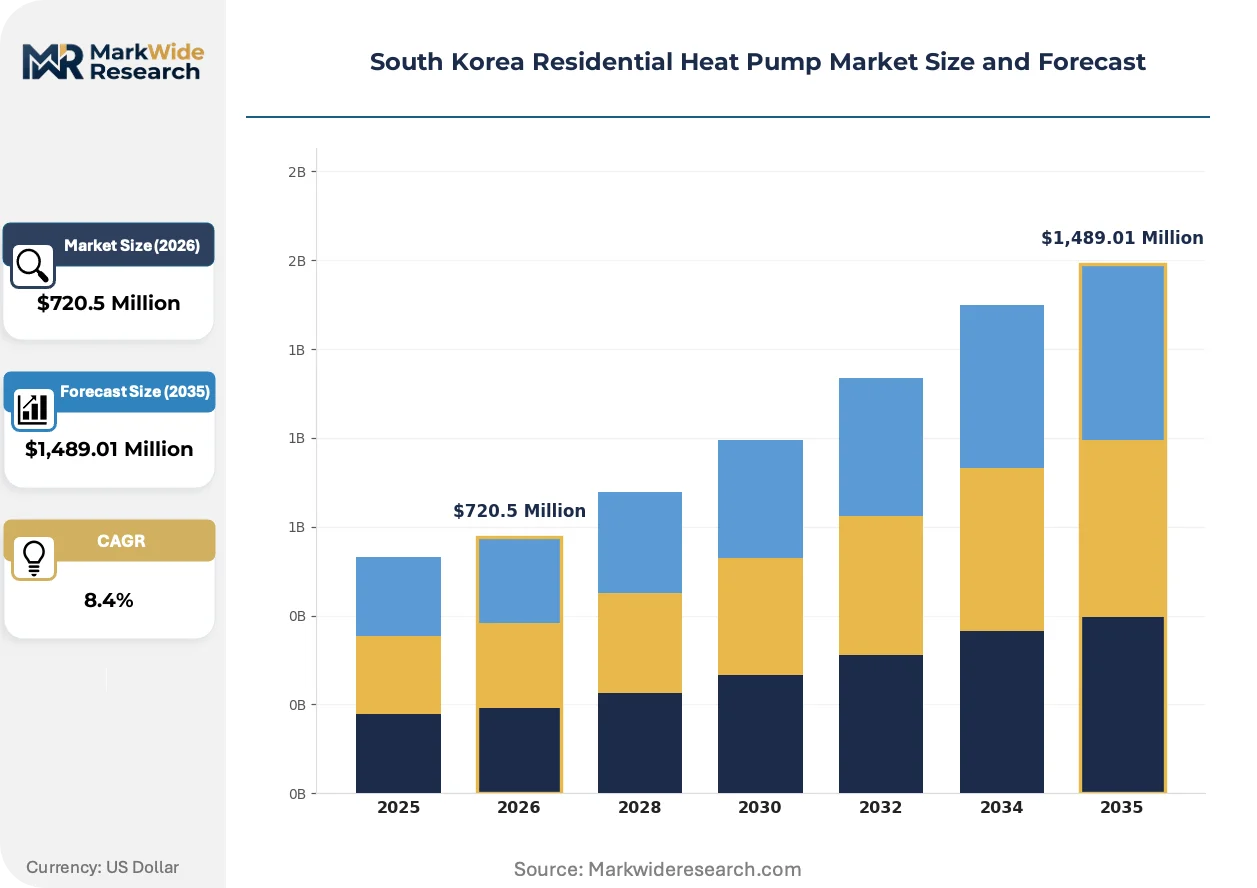
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,489.01 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Ground Source, Water Source, Hybrid Capacity: 1-3 kW, 4-6 kW, 7-10 kW, Above 10 kW Installation Type: Split System, Packaged System, Centralized System, Ductless System End User: Households, Apartments, Villas, Townhouses |
| Companies Covered | Daikin Industries, KD Navien, LG Electronics, Kiturami-Bumyang Air Conditioning, Shinsung Engineering, Mitsubishi Electric, Fujitsu General, Daesung Celtic Energy Systems, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Residential Heat Pump Market Trends and Innovations
Inverter-driven variable-speed compression is displacing fixed-capacity systems across Korean residential installations. Three interconnected developments are reshaping competitive positioning and buyer expectations.
Variable-refrigerant-flow technology is decomposing the traditional split between heating-only and cooling-capable residential systems. Villa and townhouse developers in Seongnam and Yongin are specifying unified space conditioning platforms that eliminate redundant equipment. This convergence compresses addressable market boundaries between HVAC product categories and forces portfolio reconfiguration among incumbent suppliers.
MFDS energy labeling requirements now mandate real-world seasonal performance testing rather than laboratory coefficient-of-performance ratings. This regulatory shift elevates cold-climate operating efficiency as a certified differentiator. Premium-tier products with enhanced defrost algorithms and expanded operating temperature ranges capture disproportionate buyer attention in Seoul's climate zone.
Households increasingly prioritize total cost of ownership calculations over capital expenditure minimization when selecting replacement heating equipment. Retail channels in Gyeonggi Province report extended purchase deliberation cycles as buyers model ten-year operating cost scenarios. This behavioral shift compresses price-competitive standard-tier positioning while expanding premium-efficiency addressable market share.
South Korea Residential Heat Pump Market Segmentation
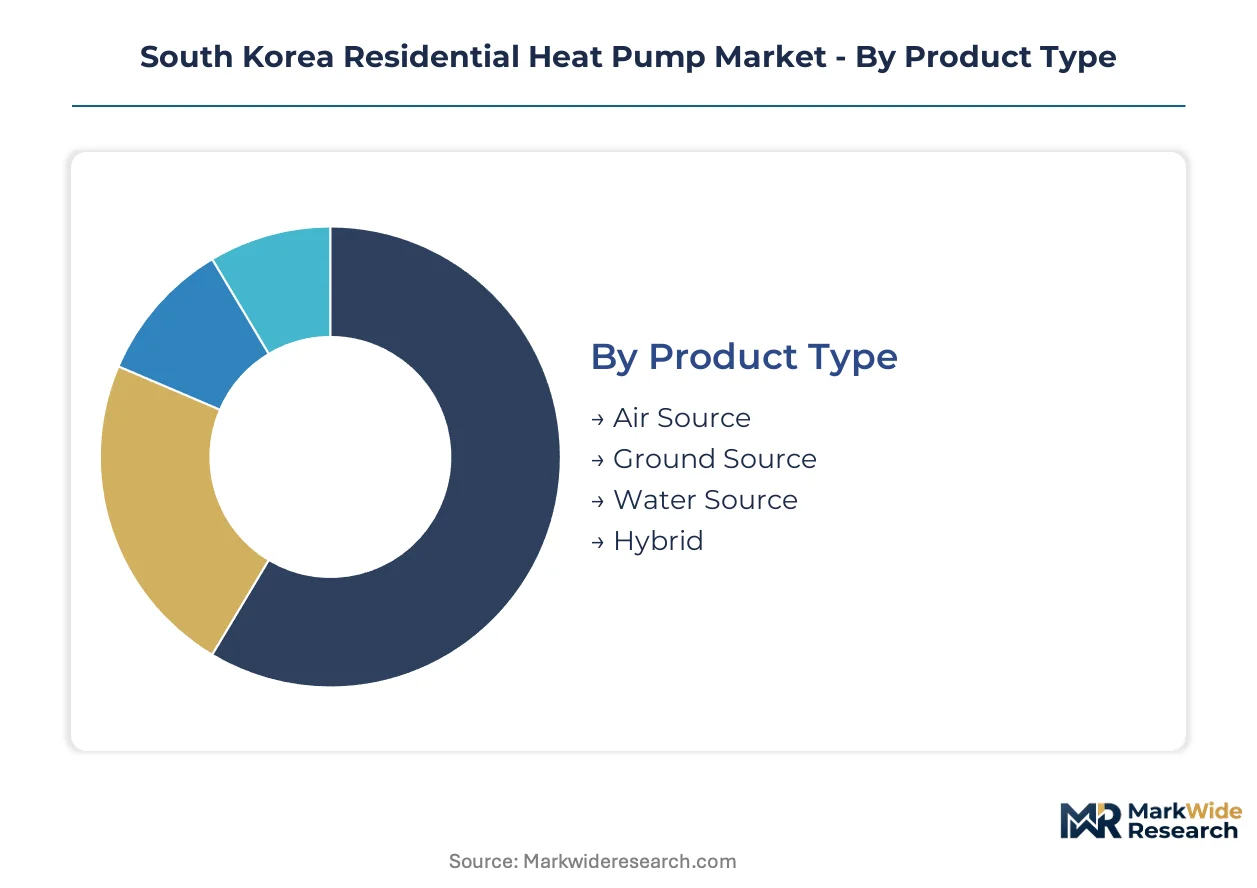
Segmentation reveals how substitution pressures from conventional heating systems vary across product architectures and installation contexts. Understanding these fault lines allows stakeholders to prioritize R&D investment and channel configuration for maximum defensive positioning.
Product Type:
Air source configurations face the most intense substitute threat from gas boilers in retrofit scenarios, while ground source systems compete primarily against district heating networks in new construction.
- Air Source:Vapor-compression units extract thermal energy from ambient air through finned evaporator coils. Demand concentrates in Seoul apartment complexes where municipal codes now prohibit fossil-fuel-only heating in new buildings, though cold-climate performance degradation below minus 15 degrees Celsius constrains deployment in Gangwon Province highlands without auxiliary heating.
- Ground Source:Geothermal heat pumps utilize buried loop fields to access stable subsurface temperatures year-round. Villa developments in Seongnam and Yongin specify these systems for superior seasonal efficiency, but property-specific geological assessment requirements and drilling permit timelines extend project durations beyond typical renovation windows.
- Water Source:Systems leverage adjacent water bodies or aquifers as thermal reservoirs. Applications cluster near coastal developments in Busan where groundwater access permits simplify loop deployment.
- Hybrid:Dual-fuel configurations combine electric heat pump operation with gas boiler backup. Aging apartment complexes in Gyeonggi Province deploy these as bridge solutions during regulatory transition periods.
Air source retains volume leadership; ground source holds the steepest expansion curve.
Capacity:
Cost tier stratification across capacity bands reflects divergent customer willingness-to-pay for performance headroom versus operating efficiency optimization.
- 4-6 kW:Mid-range capacity systems dominate Seoul metropolitan apartment installations where space conditioning loads align with standard unit specifications. MFDS energy labeling requirements drive premium-tier penetration in this band as households prioritize operating cost reduction.
- Above 10 kW:Large-capacity units serve premium villa developments with elevated heating loads and integrated cooling requirements. Installations concentrate in Yongin and Gwacheon where floor area exceeds typical apartment thresholds.
- 1-3 kW:Compact systems address studio apartments and auxiliary heating applications. Limited addressable market constrains manufacturer portfolio investment.
- 7-10 kW:Upper-mid capacity range captures townhouse segments seeking single-system solutions. Growth depends on cold-climate performance certification under revised KEMCO seasonal testing protocols.
4-6 kW commands the largest installed base; above 10 kW generates the highest margin per unit.
Installation Type:
Application complexity varies sharply across installation architectures, with centralized systems demanding building-level coordination that split units avoid.
- Split System:Separate indoor and outdoor units connected by refrigerant lines. Apartment renovations in Seoul favor this architecture for minimal structural disruption during retrofit.
- Ductless System:Wall-mounted or ceiling-cassette indoor terminals deliver zoned conditioning without air distribution infrastructure. Townhouse developments specify these for room-level temperature control flexibility.
- Packaged System:Single-unit configurations integrate all components in one enclosure. Rooftop installations in low-rise villa compounds utilize this simplified architecture.
- Centralized System:Building-scale plants distribute conditioned fluid through hydronic loops. New multi-family complexes in Busan metropolitan expansion zones specify these for unified energy management.
Split system maintains retrofit dominance; ductless gains share fastest in new townhouse construction.
End User:
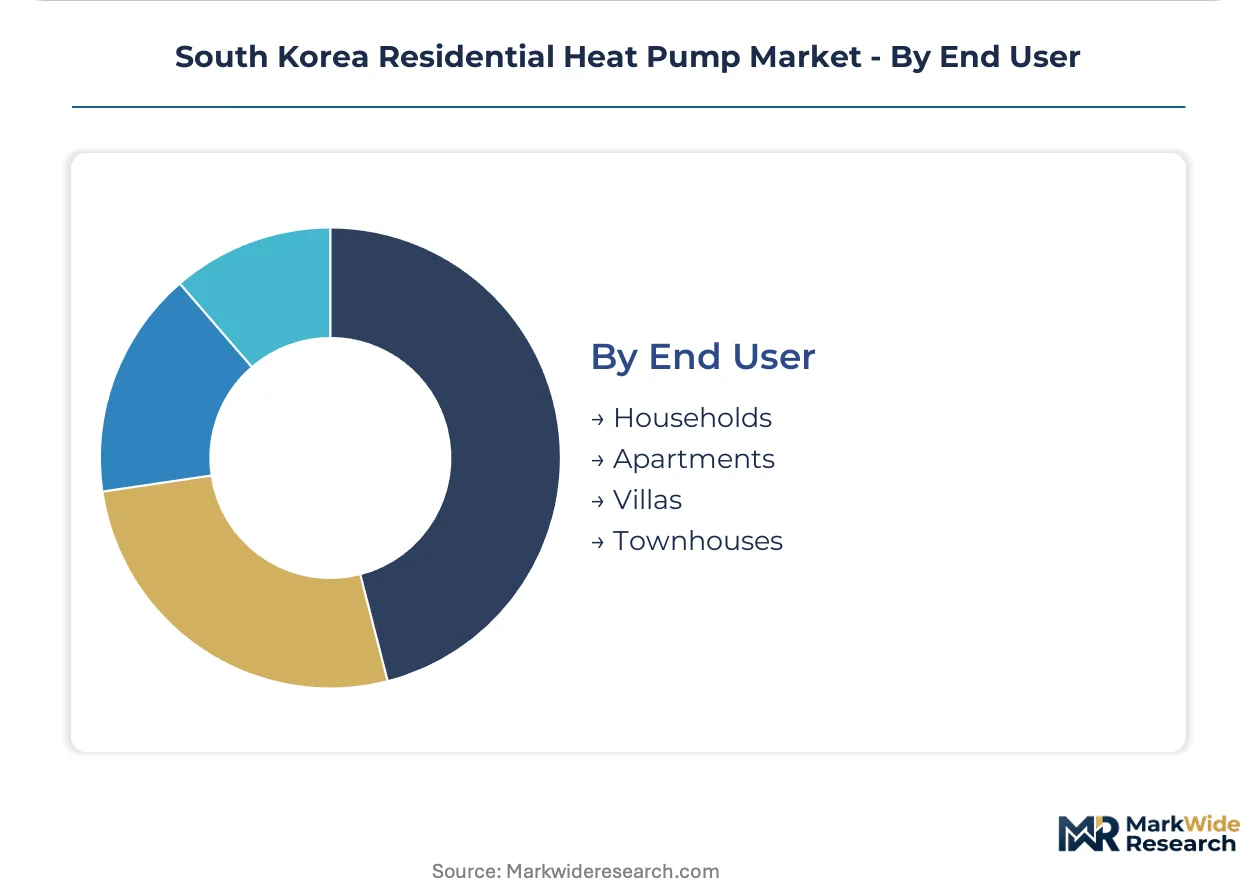
Customer type segmentation maps directly to regulatory exposure, with apartments facing the most stringent fossil-fuel restrictions and villas exhibiting highest discretionary technology adoption.
- Apartments:Multi-family complexes generate concentrated demand volume as Seoul and Gyeonggi Province municipal codes accelerate replacement cycles. Green New Deal retrofit mandates compress decision timelines for aging heating infrastructure.
- Villas:Detached single-family residences prioritize total cost of ownership calculations over capital expenditure minimization. Buyers in Seongnam and Yongin specify ground source and premium air source configurations for long-term operating efficiency.
- Townhouses:Row-house developments seek unified space conditioning platforms that eliminate redundant equipment. Variable-refrigerant-flow technology adoption concentrates in this segment.
- Households:Individual owner-occupiers across all dwelling types. Purchase deliberation cycles extend as retail channels in Gyeonggi Province report detailed ten-year operating cost modeling.
Apartments anchor absolute volume; villas deliver the highest revenue per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's residential heat pump market exhibits pronounced internal trade flows, with Seoul Capital Area consuming the majority of domestically manufactured units while component supply chains concentrate in southeastern industrial zones near Busan-Ulsan.
Seoul Capital Area
Multi-family apartment complexes in Seoul and Gyeonggi Province generate the densest demand concentration as municipal building codes now prohibit fossil-fuel-only heating in new construction. MFDS energy labeling requirements and KEMCO efficiency standards accelerate premium-tier product penetration by creating transparent operating cost comparisons. Installations cluster in Songpa-gu and Gangnam-gu districts where Green New Deal retrofit mandates compress replacement cycles for aging heating infrastructure.
Busan-Ulsan
Coastal residential developments in Busan metropolitan expansion zones drive underpenetrated demand as municipal codes increasingly mirror Seoul's fossil-fuel restrictions. The region's manufacturing base supplies inverter compressors and heat exchangers to domestic OEMs. Yongho-dong and Haeundae-gu villa developments specify ground source configurations where groundwater access permits simplify loop deployment.
Daegu-Gyeongbuk
Highland zones in Gangwon Province adjacent to this region experience cold-climate performance limitations, constraining air source deployment without auxiliary heating below minus 15 degrees Celsius. KEMCO seasonal testing protocols elevate certified cold-climate efficiency as a differentiator. Daegu's industrial corridor hosts component fabrication facilities serving national supply chains.
Daejeon-Sejong
Sejong City's planned residential developments incorporate centralized heat pump plants for unified energy management under national carbon neutrality roadmap compliance. Government administrative relocation programs concentrate housing stock with integrated smart-home infrastructure. Regulatory pilot programs here test refrigerant phase-down schedules before national rollout.
Gwangju-Honam
Slower urban density growth limits absolute demand volume relative to northern regions, though agricultural-to-residential land conversion creates greenfield installation opportunities. Local distribution networks extend from Busan-Ulsan manufacturing clusters. Honam region households exhibit extended purchase deliberation cycles as retail channels emphasize ten-year operating cost modeling.
South Korea Residential Heat Pump Market Competitive Landscape
Listed leaders compete with private specialists across technology certification tiers, with public companies leveraging capital market access for R&D scale while private operators retain flexibility in hybrid system development. The vendor base stratifies into three tiers: multinational HVAC conglomerates with inverter compressor captive supply, domestic chaebol-affiliated electronics groups with smart-home ecosystem leverage, and independent boiler-to-heat pump conversion specialists. Dominant competitive moves include backward integration into critical components and strategic partnerships with apartment complex developers for pre-installation specifications.
Within the multinational technology tier, Daikin Industries and Mitsubishi Electric exemplify archetypes built on refrigerant cycle R&D depth and regional distribution infrastructure. Among domestic chaebol-affiliated groups, LG Electronics and Samsung Electronics occupy positions leveraging consumer electronics retail channel control and smart-home platform integration. KD Navien anchors the independent specialist segment through gas-to-electric hybrid system expertise rooted in legacy boiler market presence.
| Leading Market Players |
|---|
| Daikin Industries |
| KD Navien |
| LG Electronics |
| Kiturami-Bumyang Air Conditioning |
| Shinsung Engineering |
| Mitsubishi Electric |
| Fujitsu General |
| Daesung Celtic Energy Systems |
| Samsung Electronics |
| Others |
Pricing and Supply Chain Analysis
MFDS energy labeling requirements and KEMCO efficiency standards gate both supply qualification and price differentiation simultaneously, compressing market access for uncertified manufacturers while elevating premium-tier pricing power among compliant suppliers. Household buyers in Seoul metropolitan apartment complexes prioritize transparent operating cost comparisons over upfront capital expenditure, reshaping how manufacturers calibrate cost-to-certification ratios across product portfolios.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by cold-climate performance certification grade and inverter compressor R&D depth. Price erosion runs through the standard tier as Chinese manufacturers expand presence in Gyeonggi Province retail channels. Villa developers exhibit lowest price sensitivity, prioritizing total cost of ownership calculations and ground source installation quality over capital expenditure minimization.
Supply Chain Analysis
Strategic stockpiling of copper cathode and neodymium magnet inventories characterizes Korean OEM procurement patterns, buffering against commodity volatility that compressed margins during recent price spikes. Manufacturing draws from concentrated supply bases in China, Japan, and domestic Busan-Ulsan industrial corridors. Single-source vulnerability around rare earth magnet processing creates structural risk exposure. Distribution runs through chaebol-affiliated electronics retail networks and specialized HVAC contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea residential heat pump market functions as a defensive-moat industry where regulatory entrenchment creates high switching costs for apartment complex buyers facing municipal fossil-fuel heating bans. MFDS certification requirements and Green New Deal retrofit mandates erect barriers that favor incumbent suppliers with established compliance pathways.
For Market Incumbents: Compound technology leadership in cold-climate inverter compressor performance through captive R&D investment, while securing backward integration into heat exchanger manufacturing to defend margin structures against copper price volatility. KD Navien's hybrid system expertise demonstrates how gas-to-electric conversion capabilities neutralize substitution threats from legacy boiler infrastructure during regulatory transition periods. For New Entrants and Emerging Players: Lead with smart-home ecosystem integration as a differentiated go-to-market angle, targeting Busan metropolitan expansion zones where municipal codes increasingly mirror Seoul's fossil-fuel restrictions but incumbent channel control remains less entrenched. Variable-refrigerant-flow technology adoption in Yongin and Seongnam townhouse developments represents the most penetrable white-space segment for unified space conditioning platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed HVAC conversion specialists possessing hybrid gas-to-electric system expertise and established apartment complex developer relationships. The five-to-ten year viability window favors acquisition targets with demonstrated MFDS premium-tier certification and installation capacity scaling in Gyeonggi Province. Refrigerant phase-down schedule acceleration under Korea's national carbon neutrality roadmap serves as the critical inflection signal warranting portfolio rebalancing toward low-global-warming-potential R&D leaders.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor R&D Scale-Up | Daikin Industries sustains cold-climate performance leadership through captive technology development. |
| Hybrid System Portfolio Expansion | KD Navien bridges regulatory transitions by converting legacy gas boiler infrastructure. |
| Smart-Home Platform Integration | LG Electronics leverages consumer electronics retail control for unified appliance command. |
| Refrigerant Transition Compliance | Early low-GWP alternative adoption positions suppliers for tightened MFDS phase-down deadlines. |
| Busan Metropolitan Channel Buildout | Underpenetrated coastal demand opens expansion corridors as municipal codes tighten fossil restrictions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with HVAC manufacturer product managers, apartment complex developer procurement leads, KEMCO certification engineers, and specialized installation contractors; alongside secondary validation through MFDS energy labeling databases, KEMCO efficiency standard filings, Korean customs trade statistics, and Green New Deal policy implementation records. Bottom-up unit shipment modeling triangulated against top-down construction permit analysis across Seoul Capital Area municipalities.
Across the analysis window, forecasts applied segmented growth rate derivation across product type, capacity band, installation architecture, and end-user dwelling category. Coefficient-of-performance degradation curves at sub-zero temperatures informed regional penetration assumptions for Gangwon Province highland zones. Apartment complex replacement cycle compression under retrofit mandates and villa new-build specification rates served as primary demand drivers.
Forecasts assume regulatory continuity in MFDS labeling regimes and municipal fossil-fuel heating restrictions; material policy shifts would require re-modeling. Copper and rare earth commodity volatility, refrigerant handling technician certification bottlenecks, and ground source drilling permit timeline extensions represent specific revision triggers. Revision becomes warranted when cold-climate performance certification thresholds under KEMCO seasonal testing protocols cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Global Energy Consumption Market
Energy Management
Global Utility Asset Management Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Thermostat Market
Energy Management
Brazil Energy Sector Market
Energy Management
Germany Demand Response Management Systems Market
Energy Management
Energy Management Market
Energy Management
Demand Response Management System Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
Power SCADA Market
Energy Management
Smart Power Management Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Heat Meter Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market