
 Japan Sealants Market | 2026-2036
Japan Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Sealants Market Foresight
JIS A 5758 qualification is rotating toward moisture-cure silicone and modified-silane hybrids, filtering out suppliers lacking certified weathering performance. Shin-Etsu Chemical sustains captive silane production from upstream chlorosilane operations. ThreeBond Holdings dominates automotive underhood sealing with anaerobic and room-temperature-vulcanizing portfolios. Henkel AG & Co. KGaA extends construction adhesive-sealant bundling through professional channel partnerships.
Japan sealants are polymeric compounds formulated to fill joints, gaps, and interfaces while retaining flexibility across temperature cycles from minus thirty to plus ninety degrees Celsius; they cure through moisture reaction, solvent evaporation, or thermal activation to prevent air and water ingress in structural assemblies. Silicone leads product value due to architectural specification lock-in and fifty-year durability claims, while polyurethane competes in automotive body sealing where paint compatibility and crash-energy absorption matter. Reactive technology captures margin pools in electronics potting as manufacturers reject solvent-based systems under METI chemical management guidelines.
METI enforces chemical substance reporting under the Act on the Evaluation of Chemical Substances, pushing formulators toward low-VOC water-based and hot-melt platforms. JIS standards and local prefectural building codes govern fire resistance and elastic recovery in curtainwall applications, creating compliance barriers for imported products. PMDA oversight intersects where medical-grade sealants enter device assemblies. Stakeholders must track METI's next amendment cycle for perfluorinated compound restrictions and align R&D roadmaps accordingly.
Market Dynamics
Japan's sealants sector faces a structural pivot as METI chemical management guidelines phase out solvent-based formulations, forcing formulators to rebuild product architectures around moisture-cure silicones and hot-melt reactive systems while absorbing raw material cost volatility from chlorosilane supply chains.
Growth Catalysts
- Building Standards Act amendments:Stricter energy performance criteria for commercial envelopes in Osaka Prefecture and Tokyo are retrofitting demand toward high-performance silicone sealants with certified weathering performance.
- Automotive electronics clustering:Toyota City's concentration of electronics assembly is pulling hot-melt reactive formulations for potting and underhood sealing applications.
- JIS A 5758 rotation:The qualification standard's shift toward moisture-cure silicone and modified-silane hybrids is filtering out uncertified suppliers and consolidating specification lock-in.
Market Restraints
- Chlorosilane input concentration:Captive silane production from upstream chlorosilane operations limits independent formulator access to critical raw materials, concentrating supply risk with integrated chemical conglomerates.
- Prefectural code fragmentation:Local building codes governing fire resistance and elastic recovery in curtainwall applications create compliance barriers for imported products entering Japan's construction channel.
- Perfluorinated compound uncertainty:METI's pending amendment cycle for perfluorinated restrictions is freezing R&D roadmaps as formulators await clarity on banned substance lists.
Strategic Opportunities
- Kansai retrofit wave:High-rise building stock in Osaka Prefecture built during the 1980s bubble era is reaching envelope renewal cycles, creating concentrated demand for facade sealant replacement.
- Medical device convergence:PMDA oversight intersections where medical-grade sealants enter device assemblies are opening specialized margin pools beyond construction and automotive.
- Water-based platform migration:Low-VOC water-based formulations are capturing share from solvent systems as METI enforcement tightens under the Act on the Evaluation of Chemical Substances.
Industry Challenges
- JIS certification timeline compression:Weathering performance testing cycles for A 5758 qualification are extending lead times, straining working capital for mid-tier formulators.
- Formulation chemistry retooling:Shifting from solvent evaporation to moisture-cure or thermal activation cure mechanisms requires capital investment in mixing and dispensing equipment.
- Cross-functional talent scarcity:Polymer chemists with combined expertise in silicone synthesis and construction application engineering command premium compensation, constraining R&D expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Sealants Market |
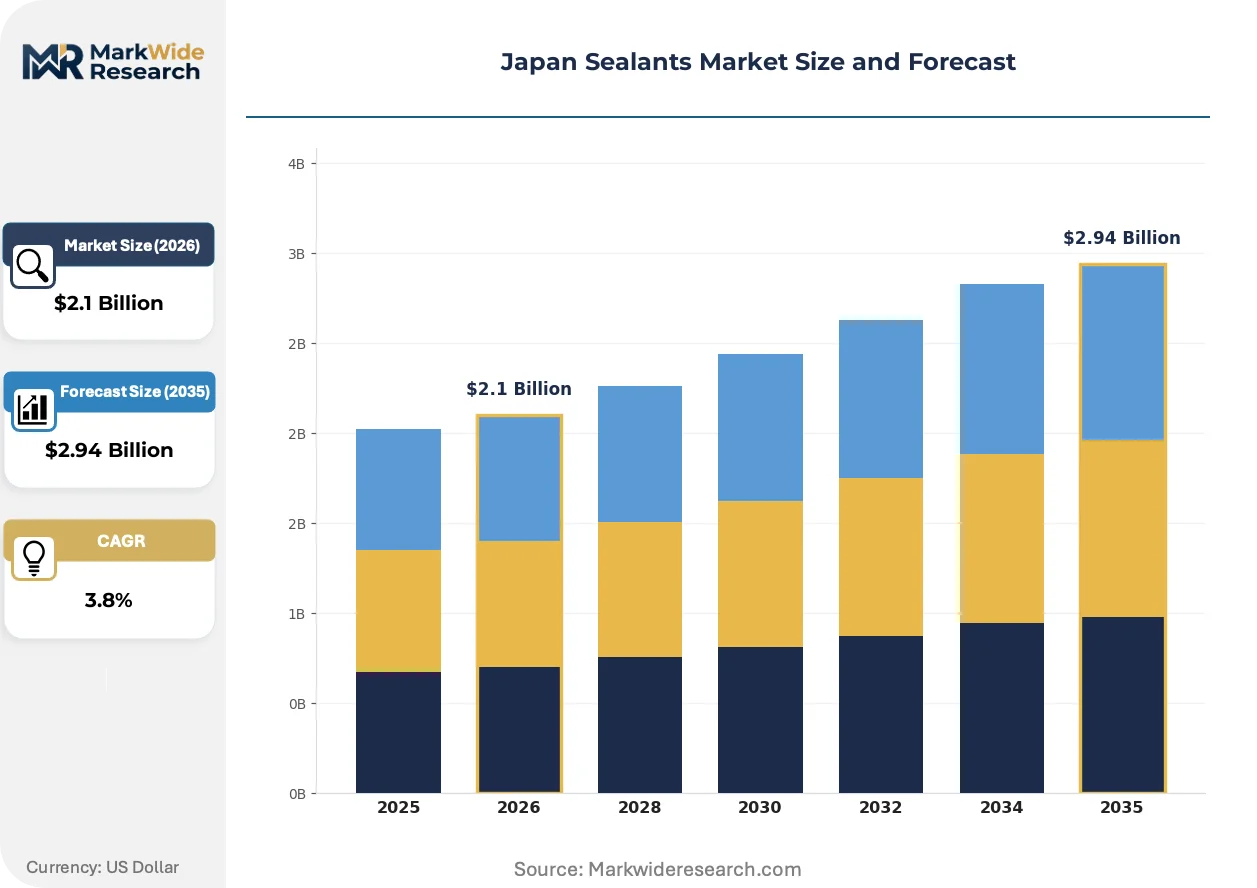
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Butyl Application: Construction, Automotive, Electronics, Aerospace End User: Contractors, Manufacturers, DIY Consumers, Retailers Technology: Solvent-Based, Water-Based, Hot Melt, Reactive |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Sika AG, 3M, ThreeBond Holdings Co., Ltd., CEMEDINE Co., Ltd., THE YOKOHAMA RUBBER CO., LTD., Henkel AG & Co. KGaA, Aica Kogyo Co., Ltd., Konishi Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Sealants Market Shifts & Advancements
Formulation chemistry is undergoing forced evolution as regulatory pressure and end-use performance requirements collide, with cure mechanisms, raw material architectures, and procurement specifications all in simultaneous flux across Japan's construction and automotive channels.
Modified-silane hybrid sealants are decomposing the traditional silicone-polyurethane product boundary by combining silicone weathering durability with polyurethane paint compatibility and primerless adhesion. Automotive body shops in Nagoya and construction contractors in Yokohama are specifying these hybrids for crash-energy absorption and facade applications respectively. This convergence is decomposing the historical segmentation where silicone dominated architecture and polyurethane dominated transportation, compressing margin pools as suppliers compete across previously distinct specification territories.
METI's Act on the Evaluation of Chemical Substances is accelerating substance-by-substance reporting requirements that push formulators toward pre-registered polymer architectures. Industrial consequence includes frozen formulation pipelines as legal teams await substance hazard classifications before R&D commits. Electronics potting and medical device assembly segments are most affected, with manufacturers rejecting unregistered raw materials even where technical performance is superior.
Specification-driven procurement is consolidating buyer power as general contractors bundle adhesive-sealant packages across multiple project phases. Professional channel partnerships with certified applicator networks are displacing traditional distributor relationships in Tokyo and Osaka construction markets. This consolidation is most visible in commercial envelope projects where JIS A 5758 certification serves as a prequalification filter, excluding non-certified suppliers from bidding processes regardless of price competitiveness.
Japan Sealants Market Segmentation
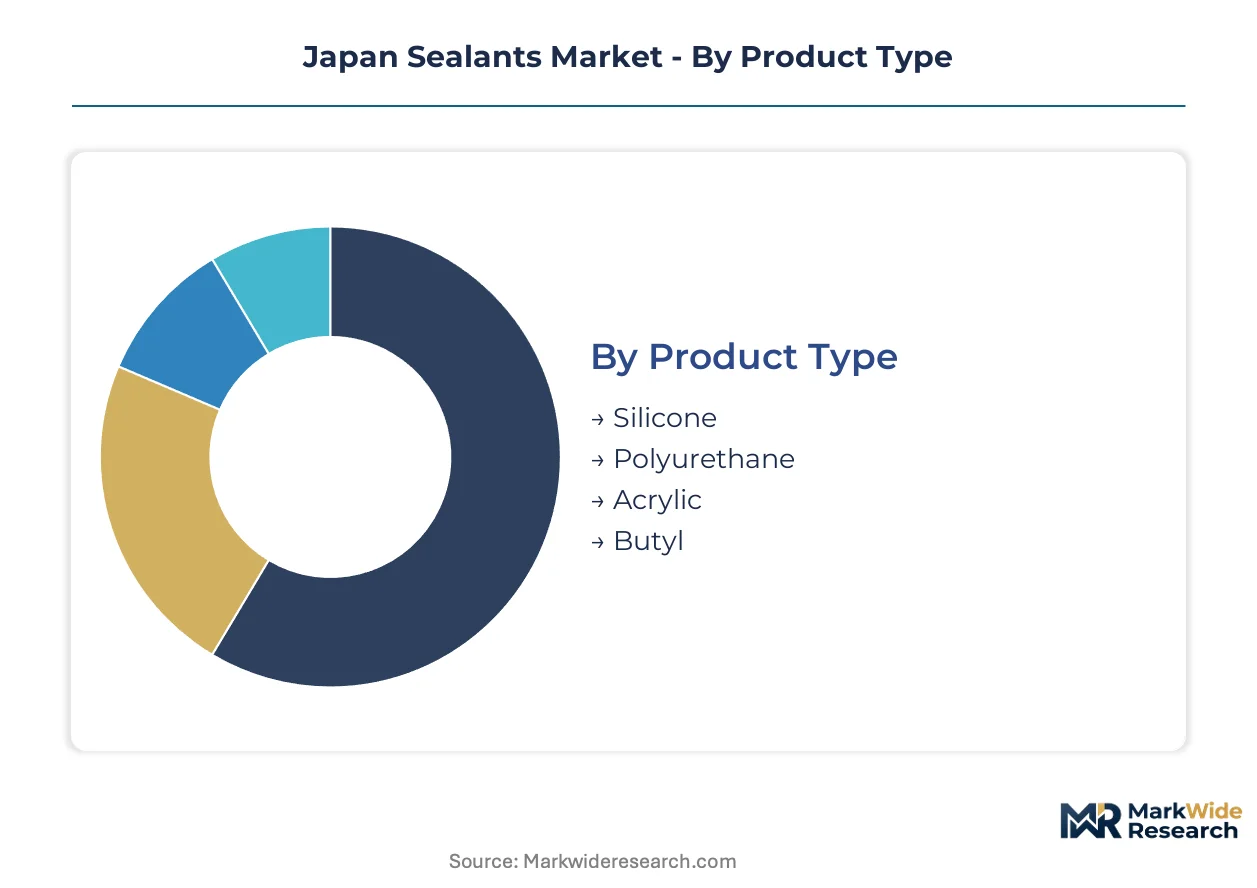
Segmentation in Japan's sealants market reveals how METI regulatory pressure and JIS certification requirements channel demand toward specific formulations and procurement relationships. Understanding these segment boundaries exposes where specification lock-in concentrates margin pools and where technology transitions are fragmenting established supply hierarchies.
Product Type:
Silicone commands professional distribution through certified applicator networks, while polyurethane and acrylic compete through construction material wholesalers; butyl routes primarily through automotive OEM supply chains.
- Silicone:Moisture-cure formulations dominate architectural specification with fifty-year durability claims and JIS A 5758 weathering certification. Osaka Prefecture's high-rise retrofit wave is concentrating procurement through general contractor bundled packages.
- Polyurethane:Paint-compatible elastomers absorb crash energy in automotive body sealing, competing with modified-silane hybrids for specification share. Toyota City electronics clustering pulls demand for primerless adhesion grades.
- Acrylic:Water-based acrylics capture interior construction applications under METI low-VOC enforcement.
- Butyl:Preformed tapes seal automotive glazing and HVAC ductwork through captive OEM supply agreements.
Silicone dominates installed base. Modified-silane hybrids are where expansion concentrates.
Application:
Cost tier stratification separates specification-grade envelope sealing from commodity interior applications, with automotive and electronics commanding premium formulations.
- Construction:Curtainwall and facade sealing absorb the highest formulation costs, with JIS fire resistance and elastic recovery standards filtering supplier participation. Prefectural code fragmentation in Tokyo and Osaka creates compliance barriers for imported alternatives.
- Automotive:Underhood sealing and electronics potting demand hot-melt reactive systems as manufacturers reject solvent-based chemistries. ThreeBond Holdings and Henkel channel partnerships control specification access.
- Electronics:Potting compounds for PCB protection require METI-registered polymer architectures, freezing pipelines pending substance hazard classifications.
- Aerospace:Specialized grades for cabin pressure sealing and fuel tank applications serve narrow defense and commercial aviation supply chains.
Construction absorbs volume scale. Automotive electronics is climbing the fastest.
End User:
Customer type determines procurement leverage, with contractors bundling adhesive-sealant packages while DIY consumers remain price-sensitive at retail.
- Contractors:General contractors in Tokyo and Osaka consolidate specification power across multi-phase commercial projects, using JIS A 5758 certification as prequalification filter.
- Manufacturers:Automotive and electronics OEMs demand formulation stability and raw material traceability, favoring suppliers with captive chlorosilane production.
- DIY Consumers:Home improvement retailers stock commodity silicone and acrylic cartridges for interior sealing applications.
- Retailers:Professional channel partnerships are displacing traditional distributor relationships in construction markets.
Contractors dominate specification flow. Manufacturers are where margin pools deepen.
Technology:
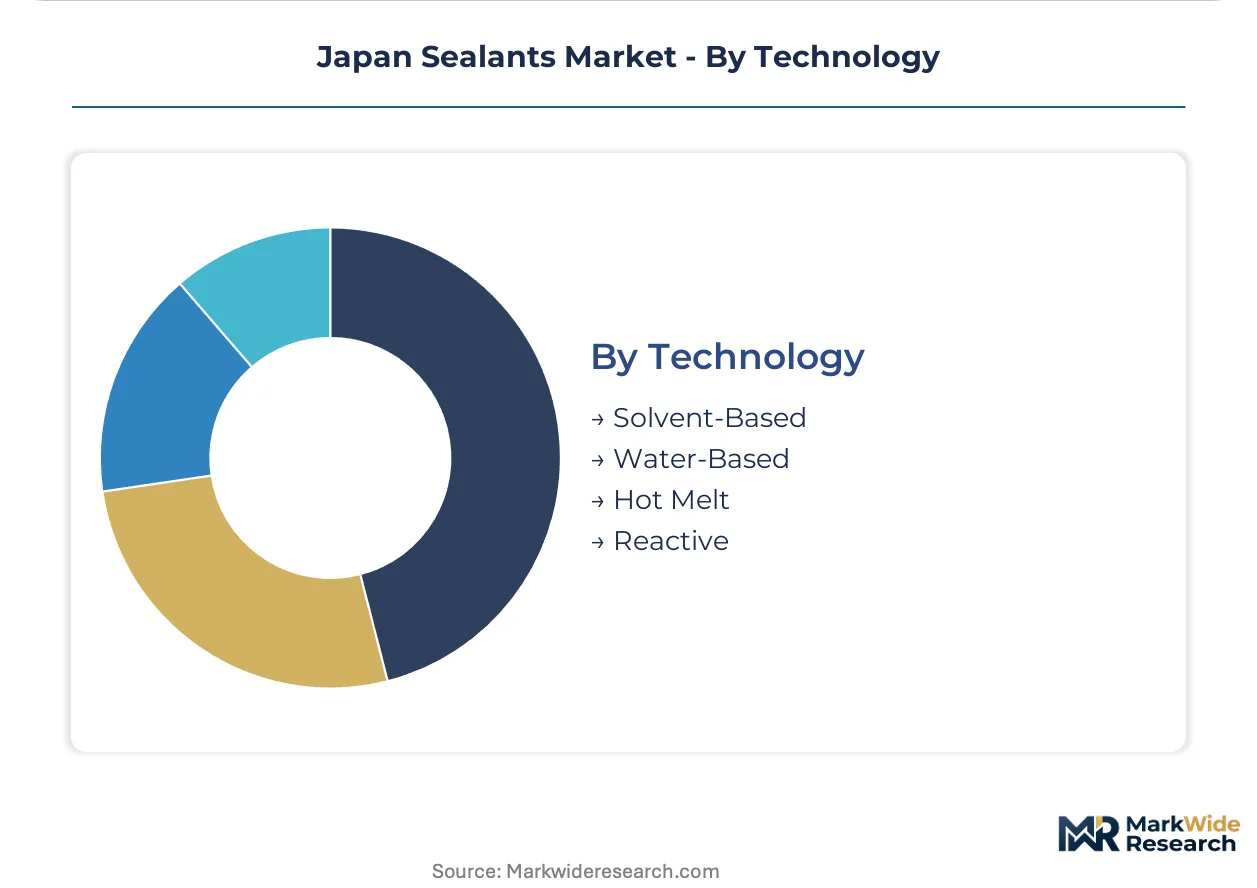
Maturity gradient separates declining solvent platforms from emerging reactive systems, with water-based formulations capturing regulatory-driven substitution.
- Solvent-Based:Declining share under METI Act on the Evaluation of Chemical Substances enforcement; remaining demand concentrates in legacy industrial maintenance applications.
- Water-Based:Low-VOC acrylics and hybrids gain construction interior share as chlorosilane cost volatility squeezes silicone margins.
- Hot Melt:Reactive polyurethanes dominate automotive electronics potting with thermal activation cure; Toyota City clustering concentrates demand.
- Reactive:Moisture-cure silicones and modified-silane hybrids represent the technology pivot, requiring capital investment in mixing and dispensing equipment.
Reactive technology commands R&D investment. Water-based platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's amended Building Standards Act and chemical substance reporting requirements are redistributing sealant demand across Japan's industrial prefectures, with energy retrofit mandates and automotive electronics clustering creating concentrated procurement zones.
Kanto/Tokyo
Tokyo's commercial envelope retrofit wave drives specification-grade silicone procurement through general contractor bundled packages. METI enforces stricter energy performance criteria for high-rise buildings under amended national codes. Curtainwall contractors in central Tokyo concentrate JIS A 5758 certified weathering performance demand.
Kansai/Osaka
Osaka Prefecture's 1980s bubble-era building stock reaches envelope renewal cycles, creating facade sealant replacement demand. Local prefectural building codes govern fire resistance and elastic recovery requirements. Construction contractors in Osaka City expand silicone sealant procurement for high-rise retrofit projects.
Chubu/Nagoya
Toyota City's automotive electronics assembly clustering pulls hot-melt reactive formulations for potting and underhood sealing. Manufacturers reject solvent-based systems under METI chemical management guidelines. Electronics potting compound demand concentrates around PCB protection applications.
Kyushu
Fukuoka's expanding semiconductor packaging operations generate demand for medical-grade sealants entering device assemblies. PMDA oversight intersects with specialized formulation requirements. Industrial sealant distributors in northern Kyushu serve aerospace and defense supply chains.
Tohoku
Sendai's post-disaster reconstruction infrastructure maintains steady construction sealant consumption. Prefectural procurement favors low-VOC water-based formulations under regional environmental guidelines. Local applicator networks consolidate specification access for public works projects.
Japan Sealants Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive chlorosilane production and specialized automotive sealing specialists. Market structure concentrates around upstream-integrated silicone producers and formulation specialists serving distinct end-use channels. Three strategic archetypes dominate: integrated silane producers controlling raw material access, automotive-focused reactive formulation specialists, and construction channel bundlers leveraging professional partnerships. Competitive moves center on JIS certification acquisition and applicator network expansion.
Within the integrated chemical tier, Shin-Etsu Chemical Co., Ltd. exemplifies upstream-integrated positioning through captive chlorosilane operations. ThreeBond Holdings Co., Ltd. and Henkel AG & Co. KGaA occupy distinct specialist positions—ThreeBond anchoring automotive underhood sealing archetypes while Henkel represents construction adhesive-sealant bundling through professional channel partnerships. These three companies collectively illustrate how raw material control, end-use specialization, and distribution integration define competitive positioning in METI-regulated formulation markets.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Sika AG |
| 3M |
| ThreeBond Holdings Co., Ltd. |
| CEMEDINE Co., Ltd. |
| THE YOKOHAMA RUBBER CO., LTD. |
| Henkel AG & Co. KGaA |
| Aica Kogyo Co., Ltd. |
| Konishi Co., Ltd. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between chlorosilane producers and silicone formulators lock in supply access while stabilizing input price visibility across the forecast period. These arrangements concentrate procurement leverage with integrated chemical conglomerates in Japan, leaving independent formulators exposed to spot market volatility for critical silane intermediates.
Pricing Analysis
Certification level under JIS A 5758 creates the primary spread between specification-grade silicone and commodity alternatives. Three-tier pricing structure across JIS-certified premium, prefectural-compliant standard, and uncertified economy levels segments buyer access. Cost compression in standard tiers is intensifying because chlorosilane feedstock volatility squeezes formulator margins. DIY consumers remain most price-sensitive, while general contractors bundling multi-phase projects absorb premium certification costs.
Supply Chain Analysis
Extended weathering performance testing cycles for JIS qualification are stretching inventory lead times beyond twelve months for mid-tier formulators. Captive chlorosilane production in Japan draws from upstream petrochemical complexes in South Korea and Taiwan, with secondary sourcing from domestic specialty chemical producers. Single-source vulnerability concentrates around Shin-Etsu's silane monomer output. Distribution runs through certified applicator networks in Tokyo and Osaka, displacing traditional construction material wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japan sealants market rewards polymer chemists who bridge silicone synthesis expertise with construction application engineering, yet this cross-functional talent pool remains critically thin. Formulators who secure this capability gap will capture specification lock-in as JIS A 5758 qualification filters intensify.
For Market Incumbents: Shield specification-grade positioning by deepening captive chlorosilane supply and accelerating JIS A 5758 certification renewal ahead of METI's perfluorinated compound amendment cycle. Expand certified applicator networks in Osaka Prefecture to capture high-rise retrofit procurement bundles before competitors consolidate channel access. For New Entrants and Emerging Players: JIS A 5758 fast-track partnerships with established testing laboratories offer the most viable entry path. Target water-based acrylic formulations for interior construction applications where METI low-VOC enforcement is displacing solvent systems. Position through construction material wholesalers in secondary prefectures before attempting Tokyo contractor network penetration. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier formulators with reactive technology platforms and pending JIS certification pipelines. Long-term viability hinges on backward integration into chlorosilane supply or exclusive offtake arrangements with integrated producers. Watch METI's perfluorinated substance ban list publication as the critical inflection signal for R&D roadmap freezes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane | Secures raw material access against Shin-Etsu's supply concentration and spot price volatility. |
| JIS A 5758 Certification Fast-Track | Unlocks bidding eligibility for Tokyo and Osaka general contractor bundled packages. |
| Modified-Silane Hybrid Platform Launch | Captures specification share across both architectural facade and automotive body applications. |
| Certified Applicator Network Expansion | Displaces traditional distributor relationships in professional construction channels. |
| Water-Based Formulation Migration | Aligns product portfolios with METI Act on the Evaluation of Chemical Substances enforcement trajectory. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with construction procurement managers at general contractors, automotive Tier 1 sealing engineers, electronics potting compound specialists, and distribution channel partners in Tokyo and Osaka. Secondary validation drew from METI chemical substance reporting databases, JIS standards documentation, prefectural building code amendments, customs trade records, and SEC filings of listed chemical conglomerates. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and technology segments.
Across the analysis window, the forecasting framework modeled demand drivers including building envelope retrofit cycles, automotive electronics clustering, and regulatory substitution effects. Segmentation dimensions encompassed formulation chemistry, cure mechanism, end-use industry, and regional prefectural demand concentration. CAGRs were derived from regression analysis of historical procurement patterns and projected specification rotation timelines, incorporating chlorosilane supply elasticity and JIS certification pipeline constraints as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of stable METI enforcement intensity and no radical JIS standard revision; material deviation in perfluorinated compound restrictions or building code harmonization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
France Adhesives Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Russia Sealants Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Asia-Pacific Sealants Market