
 Global Isobutyl Acrylate Market | 2026-2036
Global Isobutyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Isobutyl Acrylate Market Foresight
Packaging manufacturers is redrawing demand patterns for isobutyl acrylate as flexible food packaging and pressure-sensitive label applications expand. BASF SE leverages its integrated acrylic acid value chain to secure feedstock reliability across European and Asian operations. Mitsubishi Chemical Corporation anchors supply continuity through captive butanol production and coastal manufacturing infrastructure in Japan. Arkema Group differentiates via specialty-grade purification capabilities that serve pharmaceutical and electronics-adjacent adhesive markets.
Isobutyl acrylate is an acrylic ester monomer synthesized through esterification of acrylic acid with isobutanol, typically exhibiting a molecular weight of approximately 128.17 g/mol, a glass transition temperature near -45°C, and polymerization reactivity suited for pressure-sensitive and hot-melt adhesive formulations. Its primary commercial purpose centers on imparting tack, flexibility, and low-temperature performance to polymers used in packaging adhesives, automotive sealants, and textile binders. Purified Grade commands premium positioning in medical and electronics applications where residual acid content must fall below 0.05%, while Technical Grade dominates volume throughput in construction and general industrial adhesives. Adhesives application represents the deepest margin pool due to formulation complexity and customer stickiness, whereas Polymer Modification is gaining fastest as compatibilizer demand rises in multi-layer film structures.
REACH registration through ECHA governs monomer import thresholds and purity declarations across European supply chains, while EPA oversight under the Toxic Substances Control Act mandates pre-manufacture notification for novel isobutyl acrylate derivatives in the United States. China's GB standards administered by SAMR set VOC emission limits for adhesive formulations containing acrylic esters, directly influencing domestic formulation practices and export qualification protocols. Stakeholders must monitor regulatory divergence between European hazard classification updates and Asian emission control regimes when siting new production or reformulating existing product lines.
Market Dynamics
Flexible packaging converters are pulling isobutyl acrylate demand toward higher-purity grades as food-contact adhesive specifications tighten under evolving chemical safety frameworks across multiple jurisdictions.
Growth Catalysts
- Pressure-sensitive label expansion:E-commerce fulfillment centers in Germany and the United States are consuming specialty-grade acrylic esters for high-speed label application systems.
- REACH registration thresholds:ECHA's monomer purity declarations are filtering out sub-scale suppliers and consolidating qualified vendor lists for European adhesive formulators.
- Hot-melt adhesive reformulation:Automotive sealant manufacturers are substituting solvent-based systems with reactive hot-melt platforms built on isobutyl acrylate copolymers.
Market Restraints
- Acrylic acid feedstock volatility:Propylene price swings transmit directly into isobutyl acrylate production economics, compressing margin predictability for non-integrated producers.
- Supplier geographic concentration:Coastal manufacturing clusters in China and Japan control disproportionate share of Asian export volume, creating single-point vulnerability for European and North American buyers.
- UV-curable substitute penetration:Electron-beam and UV-initiated acrylate oligomers are capturing share in graphic arts and electronics laminating applications where instant cure cycles outweigh tack requirements.
Strategic Opportunities
- Indian adhesive sector formalization:BIS certification requirements for packaging adhesives are creating first-mover advantage for purified-grade suppliers establishing local technical service presence.
- Medical-grade polymer demand:Transdermal patch and wound-care film manufacturers are specifying sub-0.05% residual acid content, opening premium positioning for specialty purification operators.
- GB standard VOC alignment:SAMR's emission limits for adhesive formulations are pushing Chinese domestic producers toward higher-purity ester inputs to maintain export qualification.
Industry Challenges
- Specialized polymer chemistry expertise:Formulation-scale-up from pilot to commercial production requires rare combinations of free-radical kinetics knowledge and adhesive application engineering.
- Multi-jurisdiction registration synchronization:Maintaining concurrent EPA pre-manufacture notification, REACH dossier validity, and NMPA chemical inventory compliance stretches regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Isobutyl Acrylate Market |
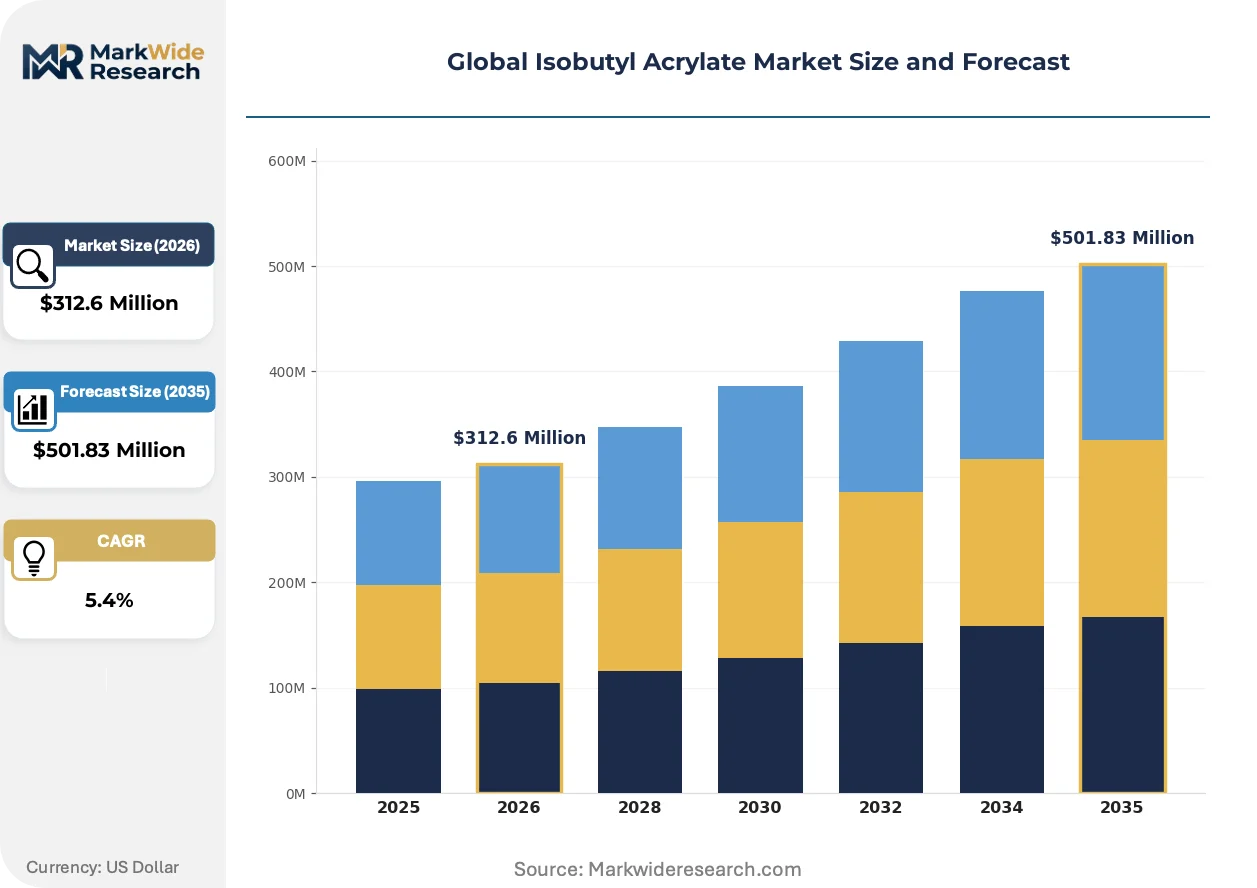
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $501.83 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purified Grade, Technical Grade, Polymer Grade, Resin Grade Application: Adhesives, Paints & Coatings, Textile Finishing, Polymer Modification End Use Industry: Packaging Manufacturers, Construction Material Suppliers, Textile Producers, Chemical Formulators Packaging Type: Drums, Intermediate Bulk Containers, Totes, Bulk Tankers |
| Companies Covered | BASF SE, Mitsubishi Chemical Corporation, Arkema Group, Nippon Shokubai Co., Ltd., Dow Chemical Company, Osaka Organic Chemical Industry Ltd., Formosa Plastics Corporation, Wanhua Chemical Group Co., Ltd., LG Chem Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Isobutyl Acrylate Market Shifts & Advancements
Bio-based feedstock pathways and reactive processing technologies are restructuring how isobutyl acrylate derivatives enter adhesive value chains, with sustainability credentials and cure-speed performance emerging as dual selection criteria.
Continuous stirred-tank reactor designs with inline spectroscopic monitoring are supplanting batch esterification for high-volume adhesive-grade production. Packaging adhesive specialists in the Netherlands and South Korea are adopting these systems to reduce lot-to-lot variability. The technology is compressing qualification timelines for multinational food brands demanding certificate-of-analysis consistency.
REACH Annex XVII restrictions on residual monomer content in finished adhesives are forcing reformulation of legacy pressure-sensitive tape constructions. European tape laminators are shifting toward pre-reacted oligomer solutions rather than monomer-rich formulations. Medical and electronics adhesive segments are absorbing the steepest compliance costs, passing specifications upstream to ester suppliers.
Direct mill procurement of acrylic esters is displacing distributor intermediaries among large-scale adhesive compounders in China and Germany. Tier-one packaging converters are establishing annual volume contracts with integrated acid-ester producers, extracting price transparency and supply priority. The behavior is most pronounced in flexible food packaging, where formulation consistency underpins brand-owner audit requirements.
Global Isobutyl Acrylate Market Segmentation
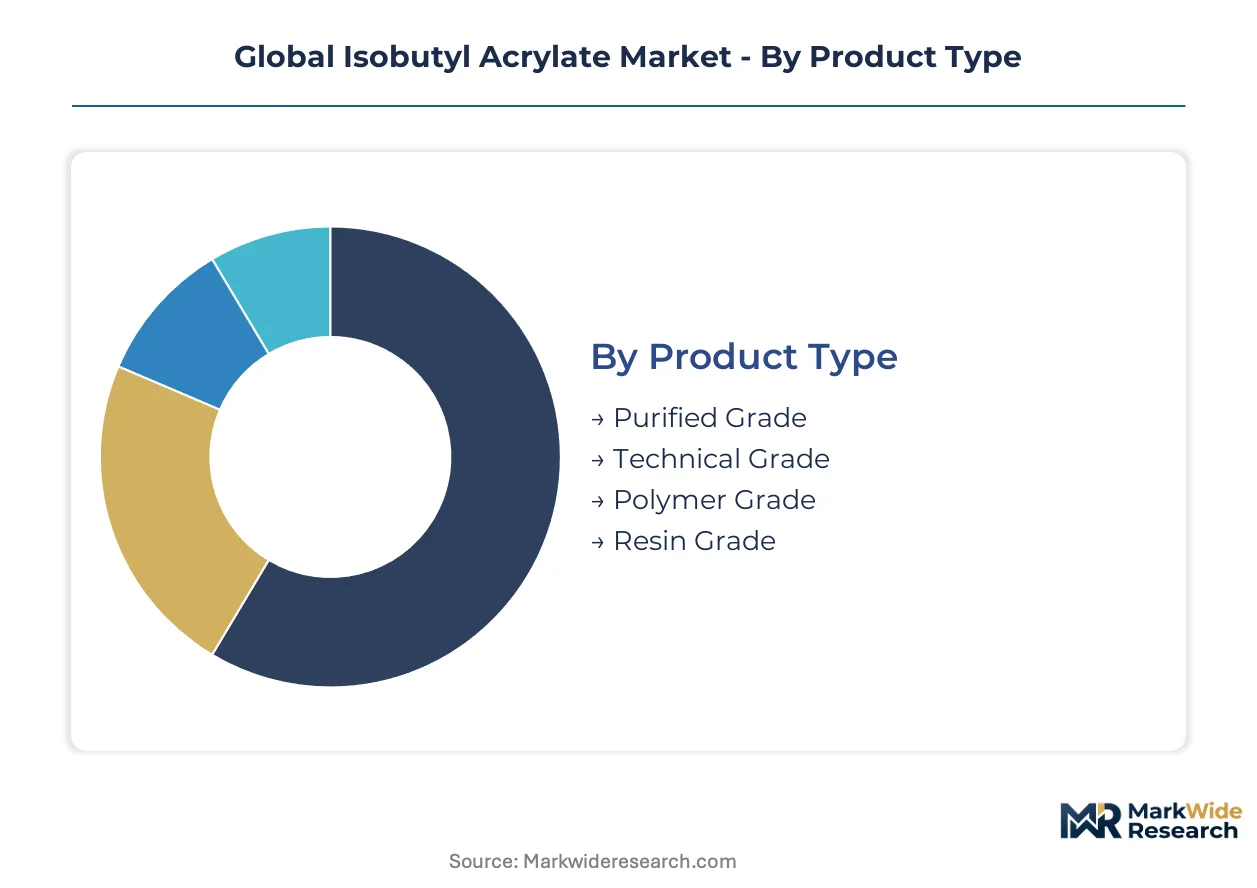
Segmentation in isobutyl acrylate reveals how purity specifications and packaging formats split procurement channels. Adhesive formulators, paint manufacturers, and textile finishers each trigger distinct supply chain configurations and margin structures.
Product Type:
Channel flow splits sharply by grade: specialty distributors handle sub-0.05% residual acid specifications for medical and electronics buyers, while bulk terminals move technical grades to construction adhesive compounders.
- Purified Grade:Residual acid content below 0.05% serves transdermal patch and wound-care film manufacturers where biocompatibility testing is mandatory. Medical device producers in Germany and Japan specify this grade exclusively, with SAMR's GB standards pushing Chinese domestic suppliers toward equivalent purity to maintain export qualification.
- Technical Grade:Standard esterification output dominates volume throughput in construction sealants and general industrial adhesives. Pressure-sensitive tape laminators in the United States consume this grade through annual volume contracts with integrated acid-ester producers, extracting supply priority and certificate-of-analysis consistency.
- Polymer Grade:Controlled molecular weight distribution suits reactive hot-melt automotive sealant platforms. Tier-one packaging converters specify this grade for food-contact adhesive consistency under evolving chemical safety frameworks.
- Resin Grade:Higher oligomer content serves textile binder and leather finishing applications where film-forming properties outweigh monomer reactivity. Chemical formulators in India source this grade through BIS-certified channels as adhesive sector formalization accelerates.
Technical Grade dominates installed base. Purified Grade is where expansion concentrates.
Application:
Cost tier stratification separates formulation complexity: high-margin specialty adhesives command premium ester inputs, while commodity coatings run on standard grades with compressed conversion economics.
- Adhesives:Pressure-sensitive, hot-melt, and construction sealant formulations absorb the deepest margin pool due to customer stickiness and specification lock-in. E-commerce fulfillment centers in Germany and the United States are pulling demand toward specialty-grade acrylic esters for high-speed label application systems.
- Paints & Coatings:Automotive refinish and industrial protective coatings leverage isobutyl acrylate copolymers for gloss retention and weatherability. REACH Annex XVII restrictions on residual monomer content are forcing reformulation of legacy solvent-borne systems toward pre-reacted oligomer solutions.
- Textile Finishing:Fabric binders and nonwoven saturants require controlled glass transition temperatures near -45°C for hand and drape properties. Textile producers in South Korea specify polymer-grade inputs through direct mill procurement contracts displacing distributor intermediaries.
- Polymer Modification:Compatibilizer demand in multi-layer film structures is climbing the fastest as packaging converters seek adhesion between dissimilar substrates. Flexible food packaging specifications under EFSA and FDA frameworks are tightening purity requirements for this application.
Adhesives commands revenue concentration. Polymer Modification is gaining share fastest.
End Use Industry:
Customer type determines order frequency and technical service intensity: multinational packaging brands demand certificate-of-analysis consistency, while construction suppliers prioritize volume pricing.
- Packaging Manufacturers:Flexible food packaging and pressure-sensitive label producers specify highest-purity grades with full regulatory documentation. Direct procurement from integrated producers is displacing distributor channels among large-scale compounders in China and Germany.
- Construction Material Suppliers:Sealant and waterproofing membrane manufacturers consume technical grades through regional bulk terminals. Propylene price volatility transmits directly into margin predictability for non-integrated producers serving this segment.
- Textile Producers:Nonwoven and technical fabric finishers source polymer-grade and resin-grade esters for binder saturation. Coastal manufacturing clusters in Japan anchor supply continuity through captive butanol production.
- Chemical Formulators:Custom adhesive and coating compounders blend multiple acrylic esters for niche applications. Multi-jurisdiction registration synchronization across EPA, REACH, and NMPA compliance stretches regulatory affairs bandwidth for formulators serving this segment.
Packaging Manufacturers anchors volume demand. Chemical Formulators is where margin expansion concentrates.
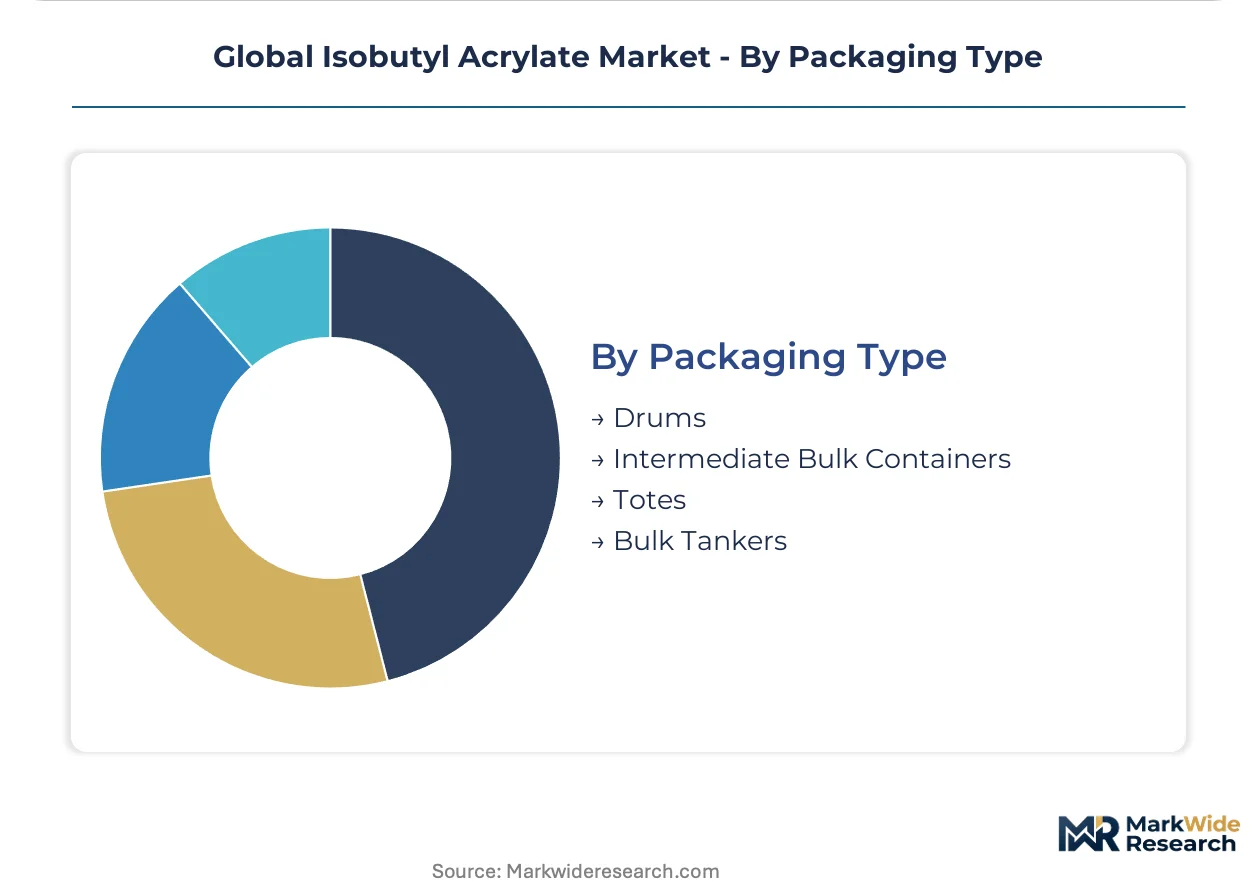
Packaging Type:
Supply concentration in coastal manufacturing clusters shapes logistics economics: drum shipments serve dispersed formulators, while bulk tankers feed integrated adhesive plants.
- Drums:Standard 200-liter steel containers serve small-to-mid adhesive compounders and specialty coating formulators requiring frequent batch turnover. REACH-registered suppliers in the Netherlands maintain drum filling lines with inline spectroscopic monitoring for lot-to-lot consistency.
- Intermediate Bulk Containers:1,000-liter flexible or rigid IBCs balance handling efficiency with formulation flexibility for mid-scale textile finishers and regional paint producers.
- Totes:Returnable and disposable tote systems serve chemical formulators with established logistics partnerships and consistent offtake patterns.
- Bulk Tankers:Dedicated rail and road tankers feed continuous stirred-tank reactor operations at large-scale adhesive plants in South Korea and Germany, compressing qualification timelines for multinational food brands.
Bulk Tankers dominates throughput volume. Intermediate Bulk Containers is where logistics innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan Deep Water Port anchors Asia-Pacific acrylic ester trade flows, handling concentrated bulk liquid chemical shipments that feed adhesive plants across the Yangtze River Delta manufacturing corridor.
China
Domestic acrylic acid capacity expansion in Ningbo and Zhenjiang is pulling regional isobutyl acrylate demand eastward. SAMR's GB standards on VOC emission limits for adhesive formulations are tightening purity specifications for export-qualified producers. Coastal manufacturing clusters in Jiangsu province now supply both domestic flexible packaging converters and Southeast Asian adhesive compounders.
Germany
Ludwigshafen's integrated chemical complex supports captive feedstock reliability for European adhesive formulators serving automotive sealant markets. ECHA's REACH registration thresholds filter sub-scale suppliers from qualified vendor lists. The Rhine-Main logistics corridor enables drum-to-bulk-tanker flexibility for multinational food packaging brands demanding certificate-of-analysis consistency.
United States
E-commerce fulfillment centers in Memphis and Louisville consume specialty-grade acrylic esters for high-speed pressure-sensitive label systems. EPA oversight under the Toxic Substances Control Act mandates pre-manufacture notification for novel derivatives. Gulf Coast propylene pipeline networks transmit price volatility directly into margin predictability for non-integrated ester producers.
Japan
Mitsubishi Chemical's coastal manufacturing infrastructure in Yokkaichi leverages captive butanol production for supply continuity. METI's chemical inventory compliance frameworks align with REACH dossier requirements for pharmaceutical-grade exports. The Keihin industrial belt concentrates purified-grade capacity serving transdermal patch manufacturers in Germany and the United States.
India
BIS certification requirements for packaging adhesives are formalizing procurement channels in Maharashtra and Gujarat. CDSCO's medical device regulations create premium positioning for sub-0.05% residual acid grade suppliers. Mundra Port's liquid chemical terminals enable direct mill procurement by large-scale adhesive compounders displacing distributor intermediaries.
Global Isobutyl Acrylate Market Competitive Landscape
Concentration sits with integrated petrochemical conglomerates controlling acrylic acid value chains. BASF SE and Dow Chemical Company anchor supply continuity through backward integration into propylene feedstocks. The vendor base stratifies across three tiers: multinational integrated producers, Asian chemical conglomerates with coastal manufacturing infrastructure, and regional specialty ester purifiers. Capacity expansion and direct procurement contracting represent the dominant competitive moves, as large-scale adhesive compounders extract price transparency through annual volume agreements.
Within the integrated multinational tier, BASF SE exemplifies feedstock control across European and Asian operations. Mitsubishi Chemical Corporation anchors Japanese supply continuity through captive butanol production. Arkema Group occupies a position in specialty-grade purification serving pharmaceutical-adj adhesive markets. These three represent distinct strategic archetypes: value chain integration, coastal infrastructure leverage, and premium purification capability.
| Leading Market Players |
|---|
| BASF SE |
| Mitsubishi Chemical Corporation |
| Arkema Group |
| Nippon Shokubai Co., Ltd. |
| Dow Chemical Company |
| Osaka Organic Chemical Industry Ltd. |
| Formosa Plastics Corporation |
| Wanhua Chemical Group Co., Ltd. |
| LG Chem Ltd. |
| Others |
Supply & Pricing Matrix
Annual volume contracts with integrated acid-ester producers lock in both supply priority and price visibility for large-scale adhesive compounders, compressing margin unpredictability for non-integrated suppliers serving European and North American buyers under volatile propylene economics.
Pricing Analysis
Three-tier pricing structure across purified, polymer, and resin grades separates medical-device specifications from construction sealant volumes. Price differentiation rests on residual acid certification thresholds and REACH registration status, with purified-grade suppliers commanding premiums for sub-0.05% content. Cost compression in technical-grade segments is intensifying as Chinese domestic capacity expansion floods Asian spot markets. Construction material suppliers exhibit highest price sensitivity due to commodity formulation economics, while pharmaceutical adhesive buyers prioritize certification consistency over unit cost.
Supply Chain Analysis
Strategic stockpiling of isobutanol feedstock dominates inventory strategy among Japanese and German producers seeking insulation from propylene price swings. Manufacturing gravity centers on coastal clusters in China, Japan, and Germany, with Jiangsu province and Ludwigshafen anchoring regional supply. Raw material dependencies span acrylic acid, isobutanol, and esterification catalysts. Single-source vulnerability concentrates in Asian butanol supply chains. Distribution runs through direct mill procurement contracts displacing distributor intermediaries among tier-one packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty-grade fragmentation creates entry niches as medical-device and electronics adhesive specifications diverge from commodity construction applications, rewarding focused purification capabilities over scale.
For Market Incumbents: Compound feedstock security through backward integration into captive butanol production or long-term propylene offtake agreements. Prioritize REACH dossier maintenance and ECHA registration renewals to filter sub-scale competitors from qualified vendor lists. Capacity addition in Zhenjiang or Ningbo secures Asian demand concentration while UV-curable substitutes threaten solvent-borne share. For New Entrants and Emerging Players: BIS certification fast-track for Indian packaging adhesive producers creates first-mover positioning before formalization hardens procurement channels. Target Maharashtra and Gujarat compounders seeking purified-grade alternatives to established European suppliers. Medical-grade polymer demand for transdermal patches offers penetrable premium positioning with sub-0.05% residual acid specifications. For Investors and Strategic Acquirers: Coastal specialty ester purifiers with pharmaceutical-grade capabilities and METI-aligned compliance frameworks represent compelling acquisition targets. Long-term viability hinges on regulatory bandwidth to synchronize EPA, REACH, and NMPA registrations across the analysis window. Watch for SAMR GB standard alignment pushing Chinese domestic producers toward export-equivalent purity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butanol | Mitsubishi Chemical's captive production anchors supply continuity against propylene volatility. |
| REACH Dossier Investment | ECHA registration thresholds filter sub-scale suppliers from European qualified vendor lists. |
| Continuous Reactor Technology | Inline spectroscopic monitoring compresses qualification timelines for multinational food brands. |
| Medical-Grade Purification Capacity | Sub-0.05% residual acid specifications open premium positioning in transdermal patch markets. |
| Direct Mill Procurement Contracts | Tier-one packaging converters extract price transparency through annual volume agreements with integrated producers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical segment filings, and Cefic acrylic ester reports. Conversations with adhesive plant managers, procurement leads at flexible packaging converters, distribution channel partners, and technical R&D directors informed supply chain configuration and pricing dynamics. Bottom-up grade-by-grade volume estimates triangulated against top-down acrylic acid derivative consumption models.
Segmentation dimensions modeled include purity grade tier, end-use industry, packaging format, and regional production hub across the projection horizon. CAGRs derive from adhesive sector growth trajectories, polymer modification adoption curves, and regulatory-driven grade substitution patterns. Forecast inputs incorporate SAMR VOC enforcement timelines and REACH Annex XVII residual monomer restrictions.
Underlying assumptions cover propylene price stability, REACH registration continuity, and Chinese export qualification alignment, with deviation risk concentrated in feedstock volatility and regulatory synchronization bandwidth. Revision becomes warranted when UV-curable substitute penetration or biobased feedstock pathways cross commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Europe Reactive Adhesives Market
Adhesives & Sealants
Low VOC Adhesive Market