
 South America Waterborne Adhesives Market | 2026-2036
South America Waterborne Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Waterborne Adhesives Market Analytics
REACH-aligned chemical safety protocols is hardening compliance costs for imported adhesive raw materials entering Mercosur economies. Henkel AG & Co. KGaA anchors its regional position through backward integration into emulsion polymerization assets in southern Brazil. Dow competes by leveraging technical service laboratories that customize acrylic dispersion viscosity for tropical humidity conditions. H.B. Fuller Company sustains woodworking sector loyalty through dedicated distribution partnerships with panel manufacturers in Chile and Colombia.
Waterborne adhesives are aqueous polymer dispersions, typically 40-60% solids content, that form bonds through evaporation-driven coalescence of latex or polyurethane particles into continuous films. These systems serve industrial and commercial markets requiring reduced flammability, lower workplace toxicity, and simplified cleanup compared with solvent-borne alternatives. Acrylic formulations dominate volume in label and tape applications where clarity and UV stability command premium positioning. Polyurethane dispersions represent the fastest-expanding product category as automotive OEMs specify heat-resistant laminating adhesives for interior trim. Bio-based technology remains nascent but concentrates margin pools among sustainability-certified packaging suppliers seeking differentiation in export markets.
Brazil's national environmental council and ANVISA jointly govern chemical substance registration and workplace exposure limits for adhesive formulations sold domestically. Argentina's Secretariat of Environment and Sustainable Development enforces comparable VOC thresholds through industrial emission inventories that affect coating and adhesive operations in Buenos Aires province. Chile's Ministry of Environment implements extended producer responsibility frameworks that push packaging adhesive users toward recyclable, repulpable bond lines. Stakeholders must monitor pending regulatory harmonization across Mercosur member states that could unify testing protocols and accelerate substitution away from residual solvent-containing systems.
Market Dynamics
REACH-aligned chemical safety protocols is hardening compliance costs for imported adhesive raw materials entering Mercosur economies, forcing formulation houses to rebuild supply chains around locally polymerized emulsions.
Growth Catalysts
- ANVISA workplace exposure limits:Brazilian packaging converters are accelerating substitution toward waterborne systems to meet tightened solvent emission thresholds in São Paulo industrial zones.
- Automotive interior laminators:Polyurethane dispersions are capturing disproportionate specification wins from OEMs seeking heat-resistant bond lines for tropical operating conditions.
- Extended producer responsibility frameworks:Chile's Ministry of Environment is pushing adhesive users toward repulpable packaging formulations that enable circular material flows.
Market Restraints
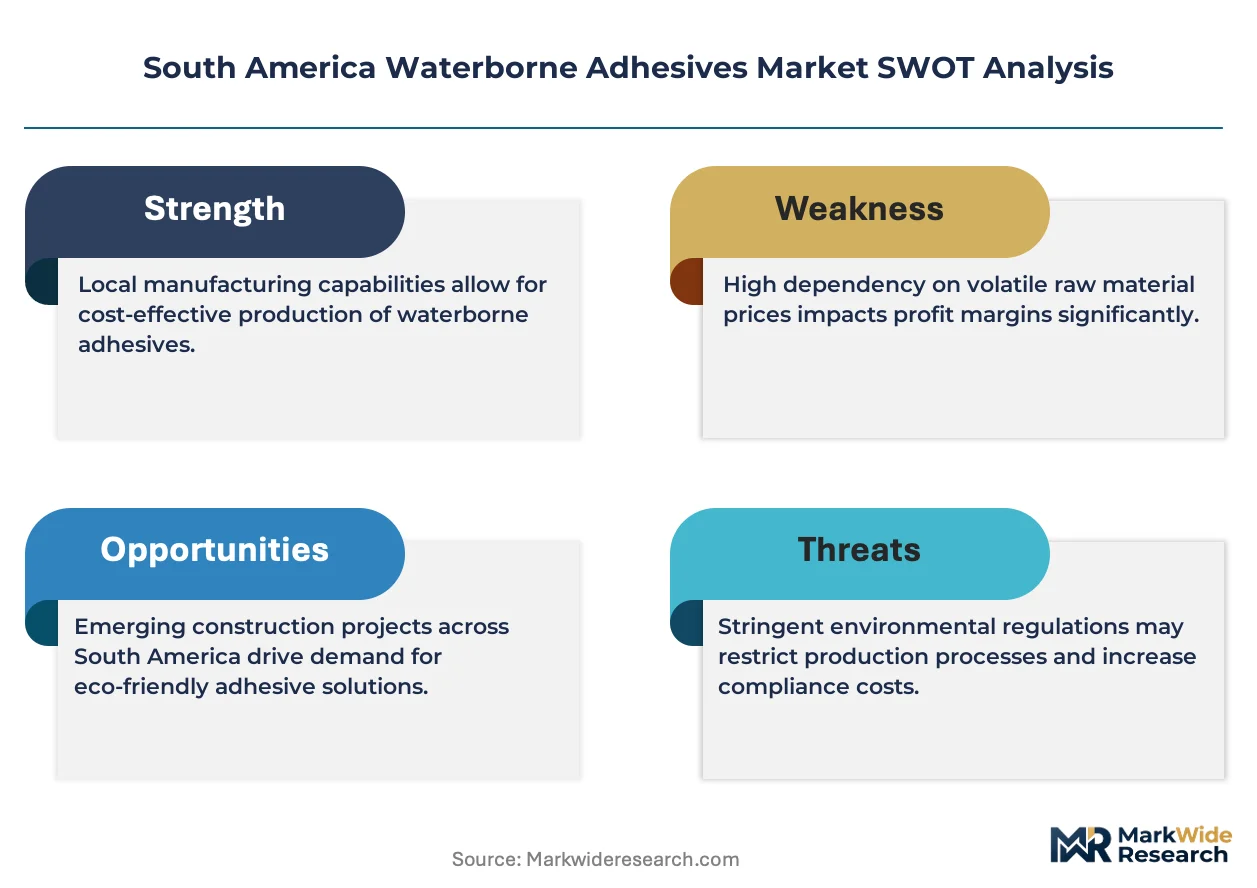
- Petrochemical feedstock volatility:Acrylic monomer costs fluctuate with naphtha pricing, compressing margin stability for emulsion producers dependent on imported intermediates.
- Import concentration risk:Specialty polyurethane dispersions rely heavily on European and Asian suppliers, exposing Brazilian automotive laminators to currency-driven cost spikes.
- Residual moisture sensitivity:Waterborne systems face technical limitations in high-humidity application environments common across Amazon basin manufacturing sites.
Strategic Opportunities
- Colombian woodworking sector:Panel manufacturers in Bogotá's industrial corridor remain underpenetrated by dedicated waterborne adhesive technical service.
- Bio-based certification demand:Sustainability-certified packaging suppliers in Argentina are creating margin pools for adhesives derived from renewable feedstocks.
- Digital formulation platforms:Remote viscosity customization and tropical climate simulation tools are compressing technical service response times for dispersed converter bases.
Industry Challenges
- Polymer chemist scarcity:Formulation houses in southern Brazil struggle to recruit specialists capable of tuning glass transition temperatures for humidity-variable performance.
- Multi-jurisdiction registration timelines:Harmonization delays across Mercosur member states extend product approval cycles for cross-border adhesive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Waterborne Adhesives Market |
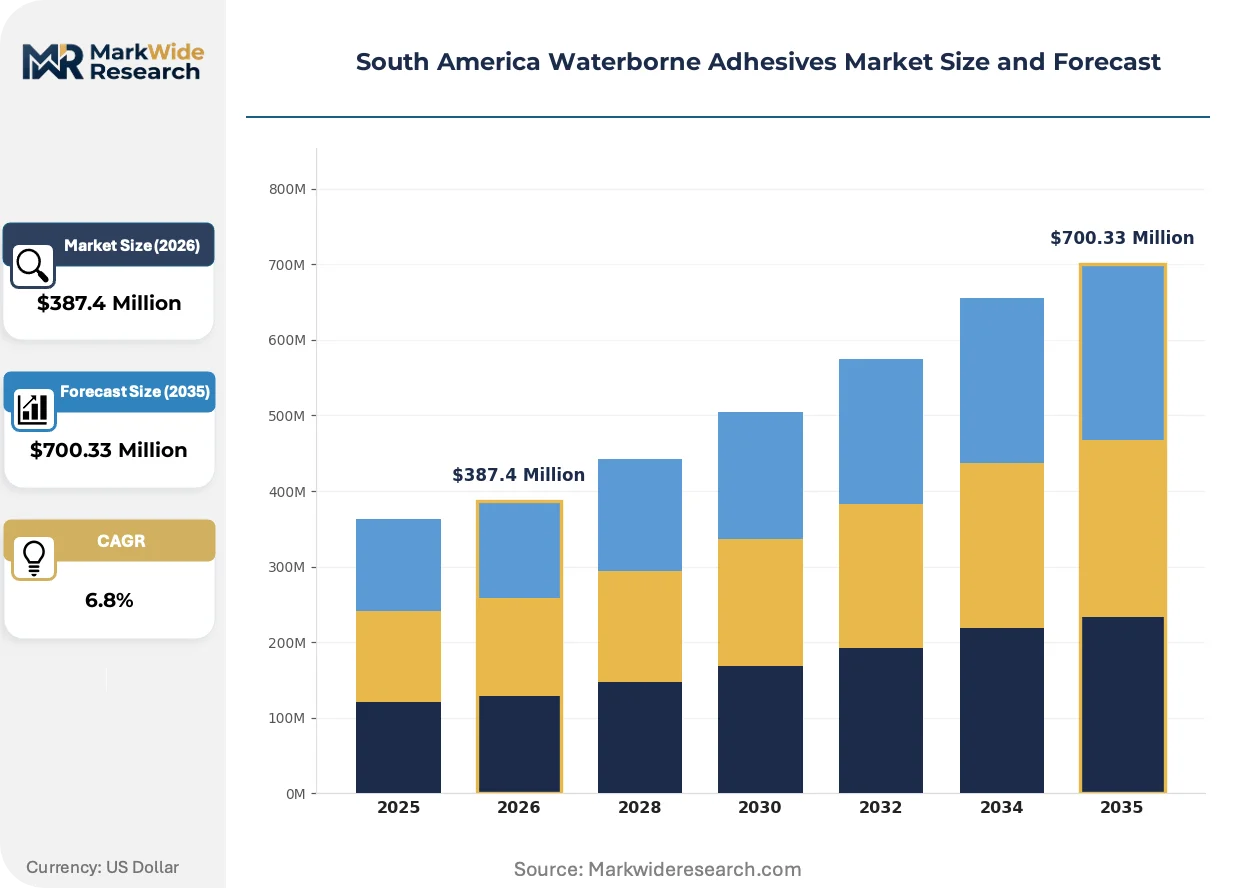
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVA, PU, Acrylic, Epoxy End User: Construction, Packaging, Automotive, Woodworking Technology: Solvent-Free, High-Performance, Low-VOC, Bio-Based Application: Flooring, Furniture, Labels, Coatings |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Dow, Arkema Group, H.B. Fuller Company, Sika AG, Ashland, Franklin Adhesives & Polymers, Bostik, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Waterborne Adhesives Market Evolving Landscape
Active reformulation of adhesive architectures is compressing performance gaps between waterborne and legacy solvent systems while regulatory pressure accelerates specification migration.
Hybrid acrylic-polyurethane copolymer technology is unifying the clarity and UV stability of acrylics with the heat resistance and flexibility of polyurethanes. Automotive OEMs in São Paulo's industrial corridor are adopting these systems at accelerated specification rates for interior trim laminations. This convergence is unifying previously separate adhesive categories into single-product platforms that reduce converter inventory complexity.
Argentina's Secretariat of Environment and Sustainable Development is enforcing industrial emission inventories that capture coating and adhesive operations in Buenos Aires province. Manufacturers must now document VOC outputs through continuous monitoring systems rather than periodic reporting. Woodworking and packaging segments are responding by retrofitting application equipment for lower-temperature waterborne curing.
Specification authority is migrating from procurement departments to technical compliance teams as regulatory documentation requirements intensify. Converter buying committees now prioritize adhesive suppliers with in-house toxicology and registration capabilities over traditional distribution relationships. This shift is most visible among Brazilian multinational packaging exporters serving EU retail chains.
South America Waterborne Adhesives Market Segmentation
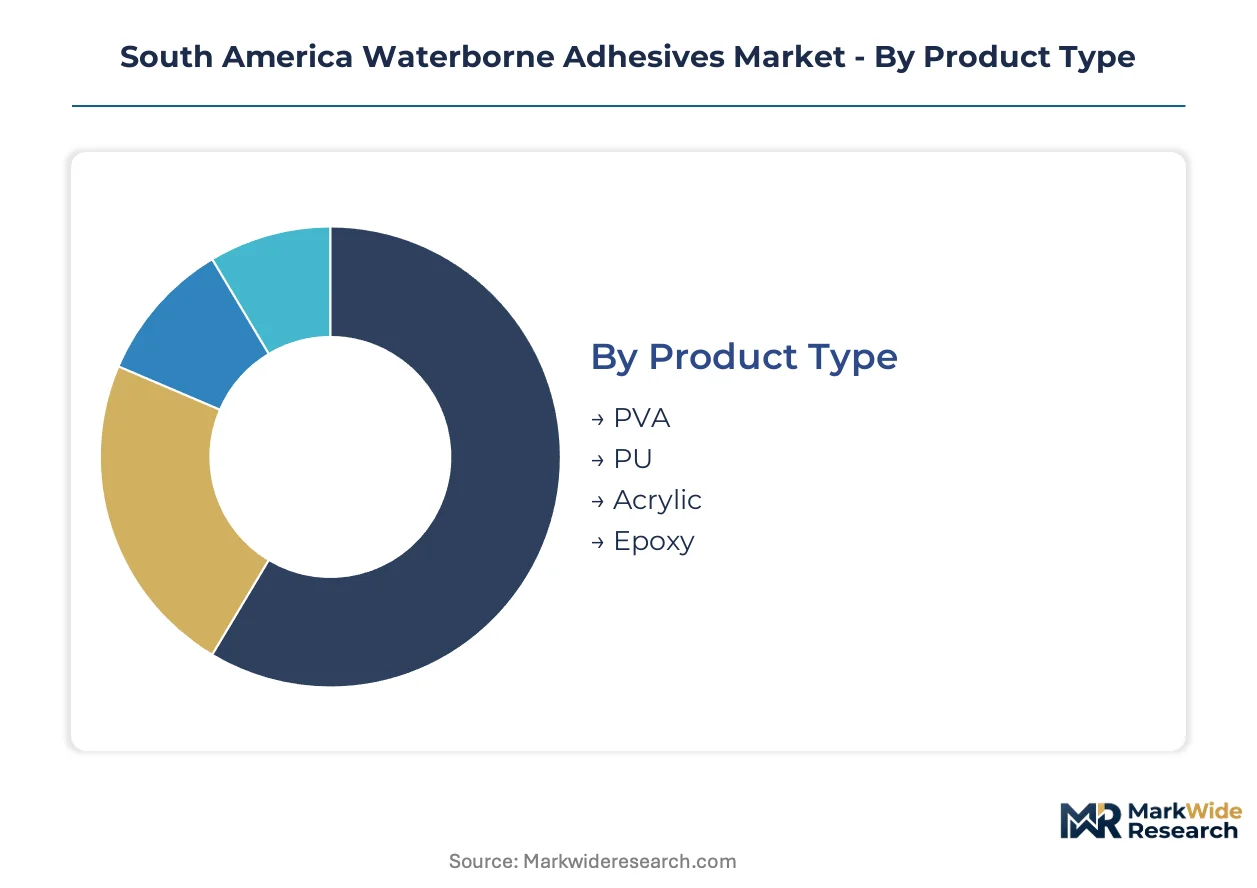
Waterborne adhesive specifications diverge sharply across South American end-uses, with tropical humidity resistance and regulatory compliance driving technology selection. Formulation houses must match polymer architecture to application-specific performance thresholds rather than offering generic emulsion platforms.
Product Type:
Polymer chemistry defines the fundamental performance envelope for waterborne systems, with each resin class occupying distinct specification territories across industrial applications.
- Acrylic:Copolymer emulsions deliver exceptional optical clarity and UV stability through carboxyl-functional particle stabilization. Brazilian label converters in São Paulo's industrial corridor specify these systems for pressure-sensitive tape applications requiring weathering resistance in high-irradiance conditions. ANVISA workplace exposure limits are accelerating specification migration from solvent-borne alternatives.
- PU (Polyurethane Dispersions):Segment-leading heat resistance and flexibility derive from segmented urethane backbone architecture with hard-soft block copolymer morphology. Automotive interior laminators across São Paulo and Buenos Aires industrial corridors disproportionately specify PUDs for dashboard and door panel bonding where tropical operating temperatures exceed 60°C surface loads. Currency-driven import cost spikes remain a supply constraint.
- PVA (Polyvinyl Acetate):Cost-competitive emulsion polymerization yields adequate wood-to-wood bonding strength for commodity furniture assembly across Chilean and Colombian panel manufacturing.
- Epoxy:Two-component waterborne systems provide structural adhesion for flooring applications requiring chemical resistance in industrial maintenance coatings.
Acrylic leads on scale; PU leads on momentum.
End User:
Customer procurement patterns stratify by technical sophistication, with multinational exporters demanding registration documentation that commodity domestic converters bypass.
- Packaging:Repulpable bond lines dominate specification criteria as Chile's Ministry of Environment implements extended producer responsibility frameworks. Brazilian carton converters serving EU retail chains prioritize adhesives with in-house toxicology documentation over distribution relationships.
- Automotive:OEM laminators specify heat-resistant polyurethane dispersions for interior trim applications where tropical humidity and temperature cycling create adhesive stress. São Paulo's industrial corridor concentrates specification authority among technical compliance teams rather than procurement departments.
- Woodworking:Panel manufacturers in Bogotá's industrial corridor remain underpenetrated by dedicated waterborne technical service, creating whitespace for formulation houses with localized application laboratories.
- Construction:Flooring and ceramic tile adhesive applications favor cost-optimized PVA-acrylic hybrid emulsions for residential building activity across Argentina's Buenos Aires province.
Packaging dominates volume concentration; automotive commands specification premium.
Technology:
Regulatory pressure and sustainability positioning are bifurcating technology adoption curves across converter segments with differential compliance burdens.
- Low-VOC:Formulations meeting ANVISA and Argentina's Secretariat of Environment emission thresholds capture specification wins in São Paulo and Buenos Aires industrial zones. Continuous monitoring requirements are retrofitting application equipment toward lower-temperature curing systems.
- Bio-Based:Renewable feedstock-derived polymers command margin premiums among sustainability-certified packaging suppliers in Argentina seeking export market differentiation. Technology remains nascent with limited regional polymerization capacity.
- Solvent-Free:Zero residual solvent systems satisfy the most stringent REACH-aligned chemical safety protocols for imported raw materials entering Mercosur economies.
- High-Performance:Hybrid acrylic-polyurethane copolymer platforms unify clarity, UV stability, and heat resistance for automotive and industrial laminating applications.
Low-VOC leads on regulatory-driven substitution; bio-based climbs fastest on sustainability certification demand.
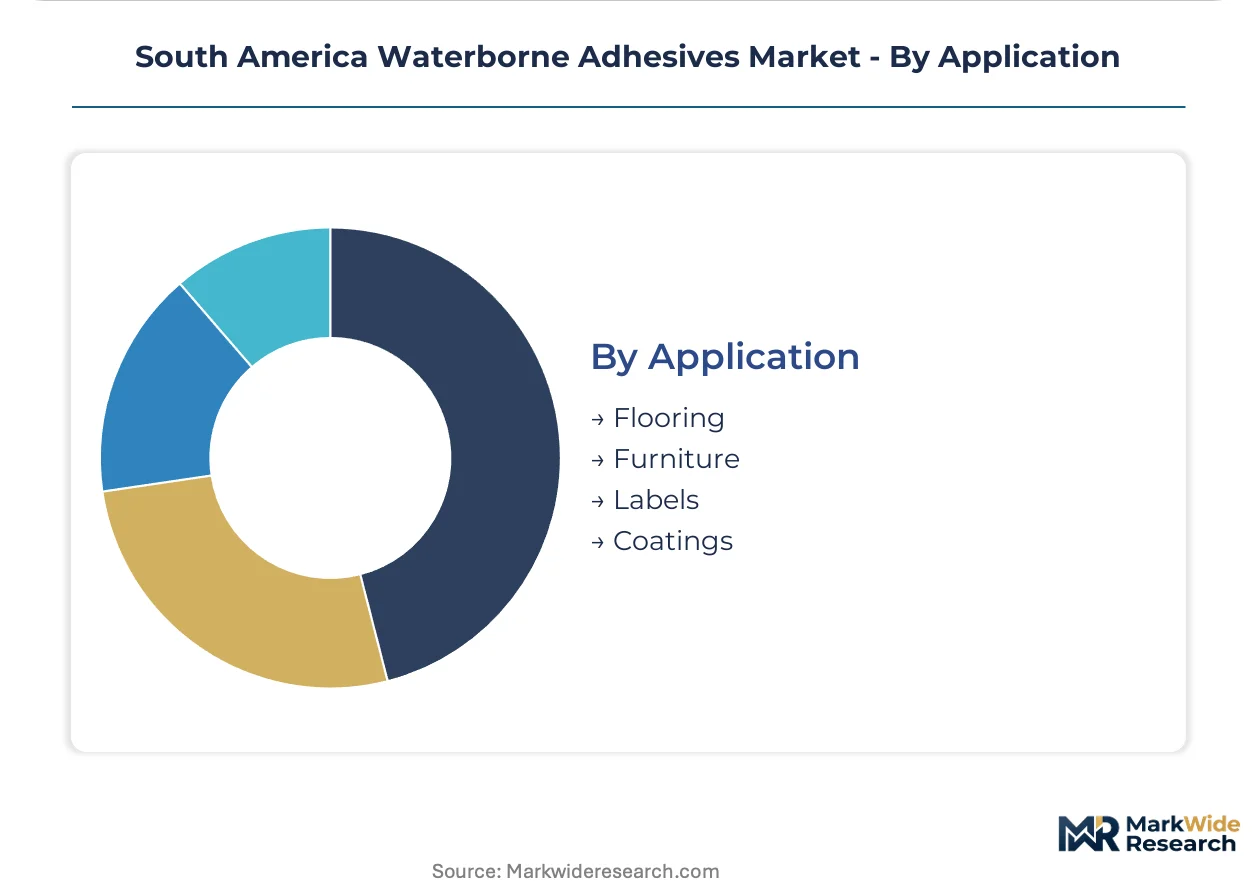
Application:
Surface preparation requirements and bond line exposure conditions determine adhesive selection across discrete manufacturing processes.
- Labels:Pressure-sensitive adhesive coatings on film and paper substrates demand acrylic emulsions with precise tack and peel balance. Brazilian label stock manufacturers prioritize UV stability for outdoor logistics applications.
- Furniture:Edgebanding and panel lamination applications in Colombian and Chilean woodworking facilities favor PVA and hybrid emulsion systems with room-temperature curing profiles.
- Flooring:Resilient sheet and tile installation requires high-green-strength adhesives with plasticizer migration resistance in vinyl substrates.
- Coatings:Industrial maintenance and decorative paint systems incorporate waterborne binders where flammability and toxicity constraints prohibit solvent-borne alternatives.
Labels concentrate volume scale; furniture offers geographic expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemists and formulation specialists concentrate in São Paulo's industrial corridor, anchoring technical service capacity for converter markets across Mercosur economies.
Brazil
Packaging converters in São Paulo's industrial zones accelerate orders for low-VOC adhesive systems as ANVISA tightens workplace exposure limits. Brazil's national environmental council governs chemical substance registration alongside ANVISA. Automotive interior laminators in São Paulo disproportionately specify polyurethane dispersions for tropical operating conditions.
Argentina
Woodworking and packaging segments retrofit application equipment for lower-temperature waterborne curing to meet emission thresholds. Argentina's Secretariat of Environment and Sustainable Development enforces industrial emission inventories through continuous monitoring systems. Buenos Aires province coating and adhesive operations face heightened documentation requirements.
Chile
Panel manufacturers drive specification of repulpable bond lines compatible with circular material flows. Chile's Ministry of Environment implements extended producer responsibility frameworks for packaging adhesive users. Santiago-based carton converters prioritize adhesives with in-house toxicology documentation for EU retail chain exports.
Colombia
Bogotá's industrial corridor panel manufacturers remain underpenetrated by dedicated waterborne adhesive technical service. Colombian environmental regulators align enforcement with emerging Mercosur harmonization protocols. Woodworking facilities in the capital region favor PVA and hybrid emulsion systems for room-temperature curing profiles.
Peru
Lima metropolitan area construction activity generates demand for cost-optimized flooring and ceramic tile adhesive applications. Peruvian chemical safety protocols adopt REACH-aligned standards for imported raw materials. Coastal manufacturing zones concentrate specification authority among technical compliance teams rather than procurement departments.
South America Waterborne Adhesives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and distribution tiers. Market structure tilts toward consolidated leadership among multinational chemical producers with backward integration into emulsion polymerization assets. Three archetypes dominate: vertically integrated polymer producers, technical service-intensive formulation houses, and distribution-anchored regional specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as players localize supply chains around Mercosur economies.
Among Germany-based chemical conglomerates, Henkel AG & Co. KGaA exemplifies the vertically integrated archetype through captive emulsion polymerization capacity in southern Brazil. Dow represents North American diversified producers competing via technical service laboratories that customize formulations. H.B. Fuller Company occupies a position among specialty adhesive houses sustaining sector loyalty through dedicated distribution partnerships. Sika AG and Arkema Group sit within the European multinational tier with construction and specialty materials positioning. 3M anchors the diversified technology conglomerate segment with broad industrial adhesive portfolios. These named entities represent competitive archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Dow |
| Arkema Group |
| H.B. Fuller Company |
| Sika AG |
| Ashland |
| Franklin Adhesives & Polymers |
| Bostik |
| Others |
Value Network & Pricing Analysis
Acrylic monomer spot prices indexed to naphtha benchmarks cascade through South American waterborne adhesive supply chains, compressing margin stability for Brazilian emulsion producers while amplifying pricing power among vertically integrated polymer houses with captive feedstock positions.
Pricing Analysis
Bundled technical service contracts command premium positioning over unbundled raw material supply across São Paulo's converter base. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified formulations from commodity emulsions and import-dependent polyurethane dispersions. Price differentiation hinges on certification grade and after-sales viscosity customization for tropical humidity conditions. Cost compression in standard-tier acrylics is intensifying because petrochemical feedstock volatility feeds through naphtha-linked monomer contracts. Domestic packaging converters in Brazil's interior states exhibit highest price sensitivity, while automotive OEM laminators in São Paulo prioritize heat resistance over unit cost.
Supply Chain Analysis
Polymer chemist scarcity in southern Brazil's manufacturing corridor constrains formulation capacity expansion despite order backlog accumulation. Supply concentration centers on Brazil, Argentina, and Chile for emulsion polymerization, with specialty polyurethane dispersions drawing from European and Asian import channels. Raw material dependencies rest on acrylic monomers, isocyanate precursors, and bio-based feedstocks for certification-tier products. Single-source vulnerability persists for heat-resistant PUDs specified by automotive interior laminators. Distribution runs through dedicated technical service partnerships with panel manufacturers rather than commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America waterborne adhesives market compounds steadily as regulatory substitution mandates across Mercosur economies generate durable specification migration away from solvent-borne alternatives.
For Market Incumbents: Hedge against import cost volatility by deepening captive emulsion polymerization capacity in southern Brazil's industrial corridor. Prioritize toxicology documentation investments to capture specification authority migrating from procurement departments to technical compliance teams among multinational packaging exporters. For New Entrants and Emerging Players: Capture whitespace in Colombian woodworking by establishing localized application laboratories in Bogotá's industrial corridor. Target sustainability-certified packaging suppliers in Argentina with bio-based certification pathways as the most penetrable segment, leveraging remote viscosity customization tools to compress technical service response times. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation houses lack backward integration into polymerization assets and remain exposed to currency-driven raw material spikes. Mid-cap specialists with ANVISA registration capabilities and tropical climate formulation expertise represent priority acquisition archetypes. Practitioners should monitor Mercosur regulatory harmonization timelines for early signals of accelerated cross-border product approval cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emulsion Polymerization | Henkel's captive southern Brazil capacity insulates margin stability from naphtha-linked monomer volatility. |
| Technical Service Laboratory Expansion | Dow's tropical humidity viscosity customization captures specification wins from São Paulo automotive laminators. |
| Bio-Based Certification Investment | Argentina's sustainability-certified packaging suppliers create margin pools for renewable feedstock-derived adhesives. |
| Distribution Partnership Deepening | H.B. Fuller's dedicated Chilean and Colombian panel manufacturer relationships sustain woodworking sector loyalty. |
| Digital Formulation Platform Deployment | Remote tropical climate simulation tools compress response times for dispersed converter bases across Mercosur. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with adhesive formulation chemists, packaging converter procurement leads, automotive OEM laminating engineers, and woodworking panel plant managers combined with secondary validation from ANVISA regulatory filings, Mercosur trade statistics, and chemical industry association reports. Bottom-up demand estimates triangulate against capacity utilization data from emulsion polymerization facilities.
The input-output matrix maps acrylic monomer consumption, polyurethane dispersion imports, and end-use application growth rates across the projection horizon. Segmentation dimensions include polymer chemistry, end-use industry, technology tier, and regional production hub. CAGRs derive from regression analysis of historical specification substitution patterns and regulatory enforcement intensity. Forecast inputs incorporate ANVISA workplace exposure limit phase-in schedules and extended producer responsibility framework adoption curves.
Underlying measurement precision varies by segment; low-VOC regulatory-driven substitution carries tighter precision than nascent bio-based certification demand. Forecasts reflect assumptions about Mercosur harmonization timelines and petrochemical feedstock price continuity. Practitioners should monitor ANVISA enforcement intensity in São Paulo industrial zones and Colombian regulatory alignment with Mercosur protocols for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
North America Adhesives Market