
 United States Sealants Market | 2026-2036
United States Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sealants Market Analytics
Silicone is pivoting toward hybrid and modified formulations as polyurethane faces cost volatility and performance limitations in extreme weather applications. Dow Inc. leverages its integrated silicone supply chain to control raw material costs across the Gulf Coast. H.B. Fuller Company anchors its position through specialty adhesives-sealants convergence in packaging and hygiene segments. Sika AG competes aggressively in construction-grade systems, particularly in infrastructure rehabilitation projects where durability specifications are tightening.
Sealants are elastomeric materials formulated to block fluids, dust, and gases while accommodating joint movement through specified elongation and recovery parameters; typical formulations comprise polymers, fillers, plasticizers, and curing agents designed for adhesion to substrates including concrete, metal, glass, and composites. The silicone segment leads in value contribution due to premium pricing in structural glazing and weatherproofing, while polyurethane maintains volume dominance in concrete joint sealing and automotive applications. Acrylic formulations occupy the fastest-growing niche in interior caulking and paintable residential finishes where DIY channel penetration is deepening.
FDA regulations govern sealants in food-contact and medical device applications, EPA VOC limits under the National Ambient Air Quality Standards constrain solvent-based formulations, and OSHA workplace exposure standards influence industrial application methods and product selection criteria. California's South Coast Air Quality Management District maintains the most stringent VOC thresholds, effectively setting the compliance ceiling for national product lines. Stakeholders must monitor evolving state-level procurement preferences for bio-based content and embodied carbon disclosure as these criteria penetrate federal infrastructure spending guidelines.
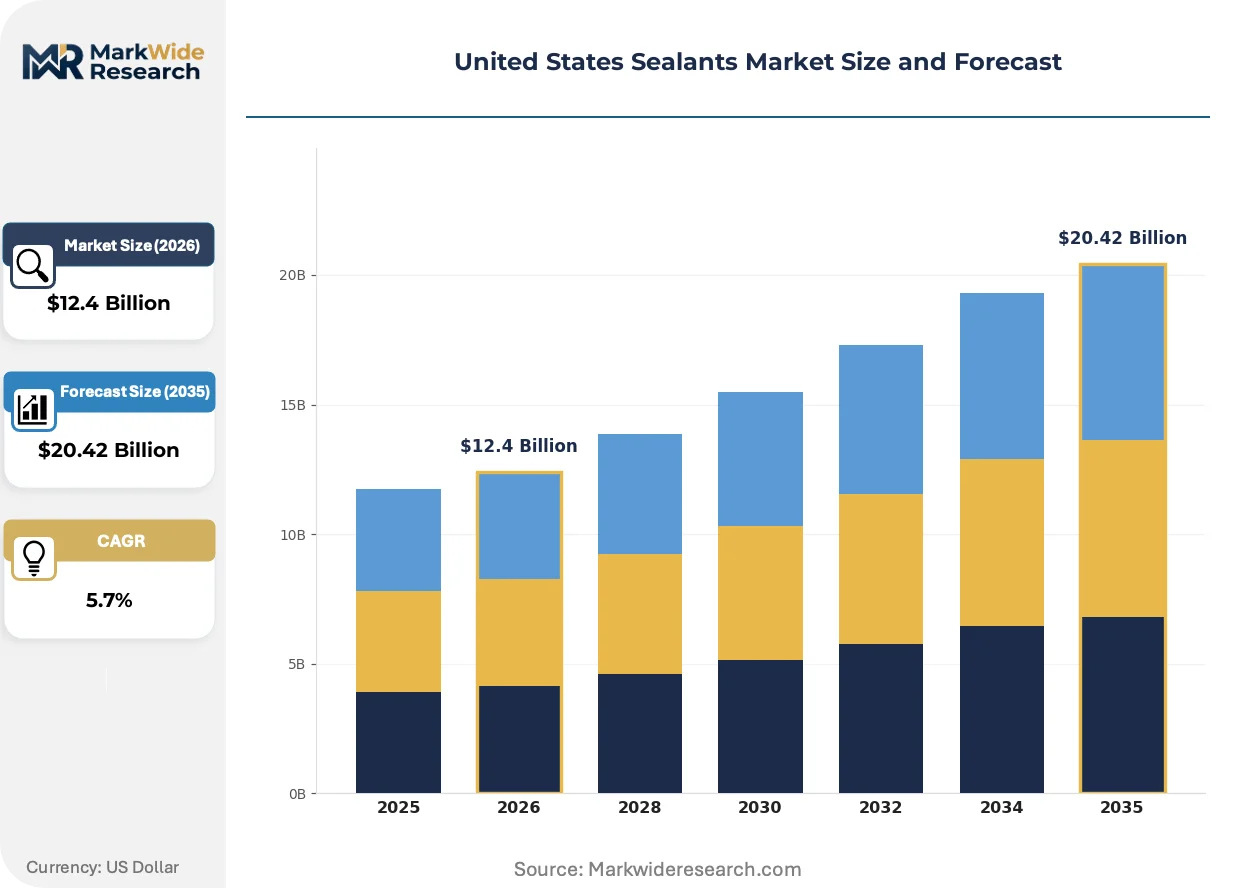
Market Dynamics
The EPA's National Ambient Air Quality Standards are compressing formulation flexibility across solvent-based sealant portfolios, forcing manufacturers to rebuild product architectures around low-VOC chemistries while maintaining performance thresholds in extreme weather applications.
Growth Catalysts
- Infrastructure Rehabilitation:Federal infrastructure spending is accelerating demand for construction-grade systems in bridge deck sealing and airport runway joint rehabilitation where durability specifications are tightening.
- South Coast Air Quality Management District Rules:California's VOC thresholds are de facto national standards, pulling manufacturers toward compliant formulations that unlock procurement eligibility across Sun Belt state projects.
- Hybrid Silicone-Polyurethane Chemistries:Modified formulations are capturing specification share in structural glazing by combining silicone weatherability with polyurethane adhesion economics.
Market Restraints
- Petrochemical Feedstock Volatility:Polyurethane raw material costs fluctuate with propylene oxide and MDI pricing, compressing margin stability for formulators without captive supply.
- Gulf Coast Supply Concentration:Silicone monomer production clusters along Texas and Louisiana chemical corridors, creating hurricane exposure risk for domestic supply continuity.
- Cure Rate Limitations:Moisture-cured polyurethanes face application window constraints in high-humidity Florida and Gulf Coast environments, restricting year-round deployment.
Strategic Opportunities
- Texas Megaproject Pipeline:Austin and Dallas-Fort Worth commercial construction is outpacing national permitting velocity, concentrating demand for high-movement joint sealants in high-rise envelopes.
- Bio-Based Content Mandates:Federal Buy Clean procurement guidelines are creating specification pathways for sealants with verified embodied carbon disclosure and renewable feedstock content.
- DIY Channel Digitalization:E-commerce platforms are capturing paintable acrylic caulk volume from traditional hardware retail, enabling direct-to-contractor replenishment models.
Industry Challenges
- Formulation Chemistry Expertise Gap:The transition from solvent-borne to water-borne and silyl-modified polymer systems demands polymer scientists with hybrid organic-inorganic synthesis experience that remains scarce in regional labor markets.
- Multi-Jurisdictional Compliance Burden:Sealant manufacturers must maintain parallel certification pathways for EPA VOC compliance, OSHA workplace exposure documentation, and state-level green building code recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sealants Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Butyl Application: Construction, Automotive, Electronics, Aerospace End User: Residential, Commercial, Industrial, Government Distribution Channel: Online, Retail, Wholesale, Direct |
| Companies Covered | 3M, H.B. Fuller Company, Henkel AG & Co. KGaA, RPM International Inc., Sika AG, Dow Inc., Huntsman Corporation, Parker Hannifin Corp, Arkema, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sealants Market Evolving Landscape
Formulation science is pivoting toward reactive chemistries that eliminate plasticizer migration while regulatory pressure is compressing the viable product portfolio toward pre-certified, disclosure-ready systems.
Hybrid silyl-modified polymer technology is rewriting competitive positioning in the construction adhesives-sealants convergence space. Commercial contractors in Texas and Florida are specifying these systems for structural glazing and insulated glass unit perimeter sealing where movement accommodation exceeds 25 percent. The technology is compressing the traditional silicone-polyurethane specification boundary by delivering paintability alongside weatherability.
California's South Coast Air Quality Management District Rule 1168 is forcing national product line consolidation around its 250 g/L VOC ceiling for architectural sealants. Manufacturers are discontinuing high-solvent formulations rather than maintaining parallel SKUs, reducing portfolio complexity but raising R&D amortization pressure. The rule is reshaping distribution inventory patterns as distributors in Arizona and Nevada now stock California-compliant SKUs exclusively.
Specification authority is migrating from general contractors to envelope consultants and commissioning agents who demand third-party validated performance data. This shift is compressing the influence of traditional distributor relationships in favor of direct technical engagement between manufacturers and design firms. The pattern is most visible in Florida's hurricane-resistant construction market where Miami-Dade County product approval carries disproportionate specification weight.
United States Sealants Market Segmentation
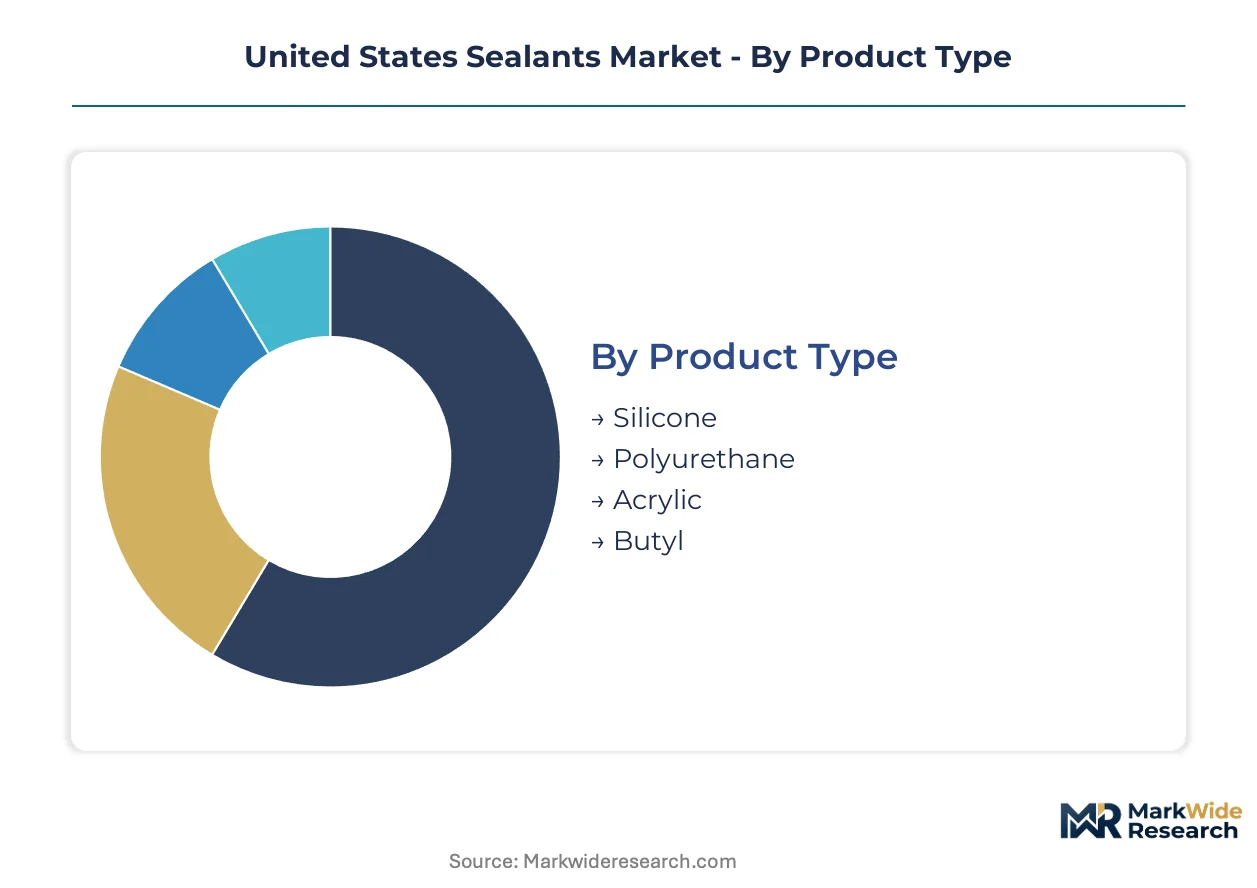
Sealant purchasing decisions in the United States split across performance specifications, regulatory compliance tiers, and channel accessibility. Understanding these fault lines clarifies where formulation investments convert to specification wins and margin protection.
Product Type:
Replacement cycles and upgrade pathways differ sharply across chemistries, with weatherability demands in Sun Belt states accelerating silicone adoption while cost sensitivity sustains polyurethane volume.
- Silicone:Formulated from polydimethylsiloxane backbones with moisture-cure chemistry, silicone delivers the elongation and UV stability required for structural glazing and high-movement building joints. Demand concentrates in Florida and Texas commercial envelopes where hurricane-resistant construction mandates exceed 50-year durability specifications. The EPA's VOC thresholds under National Ambient Air Quality Standards are compressing solvent-borne alternatives, pulling specification share toward low-VOC silicone hybrids.
- Polyurethane:Built on polyether or polyester polyol reaction with isocyanate curing agents, polyurethane dominates concrete joint sealing and below-grade waterproofing where adhesion to porous substrates matters. Volume concentrates in infrastructure rehabilitation across the Interstate highway system and airport runway projects where federal spending is accelerating. Raw material volatility in propylene oxide and MDI feedstocks is forcing formulators toward captive supply arrangements or hybrid formulations.
- Acrylic:Water-borne emulsion polymers with paintable surfaces and interior-grade flexibility, acrylics capture DIY channel volume in residential caulking and trim sealing. California's South Coast Air Quality Management District Rule 1168 compliance has become the de facto national standard for architectural sealants, eliminating high-solvent acrylic competition.
- Butyl:Synthetic rubber formulations with exceptional gas barrier properties, butyl sealants anchor insulated glass unit perimeter sealing and primary automotive glazing. Demand tracks window manufacturing clusters in Ohio and automotive assembly concentration in the Southeast.
Volume placements concentrate in polyurethane; the faster expansion belongs to silicone.
Application:
Cost tier stratification separates specification-grade systems from commodity formulations, with certification requirements widening the price gap between structural and non-structural applications.
- Construction:Encompasses structural glazing, weatherproofing, concrete joint sealing, and interior finishing across commercial, residential, and infrastructure verticals. Demand is accelerating in Texas megaprojects and Florida hurricane-resistant construction where Miami-Dade County product approval carries specification authority.
- Automotive:Direct glazing, seam sealing, and underbody coatings requiring OEM validation and crash-performance certification. Volume tracks Detroit Three and transplant assembly concentration in Tennessee, South Carolina, and Texas.
- Electronics:Potting compounds and conformal coatings protecting circuit assemblies from moisture and thermal cycling. Demand concentrates in semiconductor packaging and consumer device manufacturing where miniaturization is tightening tolerance specifications.
- Aerospace:Fuel tank sealing, firewall barriers, and pressure vessel gaskets meeting FAA flame-resistance and outgassing standards. Procurement flows through tiered supplier qualification systems with long validation cycles.
Construction absorbs the largest volume placements; electronics is climbing the fastest as device density and thermal management requirements intensify.
End User:
Customer type determines procurement sophistication, with government and commercial buyers demanding embodied carbon disclosure while residential channels prioritize shelf presence and price accessibility.
- Residential:Single-family and multifamily construction plus renovation activity, with specification authority residing with general contractors and homeowners. DIY channel digitalization is shifting replenishment toward e-commerce platforms and direct-to-contractor models.
- Commercial:Office, retail, hospitality, and institutional construction where envelope consultants and commissioning agents now control sealant specification. Federal Buy Clean procurement guidelines are creating pathways for bio-based content verification.
- Industrial:Manufacturing facility construction, equipment sealing, and maintenance operations requiring chemical resistance and temperature tolerance. Procurement emphasizes total cost of ownership over unit price.
- Government:Federal, state, and municipal infrastructure projects including bridges, airports, and water treatment facilities. Davis-Bacon prevailing wage requirements and domestic content preferences structure bidding.
Commercial placements dominate value capture; government is gaining share fastest as federal infrastructure spending accelerates.
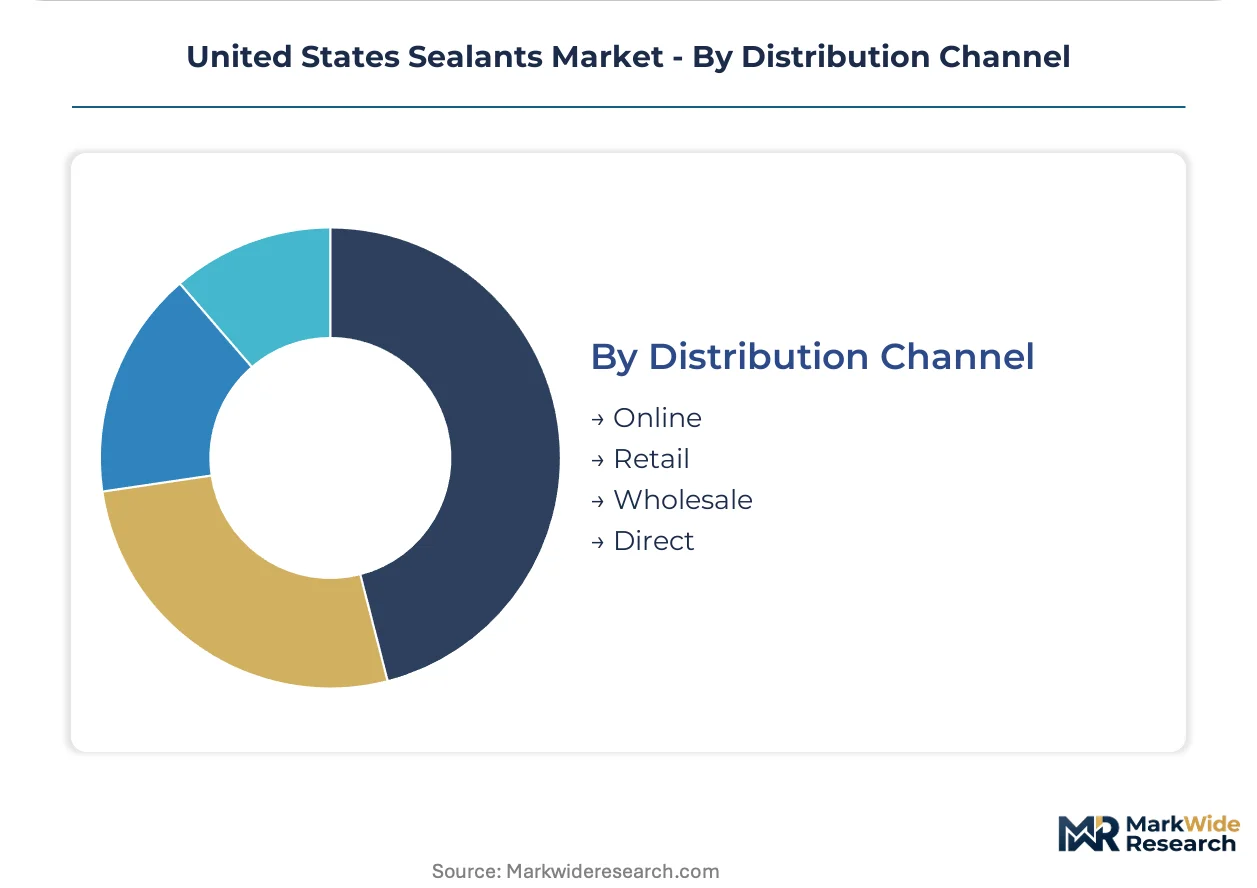
Distribution Channel:
Supply concentration along the Gulf Coast chemical corridor shapes channel economics, with hurricane exposure risk favoring inventory positioning strategies that buffer disruption.
- Online:E-commerce platforms capturing paintable acrylic volume and contractor replenishment orders, enabled by SKU consolidation around California-compliant formulations. Amazon Business and specialized construction marketplaces are compressing traditional distributor margins.
- Retail:Home centers and hardware stores serving DIY residential demand, with shelf space allocation favoring national brands with multi-SKU compliance coverage. The channel is losing share to digital as professional contractors bypass retail for direct sourcing.
- Wholesale:Distributors stocking California-compliant SKUs exclusively across Arizona and Nevada, reflecting South Coast Air Quality Management District influence beyond state borders. Technical support and specification relationships remain the channel's defensive moat.
- Direct:Manufacturer-to-contractor relationships for large commercial and infrastructure projects requiring batch certification and custom formulation. Sika AG and H.B. Fuller compete aggressively through direct technical engagement with design firms.
Wholesale retains the deepest volume concentration; online is expanding most quickly as procurement patterns digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Opportunity Zone tax incentives and state-level infrastructure bonds are concentrating sealant demand across the Sun Belt corridor, with Texas and Florida permitting velocity outpacing national averages by substantial margins.
Texas
Austin and Dallas-Fort Worth commercial construction megaprojects are driving specification-grade silicone and hybrid sealant procurement for high-rise envelope systems. The Texas Department of Transportation's accelerated bridge rehabilitation program is expanding concrete joint sealing contracts. Houston's petrochemical corridor hosts concentrated silicone monomer production, creating localized supply advantages for formulators with captive feedstock access.
Florida
Miami-Dade County's hurricane-resistant construction mandates are elevating product approval standards for structural glazing and weatherproofing systems. The Florida Building Commission's enhanced wind-load requirements are compressing specification authority toward envelope consultants. Orlando and Tampa residential permitting is sustaining DIY channel volume for paintable acrylic caulks through retail and e-commerce replenishment.
California
The South Coast Air Quality Management District's Rule 1168 VOC thresholds are de facto national standards, forcing manufacturers to consolidate product lines around 250 g/L compliant formulations. The state's Buy Clean procurement guidelines are creating specification pathways for bio-based content verification. Los Angeles and San Francisco commercial retrofits are accelerating demand for low-VOC interior sealants in LEED-certified building upgrades.
Arizona and Nevada
Distributors in Phoenix and Las Vegas now stock California-compliant SKUs exclusively, reflecting South Coast Air Quality Management District influence beyond state borders. Extreme temperature cycling in desert climates is elevating specification requirements for UV-stable exterior sealants. Residential construction in Scottsdale and Henderson is sustaining volume demand for standard-grade polyurethane joint sealers in single-family foundations.
Illinois and Ohio
Chicago's commercial envelope rehabilitation market is tightening durability specifications for structural glazing replacement cycles. The Ohio Department of Transportation's bridge deck sealing program is expanding construction-grade polyurethane procurement. Window manufacturing clusters in Toledo and Cleveland are anchoring butyl sealant demand for insulated glass unit perimeter sealing.
United States Sealants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-grade construction systems consolidating around technical service capabilities while commodity formulations fragment across regional blenders. The vendor base organizes into three strategic archetypes: integrated petrochemical producers with captive silicone supply, specialty chemical houses with adhesives-sealants convergence portfolios, and construction-focused system suppliers with direct contractor relationships. Dominant competitive moves include backward integration into raw material production and direct technical engagement with envelope consultants and commissioning agents.
Within the integrated chemical producer tier, Dow Inc. and Huntsman Corporation exemplify supply-chain control strategies that buffer margin pressure from propylene oxide and MDI feedstock volatility. Sika AG and H.B. Fuller Company occupy positions emphasizing construction-grade system specialization and adhesives-sealants convergence in packaging and hygiene segments respectively. These four entities represent distinct competitive vectors: petrochemical integration, infrastructure project capture, specialty packaging adhesion, and hybrid formulation development.
| Leading Market Players |
|---|
| 3M |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| RPM International Inc. |
| Sika AG |
| Dow Inc. |
| Huntsman Corporation |
| Parker Hannifin Corp |
| Arkema |
| Others |
Value Network & Pricing Analysis
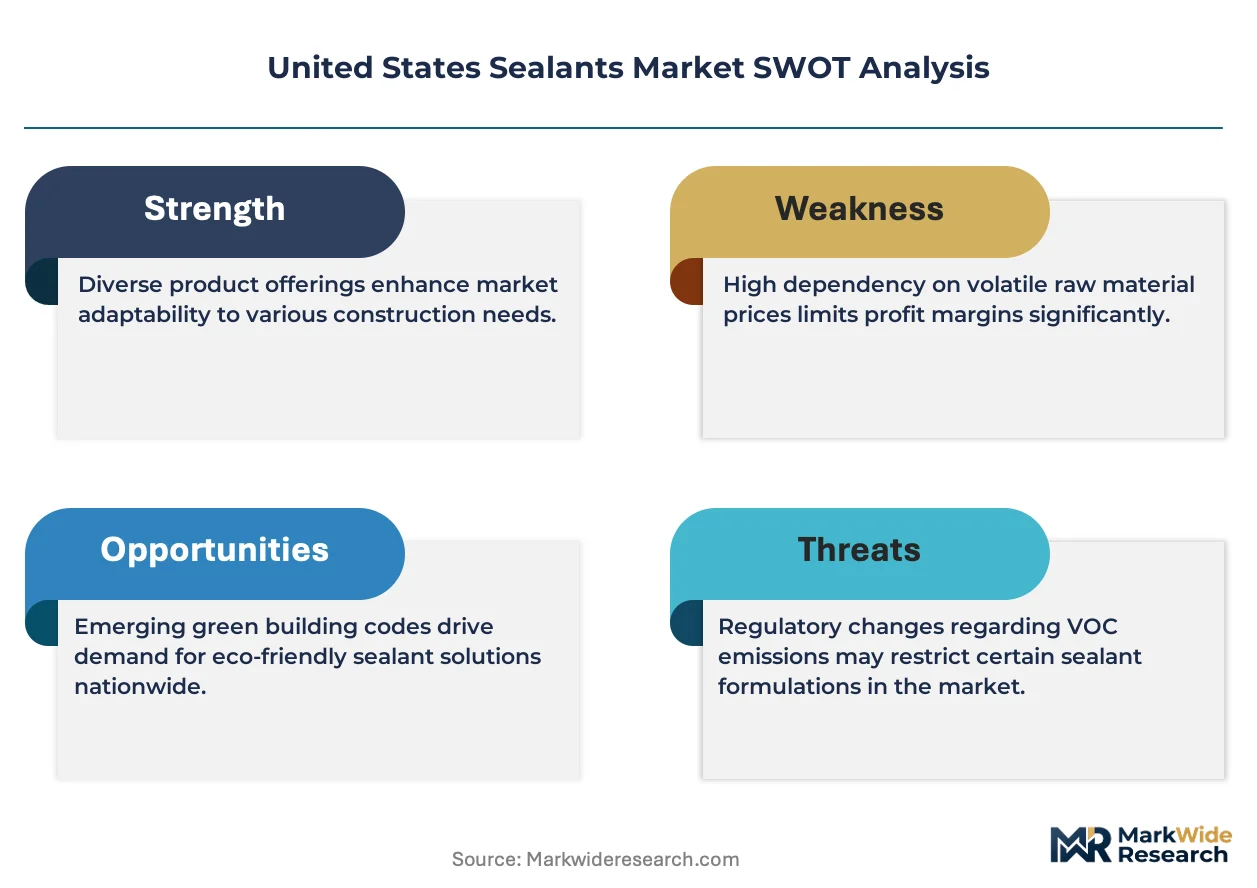
Hybrid silyl-modified polymer technology is compressing cost economics across specification-grade sealant portfolios while simultaneously concentrating production capabilities among formulators with captive silicone monomer access. The EPA's National Ambient Air Quality Standards are eliminating solvent-borne alternatives, forcing manufacturers to absorb R&D amortization across narrower SKU ranges while Gulf Coast supply clusters dictate regional pricing power.
Pricing Analysis
Volume placements concentrate in polyurethane where commodity dynamics compress margins; silicone commands premium pricing in structural glazing and hurricane-resistant construction. Three-tier pricing structure separates Miami-Dade certified systems from standard commercial grades and DIY acrylic caulks. Cost compression in polyurethane stems from propylene oxide and MDI feedstock volatility. Residential DIY channels exhibit highest price sensitivity; envelope consultants driving commercial specifications prioritize performance validation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Texas and Louisiana chemical corridors where hurricane exposure threatens silicone monomer continuity. Domestic production draws from Gulf Coast petrochemical infrastructure and imported specialty isocyanates. Tariff exposure runs through MDI feedstock dependencies on Asian supply. Distribution runs through wholesale distributors stocking California-compliant SKUs exclusively across Sun Belt states, with direct manufacturer engagement penetrating large commercial and infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States sealants market is becoming a vertical-integration race as formulators pursue captive silicone monomer production to buffer margin pressure from Gulf Coast supply concentration and petrochemical feedstock volatility.
For Market Incumbents: Acquire silicone monomer production assets or secure long-term offtake agreements with Gulf Coast chemical producers to defend against hurricane disruption risk. Build technical service capabilities targeting envelope consultants in Florida and Texas where Miami-Dade County approval and high-movement joint specifications concentrate procurement authority. Invest in silyl-modified polymer R&D to compress the silicone-polyurethane specification boundary before hybrid formulations commoditize. For New Entrants and Emerging Players: E-commerce platforms and direct-to-contractor digital channels offer the lowest barrier to entry for paintable acrylic caulk volume in residential renovation markets. Target Arizona and Nevada distribution nodes where California Rule 1168 compliance has already consolidated SKU requirements. Pursue bio-based content certification pathways under federal Buy Clean guidelines to differentiate in government infrastructure bidding. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated chemical producers seeking construction-grade system capabilities. Five-to-ten year viability favors formulators with demonstrated low-VOC formulation expertise and established relationships with envelope consultants. Watch EPA state-level green building code adoption velocity as the signal indicating acceleration or compression in specification-grade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Monomer | Gulf Coast captive supply buffers margin pressure from propylene oxide volatility. |
| California Rule 1168 Pre-Certification | EPA VOC compliance unlocks procurement eligibility across Sun Belt state projects. |
| Direct Technical Engagement Model | Envelope consultant relationships in Florida compress distributor influence. |
| Bio-Based Content Verification | Federal Buy Clean guidelines create specification pathways in infrastructure spending. |
| Hybrid Formulation Development | Silyl-modified polymers capture structural glazing share from pure silicone systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving plant managers at formulator facilities, procurement leads at commercial general contractors, distribution channel partners, and technical R&D directors specializing in hybrid polymer systems. EPA National Ambient Air Quality Standards documentation, South Coast Air Quality Management District Rule 1168 compliance databases, and SEC 10-K disclosures from integrated chemical producers provided validation benchmarks. Bottom-up volume modeling triangulated against top-down construction spending allocations.
Data-stream reconciliation across product type, application vertical, end-user procurement tier, and regional regulatory cluster produced consistent volume and value outputs across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating federal infrastructure spending velocity and state-level green building code adoption patterns. Silicone-polyurethane price differentials and DIY channel digital penetration rates served as industry-specific forecast inputs.
The model holds under stable petrochemical feedstock pricing and continued EPA VOC regulatory compression; deviation in hurricane frequency affecting Gulf Coast chemical corridors or abrupt shifts in federal infrastructure appropriations would shift volume trajectories. Forecasts reflect documented assumptions regarding specification authority migration toward envelope consultants. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Global Epoxy Adhesive Market