
 Europe Down Syndrome Market | 2026-2036
Europe Down Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Down Syndrome Market Foresight
Germany is tilting toward expanded prenatal screening infrastructure across its university hospital network. F. Hoffmann-La Roche Ltd leverages its molecular diagnostics platform to anchor testing workflows in centralized laboratories. Thermo Fisher Scientific Inc competes through chromosomal microarray and NGS-based assay portfolios. AC Immune SA specializes in tau-targeting neurodegenerative pipelines that extend into Down syndrome-associated Alzheimer's indications.
Down syndrome denotes a chromosomal condition arising from complete or partial trisomy of chromosome 21, characterized by distinctive craniofacial features, intellectual disability, and elevated risk of congenital heart defects and early-onset Alzheimer's disease. Prenatal detection relies on cell-free fetal DNA analysis, fluorescent in situ hybridization, and karyotyping, while postnatal management integrates cardiac surgery, endocrine monitoring, and developmental therapy. Diagnostic Tests command the largest revenue share due to mandatory first-trimester screening protocols across multiple European health systems. Therapeutic Drugs represent the fastest-expanding category as pharmaceutical developers advance disease-modifying candidates through EMA orphan designation pathways. Support Products maintain steady demand through durable medical equipment and assistive technology procurement by rehabilitation centers.
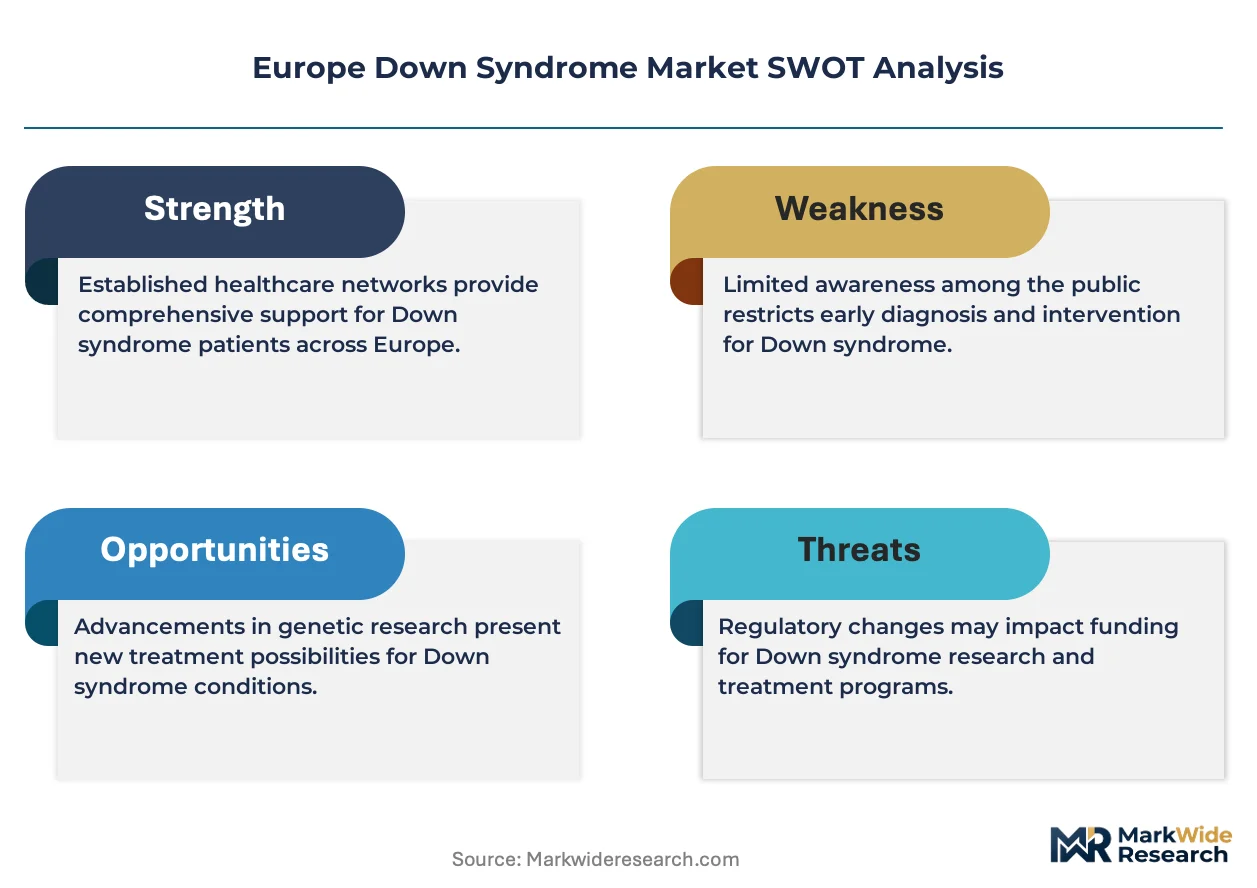
EMA orphan drug incentives and the EU Medical Device Regulation shape clinical trial design and market access conditions for Down syndrome interventions. National health technology assessment bodies in France, Germany, and England determine reimbursement eligibility for novel diagnostics and therapeutics. GDPR provisions govern genetic data handling in prenatal screening programs, adding compliance layers to laboratory information systems. Stakeholders must monitor EMA pediatric investigation plan requirements and evolving national screening committee recommendations to align development timelines with payer expectations.
Market Dynamics
EMA orphan drug incentives are compressing development timelines for neurological therapeutics targeting Down syndrome-associated Alzheimer's, while GDPR genetic data provisions reshape laboratory information system procurement across maternal-fetal medicine networks.
Growth Catalysts
- EU Medical Device Regulation:Harmonized CE marking pathways accelerate diagnostic assay commercialization across member states, reducing national fragmentation in prenatal testing approval.
- Cell-free fetal DNA analysis:Non-invasive prenatal testing platforms expand screening access beyond high-risk pregnancies into routine first-trimester protocols.
- Germany:University hospital network investments in centralized molecular diagnostics laboratories create anchor demand for chromosomal microarray workflows.
Market Restraints
- Genetic data compliance costs:GDPR Article 9 provisions governing special category data impose encryption and consent-management infrastructure burdens on screening laboratories.
- Specialized care concentration:France, Germany, and the United Kingdom capture disproportionate clinical trial and commercial activity, leaving Southern and Eastern European markets underserved.
- Reimbursement fragmentation:National health technology assessment bodies in England, France, and Germany maintain divergent evidentiary standards for novel diagnostic and therapeutic coverage.
Strategic Opportunities
- Spain and Italy:Underdeveloped national screening program infrastructure presents white-space expansion potential for prenatal diagnostic platform providers.
- Tau-targeting neurodegenerative pipelines:Disease-modifying candidates for Down syndrome-associated Alzheimer's represent unaddressed therapeutic need with EMA orphan designation pathway access.
- Developmental therapy integration:Digital health platforms enabling remote monitoring of cardiac and endocrine comorbidities create new channel economics for rehabilitation center networks.
Industry Challenges
- Pediatric investigation plan compliance:EMA requirements for juvenile toxicology studies extend timelines for neurological therapeutic candidates targeting congenital indications.
- Laboratory information system integration:Legacy hospital IT architectures in France and Germany resist seamless incorporation of cloud-based genetic data management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Down Syndrome Market |
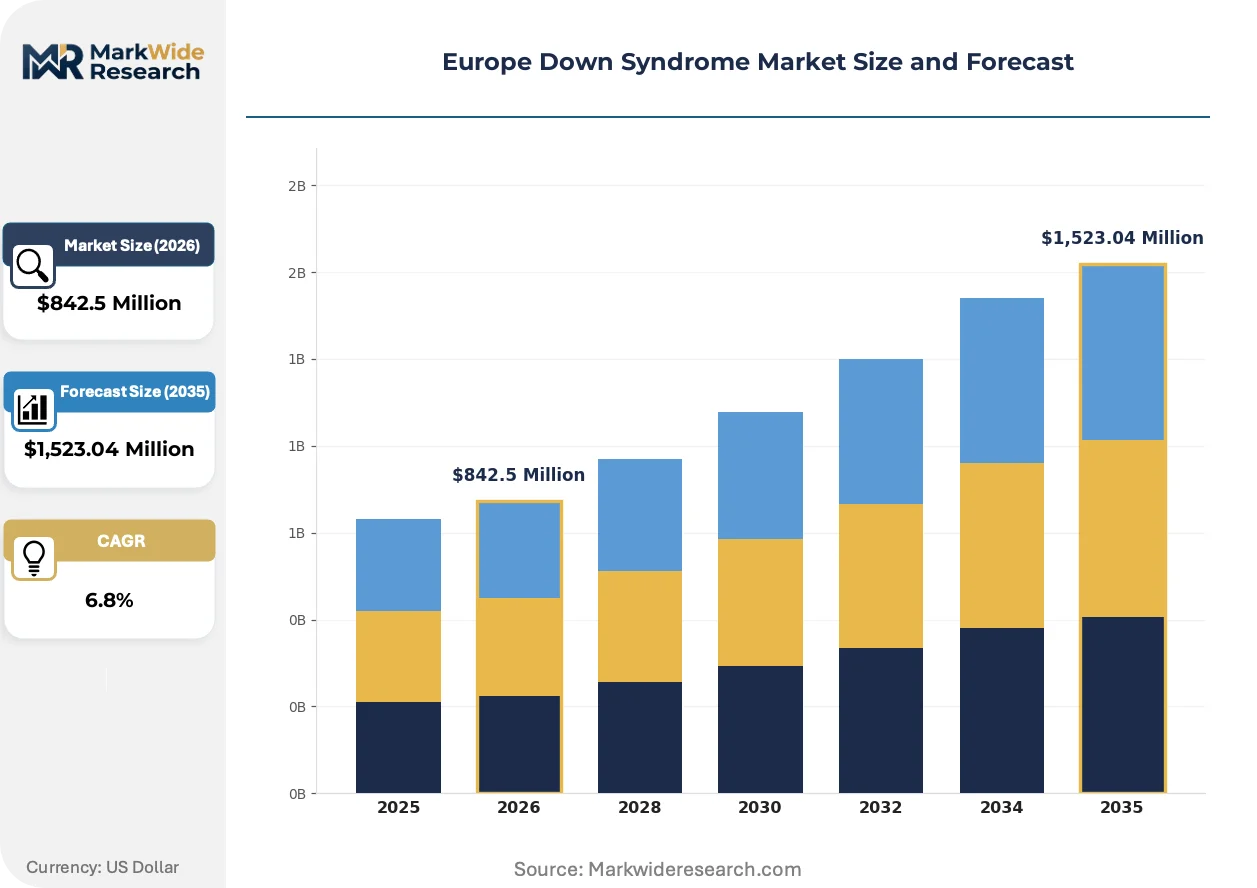
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,523.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tests, Therapeutic Drugs, Support Products, Genetic Counseling Services End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Treatment Approach: Pharmacological, Behavioral Therapy, Educational Programs, Supportive Care Age Group: Pediatric, Adolescent, Adult, Geriatric |
| Companies Covered | F. Hoffmann-La Roche Ltd, AC Immune SA, Aelis Farma, Annovis Bio, Inc., Alzheon Inc., Natera, Inc., Myriad Genetics, Inc., Thermo Fisher Scientific Inc, NeuroNascent, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Down Syndrome Market Shifts & Advancements
Digital infrastructure investments are reconfiguring how prenatal screening data flows between laboratories, clinicians, and patients across European health systems. Three developments merit particular attention.
Next-generation sequencing-based non-invasive prenatal testing is collapsing the cost and turnaround time differential between high-risk and routine screening populations. Maternal-fetal medicine units in Germany and the United Kingdom are adopting these platforms at accelerating pace. The technology is collapsing the historical bifurcation between research-grade cytogenetics and clinical diagnostic workflows, enabling single-platform standardization.
EMA's evolving pediatric investigation plan requirements for neurological orphan indications are compressing juvenile study design flexibility. Pharmaceutical developers must integrate Down syndrome-specific Alzheimer's biomarker strategies earlier in clinical development. The regulation most affects tau-targeting therapeutic pipelines, which are responding by embedding natural history study infrastructure across European specialized care networks.
Patient advocacy organizations are consolidating purchasing influence over assistive technology and durable medical equipment procurement. Rehabilitation centers in France and England increasingly coordinate procurement through consortium structures rather than individual institutional contracting. This behavioral shift is most visible in the support products segment, where bundled service agreements are displacing transactional equipment sales.
Europe Down Syndrome Market Segmentation
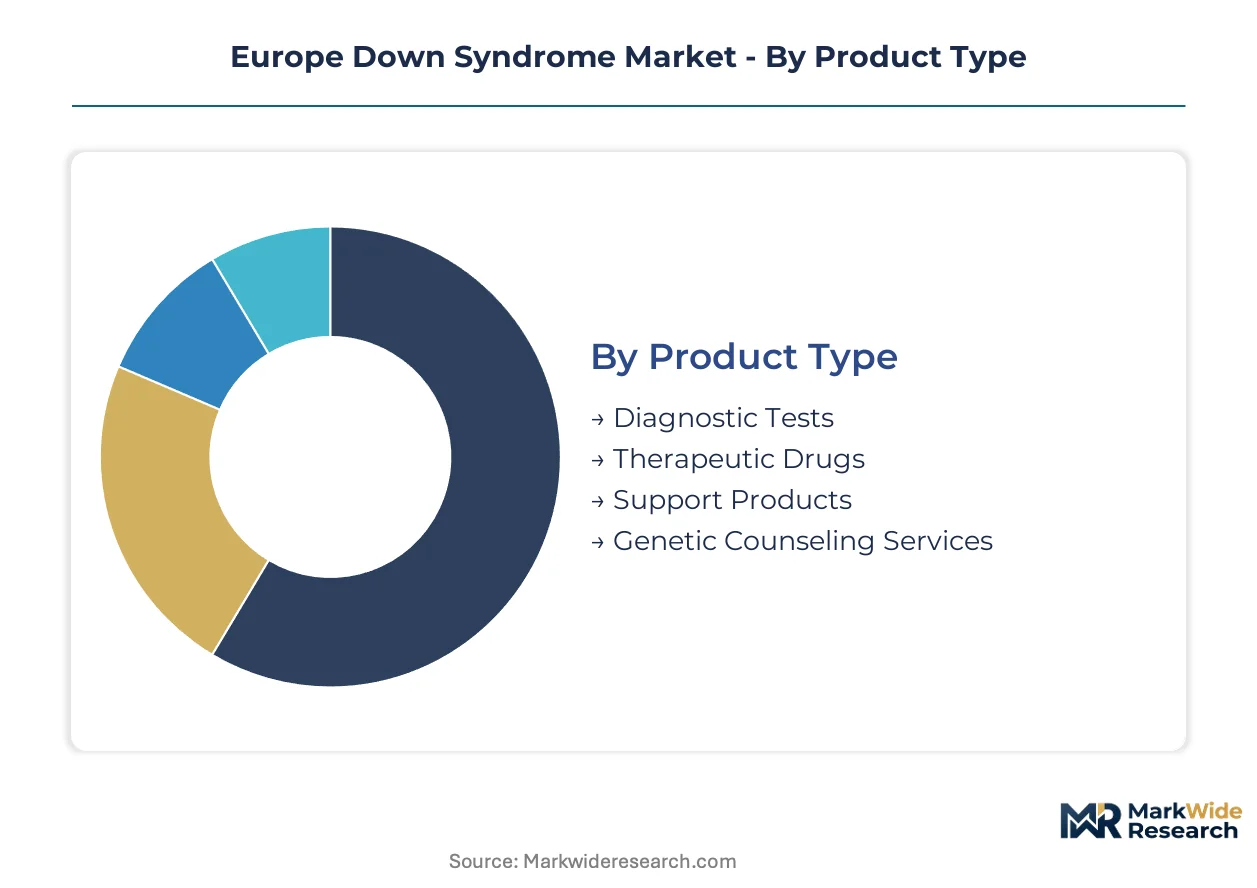
Down syndrome market segmentation reveals distinct procurement patterns across diagnostic, therapeutic, and support service categories. Each segment carries unique after-sales service intensity, from continuous laboratory calibration for molecular diagnostics to longitudinal care coordination for developmental support programs.
Product Type:
After-sales service intensity varies sharply across product categories, with diagnostic platforms requiring continuous reagent supply and regulatory recertification while support products demand maintenance networks and replacement part logistics.
- Diagnostic Tests:Cell-free fetal DNA analysis, fluorescent in situ hybridization, and karyotyping platforms constitute the revenue core. German university hospital networks anchor centralized laboratory demand for chromosomal microarray workflows. Mandatory first-trimester screening protocols across multiple European health systems sustain procurement volume.
- Therapeutic Drugs:Disease-modifying candidates targeting Down syndrome-associated Alzheimer's advance through EMA orphan designation pathways. Tau-targeting neurodegenerative pipelines from AC Immune SA and comparable developers concentrate clinical trial activity in France, Germany, and the United Kingdom.
- Support Products:Durable medical equipment and assistive technology serve rehabilitation center procurement.
- Genetic Counseling Services:Pre- and post-test consultation frameworks integrate with maternal-fetal medicine units across national screening programs.
By volume, Diagnostic Tests leads. By growth pace, Therapeutic Drugs is ahead.
End User:
Cost tier stratification determines procurement authority, with university hospitals commanding capital-intensive molecular diagnostics budgets while home care segments concentrate on consumable medical equipment.
- Hospitals:Tertiary centers perform complex cardiac surgeries and manage acute comorbidities. Germany's university hospital network drives centralized molecular diagnostics platform adoption.
- Clinics:Maternal-fetal medicine units execute first-trimester screening protocols and coordinate referrals.
- Home Care:Family-based management of daily living supports and remote monitoring of endocrine conditions.
- Rehabilitation Centers:Consortium-structured procurement in France and England displaces individual institutional contracting for assistive technology.
Hospitals capture the largest procurement value. Rehabilitation Centers are expanding most quickly through bundled service agreements.
Treatment Approach:
Application context shapes intervention selection, with acute comorbidity management favoring pharmacological protocols while developmental outcomes drive behavioral and educational investment.
- Pharmacological:Cardiac medications, thyroid hormone replacement, and emerging Alzheimer's therapeutics target specific comorbidity profiles.
- Behavioral Therapy:Speech, occupational, and physical therapy interventions address developmental delays.
- Educational Programs:Individualized learning frameworks and inclusive schooling infrastructure.
- Supportive Care:Coordinated management of sleep disorders, gastrointestinal conditions, and mental health needs.
Pharmacological approaches dominate acute intervention. Behavioral Therapy is gaining share fastest through early intervention program expansion.
Age Group:
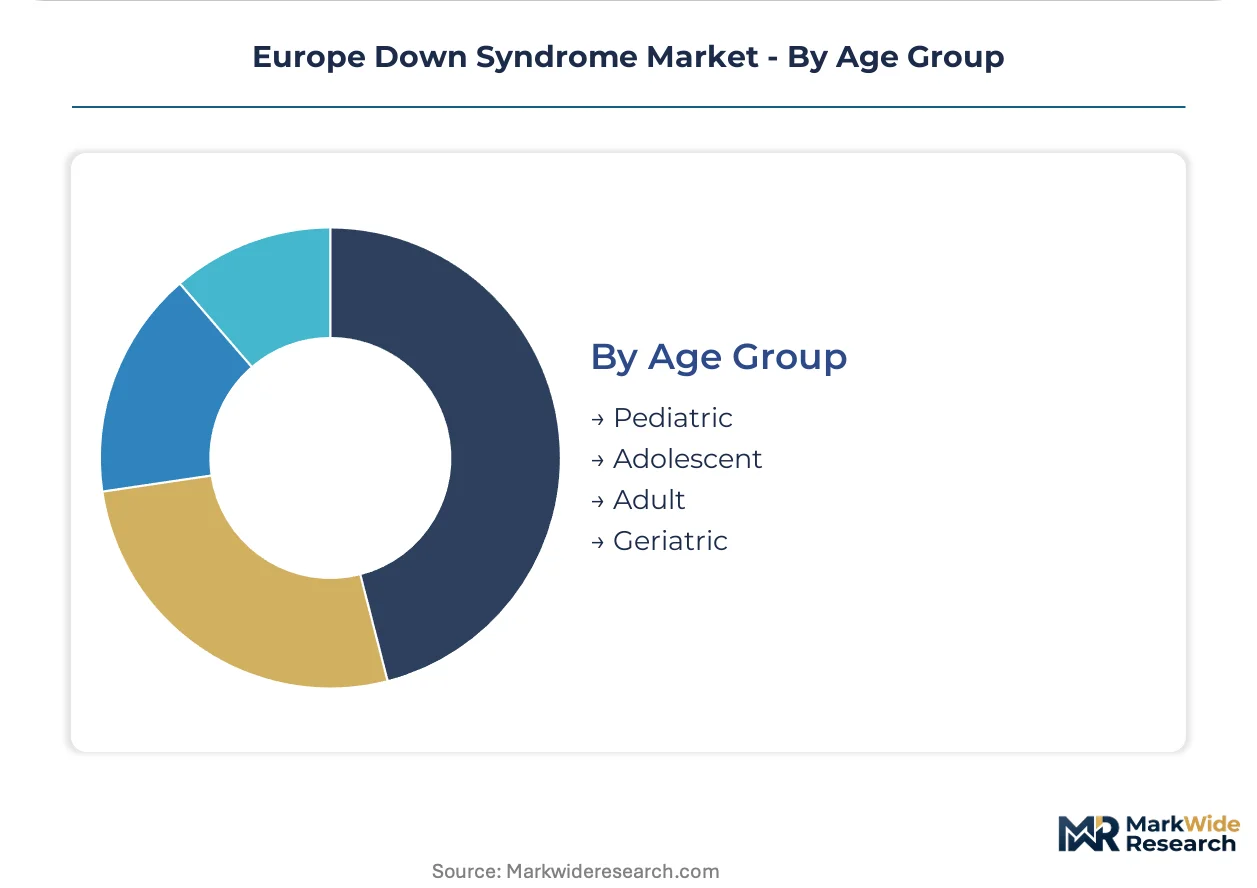
Customer lifecycle progression creates distinct service requirements, from neonatal cardiac surgery through adult transition planning to geriatric Alzheimer's monitoring.
- Pediatric:Congenital heart defect repair, early developmental screening, and family support program enrollment.
- Adolescent:Transition planning from pediatric to adult care systems and educational-vocational preparation.
- Adult:Employment support, independent living services, and routine health maintenance.
- Geriatric:Early-onset Alzheimer's disease monitoring and specialized dementia care.
Pediatric segments command the most intensive service coordination. Geriatric is climbing the fastest as population aging intersects with improved life expectancy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA regulatory pathways anchor demand concentration across Western European specialized care networks. National screening program maturity varies sharply, creating tiered market access conditions for diagnostic and therapeutic developers.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia drive centralized molecular diagnostics procurement for chromosomal microarray workflows. The Federal Joint Committee (G-BA) mandates first-trimester screening coverage through statutory health insurance. Berlin-Brandenburg clusters host specialized pediatric cardiology centers performing complex congenital heart defect repairs.
United Kingdom
National Health Service England operates the most mature non-invasive prenatal testing program in Europe, with maternal-fetal medicine units in London and the Southeast adopting NGS-based platforms. The National Screening Committee sets evidence standards for novel diagnostic introduction. Greater Manchester and West Midlands rehabilitation centers coordinate consortium-structured assistive technology procurement.
France
ANSM regulates orphan neurological therapeutics while CNIL enforces GDPR genetic data provisions for prenatal screening laboratories. The Haute Autorité de Santé determines reimbursement eligibility for novel diagnostics. Île-de-France concentrates specialized Alzheimer's research infrastructure for Down syndrome-associated neurodegeneration trials.
Spain
Underdeveloped national screening infrastructure creates white-space expansion potential for prenatal diagnostic platform providers. The Spanish Agency for Medicines and Health Products (AEMPS) maintains CE marking recognition pathways. Catalonia and Madrid host the most advanced maternal-fetal medicine units, though coverage gaps persist in Southern and Northwestern regions.
Italy
Regional health system fragmentation produces uneven access to specialized Down syndrome care, with Lombardy and Emilia-Romagna outperforming Southern regions. The Italian Medicines Agency (AIFA) manages orphan drug reimbursement through centralized negotiation. Milan and Bologna anchor the limited clinical trial infrastructure for neurodegenerative therapeutic candidates.
Europe Down Syndrome Market Competitive Landscape
Capability concentration sits with molecular diagnostics specialists; scale advantage sits with diversified life science conglomerates. The market exhibits tiered structure, with premium-tier players commanding centralized laboratory contracts and mid-tier specialists competing on assay customization. Three archetypes dominate: multinational diagnostics platforms, neurodegenerative biotech developers, and genetic testing service laboratories. Competitive moves center on EMA orphan designation pursuit and university hospital network exclusivity agreements.
Within the molecular diagnostics tier, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific Inc exemplify scale-driven platform providers anchoring centralized laboratory workflows across German and UK health systems. Among neurodegenerative specialists, AC Immune SA occupies a position representing tau-targeting therapeutic development for Down syndrome-associated Alzheimer's indications. These three entities collectively illustrate the capability-scale bifurcation shaping procurement authority in European specialized care networks.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| AC Immune SA |
| Aelis Farma |
| Annovis Bio, Inc. |
| Alzheon Inc. |
| Natera, Inc. |
| Myriad Genetics, Inc. |
| Thermo Fisher Scientific Inc |
| NeuroNascent, Inc. |
| Others |
Supply & Pricing Matrix
GDPR Article 9 compliance costs for genetic data encryption and consent-management infrastructure determine both pricing tier spreads and supply chain shape across European prenatal screening networks. Laboratories in France and Germany absorb these fixed-cost burdens differently, creating divergence in how diagnostic platforms price into centralized versus distributed procurement channels.
Pricing Analysis
German university hospital networks command lower per-test pricing than Southern European clinics due to volume-scale procurement and bundled reagent supply agreements. Three-tier pricing structure across premium NGS platforms, standard chromosomal microarray workflows, and economy-tier karyotyping separates procurement tiers by turnaround time and biomarker depth. Price differentiation hinges on CE marking tier under EU Medical Device Regulation and after-sales calibration service intensity. Cost compression in economy-tier karyotyping intensifies because Spanish and Italian laboratories delay infrastructure upgrades. Home care segments exhibit highest price sensitivity; tertiary cardiac surgery centers show lowest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier-financing structures for chromosomal microarray reagents and NGS consumables, straining mid-tier laboratory cash conversion. Supply concentrates in Germany, the United Kingdom, and Switzerland for molecular diagnostics platform manufacturing; reagent production draws from Ireland and the Netherlands. Raw material dependencies include semiconductor-grade silicon for sequencing chips, fluorophore conjugates for FISH probes, and synthetic oligonucleotide libraries. Single-source vulnerability for EU-sourced sequencing chemistries threatens continuity. Distribution runs through specialized medical device distributors with cold-chain capabilities into hospital central stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from continuous laboratory recertification and reagent subscription models expands faster than capital equipment sales across European Down syndrome diagnostics. Recurring calibration and compliance-management contracts now capture margin pools previously lost to transactional hardware procurement.
For Market Incumbents: Insulate centralized laboratory contracts by embedding EMA pediatric investigation plan consulting into diagnostic platform sales, blocking emerging entrants from trial-site relationships. Deepen backward integration into oligonucleotide synthesis to neutralize reagent supply volatility threatening margin stability in chromosomal microarray workflows. For New Entrants and Emerging Players: Spain's underdeveloped national screening infrastructure offers white-space expansion for NGS-based prenatal testing platforms seeking first-mover positioning before infrastructure consolidation. Target maternal-fetal medicine units in Catalonia and Madrid with risk-sharing pricing that defers capital commitment until volume thresholds validate. Pursue AEMPS fast-track CE marking recognition to compress time-to-revenue versus established competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-integrated diagnostics conglomerates over point-solution specialists. Long-term viability across the analysis window rests on capturing recurring reagent revenue streams rather than episodic capital equipment sales. Acquisition target archetype: molecular diagnostics specialists with embedded EMA regulatory affairs capabilities and existing university hospital network contracts. Monitor EMA orphan designation grant velocity for tau-targeting neurodegenerative pipelines as inflection indicator for therapeutic segment capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | AEMPS recognition in Spain accelerates platform entry before competitor infrastructure lock-in. |
| Hospital System Partnership | German university hospital network exclusivity agreements anchor chromosomal microarray volume commitments. |
| Software Companion Development | GDPR-compliant laboratory information systems differentiate platform offerings in French maternal-fetal medicine units. |
| Reimbursement Strategy | G-BA coverage mandates in Germany secure statutory health insurance payment for first-trimester screening protocols. |
| Regulatory Approval Pathway | EMA orphan designation for tau-targeting therapeutics unlocks development timeline compression for Down syndrome-associated Alzheimer's candidates. |
Research Methodology
Operator-level perspectives from maternal-fetal medicine directors, laboratory information system procurement managers, EMA regulatory affairs specialists, and rehabilitation center purchasing consortium leads anchored the qualitative base. Primary interviews combined with secondary validation from EMA submission databases, ClinicalTrials.gov orphan designation records, G-BA coverage decision documents, and CNIL GDPR enforcement case files. Bottom-up test volume modeling and top-down healthcare expenditure triangulation cross-verified segment sizing across the analysis window.
Scenario-bracketing framed volume and value outputs across diagnostic, therapeutic, and support product segments, with treatment approach, age group, and national regulatory cluster as core stratification dimensions. CAGRs derived from fitted growth curves against historical adoption patterns for non-invasive prenatal testing and orphan neurological therapeutic pipelines. Forecast inputs included national screening program expansion timelines and EMA pediatric investigation plan requirement evolution.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by diversified life science conglomerates or accelerated AEMPS infrastructure approvals would shift outcomes. Macroeconomic pressure on statutory health insurance budgets, regulatory deviation in GDPR genetic data enforcement, or breakthrough therapeutic efficacy in tau-targeting candidates would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market