
 Lennox-Gastaut Syndrome Market | 2026-2036
Lennox-Gastaut Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Lennox-Gastaut Syndrome Market Outlook
Good Manufacturing Practice certification for central nervous system active pharmaceutical ingredients is unwinding the competitive landscape for LGS drug developers. Eisai Co., Ltd leverages its established epilepsy franchise to sustain prescriber loyalty across refractory indications. Jazz Pharmaceuticals anchors its position through deep specialization in orphan neurological disorders and controlled-substance distribution expertise. Marinus Pharmaceuticals competes by advancing neuroactive steroid platforms distinct from traditional antiepileptic mechanisms.
Lennox-Gastaut syndrome constitutes a severe developmental epileptic encephalopathy characterized by multiple seizure types, cognitive impairment, and electroencephalographic findings of slow spike-and-wave complexes below 2.5 Hz, with treatment resistance defining its clinical management challenge. Pharmaceutical interventions dominate commercial activity, with CBD oil formulations capturing premium positioning due to FDA-approved status and restricted distribution requirements. Outpatient clinics represent the highest-velocity treatment setting as payors push toward lower-acuity care for chronic maintenance, while inpatient hospitals retain margin concentration for acute seizure rescue and device implantation procedures.
FDA orphan drug exclusivity provisions and DEA scheduling requirements for cannabinoid therapies shape product development timelines and market access conditions for LGS participants. The European Medicines Agency's pediatric investigation plans and EMA centralized procedure for orphan indications create parallel regulatory pathways that developers must navigate simultaneously. Stakeholders should monitor FDA advisory committee signals on novel antiepileptic mechanisms and DEA production quota adjustments for controlled substances that could abruptly alter competitive supply availability.
Market Dynamics
FDA orphan drug exclusivity provisions and DEA scheduling requirements for cannabinoid therapies are compressing development timelines while creating protected revenue windows for developers who navigate the dual-track approval process successfully.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug designation pathway accelerates review timelines and grants seven-year market exclusivity, pulling investment into refractory epilepsy research programs.
- Academic Medical Center Expansion:Pediatric neurology departments at major university hospitals are building dedicated LGS treatment protocols, creating institutional demand pull for specialized therapies.
- Neuroactive Steroid Platforms:Novel mechanisms targeting GABA-A receptor modulation are expanding the pharmacological armamentarium beyond traditional sodium channel and synaptic vesicle protein targets.
Market Restraints
- Controlled Substance Quotas:DEA production quota adjustments for Schedule V cannabinoid therapies create abrupt supply availability constraints that destabilize distribution planning.
- Central Nervous System API Certification:Good Manufacturing Practice certification requirements for CNS-active pharmaceutical ingredients concentrate capable manufacturing among a limited supplier base in Western Europe and North America.
- Treatment Resistance Biology:The underlying epileptic encephalopathy pathology limits therapeutic efficacy ceilings, compressing addressable patient populations for any single mechanism.
Strategic Opportunities
- EMA Centralized Orphan Pathway:The European Medicines Agency's parallel regulatory track enables simultaneous US-EU market entry, expanding protected exclusivity geography.
- Outpatient Clinic Migration:Payor pressure toward lower-acuity chronic maintenance care is shifting treatment volume from inpatient hospitals to specialized outpatient epilepsy centers.
- Pediatric Investigation Plans:EMA-mandated pediatric study requirements create regulatory data packages that accelerate adult indication expansions and build prescriber familiarity.
Industry Challenges
- Epileptologist Workforce Constraints:The limited pool of board-certified epileptologists capable of diagnosing complex electroencephalographic patterns bottlenecks accurate patient identification and referral.
- Reimbursement Coding Fragmentation:Inconsistent medical billing codes across state Medicaid programs for cannabinoid-based therapies create prior authorization friction and payment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lennox-Gastaut Syndrome Market |
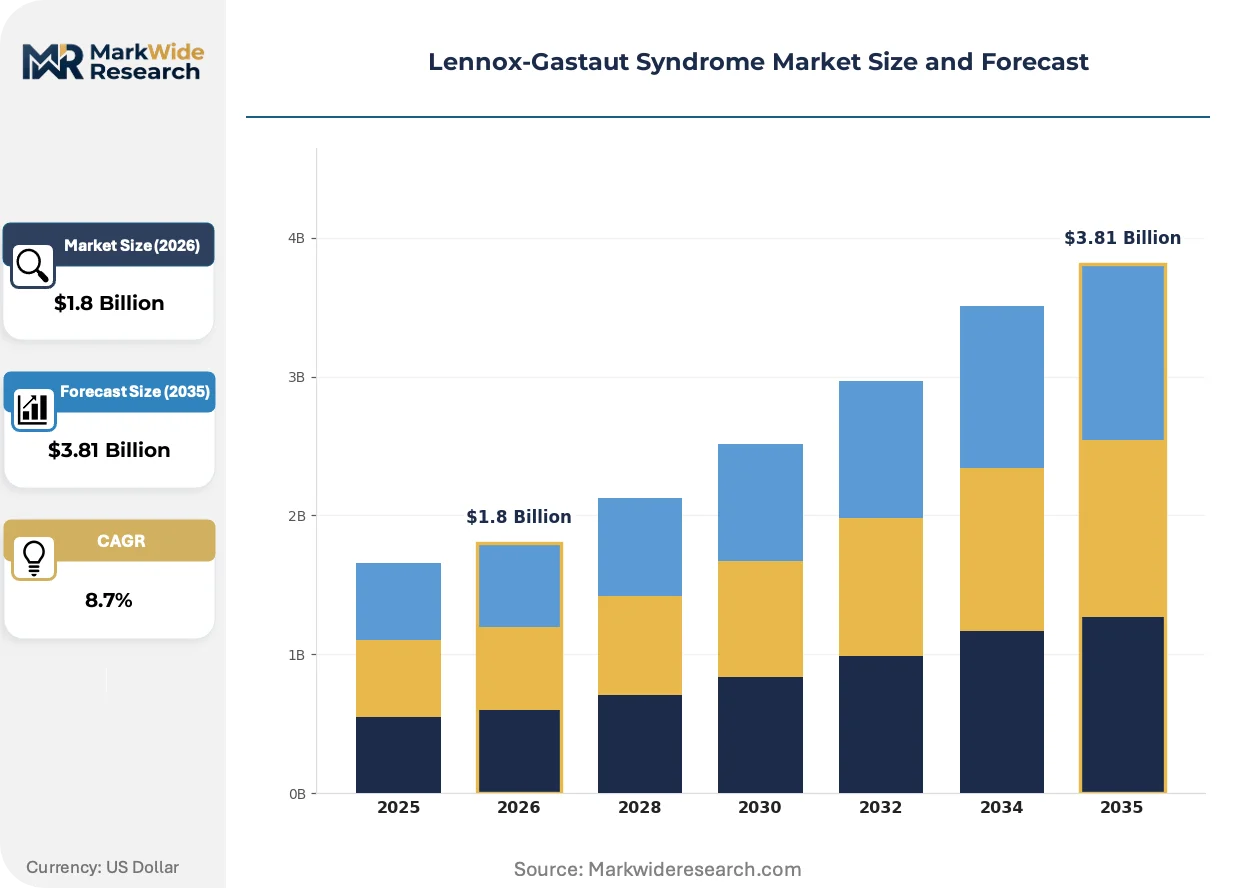
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AEDs, CBD Oil, Vagus Nerve Stimulation, Dietary Therapies Treatment Setting: Outpatient Clinics, Inpatient Hospitals, Home Care, Rehabilitation Centers Age Group: Pediatric Patients, Adolescent Patients, Adult Patients, Geriatric Patients Therapy Area: Neurology, Psychiatry, Pediatric Care, Epileptology |
| Companies Covered | Novartis AG, Pfizer Inc., F. Hoffmann-La Roche Ltd, Jazz Pharmaceuticals, Takeda Pharmaceutical, GlaxoSmithKline, Eisai Co., Ltd, Marinus Pharmaceuticals, Zogenix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lennox-Gastaut Syndrome Market Strategic Shifts
Novel antiepileptic mechanisms and device-neuropharmacology convergence are restructuring competitive positioning, with developers racing to differentiate beyond traditional receptor targets.
Responsive neurostimulation systems are miniaturizing implantable pulse generator form factors while expanding seizure detection algorithm sophistication. Pediatric epilepsy centers at Cincinnati Children's Hospital and Boston Children's Hospital are piloting next-generation devices with closed-loop stimulation capabilities. This miniaturization is compressing the invasive procedure threshold, enabling earlier intervention in developmental trajectories.
The EMA's pediatric investigation plans and FDA's orphan drug exclusivity provisions are synchronizing transatlantic development timelines. Developers must now design parallel clinical programs satisfying both agencies' evidentiary standards simultaneously. Cannabinoid therapy developers face the steepest compliance burden, as DEA scheduling and EMA quality certification create overlapping but non-identical documentation requirements.
Specialized epileptology referral networks are consolidating patient volume into designated centers of excellence. Academic medical centers in the United States are capturing complex case referrals that community neurology practices previously managed, concentrating prescriber influence and formulary decision-making. This channel compression privileges developers with established academic detailing relationships and dedicated rare disease sales infrastructure.
Lennox-Gastaut Syndrome Market Segmentation
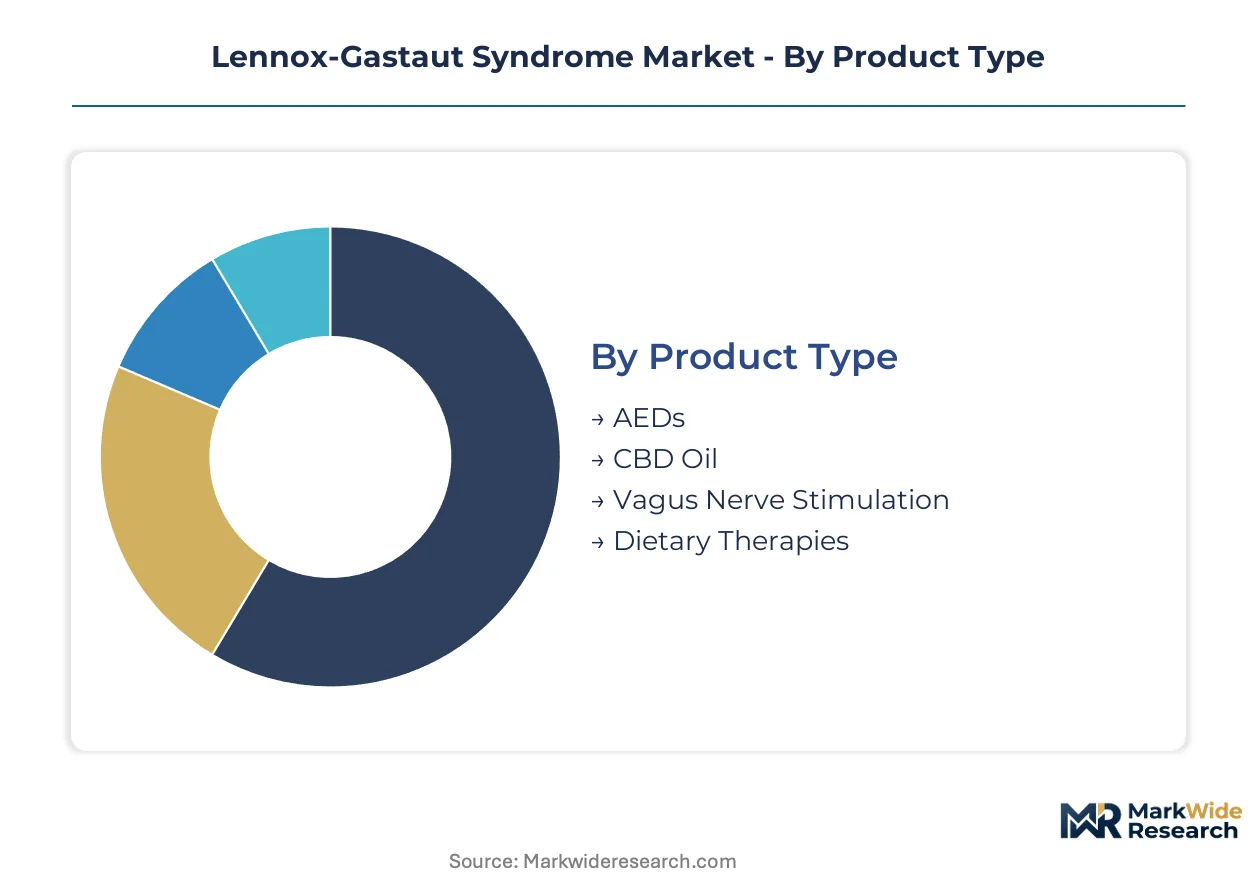
LGS treatment pathways fragment across intervention modalities and care delivery sites, with each segment carrying distinct regulatory burdens and prescriber specialization requirements. Pharmaceutical developers must align product positioning with the specific clinical settings and patient demographics where reimbursement pathways are most established.
Product Type:
Domestic demand concentrates on FDA-approved pharmaceutical formulations, while export-led growth follows EMA centralized approvals into Western European markets.
- AEDs:Traditional antiepileptic drugs including valproate, lamotrigine, and rufinamide constitute the foundational pharmacological approach, with prescriber familiarity sustaining volume despite incomplete seizure control. Demand clusters in academic medical center formularies where polytherapy protocols are standard, constrained by generic erosion of older agents.
- CBD Oil:Purified cannabidiol formulations operate under DEA Schedule V controls with restricted distribution networks, creating premium positioning through FDA orphan exclusivity. Epidiolex and competing purified extracts command specialized pharmacy channels, with supply quotas limiting geographic expansion.
- Vagus Nerve Stimulation:Implantable pulse generator systems require neurosurgical placement at designated epilepsy centers, concentrating procurement among high-volume academic hospitals with device implantation privileges.
- Dietary Therapies:Ketogenic and modified Atkins protocols rely on specialized metabolic dietitian support available primarily at pediatric referral centers in the United States.
AEDs command the established base. The steepest expansion runs through CBD Oil.
Treatment Setting:
Cost tier differentiation separates high-acuity inpatient procedures from maintenance-focused outpatient management, with margin profiles inversely distributed to volume concentration.
- Outpatient Clinics:Specialized epilepsy centers manage chronic maintenance and medication titration, capturing volume migration as payors push lower-acuity care outside hospital walls. Prescriber concentration at Cincinnati Children's Hospital, Boston Children's Hospital, and similar academic hubs drives formulary decision-making.
- Inpatient Hospitals:Acute seizure rescue, status epilepticus management, and device implantation procedures retain margin concentration despite declining share of total patient encounters. Neurosurgical capacity constraints limit expansion.
- Home Care:Rescue medication administration and ketogenic diet monitoring extend institutional protocols into residential settings, contingent on caregiver training and remote monitoring infrastructure.
- Rehabilitation Centers:Post-acute cognitive and functional recovery programs address the developmental encephalopathy sequelae, with limited pharmaceutical content in care pathways.
Inpatient Hospitals capture the premium margin tier. Outpatient Clinics are gaining share fastest.
Age Group:
Application intensity varies sharply across developmental stages, with pediatric populations driving clinical trial enrollment and adult segments presenting undertreated prevalence.
- Pediatric Patients:Children under 12 represent the diagnostic incidence peak and the mandatory population for EMA pediatric investigation plans, with seizure semiology complexity requiring specialized electroencephalographic interpretation at designated centers.
- Adolescent Patients:Transition-age youth face care coordination gaps between pediatric and adult neurology services, with medication adherence challenges and emerging psychiatric comorbidities.
- Adult Patients:Longstanding LGS cases persist into adulthood with accumulated polytherapy resistance, representing an undertreated population outside traditional pediatric drug development programs.
- Geriatric Patients:Late-onset LGS remains rare, with diagnostic confusion against other neurodegenerative epilepsies limiting recognized prevalence.
Pediatric Patients anchor clinical development investment. Adult Patients present the steepest expansion trajectory.
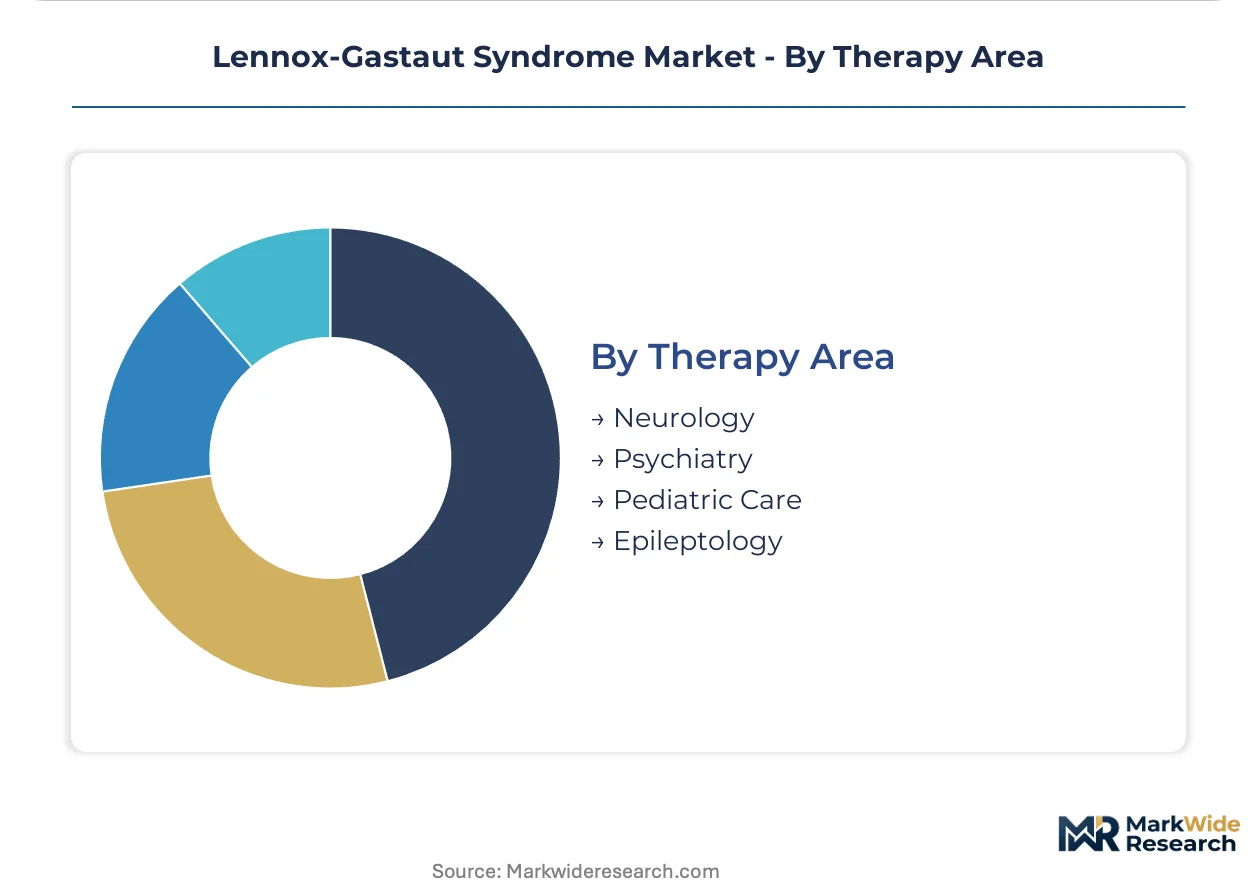
Therapy Area:
Customer type specialization determines prescriber access and detailing strategy, with neurologic subspecialty certification creating credentialing barriers.
- Neurology:General neurologists manage the broadest patient base but refer complex cases to subspecialists, serving as gatekeepers rather than definitive treaters.
- Psychiatry:Behavioral comorbidities including autism spectrum features and intellectual disability require psychiatric co-management, with psychopharmacology expertise addressing mood and aggression targets.
- Pediatric Care:Developmental pediatricians coordinate multidisciplinary care across seizure, cognitive, and functional domains, particularly in integrated academic medical center models.
- Epileptology:Board-certified epileptologists at level 3 and 4 epilepsy centers control access to advanced therapies including device implantation and clinical trial enrollment, concentrating prescriber influence.
Neurology provides the broadest access point. Epileptology controls the highest-value interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug exclusivity provisions concentrate commercial activity in the United States, while EMA centralized procedures and national reimbursement frameworks shape parallel expansion across Western Europe. Academic medical center density and specialized epileptology referral networks determine geographic demand intensity.
United States
Pediatric neurology departments at Cincinnati Children's Hospital and Boston Children's Hospital anchor specialized LGS treatment protocols. FDA orphan drug designation grants seven-year market exclusivity, accelerating developer investment. DEA Schedule V scheduling for cannabinoid therapies creates restricted distribution networks concentrated in high-volume academic centers.
Germany
EMA centralized orphan pathway approvals enable simultaneous US-EU market entry, expanding protected exclusivity geography. Germany's national pharmaceutical regulator enforces pediatric investigation plan compliance for all novel antiepileptic submissions. Heidelberg and Munich academic medical centers concentrate prescriber expertise and formulary decision-making authority.
United Kingdom
NICE technology appraisals determine NHS reimbursement for refractory epilepsy therapies, creating distinct access conditions from continental markets. The MHRA operates under retained EU orphan drug frameworks post-Brexit. London's Great Ormond Street Hospital and Manchester pediatric neurology units drive clinical trial enrollment and specialist referral volume.
Japan
PMDA orphan drug designation parallels FDA incentives, though domestic clinical trial requirements extend development timelines. METI industrial policy supports neuroactive steroid platform research through targeted R&D subsidies. Tokyo and Osaka university hospitals maintain the highest concentration of board-certified pediatric epileptologists in Asia-Pacific.
Switzerland
Swissmedic expedited pathways for rare neurological disorders attract EU-parallel development programs. Premium pricing acceptance for orphan indications supports commercial viability despite small patient populations. Basel and Zurich academic medical centers coordinate multicenter pediatric epilepsy research across German-speaking Europe.
Lennox-Gastaut Syndrome Market Competitive Environment
Player mix skews toward established epilepsy franchise holders and orphan neurological specialists. Market structure concentrates around developers with existing prescriber relationships in refractory indications. Three archetypes dominate: diversified pharmaceutical conglomerates with CNS divisions, rare disease specialists with controlled-substance distribution expertise, and mechanism-focused biotechs advancing novel GABA-A targets. Competitive moves center on portfolio expansion into adjacent refractory epilepsies and academic detailing infrastructure buildout.
Within the established franchise tier, Eisai Co., Ltd and Jazz Pharmaceuticals occupy positions anchored by prescriber loyalty and orphan specialization. Eisai exemplifies the diversified pharmaceutical archetype with sustained epilepsy portfolio presence. Jazz Pharmaceuticals represents rare disease specialist positioning with controlled-substance distribution capabilities. Marinus Pharmaceuticals sits within the mechanism-driven biotech segment, advancing neuroactive steroid platforms distinct from traditional antiepileptic targets.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Jazz Pharmaceuticals |
| Takeda Pharmaceutical |
| GlaxoSmithKline |
| Eisai Co., Ltd |
| Marinus Pharmaceuticals |
| Zogenix Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day DEA production quota cycles for Schedule V cannabinoid APIs tether pricing power to supply availability windows, concentrating margin capture among developers with captive manufacturing or long-term offtake agreements with Western European CNS-active pharmaceutical ingredient specialists.
Pricing Analysis
Cost-plus contracts with FDA orphan drug exclusivity indexation anchor pricing for purified cannabidiol formulations. Three-tier pricing structure across premium orphan-branded, standard authorized generic, and economy unlicensed import tiers separates reimbursement-eligible from cash-pay channels. Cost compression in the economy tier intensifies because DEA quota constraints limit volume scale advantages. Academic medical center formularies exhibit lowest price sensitivity due to restricted distribution requirements, while Medicaid programs demonstrate highest sensitivity due to prior authorization friction.
Supply Chain Analysis
Swissmedic certification bottlenecks for GMP-compliant neuroactive steroid synthesis concentrate API supply among Switzerland, Germany, and Ireland. Active pharmaceutical ingredient production draws from specialized CNS chemistry capabilities, purified cannabidiol agricultural extraction, and implantable pulse generator microelectronics. Single-source vulnerability runs through DEA-registered Schedule V manufacturing sites. Distribution runs through restricted specialty pharmacy networks concentrated at academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lennox-Gastaut syndrome therapeutics sit in early-cycle expansion, with neuroactive steroid platforms and responsive neurostimulation devices driving penetration beyond traditional antiepileptic polytherapy protocols.
For Market Incumbents: Secure orphan drug exclusivity extensions through pediatric investigation plan compliance and simultaneous EMA centralized pathway submissions. Deepen backward integration into GMP-certified CNS API manufacturing to defend against DEA quota volatility. Lock academic detailing relationships at Cincinnati Children's Hospital and Boston Children's Hospital before competitor device trials conclude. For New Entrants and Emerging Players: Lead with adult LGS populations outside traditional pediatric development programs, where prescriber familiarity gaps create white-space access. Target transition-age adolescent segments facing care coordination failures between pediatric and adult neurology services. Pursue rescue medication formulations with remote monitoring companions as the go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with underutilized epilepsy franchises and stalled CNS pipelines. Long-term viability hinges on neuroactive steroid mechanism differentiation and closed-loop device-neuropharmacology convergence. Watch FDA advisory committee signals on novel GABA-A modulators as the inflection indicator for competitive positioning resets.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Exclusivity Extension | FDA seven-year market protection accelerates developer investment into refractory epilepsy research programs. |
| Pediatric Investigation Plan Compliance | EMA-mandated studies build regulatory data packages that streamline adult indication expansions. |
| Neuroactive Steroid Platform Advancement | Novel GABA-A receptor modulation mechanisms differentiate beyond sodium channel and synaptic vesicle targets. |
| Academic Medical Center Partnership | Cincinnati Children's Hospital and Boston Children's Hospital anchor prescriber influence and formulary control. |
| Responsive Neurostimulation Miniaturization | Closed-loop seizure detection algorithms compress invasive procedure thresholds for earlier developmental intervention. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designations, EMA pediatric investigation plans, DEA controlled substance quotas, and academic medical center formulary databases. Conversations with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists inform demand-side validation. Bottom-up patient prevalence modeling triangulates against top-down pharmaceutical revenue estimates across the analysis window.
Segmentation dimensions modeled include treatment modality, care delivery setting, patient age group, and prescriber specialty certification. CAGRs derive from epidemiological incidence projections, therapy penetration assumptions, and pricing trajectory analysis. Neuroactive steroid pipeline advancement timelines and DEA production quota adjustment patterns serve as industry-specific forecast inputs throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside FDA orphan exclusivity enforcement, EMA centralized procedure timelines, or DEA scheduling stability would require recalibration. Practitioners should keep alternative scenarios live as regulatory agency advisory committee signals and controlled substance policy shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Fabry Disease Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Lesch-Nyhan Syndrome Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Global Hemoglobinopathies Market