
 North America Rett Syndrome Market | 2026-2036
North America Rett Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rett Syndrome Market Analytics
Gene therapy development revenue is rewriting how capital flows across the Rett Syndrome value chain. Acadia Pharmaceuticals leverages its commercial infrastructure in neuropsychiatric indications to sustain a first-mover position in approved symptomatic treatments. Anavex Life Sciences Corp. anchors its competitive profile through R&D intensity in sigma-1 receptor modulation, while Taysha Gene Therapies positions its AAV9-based programs to occupy the emerging in vivo gene correction segment.
Rett Syndrome constitutes a severe X-linked dominant neurodevelopmental disorder caused by MECP2 gene mutations, characterized by apparently normal early development followed by regression of acquired skills, loss of purposeful hand use, and respiratory abnormalities including breath-holding and hyperventilation. The condition primarily demands lifelong multidisciplinary management spanning neurology, gastroenterology, orthopedics, and respiratory support. Medications and gene therapy candidates command the deepest investment pools, while diagnostic tools benefit from expanding newborn screening panels and MECP2 sequencing protocols. Hospitals and academic medical centers represent the dominant end-user channel, though home care services are gaining structural importance as families seek to reduce institutionalization.
The FDA Office of Orphan Products Development shapes trial design incentives through orphan drug designation and rare pediatric disease priority review vouchers, while Health Canada and the US Department of Health and Human Services coordinate cross-border natural history study protocols. State-level newborn screening expansions in California and New York are reshaping early detection timelines and subsequent treatment windows. Stakeholders must monitor how gene therapy reimbursement frameworks evolve across provincial and federal payer systems before committing to manufacturing scale-up investments.
Market Dynamics
Gene therapy reimbursement uncertainty is compressing capital deployment timelines across the Rett Syndrome therapeutic pipeline. Payers in the United States and Canada are constructing novel value assessment frameworks for single-dose curative interventions, forcing developers to front-load health economic evidence generation.
Growth Catalysts
- FDA Rare Pediatric Disease Priority Review Voucher Program:Developers accelerate clinical timelines to capture transferable voucher value, channeling resources into Rett-specific trial infrastructure.
- Newborn screening expansion in California and New York:Earlier MECP2 detection compresses diagnostic delay, widening the addressable patient pool for intervention candidates.
- Academic medical center clustering:Boston and New York anchor specialized neurology referral networks, concentrating trial-ready patient access for sponsors.
Market Restraints
- AAV manufacturing capacity concentration:Viral vector production bottlenecks in contract manufacturing organizations delay gene therapy supply scale-up.
- Cross-border reimbursement heterogeneity:Provincial formulary divergence in Canada fragments commercial strategy for unified North American launches.
- Natural history data gaps:Incomplete longitudinal registries complicate regulatory endpoint validation for novel mechanism drugs.
Strategic Opportunities
- Home-based respiratory monitoring technology:Remote patient monitoring platforms create new reimbursement codes for decentralized Rett care management.
- Sigma-1 receptor modulation expansion:Adjacent neurodevelopmental indications offer label expansion pathways beyond core Rett symptoms.
- Centers of Excellence network development:Tiered hospital certification programs concentrate high-acuity procedures and command premium reimbursement.
Industry Challenges
- Pediatric neurology specialist scarcity:Fellowship program output fails to match Rett-specific clinic expansion demand across academic medical centers.
- Gene therapy site activation complexity:Institutional review board variability across states prolongs multi-center trial initiation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rett Syndrome Market |
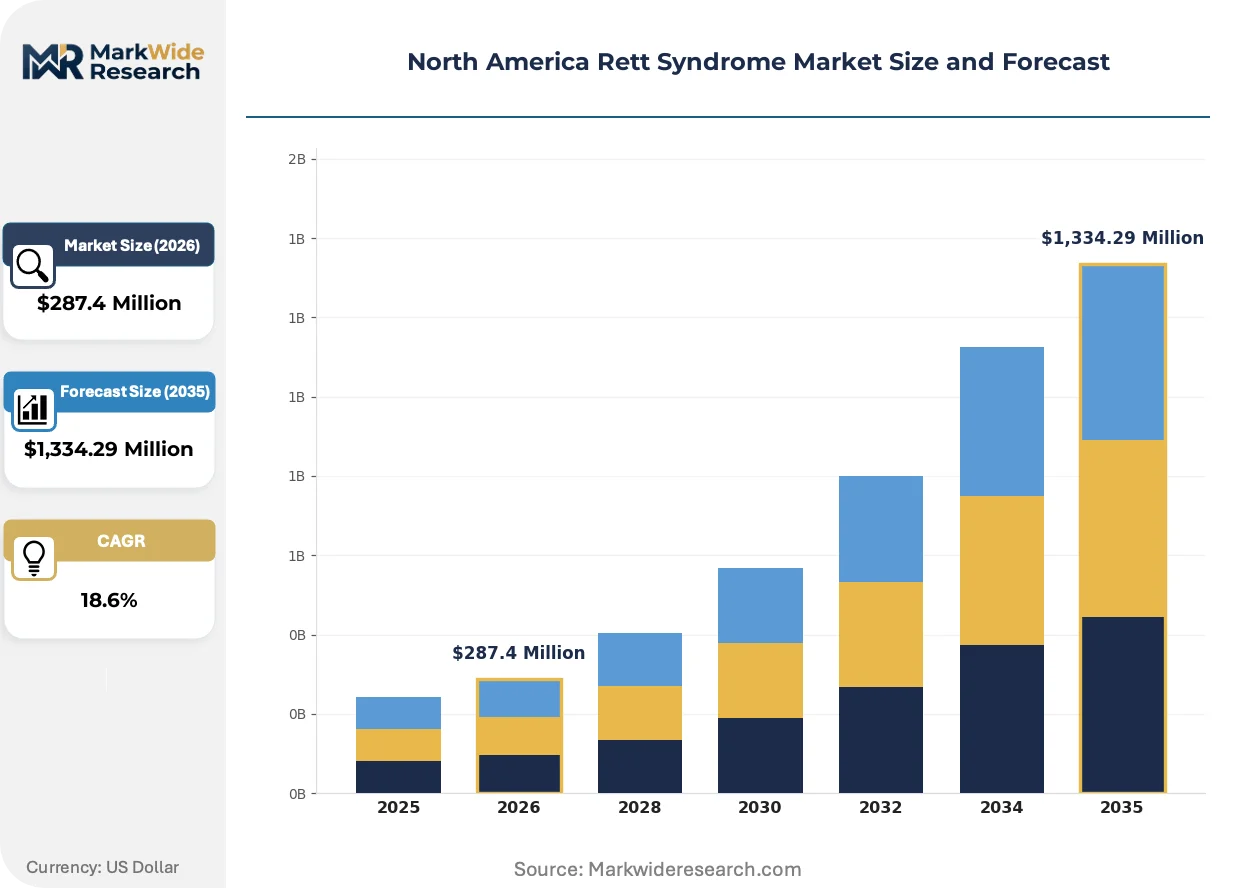
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $1,334.29 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Therapies, Diagnostic Tools, Support Services End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Oral, Injectable, Infusion, Transdermal Application: Symptom Management, Genetic Testing, Behavioral Support, Educational Programs |
| Companies Covered | Acadia Pharmaceuticals Inc., Anavex Life Sciences Corp., Neurogene Inc., Taysha Gene Therapies, Inc., Biohaven Pharmaceuticals, Inc., Wave Life Sciences, Axonis Therapeutics, Unravel Biosciences, Inc., Prilenia Therapeutics B.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rett Syndrome Market Evolving Landscape
Biomarker-guided trial design is replacing functional endpoint dependency in neurodevelopmental drug development. This shift demands concurrent investment in digital health phenotyping platforms and regulatory science alignment.
AAV9-based in vivo gene correction is collapsing the traditional separation between symptomatic management and disease modification. Pediatric neurology clinics in Boston and New York are adopting pre-symptomatic intervention protocols for screen-detected infants. This compression is redrawing competitive boundaries between gene therapy developers and established neurology drug franchises.
FDA Office of Orphan Products Development is streamlining natural history study requirements for Rett Syndrome through its Rare Disease Cures Accelerator program. Sponsors now integrate prospective registry data into pivotal trial designs rather than conducting parallel observational studies. Gene therapy candidates targeting MECP2 replacement are the primary beneficiaries of this procedural consolidation.
Family advocacy organizations are displacing traditional physician referral as the dominant patient identification channel. Rett Syndrome Research Trust and International Rett Syndrome Foundation direct families toward trial-naive academic centers, bypassing community neurology. This behavioral shift concentrates trial enrollment in a shrinking number of high-volume sites across the United States.
North America Rett Syndrome Market Segmentation
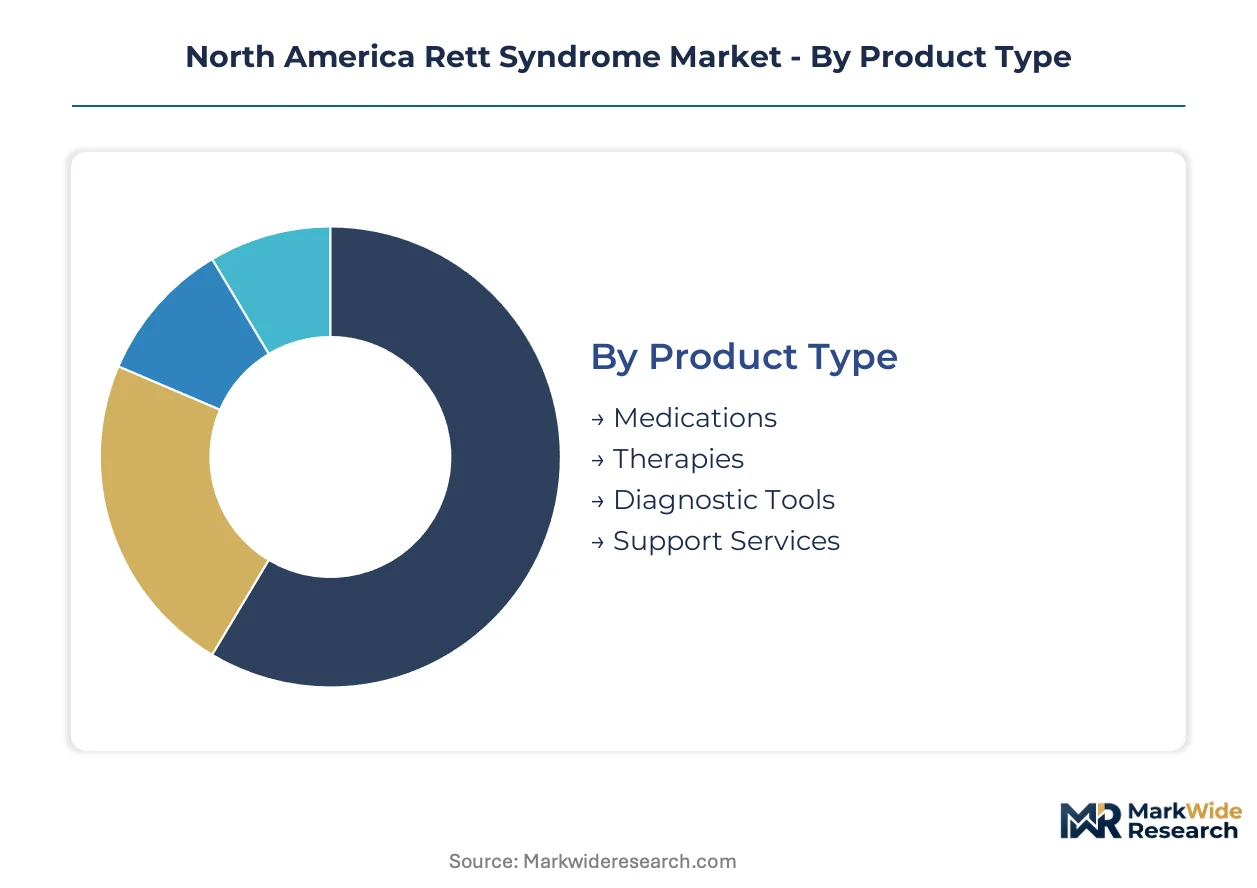
Segmentation in the North America Rett Syndrome market reveals how capital and patient flow concentrate across intervention modalities and care settings. Understanding these divides exposes where reimbursement frameworks and clinical trial infrastructure align or fracture.
Product Type:
Mature pharmaceutical infrastructure coexists with emerging gene therapy platforms across this category.
- Medications:Symptomatic treatments including antiepileptics, gastroprokinetics, and respiratory modulators dominate current prescription volumes. Demand clusters in Boston and New York academic medical centers where pediatric neurologists anchor specialized Rett clinics and trial enrollment pipelines.
- Therapies:Gene replacement candidates utilizing AAV9 vectors and antisense oligonucleotides represent the disease-modification frontier. Investment intensity from venture and strategic capital concentrates here as FDA rare pediatric disease designations accelerate development timelines.
- Diagnostic Tools:MECP2 sequencing panels and newborn screening assays enable earlier detection windows.
- Support Services:Multidisciplinary care coordination spans nutrition, orthopedics, and respiratory management.
Medications handles the majority of throughput; therapies is expanding most quickly on share.
End User:
Cost tier stratification separates institutional reimbursement from emerging home-based payment models.
- Hospitals:Academic medical centers command premium reimbursement for complex procedures including gastrostomy placement and scoliosis correction. California and New York state Medicaid programs increasingly require tiered center-of-excellence certification for high-acuity Rett procedures.
- Clinics:Outpatient pediatric neurology practices deliver ongoing symptomatic management and trial monitoring. Site concentration in metropolitan corridors creates geographic access disparities for rural families seeking specialized care.
- Home Care:Respiratory monitoring and feeding support services are gaining structural importance as families pursue decentralized care models.
- Rehabilitation Centers:Physical and occupational therapy programs address motor regression and adaptive equipment needs.
Hospitals retains the dominant revenue position; home care is climbing the fastest as payment models shift toward community-based management.
Delivery Mode:
Application context determines route selection across acute intervention versus chronic maintenance.
- Oral:Liquid formulations and compounded suspensions accommodate dysphagia common in Rett patients. Palatability and gastric motility challenges limit bioavailability for certain drug classes.
- Injectable:Subcutaneous and intramuscular routes serve rescue medications and long-acting formulations. Boston Children's Hospital and NewYork-Presbyterian anchor injection protocol standardization for clinical trial networks.
- Infusion:Intravenous gene therapy delivery requires specialized infusion centers with anesthesia support.
- Transdermal:Patch-based delivery avoids gastrointestinal complications for select symptomatic agents.
Oral administration maintains the highest prescription frequency; infusion is gaining share fastest as gene therapy candidates advance through pivotal trials.
Application:
Volume concentration sits with ongoing management while margin opportunity aligns with predictive and curative modalities.
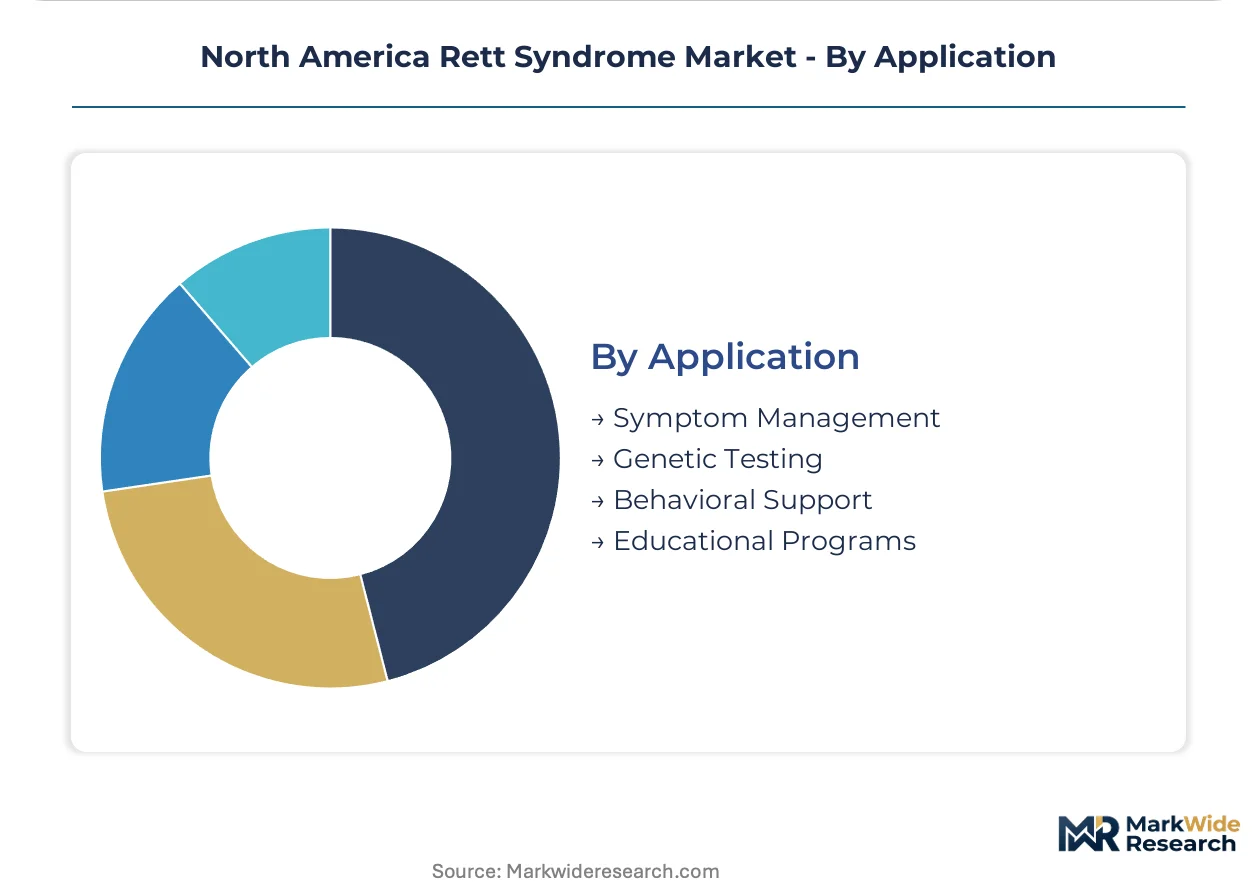
- Symptom Management:Respiratory, seizure, and gastrointestinal interventions constitute the persistent clinical burden. FDA-approved therapies from Acadia Pharmaceuticals and off-label neurology drugs anchor this segment's revenue base.
- Genetic Testing:MECP2 sequence analysis and copy number variant detection enable definitive diagnosis. California and New York newborn screening expansions are compressing diagnostic delay from years to weeks for screen-positive infants.
- Behavioral Support:Augmentative communication devices and anxiety management protocols address core functional deficits.
- Educational Programs:Individualized education plans and adaptive learning technologies support developmental maintenance.
Symptom management carries the bulk of current expenditure; genetic testing shows the steepest expansion trajectory as screening infrastructure proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North American payers: United States commercial insurers absorb premium gene therapy pricing with minimal resistance, while Canadian provincial formularies impose stringent cost-effectiveness thresholds that compress reimbursement timelines. Mexico's out-of-pocket dominant structure creates acute price sensitivity at the patient level, fragmenting market access.
United States
FDA Rare Pediatric Disease Priority Review Vouchers and orphan drug tax credits concentrate gene therapy investment in Massachusetts and New York. Boston Children's Hospital and NewYork-Presbyterian anchor specialized Rett clinic networks that capture trial-ready patient referrals from across the country. State-level newborn screening expansions in California and New York compress diagnostic delay to weeks rather than years.
Canada
Health Canada coordinates cross-border natural history studies with the US Department of Health and Human Services, harmonizing regulatory evidence requirements. Provincial formulary divergence—particularly between Ontario's public drug programs and Quebec's mixed public-private structure—fragments commercial launch strategy. Toronto's Hospital for Sick Children anchors specialized pediatric neurology referral networks serving eastern provinces.
Mexico
Private hospital chains in Mexico City and Monterrey deliver specialized pediatric neurology services to affluent families, while public sector access remains constrained by diagnostic capacity gaps. The national health system's segmentation between IMSS, ISSSTE, and Seguro Popular creates reimbursement complexity for imported therapeutics. Guadalajara's university hospitals are emerging as regional referral hubs for western Mexico.
North America Rett Syndrome Market Competitive Landscape
Capability concentration sits with gene therapy developers commanding vector manufacturing expertise and regulatory science infrastructure; scale advantage sits with established neurology franchises leveraging commercial infrastructure and payer relationships. The market structures around three tiers: approved symptomatic drug marketers, clinical-stage gene correction developers, and preclinical platform technology companies. Dominant competitive moves include strategic partnerships bridging vector manufacturing bottlenecks and portfolio diversification into adjacent neurodevelopmental indications.
Within the gene therapy archetype, Taysha Gene Therapies exemplifies AAV9-based in vivo correction strategy, while Neurogene Inc. occupies a position emphasizing regulatory pathway efficiency. Acadia Pharmaceuticals anchors the commercial-stage tier, representing how neuropsychiatric infrastructure translates into rare disease market access. Anavex Life Sciences Corp. sits within the sigma-1 receptor modulation specialist category, bridging symptomatic and disease-modification positioning.
| Leading Market Players |
|---|
| Acadia Pharmaceuticals Inc. |
| Anavex Life Sciences Corp. |
| Neurogene Inc. |
| Taysha Gene Therapies, Inc. |
| Biohaven Pharmaceuticals, Inc. |
| Wave Life Sciences |
| Axonis Therapeutics |
| Unravel Biosciences, Inc. |
| Prilenia Therapeutics B.V. |
| Others |
Value Network & Pricing Analysis
AAV9 vector manufacturing concentration in the United States and contract manufacturing organizations in Massachusetts and North Carolina anchors where margin pools accumulate across the Rett Syndrome therapeutic value chain. Gene therapy developers face steep upfront production costs that cascade into reimbursement negotiations with commercial insurers and provincial formularies.
Pricing Analysis
After-sales revenue from long-term respiratory monitoring subscriptions and multidisciplinary care coordination contracts drives lifetime patient value beyond initial therapeutic intervention. Three-tier pricing structure across gene therapy, branded symptomatic agents, and generic off-label alternatives segments the market by intervention modality and certification status. Pricing pressure stems from provincial formulary divergence in Canada and Medicaid managed care constraints in California and New York. Home care service providers exhibit highest price sensitivity due to thin reimbursement margins, while academic medical centers command premium rates for complex procedures.
Supply Chain Analysis
Tariff exposure between the United States and China for plasmid DNA and cell culture media inputs dominates supply chain risk assessment for gene therapy developers. Manufacturing capacity concentrates in the United States, with secondary nodes in Germany and Switzerland for specialized reagents. Raw material dependencies include HEK293 cell lines, transfection reagents, and chromatography resins. Single-source vulnerability for GMP-grade AAV9 capsid supply creates bottlenecks. Distribution runs through hospital-based infusion centers and specialized pharmacy networks rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vector manufacturing expertise and regulatory science infrastructure represent acute capability gaps that concentrate competitive advantage among firms with captive bioproduction assets. The market rewards players who can bridge the divide between clinical proof-of-concept and scalable commercial supply.
For Market Incumbents: Insulate gene therapy revenue streams by securing multi-year AAV manufacturing offtake agreements with CDMOs in North Carolina and Massachusetts before capacity constraints intensify. Expand backward integration into plasmid DNA production to reduce input cost volatility. Defend against emerging sigma-1 receptor modulation entrants by deepening relationships with Boston and New York academic medical center referral networks. For New Entrants and Emerging Players: Build out home-based respiratory monitoring platforms as a service layer adjacent to pharmaceutical interventions, capturing reimbursement codes that incumbent drug marketers have underdeveloped. Target California and New York state Medicaid programs where newborn screening expansion creates addressable patient pools without entrenched competitor relationships. Pursue white-label partnerships with family advocacy organizations as the dominant patient identification channel. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed gene therapy developers that have completed Phase I/II trials but face manufacturing scale-up capital requirements. Five-to-ten year viability hinges on FDA rare pediatric disease priority review voucher monetization and cross-border reimbursement harmonization. Watch Health Canada and provincial formulary negotiations as the signal for North American commercial launch timing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Captive AAV9 production capacity at CDMOs in Massachusetts secures supply for pivotal trials. |
| Regulatory Approval Pathway | FDA rare pediatric disease designation accelerates timelines for MECP2 replacement candidates. |
| Reimbursement Strategy | Value-based contracts with Ontario and Quebec public drug programs enable Canadian market access. |
| Hospital System Partnership | Preferred provider agreements with Boston Children's Hospital concentrate trial-ready patient referrals. |
| Pipeline Diversification | Sigma-1 receptor modulation expansion into adjacent neurodevelopmental indications extends platform utility. |
Research Methodology
Operator-level perspectives from gene therapy development executives, regulatory affairs leads at FDA-designated orphan product sponsors, hospital formulary directors in Massachusetts and New York, and provincial payer access specialists in Ontario and Quebec anchored the qualitative base. Secondary validation drew from FDA Office of Orphan Products Development filings, Health Canada regulatory submissions, ClinicalTrials.gov protocol records, and CMS Medicare Part D formulary databases. Bottom-up patient flow modeling and top-down therapeutic category spend analysis were triangulated to constrain estimate variance.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning intervention modality, delivery route, end-user setting, and regional regulatory cluster. CAGRs were derived from patient prevalence projections, newborn screening expansion timelines, and assumed therapy penetration curves. Industry-specific inputs included MECP2 mutation spectrum epidemiology, AAV manufacturing capacity build-out schedules, and cross-border reimbursement policy divergence assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive manufacturing capacity additions by established pharmaceutical players or sudden FDA policy shifts on gene therapy approval standards would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Acid Sphingomyelinase Deficiency Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Batten Disease Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Glanzmann Thrombasthenia Market