
 Edward’s Syndrome Treatment Market | 2026-2036
Edward’s Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Edward’s Syndrome Treatment Market Insights
Modular service bundling is recalibrating how payers and providers purchase Edward's syndrome care, shifting from discrete interventions to integrated care pathways. Abbott Laboratories leverages its diagnostic platform breadth to anchor prenatal screening workflows that identify trisomy 18 cases earlier. F. Hoffmann-La Roche sustains R&D intensity across companion diagnostics that support treatment decisions in neonatal settings. Illumina dominates sequencing infrastructure, giving it upstream control over the genetic confirmation stage that precedes therapeutic intervention.
Edward's syndrome treatment encompasses medical and supportive interventions for trisomy 18, a life-limiting chromosomal abnormality caused by three copies of chromosome 18, with care focused on organ-specific symptom management rather than curative therapy. Gene therapy represents the fastest-expanding segment, though most programs remain preclinical, while supportive care commands the largest current spend due to chronic cardiac, respiratory, and feeding interventions. Pediatric hospitals capture the deepest margin pools among end users, given their concentration of multidisciplinary specialists and intensive care capacity.
The FDA's orphan drug program and EMA's paediatric investigation plans shape clinical trial design and market exclusivity timelines for developers targeting this ultra-rare indication. Reimbursement pathways through CMS and private payers determine access to high-cost interventions, creating divergent market dynamics across funding environments. Stakeholders must monitor regulatory precedent for gene therapy pricing in ultra-rare diseases, as this will establish the commercial framework for any disease-modifying approach that reaches patients.
Market Dynamics
Gene therapy pipelines are compressing development timelines for trisomy 18 interventions, forcing incumbent supportive care providers to reconfigure service delivery models around anticipatory rather than reactive clinical management.
Growth Catalysts
- FDA Orphan Drug Designation:Developers receive tax credits and seven-year market exclusivity, accelerating investment in ultra-rare chromosomal disorder programs. Pediatric academic medical centers in Boston and Philadelphia anchor early-phase trial recruitment.
- Non-invasive prenatal testing (NIPT):Cell-free DNA screening identifies trisomy 18 at 10-12 weeks gestation, expanding the addressable patient window for prenatal counseling and postnatal care planning. Maternal-fetal medicine units integrate these workflows into standard obstetric protocols.
- Pediatric hospital consolidation:Multi-state health systems acquire standalone children's hospitals, concentrating NICU capacity and multidisciplinary specialist teams in regional hubs. Cincinnati Children's and Texas Children's expand satellite networks into secondary markets.
Market Restraints
- Gene therapy manufacturing complexity:AAV vector production requires dedicated GMP facilities with six-month batch timelines, constraining supply elasticity for any approved disease-modifying therapy.
- Reimbursement fragmentation:State Medicaid programs apply divergent medical necessity criteria for cardiac and respiratory interventions, creating access inequities across jurisdictions. CMS has not established a uniform billing code for comprehensive trisomy 18 care bundles.
- Clinical trial enrollment scarcity:Incidence of 1 in 5,000 live births limits feasible study populations, forcing developers to rely on surrogate endpoints and adaptive trial designs that regulators scrutinize heavily.
Strategic Opportunities
- Canada's Rare Disease Drug Framework:Health Canada prioritizes accelerated review pathways for pediatric genetic conditions, offering a regulatory beachhead for developers seeking North American market entry ahead of US FDA submission.
- Telehealth genetic counseling:Virtual prenatal consultation platforms extend specialist access to rural and underserved counties, reducing geographic barriers to early diagnosis and care coordination.
- CRISPR base editing convergence with in utero delivery:Preclinical programs combining targeted chromosomal correction with maternal-fetal surgical administration could redefine the therapeutic window for aneuploidy disorders.
Industry Challenges
- Neonatal palliative care workforce shortage:Fellowship-trained perinatal hospice specialists number fewer than 400 across US academic centers, limiting family-centered care capacity.
- Cross-border data sharing for natural history studies:GDPR compliance complexity impedes European patient registry participation, fragmenting longitudinal outcome datasets that regulators demand for gene therapy approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edward’s Syndrome Treatment Market |
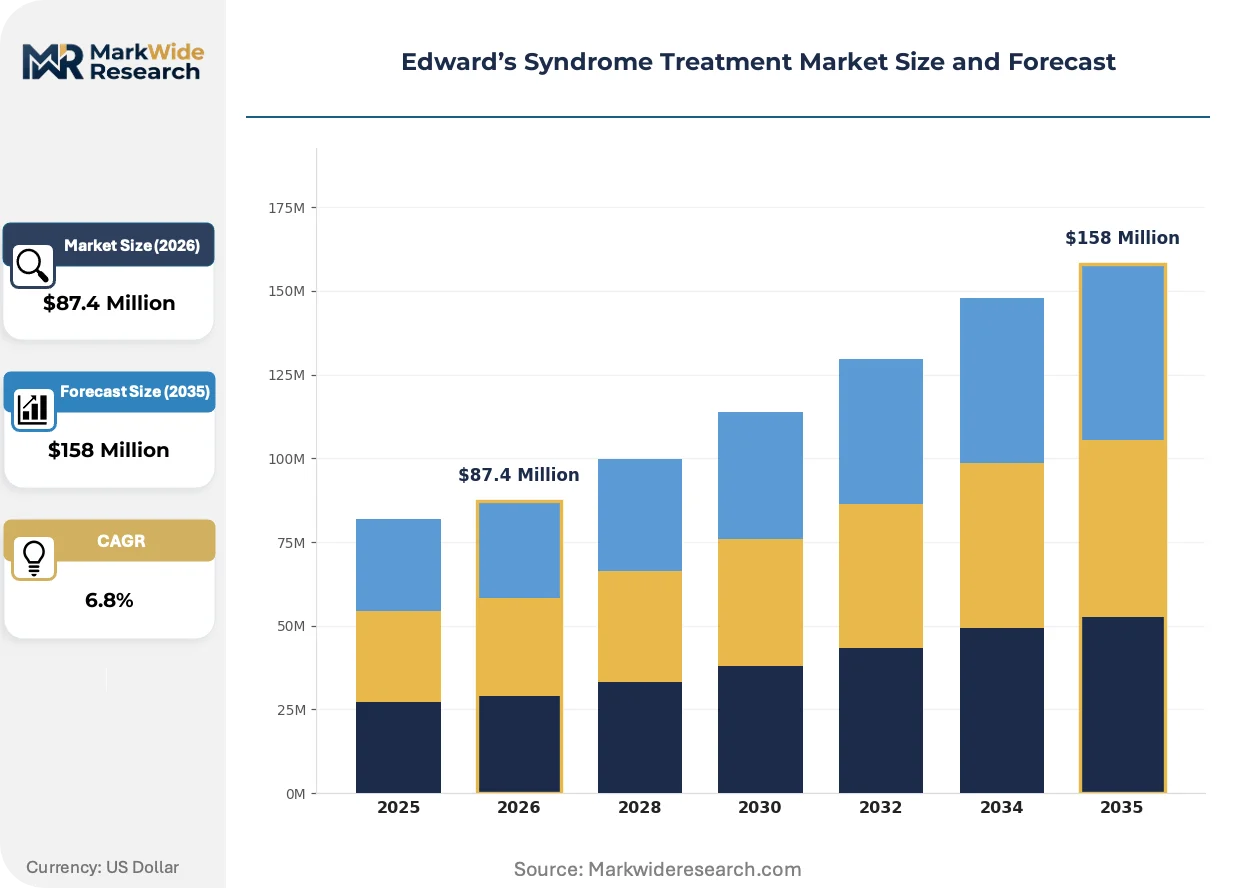
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Gene Therapy, Supportive Care, Surgical Intervention, Nutritional Supplements Therapy Area: Genetic Disorders, Congenital Anomalies, Neonatal Care, Pediatric Neurology, Developmental Support End User: Specialty Clinics, Pediatric Hospitals, Genetic Counseling Centers, Home Care Providers, Rehabilitation Facilities Delivery Mode: Oral Administration, Injectable, Intravenous, Topical, Inhalation |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche, PerkinElmer, Quest Diagnostics, Illumina, Natera, Myriad Genetics, Medtronic, Edwards Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edward’s Syndrome Treatment Market Trends and Innovations
Prenatal diagnostic workflows are converging with therapeutic decision support systems, compressing the interval between chromosomal confirmation and clinical intervention planning while raising computational infrastructure requirements for maternity care networks.
Artificial intelligence-assisted ultrasound interpretation is modularizing first-trimester screening protocols, enabling sonographers with limited specialized training to flag trisomy 18-associated soft markers. Community hospital obstetric departments in Michigan and North Carolina deploy these tools to reduce referral delays. The technology is compressing the specialist bottleneck that previously concentrated diagnostic expertise in academic centers.
The EMA's paediatric investigation plan (PIP) mandate now requires neonatal genetic disorder developers to submit juvenile toxicity data earlier in development, extending preclinical timelines but reducing regulatory risk at marketing authorization. European biotechnology firms restructure toxicology contracts to accommodate rodent and non-human primate infant dosing studies. Gene therapy sponsors targeting trisomy 18 report PIP negotiations consuming 14-18 months of preparatory dialogue.
Family advisory councils are displacing traditional physician-centric care planning in major pediatric hospitals, with parents of children with trisomy 18 serving on ethics committees and quality improvement boards. Cincinnati Children's and Children's Hospital of Philadelphia embed these stakeholders in cardiac intervention consent processes. This participation model is most visible in US centers with established perinatal palliative care programs, where shared decision-making documentation has become a Joint Commission review focus.
Edward’s Syndrome Treatment Market Segmentation
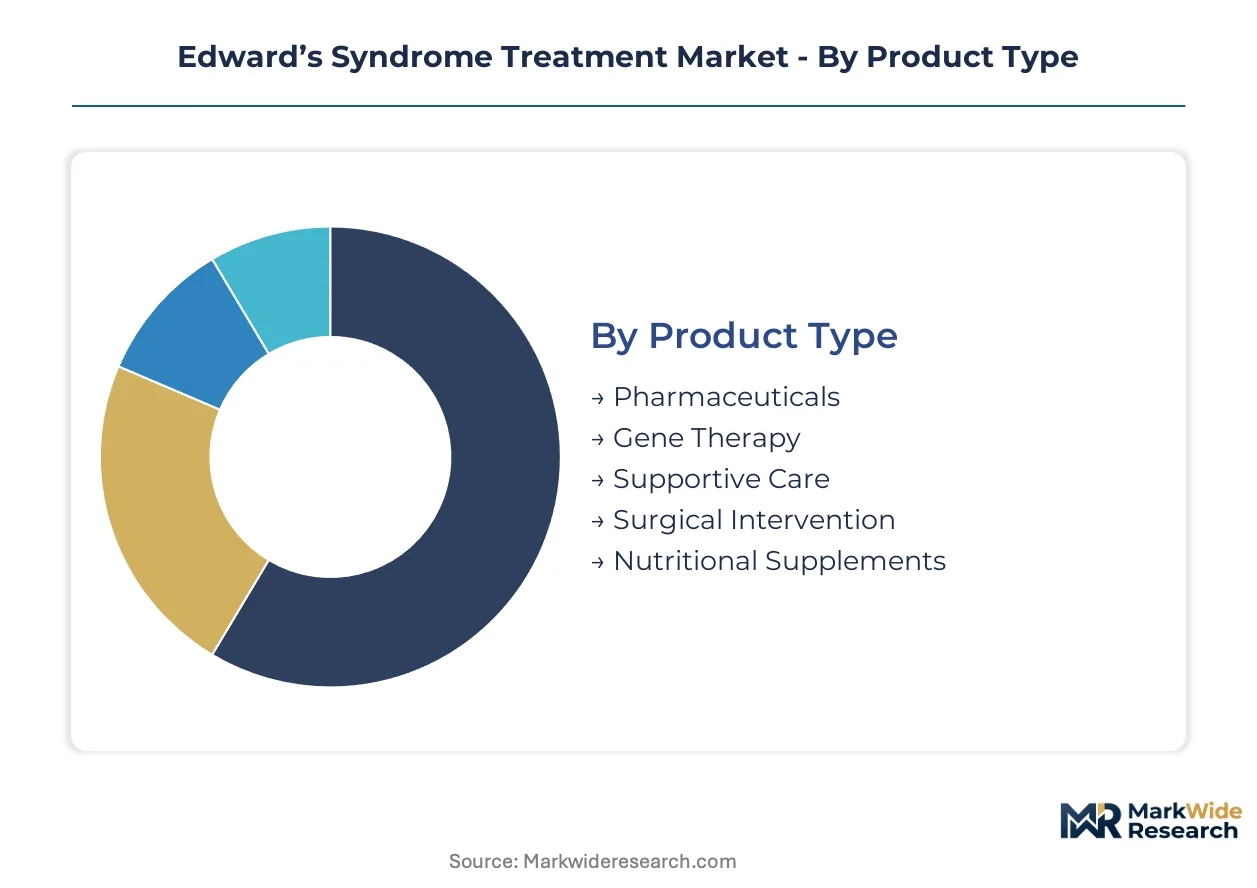
Segmentation in Edward's syndrome treatment reveals how care pathways fragment across intervention modalities and care settings. Each axis exposes distinct margin structures, regulatory exposure, and competitive dynamics that shape stakeholder positioning.
Product Type:
Technology maturity separates segments with established reimbursement from those requiring novel payment models.
- Supportive Care:Chronic cardiac, respiratory, and feeding interventions dominate current clinical spend. Pediatric hospitals in Boston and Philadelphia anchor demand concentration due to their NICU capacity and multidisciplinary specialist density.
- Gene Therapy:Preclinical programs targeting chromosomal correction are compressing development timelines. FDA orphan drug designation and seven-year market exclusivity accelerate investment despite AAV vector manufacturing constraints.
- Pharmaceuticals:Organ-specific symptom management agents follow standard pediatric drug approval pathways.
- Surgical Intervention:Cardiac defect repairs and gastrostomy placements require specialized neonatal surgical teams.
- Nutritional Supplements:Enteral feeding formulations support growth in infants with feeding difficulties.
Supportive care leads on scale; gene therapy leads on momentum.
Therapy Area:
Clinical specialization depth determines where academic medical centers concentrate resources versus community hospital participation.
- Neonatal Care:Immediate postnatal stabilization and intensive monitoring define the critical intervention window. Cincinnati Children's and Texas Children's expand satellite networks to capture regional patient flow.
- Genetic Disorders:Chromosomal abnormality management requires molecular diagnostic integration with clinical protocols. Cell-free DNA screening at 10-12 weeks gestation expands the addressable patient window.
- Congenital Anomalies:Multi-organ structural defects demand coordinated surgical and medical planning.
- Pediatric Neurology:Seizure management and neurodevelopmental monitoring address central nervous system involvement.
- Developmental Support:Early intervention services target motor and cognitive milestone achievement.
Neonatal care commands the deepest specialist concentration; genetic disorders are expanding most quickly via prenatal diagnostic integration.
End User:
Facility reimbursement tier and case complexity capability create stratified access patterns.
- Pediatric Hospitals:Multi-state health system consolidation concentrates NICU capacity and multidisciplinary teams. These centers capture the deepest margin pools through bundled care pathways.
- Genetic Counseling Centers:Virtual prenatal consultation platforms extend specialist access to rural counties. Health Canada's rare disease framework accelerates regulatory beachhead strategies for developers.
- Specialty Clinics:Maternal-fetal medicine units integrate non-invasive prenatal testing into standard obstetric workflows.
- Home Care Providers:Palliative and hospice services support family-centered care outside institutional settings.
- Rehabilitation Facilities:Physical and occupational therapy addresses developmental delays in surviving infants.
Pediatric hospitals dominate revenue concentration; genetic counseling centers are gaining share fastest through telehealth extension.
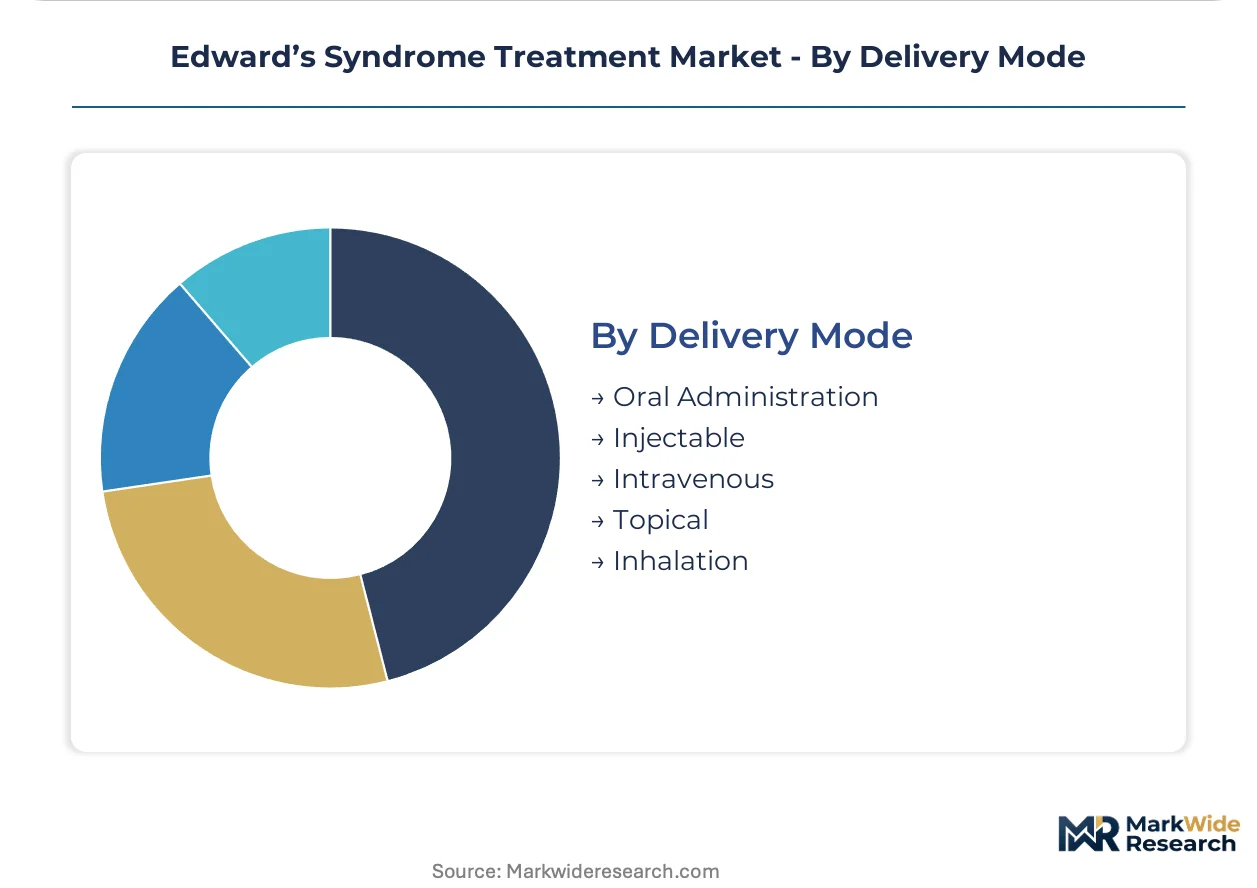
Delivery Mode:
Route of administration aligns with patient physiological status and intervention urgency.
- Injectable:Direct delivery bypasses gastrointestinal compromise common in trisomy 18. EMA paediatric investigation plans mandate juvenile toxicity data earlier in development.
- Intravenous:Critical care settings require vascular access for emergency interventions. State Medicaid programs apply divergent medical necessity criteria creating access inequities.
- Oral Administration:Feeding difficulties in affected infants limit practical utility despite convenience advantages.
- Topical:Skin integrity management addresses dermatological manifestations.
- Inhalation:Respiratory support delivery targets chronic pulmonary complications.
Intravenous delivery anchors acute care; injectable routes are climbing the fastest via gene therapy pipeline advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prenatal diagnostic capabilities for trisomy 18 first scaled through US academic medical centers in the 1990s, with cell-free DNA testing later commercializing in California and Massachusetts before diffusing to European and Asia-Pacific markets.
United States
Pediatric hospital consolidation concentrates NICU capacity in Boston and Philadelphia, where multidisciplinary specialist teams manage complex cardiac and respiratory interventions. FDA orphan drug designation accelerates developer investment through tax credits and seven-year market exclusivity. Cincinnati Children's and Texas Children's expand satellite networks into secondary markets across the Midwest and Southwest.
Germany
Maternal-fetal medicine units in Munich and Heidelberg integrate non-invasive prenatal testing into standard obstetric workflows, expanding early diagnosis windows. EMA paediatric investigation plans mandate juvenile toxicity data submission earlier in development, extending preclinical timelines. The country's pharmaceutical regulator maintains strict scrutiny of adaptive trial designs for ultra-rare chromosomal disorders.
United Kingdom
Genetic counseling centers in London and Manchester deploy telehealth platforms to extend specialist access to rural counties across England and Scotland. The NHS England specialized commissioning framework determines access to high-cost cardiac interventions, creating regional variation in treatment intensity. Academic clusters in Cambridge and Oxford anchor natural history study recruitment for preclinical gene therapy programs.
Japan
Metropolitan medical centers in Tokyo and Osaka concentrate perinatal hospice specialists and family-centered care programs for trisomy 18. PMDA consultation pathways for rare pediatric diseases offer structured pre-submission dialogue that reduces regulatory risk at marketing authorization. The country's national health insurance system applies uniform reimbursement criteria that limit access inequities across prefectures.
Canada
Health Canada's rare disease drug framework prioritizes accelerated review pathways for pediatric genetic conditions, offering developers a regulatory beachhead ahead of US FDA submission. Maternal-fetal medicine units in Toronto and Vancouver integrate cell-free DNA screening at 10-12 weeks gestation. Provincial health authorities apply divergent funding criteria for comprehensive trisomy 18 care bundles, creating access variation across Ontario, Quebec, and British Columbia.
Edward’s Syndrome Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across diagnostic platform breadth and therapeutic development intensity. The market structures around three tiers: diversified diagnostics conglomerates with prenatal screening workflows, specialized genetic testing laboratories with sequencing infrastructure, and emerging gene therapy developers with chromosomal correction platforms. Consolidation concentrates among multi-state health systems acquiring standalone children's hospitals, while strategic partnerships link diagnostic confirmation to care coordination services.
Among diversified diagnostics conglomerates, Abbott Laboratories and F. Hoffmann-La Roche exemplify platform breadth that anchors prenatal screening workflows and companion diagnostic development. Illumina occupies a position upstream of therapeutic intervention through its dominance in sequencing infrastructure that controls genetic confirmation stages. These three companies represent the diagnostic-to-therapeutic continuum that shapes patient access timelines.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| PerkinElmer |
| Quest Diagnostics |
| Illumina |
| Natera |
| Myriad Genetics |
| Medtronic |
| Edwards Lifesciences |
| Others |
Pricing and Supply Chain Analysis
Payer consolidation around bundled care pathways for trisomy 18 management is compressing reimbursement rates for discrete cardiac and respiratory interventions, forcing pediatric hospitals to renegotiate supplier contracts and absorb margin compression through volume commitments rather than price pass-through.
Pricing Analysis
Three-tier pricing structure across academic medical center, community hospital, and home care levels dominates Edward's syndrome treatment reimbursement. Price differentiation rests on NICU capability certification and multidisciplinary specialist density. Cost compression in community hospital tiers is intensifying because state Medicaid programs apply divergent medical necessity criteria. Academic medical centers exhibit lowest price sensitivity due to bundled payment capture and philanthropic offset programs.
Supply Chain Analysis
Single-source vulnerability sits with AAV vector manufacturing facilities concentrated in the United States and Germany. Gene therapy raw material dependencies include plasmid DNA, cell culture media, and GMP-grade viral vectors. Supply chain risk centers on six-month batch timelines that constrain supply elasticity for any approved disease-modifying therapy. Distribution runs through specialized cold-chain logistics networks serving pediatric hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
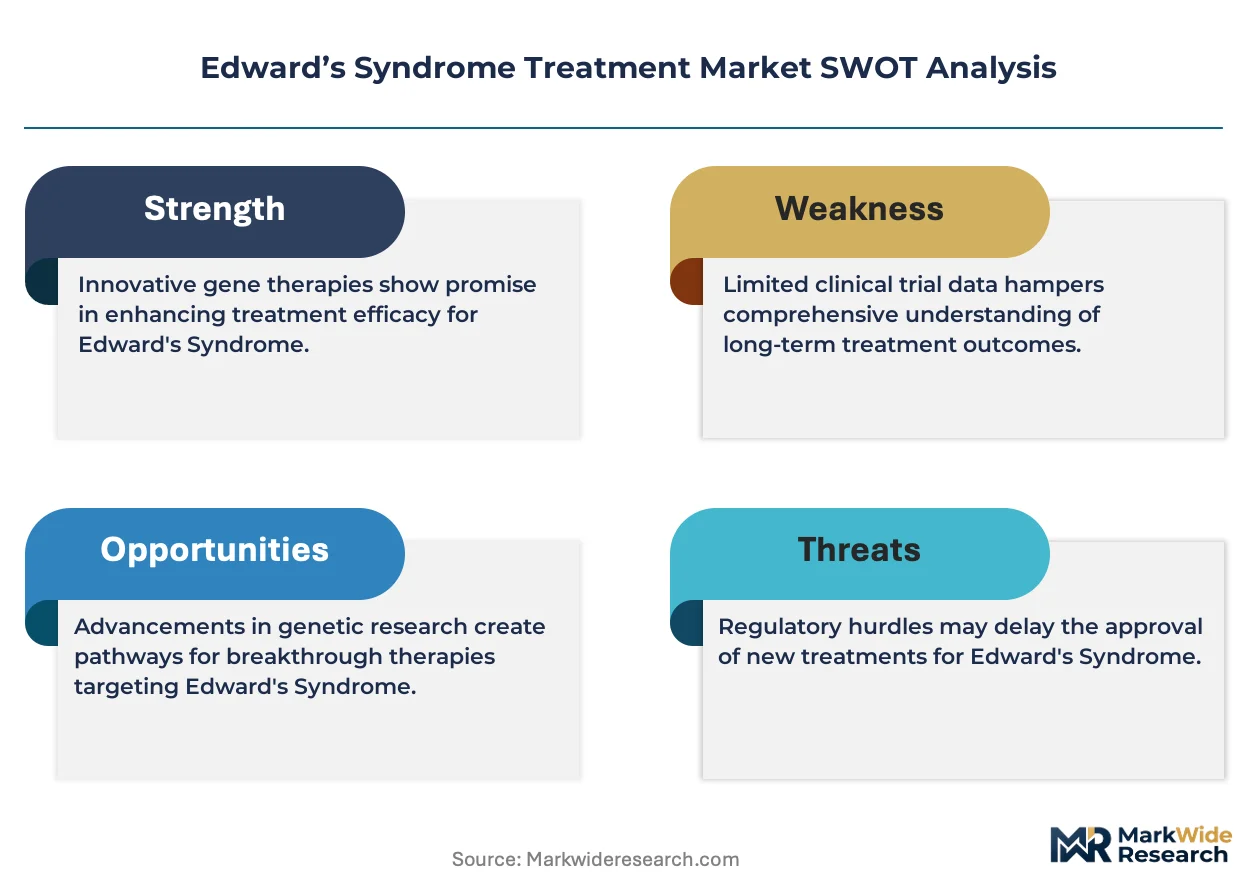
Edward's syndrome treatment functions as a stable compounder market where FDA orphan drug designation and seven-year market exclusivity provisions create durable incentive structures for developer investment.
For Market Incumbents: Hedge against gene therapy pipeline maturation by expanding anticipatory care coordination services that capture families earlier in the diagnostic window. Cincinnati Children's and Texas Children's satellite network expansion models offer templates for geographic coverage without full capital commitment. Backward integration into genetic counseling workflows secures patient flow before therapeutic intervention decisions crystallize. For New Entrants and Emerging Players: Capture share in telehealth genetic counseling platforms serving rural counties underserved by maternal-fetal medicine specialists. Canada's Rare Disease Drug Framework offers the most penetrable regulatory entry point for North American market access ahead of US FDA submission. Partnership models with existing NIPT laboratories reduce customer acquisition costs and accelerate care pathway integration. For Investors and Strategic Acquirers: Asymmetric upside sits with gene therapy developers combining chromosomal correction platforms with in utero delivery capabilities. Five-to-ten year viability hinges on regulatory precedent for ultra-rare disease gene therapy pricing. The signal to watch is PMDA consultation pathway engagement for rare pediatric diseases, as Japanese regulatory validation often accelerates subsequent FDA dialogue.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Adaptive trial designs for ultra-rare indications reduce enrollment burden while satisfying FDA scrutiny standards. |
| Regulatory Approval Pathway | Health Canada accelerated review offers beachhead positioning ahead of US FDA orphan drug submission. |
| Hospital System Partnership | Cincinnati Children's satellite network model demonstrates scalable care coordination without full capital deployment. |
| Manufacturing Scale-Up | AAV vector GMP capacity expansion addresses six-month batch timeline constraints for gene therapy supply. |
| Reimbursement Strategy | CMS bundled billing code advocacy reduces state Medicaid fragmentation for comprehensive trisomy 18 care. |
Research Methodology
Bottom-up pediatric hospital capacity modeling reconciled against top-down gene therapy pipeline tracking forms the analytical core. Primary interviews with neonatologists, maternal-fetal medicine specialists, payer formulary directors, and genetic counseling center administrators combined with secondary validation against FDA orphan drug designations, EMA paediatric investigation plans, ClinicalTrials.gov entries, and CMS reimbursement databases. Triangulation across supply-side manufacturing capacity and demand-side patient flow data ensures segmentation integrity.
Input-output matrices map gene therapy development stages to supportive care intervention volumes across the projection horizon. Segmentation dimensions include treatment modality, care setting tier, delivery route, and regional regulatory cluster. CAGRs derive from patient incidence modeling, intervention penetration curves, and pricing trajectory assumptions. Forecast inputs incorporate NICU capacity expansion plans and prenatal diagnostic adoption rates by geography.
Gene therapy regulatory approval delays, state Medicaid reimbursement fragmentation, and neonatal palliative care workforce shortages are the dominant revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Erdheim-Chester Disease Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Arthrogryposis Management Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Batten Disease Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market