
 Rare Diseases Treatment Market | 2026-2036
Rare Diseases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Diseases Treatment Market Analytics
Risk-sharing agreements and outcome-based reimbursement models are reshaping how rare disease therapies reach patients, lowering upfront barriers for healthcare systems. Pfizer leverages its global manufacturing footprint to supply biologics across multiple therapy areas. Novartis anchors its rare disease portfolio through deep specialization in gene therapies. F. Hoffmann-La Roche Ltd. sustains competitive position via integrated diagnostic-drug platforms that streamline patient identification.
Rare diseases treatment encompasses therapies targeting conditions affecting fewer than 200,000 individuals in the United States, typically requiring biologic manufacturing in controlled environments with cold-chain integrity and stringent purity thresholds. These interventions primarily aim to modify disease progression, replace deficient enzymes, or correct genetic defects in populations with limited therapeutic alternatives. Gene therapies represent the fastest-expanding segment, driven by one-time curative potential and premium reimbursement structures, while enzyme replacement therapies occupy a mature, high-margin position sustained by chronic administration models. Small molecule drugs compete on manufacturing scalability and oral delivery convenience, particularly in hematologic disorders where patient compliance shapes clinical outcomes.
The FDA Orphan Drug Act and EMA orphan designation frameworks reduce development costs through tax credits and market exclusivity, directly influencing where sponsors allocate R&D capital. The EU AI Act and GDPR impose data governance requirements on patient registries and real-world evidence collection, shaping trial design and post-market surveillance obligations. Stakeholders must monitor how cross-border regulatory divergence affects multi-territory launch sequencing and pricing negotiations.
Market Dynamics
Gene therapy manufacturing platforms are compressing development timelines while simultaneously concentrating production capabilities among a handful of specialized CDMOs with viral vector expertise.
Growth Catalysts
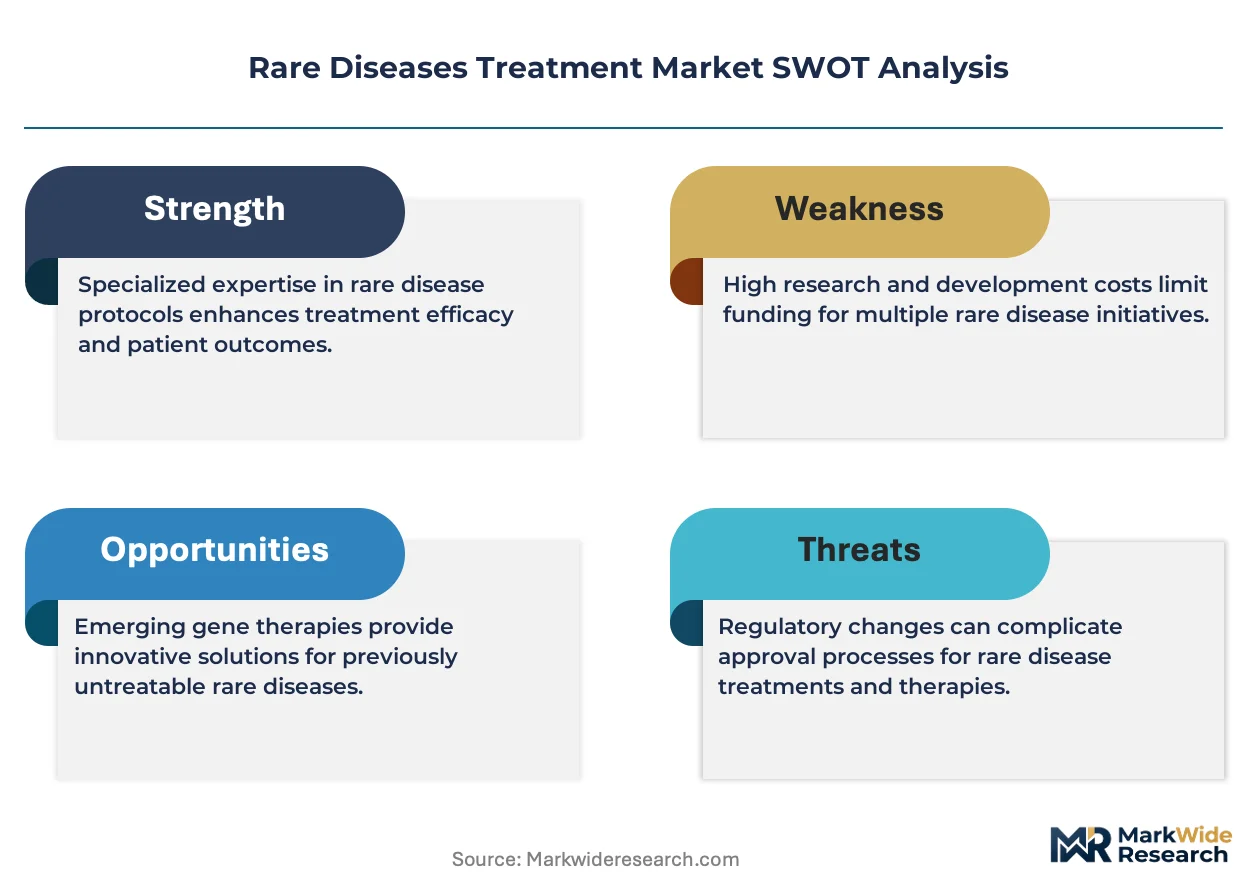
- FDA Orphan Drug Act:Tax credits and seven-year market exclusivity reduce effective development costs for sponsors targeting ultra-rare indications.
- Gene therapy vectors:AAV and lentiviral delivery systems enable one-time curative interventions that command premium reimbursement structures.
- Pediatric hospital networks:Specialized treatment centers in the United States are expanding dedicated rare disease programs to capture referral volume.
Market Restraints
- Plasmid DNA supply:Viral vector manufacturing depends on limited GMP-grade plasmid sources concentrated in North America and Europe.
- EMA GDPR compliance:Patient registry data collection for natural history studies faces consent and cross-border transfer restrictions.
- Chronic enzyme replacement:Intravenous biweekly administration schedules create lifetime cost burdens that payers increasingly scrutinize.
Strategic Opportunities
- India CDMO expansion:Domestic biologics manufacturing capabilities are scaling to serve Asia-Pacific demand at reduced cost structures.
- Real-world evidence pathways:FDA accelerated approval frameworks accept post-market efficacy data, shortening time-to-revenue for novel modalities.
- Direct-to-patient distribution:Cold-chain logistics providers are building last-mile capabilities that bypass traditional hospital pharmacy intermediaries.
Industry Challenges
- Gene therapy workforce gap:Viral vector process development and analytical characterization expertise remains scarce across manufacturing sites.
- Multi-territory launch sequencing:Divergent EMA and FDA evidentiary requirements force sponsors to maintain parallel regulatory dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Diseases Treatment Market |
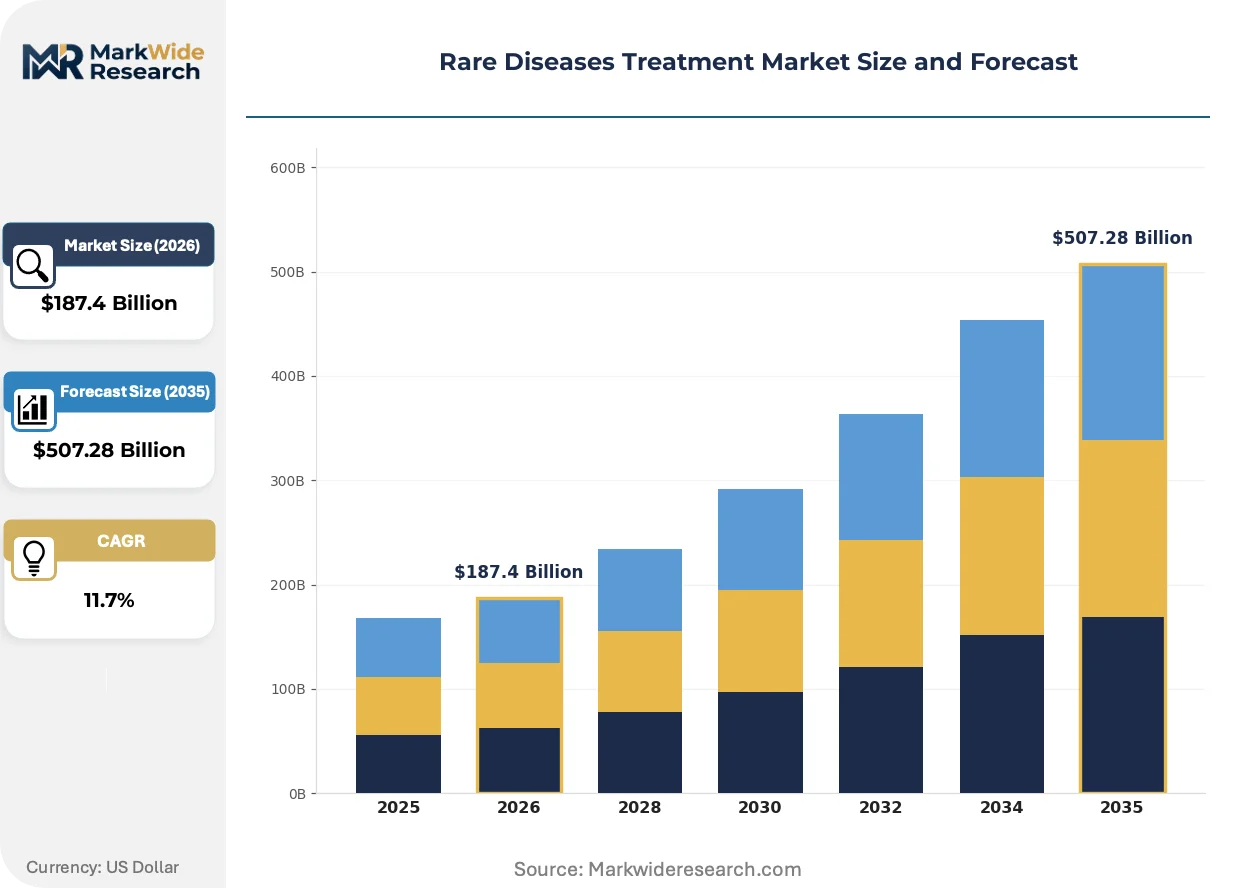
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Gene Therapies, Enzyme Replacement Therapies, Small Molecule Drugs Therapy Area: Neuromuscular Disorders, Hematologic Disorders, Rare Cancers, Lysosomal Storage Disorders End User: Hospitals, Specialty Clinics, Research Institutions, Home Healthcare Delivery Mode: Injectable, Oral, Infusion, Topical |
| Companies Covered | Pfizer, AstraZeneca, Novartis, Bristol-Myers Squibb, Bayer AG, F. Hoffmann-La Roche Ltd., Sanofi, Amgen, BioMarin Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Diseases Treatment Market Evolving Landscape
Platform manufacturing approaches are collapsing the traditional trade-off between product customization and production scale, enabling economic viability for smaller patient populations.
CRISPR-based editing systems are rendering obsolete the need for ex vivo cell manipulation in certain hematologic indications. Large academic medical centers in the United States are adopting these platforms for in-house protocol development. The shift is compressing the addressable market for centralized manufacturing facilities while expanding site-of-care capabilities.
EMA's revised ATMP classification guidance is clarifying borderline cases between gene therapy and somatic cell therapy, reducing regulatory uncertainty for sponsors with hybrid modalities. Manufacturers are restructuring CMC dossiers to align with the new decision trees. The guidance most affects European sponsors developing CAR-T variants with integrated editing components.
Patient advocacy organizations are consolidating purchasing power through centralized registries that negotiate access agreements directly with manufacturers. These entities are displacing traditional payer intermediaries in price-setting conversations for ultra-rare conditions. The phenomenon is most developed in the United States, where 501(c)(3) structures enable collective bargaining.
Rare Diseases Treatment Market Segmentation
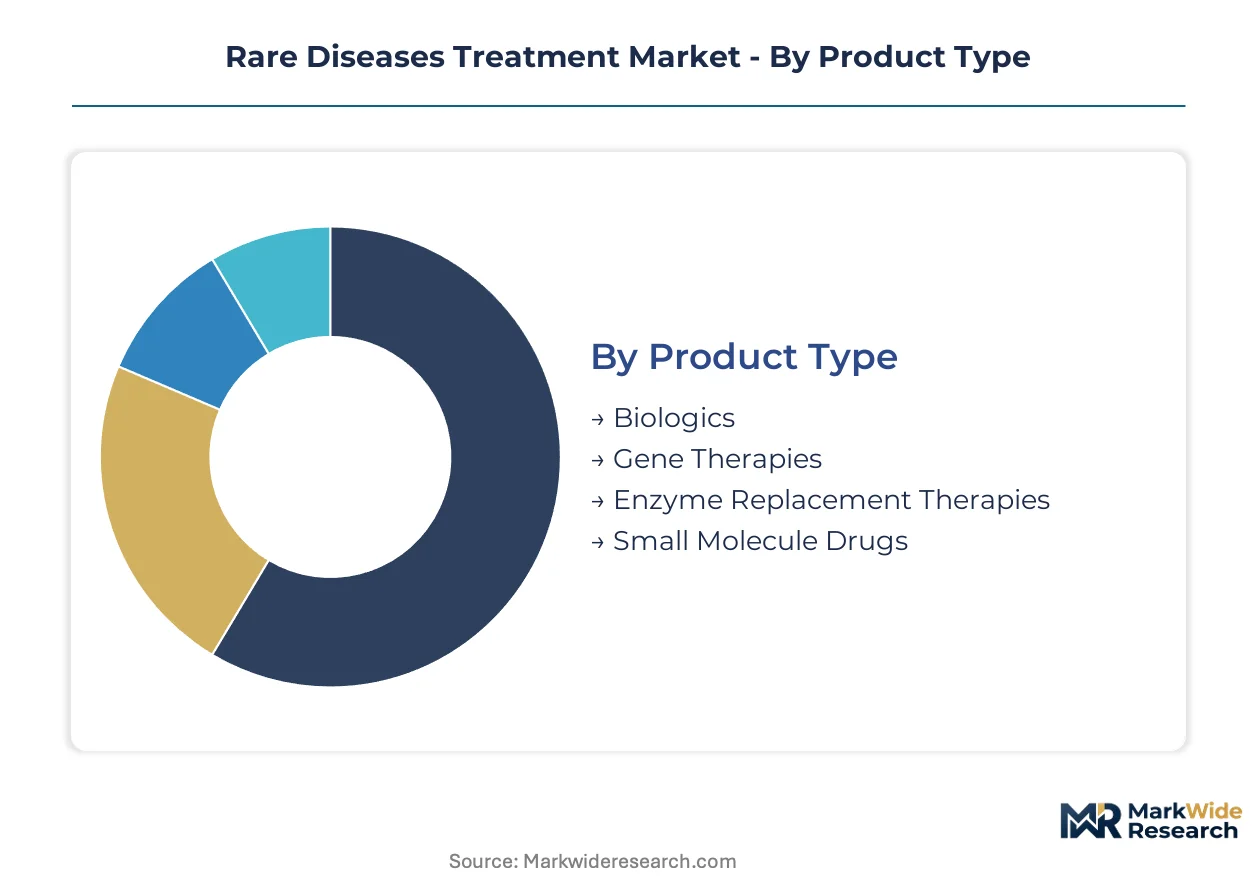
Rare disease therapies demand precise segmentation because patient populations below 200,000 individuals require tailored manufacturing scales, distribution models, and reimbursement negotiations. Each category reflects distinct technical constraints and stakeholder economics that shape commercial viability.
Product Type:
Clinical use spans chronic maintenance regimens to one-time curative interventions, with manufacturing complexity and pricing power varying dramatically across modalities.
- Biologics:Recombinant proteins manufactured in mammalian cell cultures require cold-chain distribution and GMP facilities with biosafety level containment. Pediatric hospitals in the United States absorb the majority of volume for neuromuscular indications where IV infusion protocols dominate.
- Gene Therapies:AAV and lentiviral vector platforms deliver functional genetic material directly to target tissues, enabling single-administration cures that command premium reimbursement. FDA accelerated approval pathways favor these modalities in ultra-rare conditions with no existing alternatives.
- Enzyme Replacement Therapies:Chronic intravenous administration schedules create predictable recurring revenue streams for manufacturers.
- Small Molecule Drugs:Oral bioavailability and scalable chemical synthesis support broader geographic access.
Established volume favors enzyme replacement therapies; emerging adoption favors gene therapies.
Therapy Area:
Prevalence thresholds and diagnostic infrastructure availability determine addressable patient pools across disease categories.
- Neuromuscular Disorders:Spinal muscular atrophy and Duchenne muscular dystrophy represent concentrated demand centers where gene therapy approvals have reset treatment paradigms. Specialty clinics in Boston and San Francisco coordinate multidisciplinary care for these complex progressive conditions.
- Hematologic Disorders:Sickle cell disease and hemophilia offer larger patient populations with established diagnostic pathways and payer familiarity. CRISPR-based editing is displacing ex vivo approaches in academic medical centers with in-house protocol capabilities.
- Rare Cancers:Tumor-agnostic biomarker definitions expand eligible populations beyond histologic boundaries.
- Lysosomal Storage Disorders:Gaucher, Fabry, and Pompe diseases maintain stable demand through chronic ERT administration.
Diagnostic infrastructure maturity favors hematologic disorders; therapeutic innovation velocity favors neuromuscular applications.
End User:
Site-of-care capabilities determine which modalities reach patients, with infusion complexity and monitoring requirements filtering distribution options.
- Hospitals:Tertiary centers with pharmacy compounding units and intensive care backup manage gene therapy administration and acute adverse event protocols. Pediatric hospitals expanding dedicated rare disease programs capture referral volume from surrounding states.
- Specialty Clinics:Focused neuromuscular and metabolic centers concentrate expertise and patient registries that accelerate trial recruitment. These sites negotiate directly with manufacturers for preferred access agreements.
- Research Institutions:Academic medical centers with IND-enabling capabilities pioneer first-in-human protocols.
- Home Healthcare:Subcutaneous ERT formulations and oral small molecules shift administration from clinical to residential settings.
Revenue concentration favors hospitals; patient convenience trends favor home healthcare.
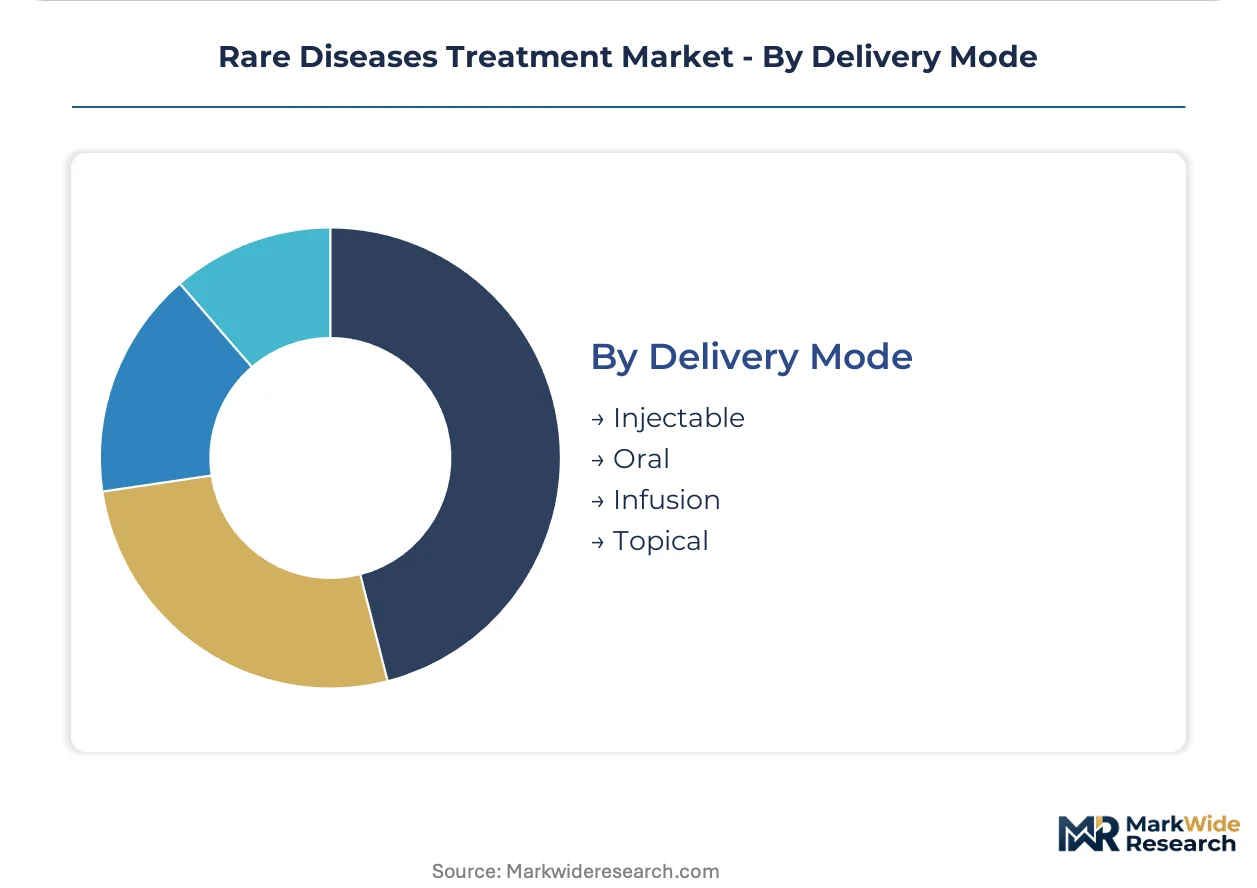
Delivery Mode:
Route of administration shapes compliance economics, with frequency and invasiveness directly influencing lifetime therapy adherence.
- Injectable:Subcutaneous and intramuscular routes enable self-administration training for patients and caregivers, reducing clinic dependency. Cold-chain requirements for biologics limit geographic reach to regions with established logistics networks.
- Oral:Small molecule bioavailability and hepatic metabolism profiles determine dosing schedules and drug-drug interaction profiles. Patient compliance advantages in chronic conditions support preference in hematologic maintenance regimens.
- Infusion:IV delivery remains mandatory for large-molecule biologics and cellular therapies requiring controlled administration rates.
- Topical:Limited applicability in rare diseases due to skin barrier penetration challenges for macromolecular actives.
Chronic administration economics favor oral delivery; curative intervention suitability favors infusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Orphan Drug Act tax credits and seven-year exclusivity provisions draw the majority of rare disease clinical investment toward the United States. Payer structures and specialized pediatric treatment centers concentrate demand in specific metropolitan clusters.
United States
Pediatric hospitals in Boston and San Francisco anchor neuromuscular gene therapy referral networks that capture patients from surrounding states. FDA accelerated approval pathways enable post-market efficacy confirmation, shortening time-to-revenue for novel modalities. The Research Triangle Park corridor in North Carolina hosts viral vector manufacturing facilities supplying AAV platforms.
Germany
Specialized metabolic centers in Munich and Heidelberg concentrate expertise for lysosomal storage disorder management. EMA orphan designation frameworks provide parallel market exclusivity incentives, though GDPR compliance adds friction to patient registry operations. The Heidelberg University Hospital coordinates multicenter natural history studies across Baden-Württemberg.
Switzerland
Gene therapy developers cluster around Basel's pharmaceutical corridor, leveraging proximity to Novartis and Roche diagnostic platforms. Swissmedic maintains alignment with EMA procedures while offering streamlined review timelines for ATMP classifications. The Basel Area Business & Innovation Agency coordinates CDMO partnerships for viral vector production.
United Kingdom
The NHS England Highly Specialised Services program centralizes funding for ultra-rare conditions through designated treatment centers in London and Manchester. MHRA post-Brexit regulatory autonomy enables divergence from EMA timelines on accelerated approvals. The Cell and Gene Therapy Catapult in Stevenage provides manufacturing scale-up support for domestic sponsors.
Japan
PMDA sakigake designation system grants priority review to rare disease therapies addressing unmet needs in pediatric populations. The Kobe Biomedical Innovation Cluster hosts contract development organizations specializing in Asian patient recruitment for global trials. Osaka University Hospital anchors a gene therapy treatment network serving the Kansai region.
Rare Diseases Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around integrated diagnostic-drug platforms and specialized viral vector manufacturing capabilities. Large-cap pharmaceutical companies dominate through gene therapy acquisitions and pediatric hospital network partnerships. Mid-tier biologics specialists occupy enzyme replacement therapy niches with chronic administration models. Competitive moves center on CDMO capacity reservations and real-world evidence collection infrastructure.
Within the large-cap integrated tier, Pfizer leverages global manufacturing footprints across multiple therapy areas while Novartis anchors rare disease positioning through gene therapy specialization. F. Hoffmann-La Roche Ltd. exemplifies the diagnostic-drug convergence archetype. BioMarin Pharmaceutical occupies a distinct position among biologics-focused developers with enzyme replacement expertise.
| Leading Market Players |
|---|
| Pfizer |
| AstraZeneca |
| Novartis |
| Bristol-Myers Squibb |
| Bayer AG |
| F. Hoffmann-La Roche Ltd. |
| Sanofi |
| Amgen |
| BioMarin Pharmaceutical |
| Others |
Value Network & Pricing Analysis
The Memphis-Dallas cold-chain corridor carries GMP-grade biologics from viral vector manufacturing sites to pediatric treatment centers, with freight costs compressing margins on enzyme replacement therapies while enabling premium pricing for gene therapies that bypass traditional hospital pharmacy intermediaries. This logistics backbone concentrates supply-side power among CDMOs with validated cryogenic capabilities, forcing price differentiation across certification tiers.
Pricing Analysis
Certification level creates the primary spread between FDA-grade viral vector production and standard GMP biologics manufacturing. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain validation depth, vector characterization rigor, and batch release timeline guarantees. Cost compression in standard-grade enzyme replacement therapies is intensifying because payer pharmacy benefit managers are consolidating formulary control. Pediatric hospitals demonstrate lowest price sensitivity due to captive patient referral networks, while regional health systems face highest budget scrutiny for chronic administration regimens.
Supply Chain Analysis
CDMO concentration at Lonza, Catalent, and Thermo Fisher's viral vector facilities anchors North American and European production capacity. Manufacturing draws from plasmid DNA sourced primarily in the United States, Germany, and Switzerland, with GMP-grade media and specialized bioreactor components resting on Japanese and South Korean suppliers. Single-source vulnerability in AAV capsid production creates systemic risk for gene therapy sponsors with accelerated approval timelines. Distribution runs through direct-to-patient cold-chain logistics that bypass wholesale distributors for ultra-rare indications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for gene therapies are compressing traditional development timelines, creating asymmetric returns for sponsors that master viral vector manufacturing and real-world evidence collection infrastructure.
For Market Incumbents: Build regulatory exclusivity moats through pediatric rare disease designations that extend market protection beyond standard patent terms. Secure captive plasmid DNA supply through backward integration into GMP-grade raw material production, countering emerging CDMO competition from India. Anchor hospital pharmacy partnerships with outcome-based contracts that lock in preferred formulary positioning for chronic enzyme replacement therapies. For New Entrants and Emerging Players: Build out site-of-care gene therapy administration capabilities in academic medical centers with existing IND-enabling infrastructure, targeting hematologic disorders where CRISPR protocols reduce manufacturing complexity. Penetrate the Asia-Pacific reimbursement landscape through partnerships with domestic regulators in Japan and South Korea, leveraging PMDA sakigake and MFDS priority review pathways. Lead with direct-to-patient distribution models that displace traditional specialty pharmacy intermediaries. For Investors and Strategic Acquirers: Viral vector CDMOs with validated AAV platform capacity represent the most defensible acquisition archetype in a supply-constrained environment. Long-term viability hinges on manufacturing scale-up execution rather than clinical pipeline depth alone. Watch FDA breakthrough therapy designation velocity as the signal for which modalities will capture premium reimbursement windows.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses time-to-revenue for gene therapy sponsors with surrogate endpoints. |
| Manufacturing Scale-Up | Viral vector CDMO capacity reservations at Lonza and Catalent determine launch sequencing for AAV platforms. |
| Reimbursement Strategy | Outcome-based contracts with CMS and commercial payers secure access for one-time curative interventions. |
| Hospital System Partnership | Pediatric hospital network affiliations in Boston and San Francisco concentrate neuromuscular referral volume. |
| Pipeline Diversification | CRISPR editing platforms expand addressable indications beyond traditional ex vivo cell therapy constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with gene therapy development executives, regulatory affairs leads at sponsors and CDMOs, hospital pharmacy directors managing rare disease formularies, and payer access specialists negotiating outcome-based contracts. Secondary validation drew from FDA orphan drug designations, EMA ATMP classification guidance, ClinicalTrials.gov enrollment data, and hospital procurement databases. Bottom-up patient population estimates and top-down manufacturer revenue triangulation anchored segmentation modeling.
Calibration against historical approval timelines and reimbursement decisions informed projection assumptions across the analysis window. Segmentation dimensions included product type, therapy area, end-user site-of-care capabilities, and regional regulatory cluster. CAGRs were derived from epidemiological prevalence trends, pricing power assessments by modality, and manufacturing capacity expansion schedules. Forecast inputs incorporated FDA breakthrough therapy designation velocity and EMA orphan market exclusivity expiration patterns.
Stress conditions across plasmid DNA supply disruptions, payer formulary restriction scenarios, and gene therapy adverse event regulatory responses were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about approval pathway success rates and reimbursement negotiation timelines. Quarterly review of FDA gene therapy guidance updates and CMS national coverage determination precedents is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Dravet Syndrome Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market