
 Global Ureteroscopes Market | 2026-2036
Global Ureteroscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ureteroscopes Market Foresight
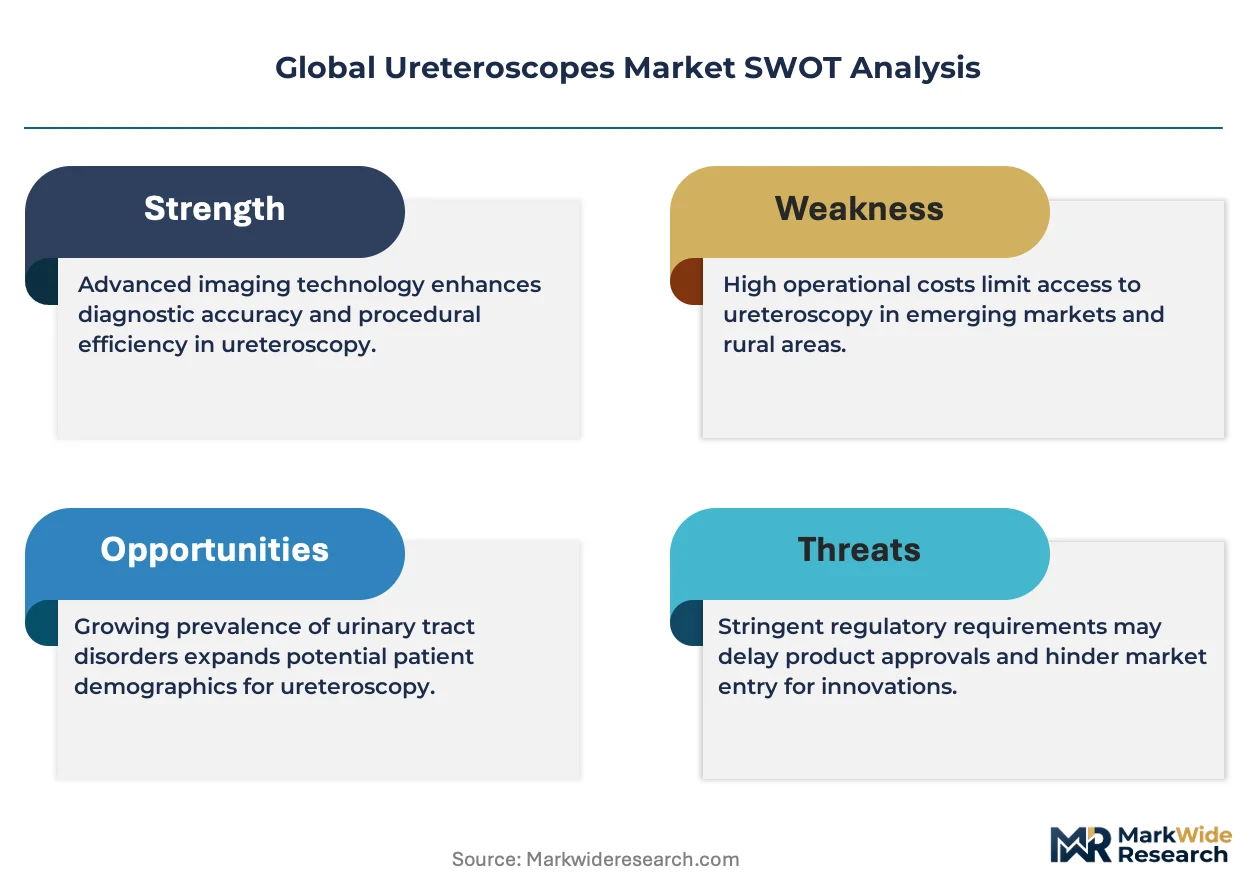
Polymer-based disposable sheaths are pivoting away from traditional stainless steel reusable architectures, cutting reprocessing costs and cross-contamination risks. Boston Scientific Corporation leverages its integrated urology portfolio to dominate North American hospital contracts. Karl Storz sustains European leadership through precision-engineered rigid and flexible platforms. Olympus Corporation competes in Asia-Pacific with advanced optical systems and narrow-band imaging capabilities.
A ureteroscope is a slender endoscopic instrument, typically 2.8–3.6 mm in outer diameter, designed for retrograde visualization and intervention within the urinary collecting system. It incorporates fiber optic or digital image sensors, working channels for irrigation and instrument passage, and active deflection mechanisms up to 270 degrees for renal calyceal access. Digital ureteroscopes now command the premium tier as hospitals prioritize high-definition CMOS sensors and improved durability over fiber optic alternatives. Single-use devices represent the fastest-growing technology segment, capturing ambulatory surgical center demand where reprocessing infrastructure remains limited. Reusable platforms still anchor revenue in high-volume tertiary centers where procedure economics favor capital amortization.
FDA 510(k) clearance requirements and the EU MDR conformity assessment process shape product development timelines and commercialization costs for manufacturers seeking transatlantic distribution. Japan's PMDA and China's NMPA impose additional localization testing that extends regulatory pathways for Western entrants. Stakeholders must monitor reimbursement parity between single-use and reusable platforms across German, French, and Japanese national health systems, as payment policy will determine adoption velocity regardless of technical superiority.
Market Dynamics
Single-use digital ureteroscopes are compressing the installed base of reusable fiber optic systems across ambulatory surgical centers and community hospitals, restructuring capital allocation and service revenue models for manufacturers and distributors alike.
Growth Catalysts
- FDA 510(k) clearance streamlining:Accelerated premarket notification pathways for predicate-equivalent digital platforms reduce time-to-revenue for manufacturers targeting US hospital procurement cycles.
- Cross-contamination risk protocols:Joint Commission and CDC guidelines on endoscope-associated infections drive conversion from reprocessed flexible ureteroscopes to single-use alternatives in outpatient settings.
- CMOS sensor miniaturization:Advances in complementary metal-oxide semiconductor imaging deliver high-definition visualization at reduced distal tip diameter, expanding renal calyceal access capabilities.
Market Restraints
- EU MDR conformity assessment costs:Enhanced clinical evidence requirements and notified body capacity constraints extend certification timelines and inflate regulatory expenditure for transatlantic market entry.
- Supply concentration in German precision optics:Dependency on Baden-Württemberg and Bavaria-based component suppliers for lens arrays and deflection mechanisms creates geographic single-point vulnerability.
- Stainless steel reprocessing infrastructure:Sunk capital in automated washer-disinfectors and sterilization departments at tertiary centers delays full single-use conversion despite operational cost advantages.
Strategic Opportunities
- Japanese super-aging society:PMDA reimbursement parity negotiations for single-use platforms in geriatric stone disease management open premium pricing acceptance in the world's fastest-aging population.
- AI-assisted stone recognition:Integration of real-time computer vision algorithms with digital ureteroscope feeds enables automated calyceal mapping and fragment clearance verification.
- Direct-to-ambulatory distribution:Bypassing traditional distributor markups through manufacturer-managed inventory systems captures margin in high-volume outpatient lithotripsy chains.
Industry Challenges
- Deflection mechanism durability:Active steering cables in flexible platforms experience material fatigue at 270-degree articulation angles, requiring field service intervention and warranty reserve accruals.
- ISO 13485 quality management recertification:Transition to single-use manufacturing lines necessitates cleanroom validation and process requalification that disrupts production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ureteroscopes Market |
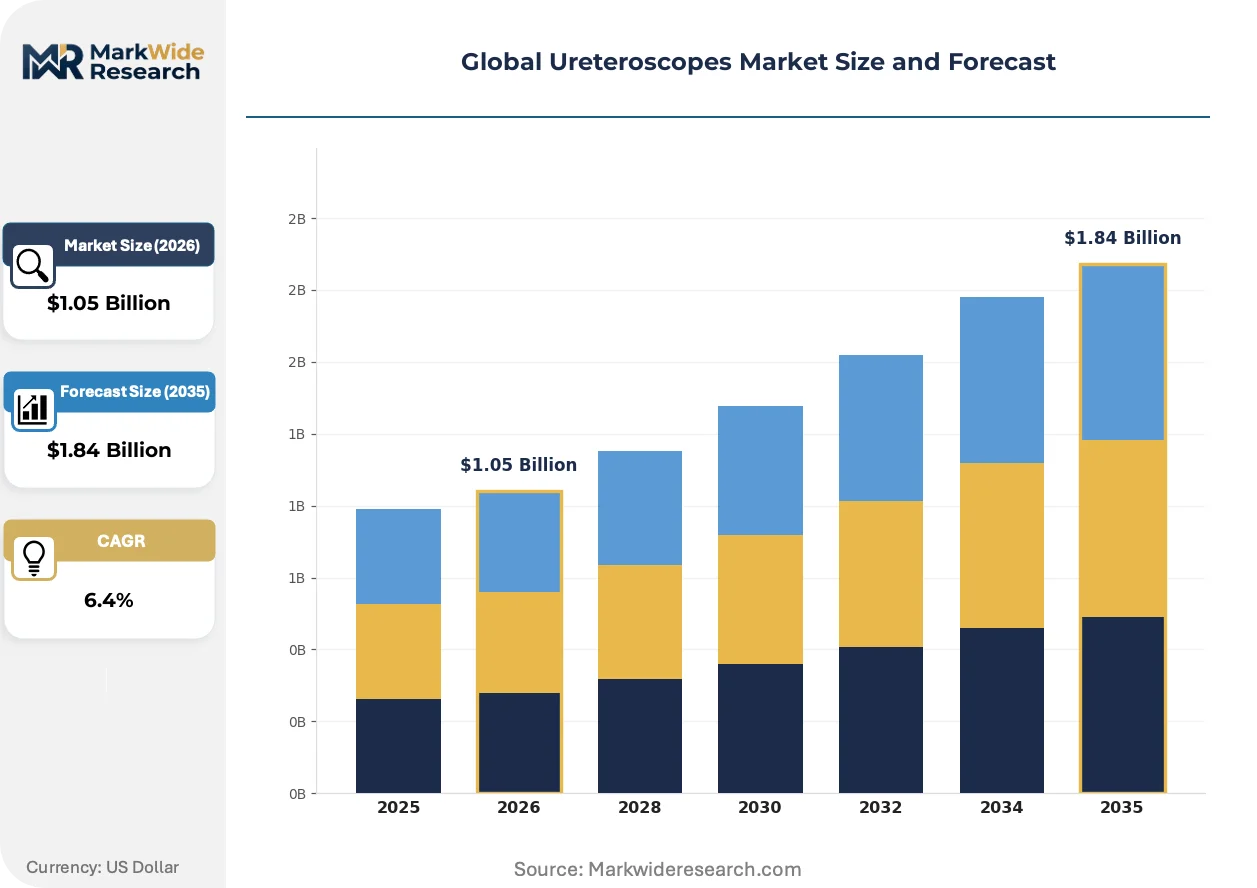
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
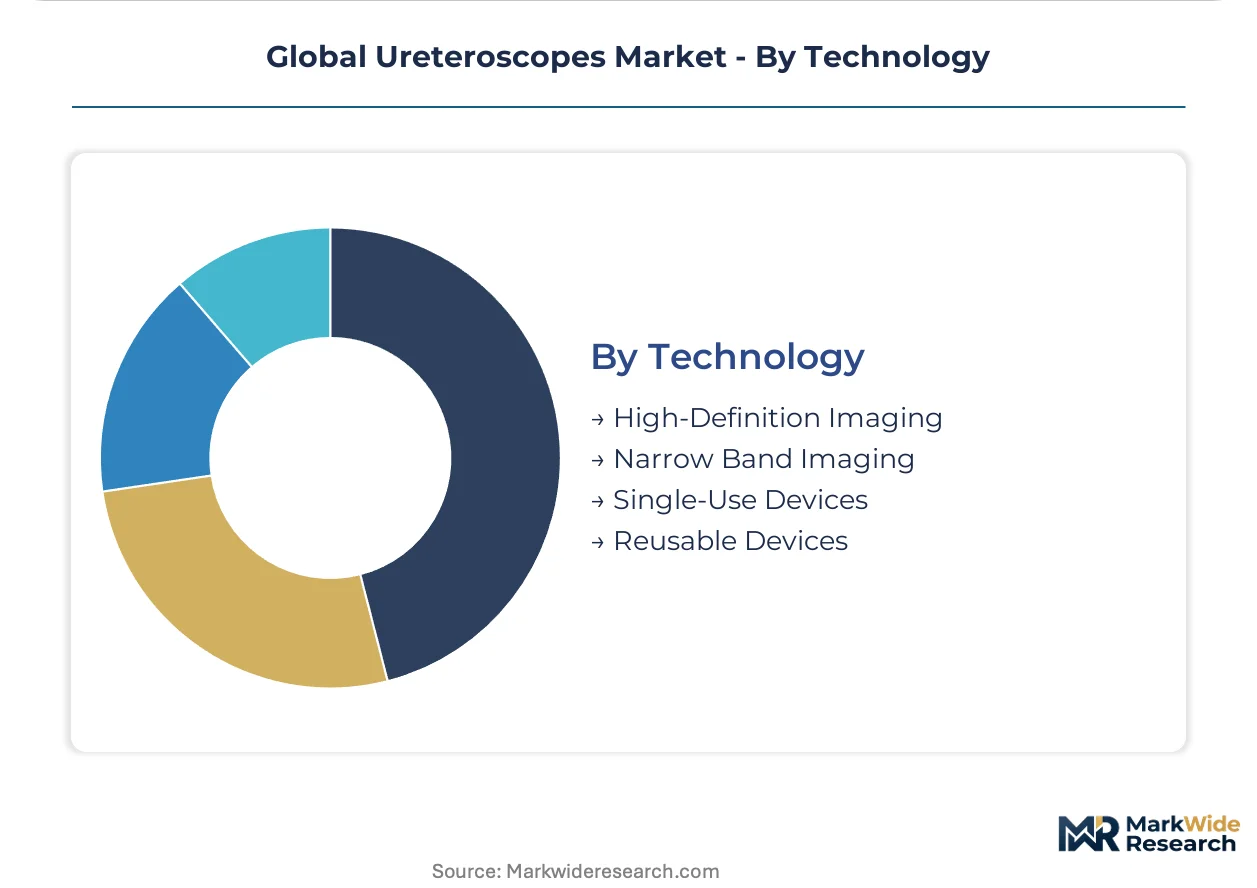
| Segmentation | Product Type: Fiber Optic Ureteroscopes, Digital Ureteroscopes, Flexible Ureteroscopes, Semi-Rigid Ureteroscopes Application: Urolithiasis Treatment, Tumor Diagnosis, Stricture Management, Biopsy Procedures End User: Specialized Clinics, Surgical Centers, Diagnostic Laboratories, Ambulatory Care Facilities Technology: High-Definition Imaging, Narrow Band Imaging, Single-Use Devices, Reusable Devices |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Stryker Corporation, Karl Storz, Richard Wolf, PENTAX Medical, Dornier MedTech, Elmed Medical Systems, Ambu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ureteroscopes Market Shifts & Advancements
Digital image sensor technology is compressing the performance gap between premium and standard-tier ureteroscopes, while regulatory harmonization efforts and procurement centralization reshape competitive access and pricing power across hospital systems.
Robotic-assisted ureteroscopy platforms are automating instrument positioning and laser fiber manipulation during percutaneous nephrolithotomy procedures. Academic medical centers in Germany and the United States are piloting these systems for complex staghorn calculus cases. The technology is automating portions of the surgical workflow previously requiring dual-operator coordination, reducing fluoroscopy exposure and operative duration.
REACH restrictions on per- and polyfluoroalkyl substances are compelling manufacturers to reformulate lubricious hydrophilic coatings on ureteroscope insertion shafts. European notified bodies now require substance-level documentation for coating chemistries previously grandfathered under legacy medical device directives. German and French manufacturers are accelerating biocompatible polymer alternatives to maintain CE marking continuity.
Hospital procurement consortia are consolidating vendor selection authority previously held by individual urology department chairs. Integrated delivery networks in the United States now mandate single-source contracts covering capital equipment, disposables, and service across multiple facilities. This concentration is visible most acutely in Texas and Florida health systems where ambulatory surgery center rollups have created regional purchasing monopolies.
Global Ureteroscopes Market Segmentation
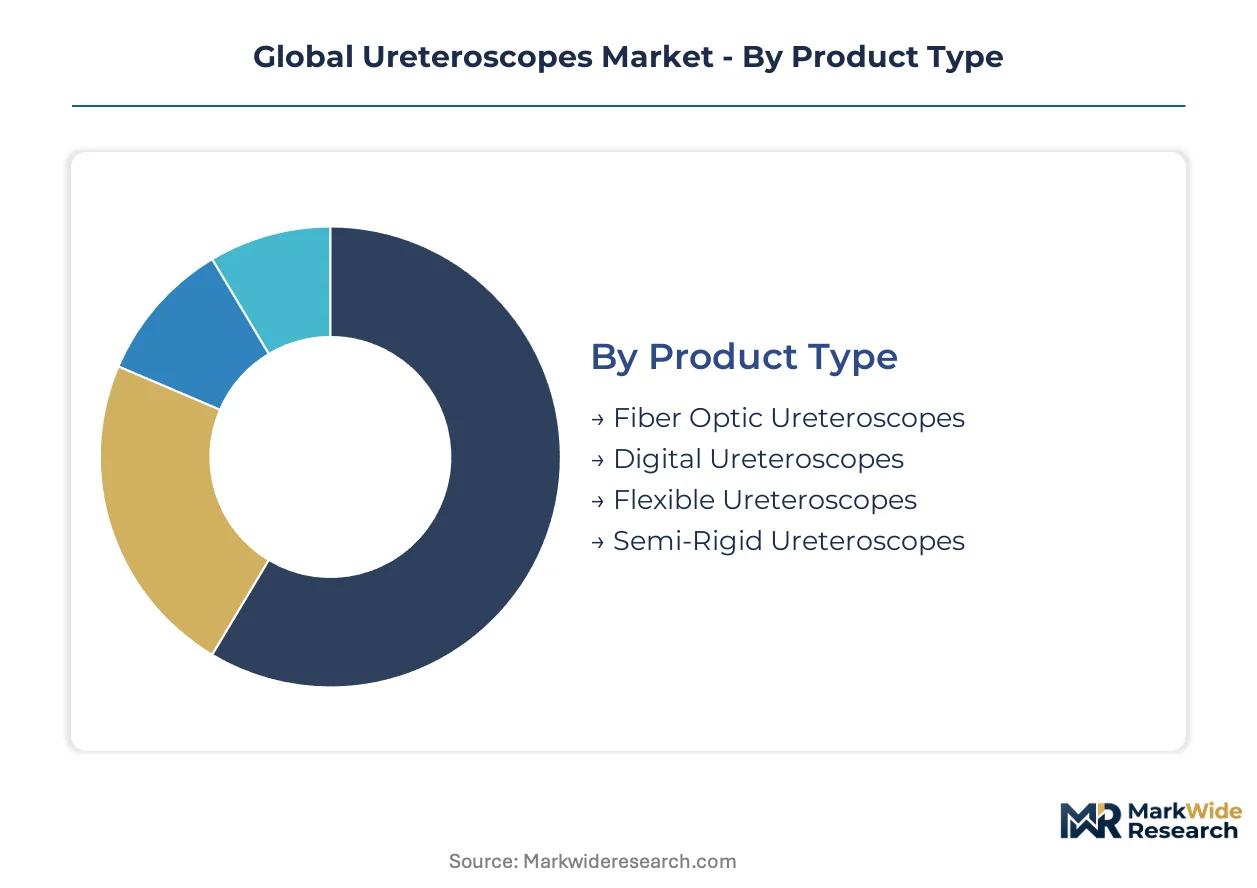
Ureteroscope procurement decisions hinge on the tension between capital efficiency and clinical performance across four intersecting dimensions. Hospital administrators weigh reprocessing infrastructure against single-use economics, while urologists prioritize image fidelity and deflection range for renal access.
Product Type:
Technology maturity and procedural volume determine capital allocation across ureteroscope platforms.
- Digital Ureteroscopes:CMOS sensor arrays deliver high-definition visualization with improved durability over fiber optic alternatives. Demand concentrates in German and United States academic medical centers upgrading to high-definition imaging platforms where reimbursement supports premium capital expenditure.
- Flexible Ureteroscopes:Active deflection mechanisms up to 270 degrees enable complete renal calyceal access. Japanese super-aging demographics and elevated stone disease prevalence in geriatric populations are accelerating flexible platform deployment across Tokyo and Osaka metropolitan hospital networks.
- Fiber Optic Ureteroscopes:Legacy fiber bundles continue serving cost-constrained community hospitals in India and Brazil where capital replacement cycles extend beyond seven years.
- Semi-Rigid Ureteroscopes:Stainless steel shaft construction with limited distal deflection suits distal ureteral and intramural tunnel procedures in Chinese county-level hospitals.
Digital ureteroscopes lead on scale; flexible ureteroscopes lead on momentum.
Application:
Procedure reimbursement rates and disease epidemiology shape segment prioritization across healthcare systems.
- Urolithiasis Treatment:Percutaneous nephrolithotomy and retrograde intrarenal surgery for kidney stone fragmentation commands the largest procedure volume. United States ambulatory surgery centers in Texas and Florida are converting to single-use platforms where lithotripsy case density justifies disposable economics.
- Tumor Diagnosis:Upper tract urothelial carcinoma surveillance requires high-magnification white-light and narrow-band imaging. German university hospitals in Munich and Heidelberg are piloting AI-assisted lesion recognition integrated with digital ureteroscope feeds.
- Stricture Management:Balloon dilation and incision of ureteral strictures demands combined endourological and fluoroscopic guidance.
- Biopsy Procedures:Forceps tissue sampling for histopathological confirmation relies on large working channel diameter.
Urolithiasis treatment anchors installed base; tumor diagnosis is climbing the fastest.
End User:
Facility scale and sterilization infrastructure determine technology access and procurement authority distribution.
- Surgical Centers:High-volume outpatient lithotripsy chains in the United States are bypassing traditional distributor markups through manufacturer-managed inventory systems. Consolidated purchasing by Texas and Florida integrated delivery networks is compressing vendor selection to single-source contracts.
- Ambulatory Care Facilities:Limited reprocessing infrastructure and Joint Commission infection control protocols are driving single-use digital ureteroscope conversion. CDC guidelines on endoscope-associated infections accelerate displacement of reprocessed flexible platforms.
- Specialized Clinics:Urology-focused practices in Japan's urban corridors leverage PMDA reimbursement parity for geriatric stone disease management.
- Diagnostic Laboratories:Pathology-confirmed biopsy workflows require sterile specimen handling protocols.
Surgical centers dominate procurement volume; ambulatory care facilities show steepest expansion trajectory.
Technology:
Regulatory clearance pathways and manufacturing scale separate commercial viability across technology tiers.
- Single-Use Devices:Polymer-based disposable sheaths eliminate cross-contamination risks and reprocessing labor costs. FDA 510(k) clearance streamlining for predicate-equivalent digital platforms accelerates time-to-revenue for manufacturers targeting United States hospital procurement cycles.
- High-Definition Imaging:CMOS sensor miniaturization delivers visualization performance at reduced distal tip diameter. Baden-Württemberg and Bavaria-based precision optics suppliers provide lens arrays for German and French manufacturers maintaining CE marking continuity under EU MDR.
- Reusable Devices:Sunk capital in automated washer-disinfectors at tertiary centers delays full conversion despite operational cost advantages.
- Narrow Band Imaging:Optical filtering enhances vascular pattern recognition for tumor surveillance applications.
High-definition imaging commands premium positioning; single-use devices are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision optics cluster supplies lens arrays and deflection mechanisms to manufacturers across Germany, France, and Switzerland, anchoring European production capacity for digital ureteroscope platforms.
United States
Academic medical centers in Boston and Houston are upgrading to high-definition CMOS sensor platforms where reimbursement supports premium capital expenditure. FDA 510(k) clearance streamlining accelerates predicate-equivalent digital platform approvals for manufacturers targeting hospital procurement cycles. Texas and Florida integrated delivery networks now mandate single-source contracts covering capital equipment, disposables, and service across multiple facilities.
Germany
University hospitals in Munich and Heidelberg pilot AI-assisted lesion recognition integrated with digital ureteroscope feeds for tumor surveillance applications. EU MDR conformity assessment requirements and notified body capacity constraints extend certification timelines for transatlantic market entry. Bavaria-based Karl Storz and Baden-Württemberg precision engineering suppliers maintain CE marking continuity through enhanced clinical evidence documentation.
Japan
Tokyo and Osaka metropolitan hospital networks are accelerating flexible platform deployment amid super-aging demographics and elevated stone disease prevalence in geriatric populations. PMDA reimbursement parity negotiations for single-use platforms in geriatric stone disease management open premium pricing acceptance. METI industrial policy supports domestic manufacturing of advanced optical systems for regional export.
China
County-level hospitals in Sichuan and Shandong provinces continue deploying semi-rigid stainless steel platforms for distal ureteral procedures where capital replacement cycles extend beyond seven years. NMPA localization testing requirements extend regulatory pathways for Western entrants seeking market access. Yangtze River Delta medical device clusters are developing domestic CMOS sensor capabilities to reduce import dependency.
United Kingdom
NHS procurement frameworks are consolidating vendor selection authority previously held by individual urology department chairs, compressing supplier margins. MHRA post-Brexit regulatory alignment with EU MDR maintains CE marking recognition for German and French manufacturers. London and Southeast England academic centers represent the primary demand concentration for premium digital platforms.
Global Ureteroscopes Market Competitive Landscape
Global majors compete with regional champions across regulatory clearance capabilities and hospital procurement relationships, producing a tiered structure where integrated portfolios command multi-year contracts. The vendor base separates into three strategic archetypes: diversified medtech conglomerates with urology divisions, specialized endoscopy manufacturers with precision optics heritage, and single-use disposable specialists attacking the ambulatory surgery center channel. Dominant competitive moves include M&A to fill portfolio gaps and direct distribution bypassing traditional markups in high-volume outpatient chains.
Within the diversified conglomerate tier, Boston Scientific Corporation and Stryker Corporation exemplify players leveraging integrated urology portfolios to dominate North American hospital contracts. Among specialized endoscopy manufacturers, Karl Storz and Olympus Corporation occupy positions anchored in European and Asia-Pacific precision engineering heritage respectively. Ambu represents the single-use disposable archetype, capturing ambulatory surgical center demand where reprocessing infrastructure remains limited.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Stryker Corporation |
| Karl Storz |
| Richard Wolf |
| PENTAX Medical |
| Dornier MedTech |
| Elmed Medical Systems |
| Ambu |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in Texas and Florida now dictate pricing terms through single-source contracts covering capital equipment, disposables, and service, compressing margins for manufacturers dependent on premium digital platforms while rewarding disposable specialists with ambulatory surgery center volume.
Pricing Analysis
CMOS sensor miniaturization costs and German precision optics sourcing determine input-cost pass-through to end-user pricing. Three-tier pricing structure across premium digital, standard fiber optic, and economy semi-rigid levels differentiates by image fidelity and deflection capability. Pricing pressure stems from procurement consortium consolidation mandating bundled service contracts. Community hospitals in India and Brazil exhibit highest price sensitivity, while academic medical centers in Germany and the United States absorb premium tiers.
Supply Chain Analysis
ISO 13485 and EU MDR conformity assessment requirements gate supplier qualification for lens arrays and deflection mechanisms. Manufacturing concentrates in Germany, Japan, and China, with Baden-Württemberg precision optics clusters feeding European assembly. Supply chains draw from rare-earth phosphors for CMOS sensors, nitinol steering cables, and biocompatible polymer sheaths. Single-source vulnerability in German lens array suppliers creates geographic concentration risk. Distribution runs through manufacturer-managed inventory systems bypassing traditional distributor markups in high-volume outpatient chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Ureteroscopes Market functions as a geographic-arbitrage play where EU MDR conformity assessment costs and extended timelines deter Western entrants from European positioning, while FDA 510(k) streamlining accelerates US revenue capture for predicate-equivalent digital platforms.
For Market Incumbents: Hedge against single-use disposable erosion by securing backward integration into CMOS sensor supply and expanding cleanroom manufacturing capacity in Baden-Württemberg to maintain CE marking continuity. Lock multi-year service contracts with Texas and Florida integrated delivery networks before procurement authority centralizes further. Prioritize AI-assisted stone recognition R&D to differentiate premium platforms from commoditizing fiber optic alternatives. For New Entrants and Emerging Players: Direct-to-ambulatory distribution channels offer the lowest barrier to outpatient lithotripsy chains in the United States where reprocessing infrastructure constraints favor disposable economics. Target Japanese geriatric stone disease management where PMDA reimbursement parity negotiations create pricing acceptance for single-use platforms. Pursue white-label manufacturing partnerships with Yangtze River Delta medical device clusters to bypass NMPA localization testing requirements. For Investors and Strategic Acquirers: Diversified medtech conglomerates with urology divisions are the most active acquirers in this space, seeking single-use disposable specialists to fill portfolio gaps. The long-term viability window favors platforms with software companion development capabilities and hospital system partnership depth. Watch PMDA reimbursement parity decisions as the inflection indicator for premium pricing acceptance in super-aging demographics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment gates transatlantic market access for German and French manufacturers. |
| Hospital System Partnership | Single-source contracts with Texas and Florida IDNs compress vendor selection to integrated portfolios. |
| Software Companion Development | AI-assisted stone recognition integration differentiates premium digital platforms in academic medical centers. |
| Reimbursement Strategy | PMDA parity negotiations determine single-use adoption velocity in Japanese geriatric stone disease management. |
| Backward Integration | Captive supply of CMOS sensors and precision optics defends margin against component cost volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with urologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Segment-weighting approaches distributed value across product type, application, end user, and technology dimensions over the projection horizon. CAGRs derived from fitted growth curves applied to procedure volume forecasts and capital replacement cycles. Industry-specific inputs included PMDA reimbursement parity timelines, EU MDR notified body capacity constraints, and ambulatory surgery center rollups in Texas and Florida.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted ureteroscopy would alter the outlook. Forecasts reflect assumptions regarding FDA clearance streamlining continuity, EU MDR implementation stability, and Japanese super-aging demographics trajectory. Deviation in PMDA reimbursement policy or REACH coating chemistry restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Surgical Robotic Services Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Ocular Implants Market
Medical Devices
Heated Humidifiers Market
Medical Devices
Lactation Massager Market
Medical Devices
Subcutaneous Implantable Defibrillator System Market