
 Non-Invasive Colon Cancer Screening Market | 2026-2036
Non-Invasive Colon Cancer Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Colon Cancer Screening Market Analytics
US clinical laboratory networks is rebalancing capacity toward decentralized sample collection. Exact Sciences Corporation leverages its integrated lab-to-patient logistics platform to sustain kit fulfillment density across primary care channels. Guardant Health, Inc. competes through liquid biopsy specialization, while Sysmex Corporation anchors automated immunoassay throughput in Asia-Pacific reference labs.
Non-invasive colon cancer screening encompasses fecal, serological, and volatile biomarker assays that detect neoplastic lesions or advanced adenomas without endoscopic instrumentation; polymerase chain reaction amplification of methylated DNA markers in stool samples achieves sensitivity above ninety percent for stage one colorectal malignancies. The primary commercial purpose is population-scale early detection in average-risk adults aged forty-five and older who avoid optical colonoscopy. Fecal immunochemical tests occupy the mature volume tier with established reimbursement, whereas stool DNA tests capture expanding margin pools through higher per-test pricing and longitudinal patient retention. Liquid biopsy technology leads R&D intensity but remains pre-commercial for colorectal indications, while microbiome analysis attracts venture funding for multi-omics panel development.
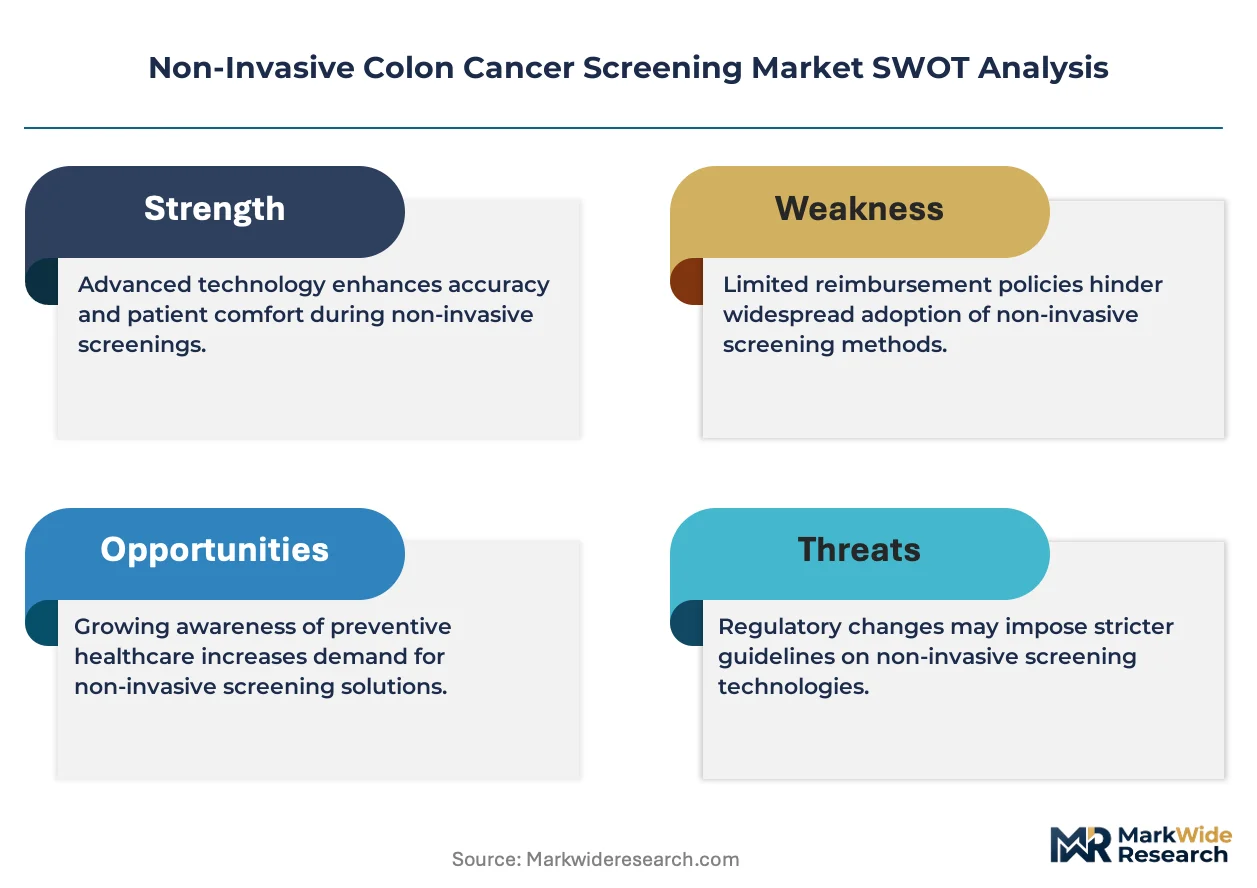
FDA premarket approval and CMS national coverage determinations govern US market access timelines and reimbursement thresholds, directly constraining product launch cadence and clinical validation requirements. The European Medicines Agency coordinates centralized marketing authorization under the In Vitro Diagnostic Medical Devices Regulation, while national health technology assessment bodies in France and Germany negotiate conditional reimbursement for novel screening modalities. Stakeholders must monitor evolving USPSTF grade A recommendation expansions to age forty-five cohorts and corresponding commercial plan coverage mandates.
Market Dynamics
CMS national coverage determinations for multi-target stool DNA tests are compressing commercialization timelines while diagnostic laboratories rebalance capacity toward decentralized sample collection models.
Growth Catalysts
- USPSTF Grade A Recommendation Expansion:The United States Preventive Services Task Force lowered screening age thresholds to forty-five, triggering commercial plan coverage mandates that expand addressable patient populations.
- Automated Immunoassay Platforms:Reference laboratories in Japan and South Korea are deploying high-throughput systems that reduce per-sample processing costs and enable population-scale screening programs.
- Fecal Sample Logistics Networks:Integrated kit-to-laboratory fulfillment infrastructure now supports primary care channel density without requiring endoscopy suite capacity.
Market Restraints
- Reimbursement Rate Compression:Medicare fee schedules for fecal immunochemical tests create pricing ceilings that constrain margin expansion for novel assay developers.
- Clinical Validation Burden:FDA premarket approval pathways demand prospective trials exceeding ten thousand subjects, extending capital lockup periods for stool DNA test commercialization.
- Optical Colonoscopy Substitution:Established endoscopic screening maintains physician preference in health systems with captive gastroenterology capacity.
Strategic Opportunities
- Microbiome Panel Convergence:Multi-omics integration of bacterial biomarkers with methylated DNA detection is opening venture-funded development tracks for next-generation screening specificity.
- Employer-Sponsored Wellness Channels:Self-insured corporations are adding non-invasive screening to preventive benefit tiers, bypassing traditional clinical referral pathways.
- EMA Centralized Authorization:The In Vitro Diagnostic Medical Devices Regulation streamlines EU-wide market access for manufacturers achieving CE marking under notified body supervision.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories face recruitment gaps for computational biologists capable of validating algorithmic scoring systems for stool DNA interpretation.
- Sample Stability Logistics:Temperature-controlled transport requirements for fecal specimens complicate last-mile distribution to centralized processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Colon Cancer Screening Market |
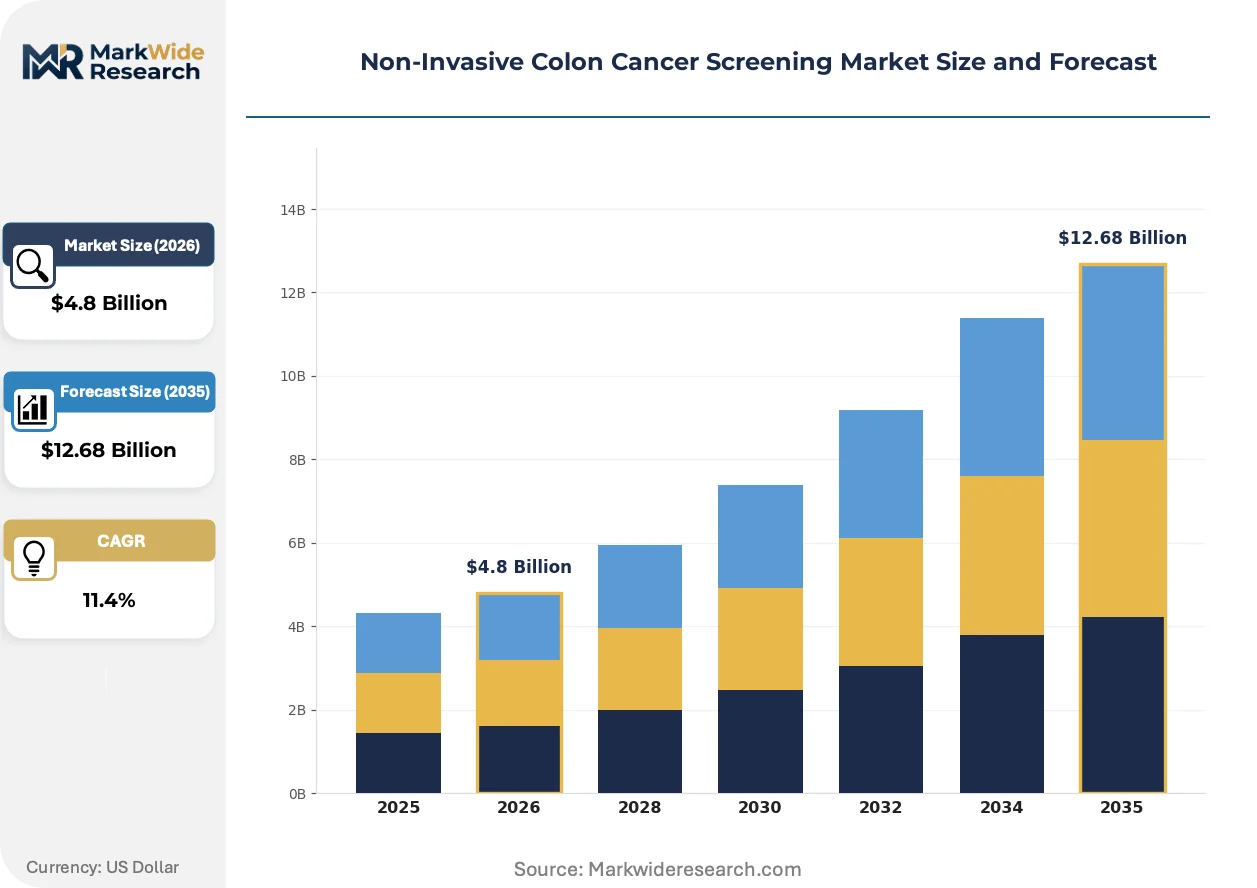
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fecal Immunochemical Test, Stool DNA Test, Serum Test, Breath Test Delivery Mode: Home Testing, Laboratory Testing, Direct-to-Consumer, Physician Office End User: Clinics, Hospitals, Diagnostic Laboratories, At-Home Consumers Technology: Polymerase Chain Reaction, Immunohistochemistry, Liquid Biopsy, Microbiome Analysis |
| Companies Covered | Exact Sciences Corporation, Guardant Health, Inc., Epigenomics Inc., Abbott Laboratories, Sysmex Corporation, Siemens Healthineers, FUJIFILM Holdings Corporation, Geneoscopy, Inc., Novigenix SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Colon Cancer Screening Market Evolving Landscape
Liquid biopsy platforms are attracting R&D investment intensity while regulatory frameworks mature for blood-based colorectal screening, reshaping competitive positioning between sample modalities.
Multi-cancer early detection panels are decentralizing the diagnostic workflow by enabling blood-draw collection at retail pharmacy sites rather than clinical laboratory networks. Primary care physicians in the United States are adopting these platforms for patient compliance improvement. The shift is compressing dependence on specialized phlebotomy infrastructure and expanding geographic reach into rural service areas.
The European Medicines Agency's implementation of the In Vitro Diagnostic Medical Devices Regulation is elevating clinical evidence requirements for novel biomarker assays seeking CE marking. Manufacturers must now submit prospective performance data through notified body review pathways. German and French health technology assessment bodies are responding with conditional reimbursement frameworks that reward superior sensitivity metrics.
Direct-to-consumer screening channels are disrupting traditional physician-referral pathways as patients initiate testing through employer wellness portals and telemedicine platforms. This bypasses gastroenterology gatekeepers who previously controlled screening access. The United States exhibits the most pronounced channel fragmentation, though comparable patterns are emerging in United Kingdom private health networks.
Non-Invasive Colon Cancer Screening Market Segmentation
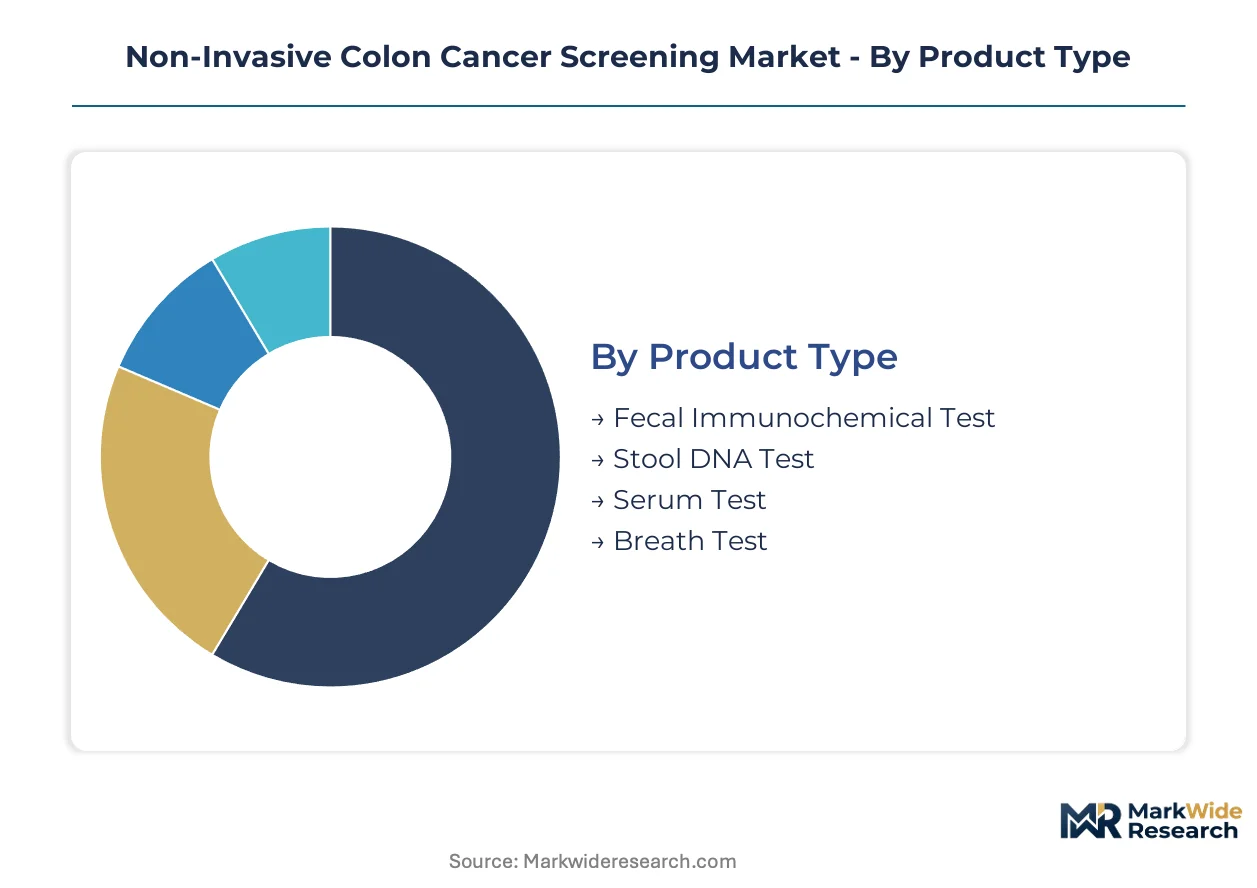
Non-invasive colon cancer screening markets fragment across four analytical dimensions that determine reimbursement pathways, regulatory validation burdens, and channel economics. Product type and technology selection drive capital intensity and clinical evidence requirements, while delivery mode and end user configuration shape logistics infrastructure and patient compliance rates.
Product Type:
Supply concentration in stool-based platforms reflects manufacturing economies and established reimbursement codes that constrain novel assay entry.
- Fecal Immunochemical Test:Quantitative antibody detection of human hemoglobin in stool samples achieves detection thresholds of fifty micrograms per gram with standardized cutoff protocols. Demand concentrates in Germany and Japan where national screening programs mandate annual testing for populations over fifty, constrained by Medicare fee schedule compression in the United States that limits per-test margins.
- Stool DNA Test:Multi-target assays amplify methylated DNA markers through polymerase chain reaction with sensitivity exceeding ninety percent for stage one malignancies. Exact Sciences Corporation's integrated logistics platform sustains kit fulfillment density across United States primary care channels, though FDA premarket approval demands prospective trials exceeding ten thousand subjects.
- Serum Test:Blood-based protein and circulating tumor DNA detection remains pre-commercial for colorectal indications with ongoing clinical validation.
- Breath Test:Volatile organic compound analysis through gas chromatography-mass spectrometry attracts venture funding for non-invasive screening alternatives.
Fecal immunochemical tests absorb the bulk of installed capacity; stool DNA tests are expanding most quickly.
Delivery Mode:
Cost tier differentiation separates centralized laboratory processing from decentralized collection models that reduce per-patient logistics expenditure.
- Home Testing:Patient-collected stool samples with prepaid return mailers eliminate phlebotomy infrastructure requirements. Demand concentrates in United States employer wellness channels and United Kingdom private health networks where telemedicine platforms bypass traditional gastroenterology referrals.
- Laboratory Testing:Centralized high-throughput processing in reference facilities achieves economies of scale for population screening programs. Sysmex Corporation anchors automated immunoassay throughput in Japan and South Korea where national health systems deploy standardized platforms.
- Direct-to-Consumer:Retail pharmacy blood-draw collection for multi-cancer panels compresses dependence on specialized infrastructure.
- Physician Office:Point-of-care fecal testing with immediate results supports compliance in rural service areas with limited laboratory access.
Laboratory testing commands the highest volume throughput; direct-to-consumer channels are climbing the fastest.
End User:
Customer type stratification determines procurement authority and reimbursement negotiation leverage across institutional and individual purchasers.
- Diagnostic Laboratories:Reference facilities with automated platforms process population-scale screening volumes under national program contracts. French and German health technology assessment bodies negotiate conditional reimbursement for novel modalities based on superior sensitivity metrics.
- Clinics:Primary care practices serve as gatekeepers for screening initiation with integrated kit distribution.
- Hospitals:Captive gastroenterology capacity maintains physician preference for optical colonoscopy substitution in integrated health systems.
- At-Home Consumers:Self-initiated testing through employer portals and telemedicine platforms fragments traditional referral pathways most pronouncedly in the United States.
Diagnostic laboratories capture the dominant procurement volume; at-home consumers are gaining share fastest.
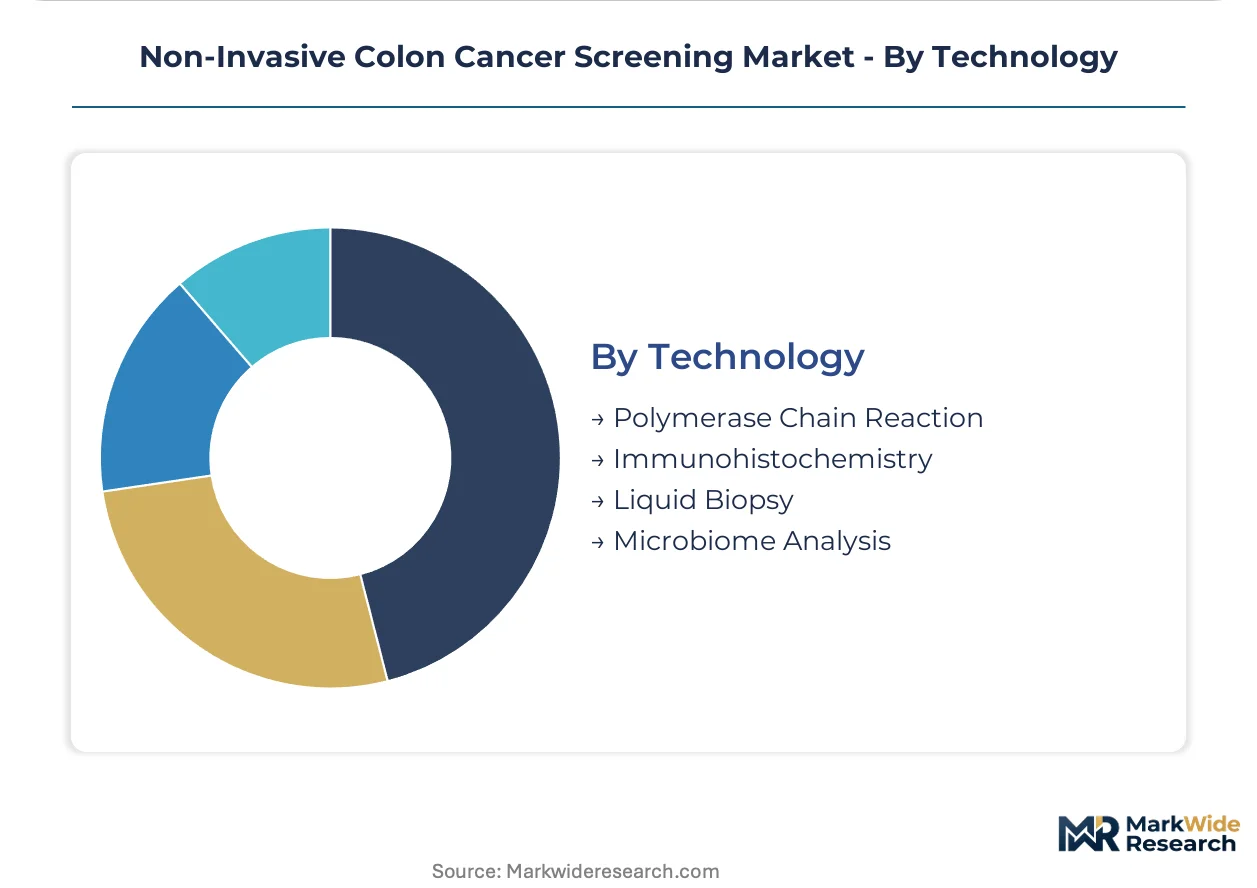
Technology:
Maturity gradients separate commercially validated platforms from venture-funded development tracks with unproven regulatory pathways.
- Polymerase Chain Reaction:DNA amplification of methylated biomarkers in stool achieves clinical validation with established FDA premarket approval precedents.
- Liquid Biopsy:Circulating tumor DNA detection from peripheral blood attracts R&D intensity while regulatory frameworks mature for colorectal indications.
- Immunohistochemistry:Antibody-based protein detection supports complementary diagnostic confirmation in laboratory settings.
- Microbiome Analysis:Bacterial biomarker integration with methylated DNA detection opens multi-omics panel development funded by venture capital for next-generation specificity.
Polymerase chain reaction retains the deepest regulatory validation; microbiome analysis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stool-based assay manufacturing concentrates in automated immunoassay production clusters across Japan and South Korea, while regulatory validation infrastructure anchors in the United States and Germany. Diagnostic laboratory networks in these geographies determine commercial access velocity.
United States
FDA premarket approval pathways and CMS national coverage determinations govern market access timelines for multi-target stool DNA tests. Commercial plan coverage mandates triggered by USPSTF grade A recommendation expansions to age forty-five cohorts reshape addressable patient populations. Exact Sciences Corporation leverages integrated lab-to-patient logistics platforms across primary care channels in Wisconsin and California.
Germany
Preventive oncology infrastructure and statutory health insurance integration drive demand concentration for fecal immunochemical tests. The Federal Joint Committee (G-BA) negotiates conditional reimbursement for novel screening modalities based on superior sensitivity metrics. Diagnostic laboratory networks in Bavaria and North Rhine-Westphalia process population-scale screening volumes under national program contracts.
Japan
National health system deployment of standardized screening platforms and aging demographics expand fecal immunochemical test volumes. PMDA regulatory frameworks govern in vitro diagnostic medical device approvals. Sysmex Corporation anchors automated immunoassay throughput in reference laboratories concentrated in Kobe and Tokyo metropolitan clusters.
South Korea
National Cancer Screening Program infrastructure and high-throughput laboratory automation support population-scale fecal testing deployment. MFDS regulatory oversight shapes clinical validation requirements for novel biomarker assays. Diagnostic processing facilities in Seoul Capital Area and Busan-Ulsan region achieve economies of scale for standardized platform deployment.
United Kingdom
NHS bowel cancer screening programme procurement frameworks and private health network expansion fragment traditional referral pathways. MHRA post-Brexit regulatory autonomy reshapes CE marking transition timelines for IVD manufacturers. Telemedicine platforms and employer wellness portals in London/Southeast and Manchester clusters enable direct-to-consumer channel growth.
Non-Invasive Colon Cancer Screening Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue liquid biopsy specialization and microbiome multi-omics integration. The market structure fragments across three maturity tiers: integrated diagnostic platform operators, reference laboratory automation specialists, and venture-funded biomarker developers. Strategic archetypes include logistics-integrated kit fulfillment networks, high-throughput immunoassay scale operators, and blood-based assay R&D specialists. Competitive moves concentrate on automated platform deployment partnerships and longitudinal patient retention program development.
Among United States-based molecular diagnostics specialists, Exact Sciences Corporation and Guardant Health, Inc. exemplify contrasting archetype positions. Exact Sciences represents the logistics-integrated stool DNA platform operator with established FDA premarket approval precedents. Guardant Health occupies the liquid biopsy R&D specialist tier with blood-based assay development concentration. Japanese precision instrument manufacturer Sysmex Corporation anchors the automated immunoassay throughput archetype in Asia-Pacific reference laboratory networks. These three entities collectively illustrate the technology-modality segmentation shaping competitive positioning.
| Leading Market Players |
|---|
| Exact Sciences Corporation |
| Guardant Health, Inc. |
| Epigenomics Inc. |
| Abbott Laboratories |
| Sysmex Corporation |
| Siemens Healthineers |
| FUJIFILM Holdings Corporation |
| Geneoscopy, Inc. |
| Novigenix SA |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up diagnostic laboratory networks in the United States and Germany are consolidating stool-based assay processing capacity, creating pricing discipline through volume concentration while squeezing margins for independent kit manufacturers lacking captive logistics infrastructure. This ownership pattern directly links supply-side consolidation to reimbursement rate compression, as centralized buyers negotiate preferential fee schedules with payers.
Pricing Analysis
Warranty and service bundling separates integrated logistics platforms from unbundled kit suppliers, with Exact Sciences Corporation's prepaid return mailers and patient navigation support commanding premium positioning against bare-bones fecal immunochemical test vendors. Three-tier pricing structure across premium, standard, and economy levels reflects test complexity tiers: multi-target stool DNA assays with longitudinal patient retention programs occupy premium positioning, quantitative FIT with automated processing occupies standard, and basic qualitative FIT without support services anchors economy. Cost compression in the standard tier is intensifying because Medicare fee schedule ceilings constrain per-test margins, while diagnostic laboratories with national program contracts in Germany and Japan exhibit lowest price sensitivity due to statutory reimbursement guarantees.
Supply Chain Analysis
Reverse logistics for stool sample collection kits—prepaid return mailers, temperature-controlled transit packaging, and patient-reminder fulfillment—consume disproportionate working capital relative to forward distribution, with kit expiration management and re-shipment protocols adding complexity absent in standard diagnostic consumables. Manufacturing concentration spans Japan, South Korea, and the United States, with Sysmex Corporation and FUJIFILM Holdings Corporation anchoring automated immunoassay production in Kobe and Tokyo metropolitan clusters. Raw material dependencies include methylated DNA primer synthesis, antibody production for hemoglobin detection, and specialized stool collection vessel polymers. Single-source vulnerability in PCR reagent supply creates exposure to batch contamination recalls. Distribution runs through integrated lab-to-patient logistics platforms rather than traditional medical device wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated diagnostic platform operators, with FDA premarket approval burdens and ten-thousand-subject clinical validation requirements forcing capital-constrained stool DNA developers toward acquisition or exit.
For Market Incumbents: Anticipate liquid biopsy substitution threats by securing longitudinal patient retention through microbiome panel R&D partnerships, while defending reference laboratory automation positions in Japan and South Korea through capacity additions in Seoul Capital Area and Kobe clusters. Backward integration into stool collection vessel manufacturing reduces polymer supply exposure. For New Entrants and Emerging Players: Employer-sponsored wellness portals in the United States offer the most penetrable channel bypassing gastroenterology gatekeepers, with telemedicine platform partnerships enabling direct-to-consumer screening initiation. White-space targets include rural service areas with limited endoscopy suite capacity and United Kingdom private health networks fragmenting NHS referral pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor venture-funded microbiome analysis developers with multi-omics intellectual property in the United States, where bioinformatics talent scarcity has stalled algorithmic validation timelines. Long-term viability hinges on achieving FDA premarket approval precedents for bacterial biomarker integration. The signal to watch is EMA centralized authorization progress under IVDR for CE marking acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Unlocks CMS national coverage determination and commercial plan mandate eligibility for stool DNA assays. |
| Integrated Logistics Platform Expansion | Exact Sciences Corporation's kit fulfillment density sustains primary care channel capture against laboratory testing competitors. |
| Microbiome Panel Convergence R&D | Multi-omics bacterial biomarker integration attracts venture funding for next-generation screening specificity improvements. |
| Employer Wellness Channel Partnership | Self-insured corporations bypass traditional clinical referral pathways for direct-to-consumer screening access. |
| Automated Immunoassay Scale-Up | Sysmex Corporation's high-throughput deployment in Japan and South Korea enables population-scale screening program economics. |
Research Methodology
Document review covered FDA 510(k) and PMA filings, CMS national coverage determinations, EMA IVDR implementation guidance, and health technology assessment body reports from France and Germany, complemented by interviews with diagnostic laboratory operations directors, clinical validation biostatisticians, GPO contracts managers, and payer policy leads. Secondary sources included hospital procurement databases, CMS Medicare fee schedules, ClinicalTrials.gov registration records, and statutory health insurance reimbursement frameworks. Bottom-up assay volume modeling triangulated against top-down national screening program penetration targets.
Market sizing outputs reflect segment-level disaggregation across product type, delivery mode, end user, and technology dimensions over the projection horizon, with polymerase chain reaction and liquid biopsy platforms tracked separately for regulatory validation maturity. CAGRs were derived from logistic diffusion modeling of screening guideline adoption curves and reimbursement expansion schedules. Forecast inputs incorporated USPSTF recommendation threshold effects, IVDR transition timeline uncertainty, and employer wellness channel penetration rates.
The model holds under stable FDA and EMA regulatory frameworks; deviation in CMS national coverage determination timelines or G-BA conditional reimbursement negotiations would shift commercialization velocity assumptions. Practitioners should monitor USPSTF grade A recommendation expansion signals and IVDR notified body capacity constraints for early indicators of access timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Gastroscopes Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Esophageal Stents Market
Endoscopy
United States Endoscopy Devices Market
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Global Endoscopes Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
Industrial Endoscope Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Endoscopy Market