
 Esophageal Stents Market | 2026-2036
Esophageal Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Esophageal Stents Market Analysis
Hospital procurement consolidation is repositioning buyer power toward integrated delivery networks and group purchasing organizations across major tertiary centers. Boston Scientific Corporation leverages its endoscopy portfolio depth to sustain contract leverage with these consolidated buyers. Cook Medical LLC anchors its position through specialized interventional gastroenterology channels. Merit Medical Systems, Inc. competes on interventional radiology cross-selling that extends its reach beyond pure gastroenterology.
An esophageal stent is a tubular prosthesis deployed within the esophageal lumen to restore patency in malignant strictures, tracheoesophageal fistulas, or benign refractory narrowings, typically manufactured from nitinol wire mesh or silicone-coated polymers with radial forces calibrated to resist compression while permitting mucosal ingrowth. Self-expanding metal stents dominate procedural volume due to their deployment reliability and tissue integration profile, while biodegradable polymer platforms represent the fastest-growing material category as clinicians seek to reduce extraction morbidity in benign indications. Endoscopic delivery mode occupies the primary procedural channel, though fluoroscopic guidance commands premium positioning in complex proximal or tortuous anatomies where direct visualization proves insufficient.
FDA quality system regulations, EU MDR conformity requirements, and Japan's PMDA stent approval pathways collectively elevate clinical evidence thresholds and post-market surveillance obligations for manufacturers seeking multi-regional market access. These frameworks shape demand by favoring suppliers with established regulatory infrastructure and documented long-term patency data. Stakeholders must monitor evolving reimbursement criteria for palliative versus curative-intent stent placement as health technology assessment bodies recalibrate value thresholds for interventional oncology spending.
Market Dynamics
Hospital procurement consolidation into integrated delivery networks concentrates purchasing power among fewer buyers, forcing manufacturers to restructure contract terms and service bundling around volume commitments rather than individual device margins.
Growth Catalysts
- Palliative care infrastructure:The United States, Germany, and Japan are expanding dedicated esophageal cancer treatment centers. These facilities require reliable stent supply chains for malignant stricture management.
- Biodegradable polymer platforms:Clinicians in tertiary centers increasingly specify absorbable stents for benign indications. This material category reduces extraction morbidity and repeat endoscopy costs.
- FDA quality system regulations:Updated QSR requirements favor manufacturers with established clinical documentation. Suppliers with long-term patency data gain preferential access to institutional formularies.
Market Restraints
- Nitinol supply concentration:Shape-memory alloy production clusters in specific metallurgical regions. Stent manufacturers face input cost volatility when nickel-titanium supply tightens.
- EU MDR conformity timelines:Extended clinical evidence requirements delay product launches. Small manufacturers struggle to fund post-market surveillance infrastructure.
- Surgical resection alternatives:Minimally invasive esophagectomy techniques improve curative outcomes. Early-stage malignancy patients increasingly bypass palliative stenting.
Strategic Opportunities
- Japan's PMDA stent approval pathways:Streamlined review for devices with US or EU precedent creates fast-track access. Manufacturers with existing FDA clearances can prioritize Japanese market entry.
- Fluoroscopic-guided complex deployment:Interventional radiology suites require premium-positioned stents for tortuous proximal anatomy. Cross-selling opportunities extend beyond pure gastroenterology channels.
- Telemedicine-integrated follow-up:Remote monitoring protocols for stent patency assessment reduce in-person endoscopy burden. Integrated delivery networks value bundled remote care solutions.
Industry Challenges
- Interventional gastroenterology fellowship capacity:Specialized training programs produce insufficient operators for complex stent deployment. Tertiary centers compete for skilled proceduralists.
- ISO 13485 certification maintenance:Medical device quality management audits require sustained documentation investment. Mid-size manufacturers allocate disproportionate resources to compliance personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esophageal Stents Market |
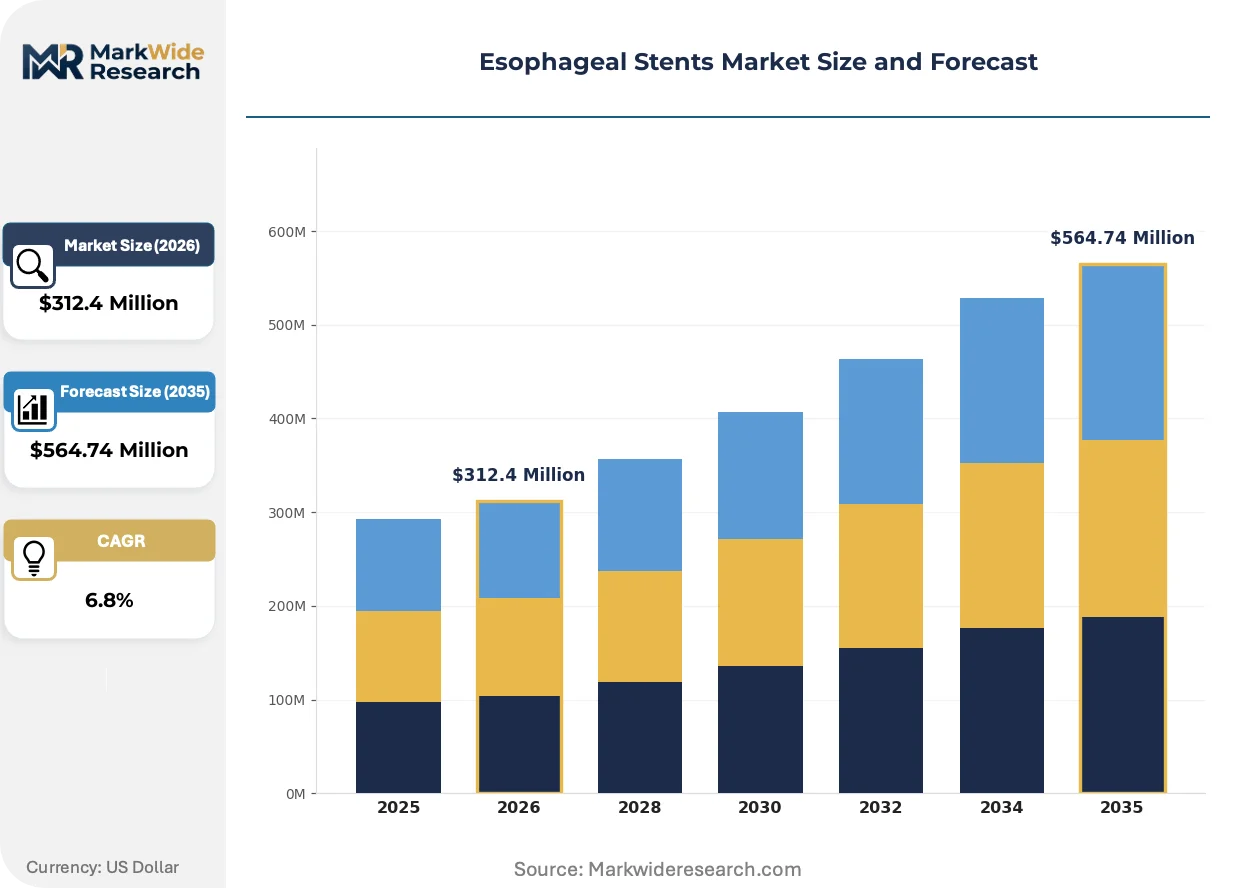
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding, Connected, Flared, Balloon Delivery Mode: Endoscopic, Laparoscopic, Fluoroscopic, Radiological Material: Metal, Polymer, Biodegradable, Coated End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes |
| Companies Covered | Taewoong Medical Co., Ltd., Micro-Tech Endoscopy Co., Ltd., Boston Scientific Corporation, BD, Olympus Corporation, Cook Medical LLC, Merit Medical Systems, Inc., Ella - CS, s.r.o., Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esophageal Stents Market Emerging Trajectories
Biodegradable materials and regulatory harmonization are compressing traditional product lifecycles while reshaping how manufacturers structure clinical evidence generation and post-market commitments.
Biodegradable polymer stents are absorbing clinical attention in benign esophageal stricture management. Pediatric gastroenterology units and post-radiation fibrosis centers specify these platforms to eliminate extraction procedures. The technology is absorbing market share from conventional metal stents in non-malignant indications where temporary scaffolding suffices.
EU MDR conformity requirements now mandate systematic clinical follow-up for all permanent implantable devices. Stent manufacturers must maintain patient registries documenting long-term patency and adverse events. European tertiary centers increasingly specify suppliers with established MDR technical documentation, compressing vendor shortlists before procurement negotiations begin.
Integrated delivery networks now unbundle device procurement from procedural service contracts. Group purchasing organizations negotiate enterprise-wide stent pricing across multiple hospital systems. The United States exhibits the most advanced concentration of buyer power, with IDNs commanding volume-based rebates that reshape manufacturer margin structures.
Esophageal Stents Market Segmentation
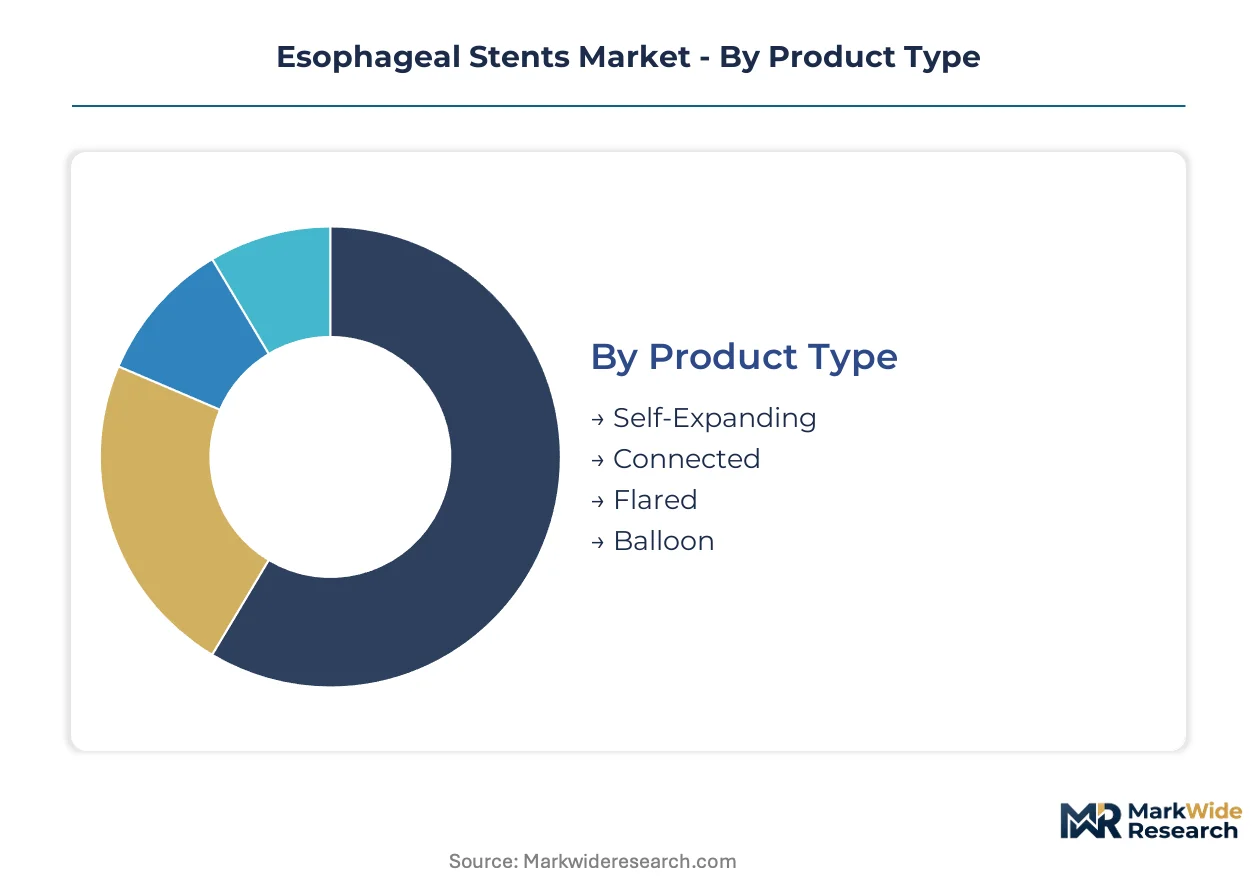
Segmentation in esophageal stents reveals how procedural complexity, material science advances, and site-of-care economics fragment purchasing decisions across divergent clinical workflows. Manufacturers must align product configurations with specific deployment environments rather than pursuing universal platform strategies.
Product Type:
Deployment mechanics and radial force requirements differentiate buying criteria across malignant versus benign indications.
- Self-Expanding:Nitinol wire mesh constructs deliver calibrated radial force upon deployment from constrained delivery systems. United States tertiary cancer centers specify these for malignant strictures where tissue ingrowth stability matters. FDA-cleared designs with documented patency durations command preferential formulary placement.
- Connected:Linked stent segments accommodate tortuous esophageal anatomy and long-segment strictures. German interventional gastroenterology units favor connected platforms for post-radiation fibrosis cases where single-unit stents risk migration.
- Flared:Proximal and distal flanges anchor against luminal walls to resist dislocation in distal esophageal placements.
- Balloon:Balloon-expandable platforms permit precise diameter control in benign refractory strictures where over-expansion risks perforation.
Self-expanding configurations dominate malignant indication volumes; biodegradable-connected hybrids are climbing fastest in benign applications.
Delivery Mode:
Operator specialty and anatomical complexity determine whether visualization relies on direct endoscopy or radiological guidance.
- Endoscopic:Direct visualization through flexible endoscopes enables real-time positioning assessment and immediate mucosal response evaluation. Japanese tertiary centers with high procedural volumes prefer endoscopic delivery for routine distal and mid-esophageal placements where anatomy permits straight-line access.
- Fluoroscopic:X-ray guidance permits deployment in proximal cervical esophagus or markedly tortuous segments where endoscopic advancement fails. Interventional radiology suites in United States academic medical centers command premium pricing for these complex cases.
- Laparoscopic:Surgical stent placement addresses combined esophageal-gastric procedures or failed endoscopic access scenarios.
- Radiological:CT-guided deployment serves patients with altered anatomy from prior resection or gastric pull-up reconstruction.
Endoscopic delivery handles the majority of placements; fluoroscopic-guided deployment shows steepest expansion trajectory as complex case referrals concentrate at academic centers.
Material:
Implant permanence versus absorbability splits material selection between oncologic palliation and pediatric or benign adult indications.
- Metal:Nitinol and stainless steel platforms provide permanent structural support with established extraction protocols when occlusion occurs. German and Japanese reimbursement frameworks favor metal stents for malignant indications where device longevity reduces replacement frequency.
- Biodegradable:Absorbable polymer scaffolds eliminate extraction morbidity in benign strictures and pediatric patients. United States pediatric gastroenterology programs specify these to avoid repeated anesthesia exposure for device removal.
- Polymer:Silicone and polyurethane constructs offer drug-eluting potential and reduced tissue ingrowth compared to bare metal.
- Coated:Polymer-covered metal stents prevent tumor ingrowth in malignant strictures while maintaining radial strength.
Metal platforms retain the largest installed base; biodegradable materials are expanding most quickly as benign indication protocols mature.
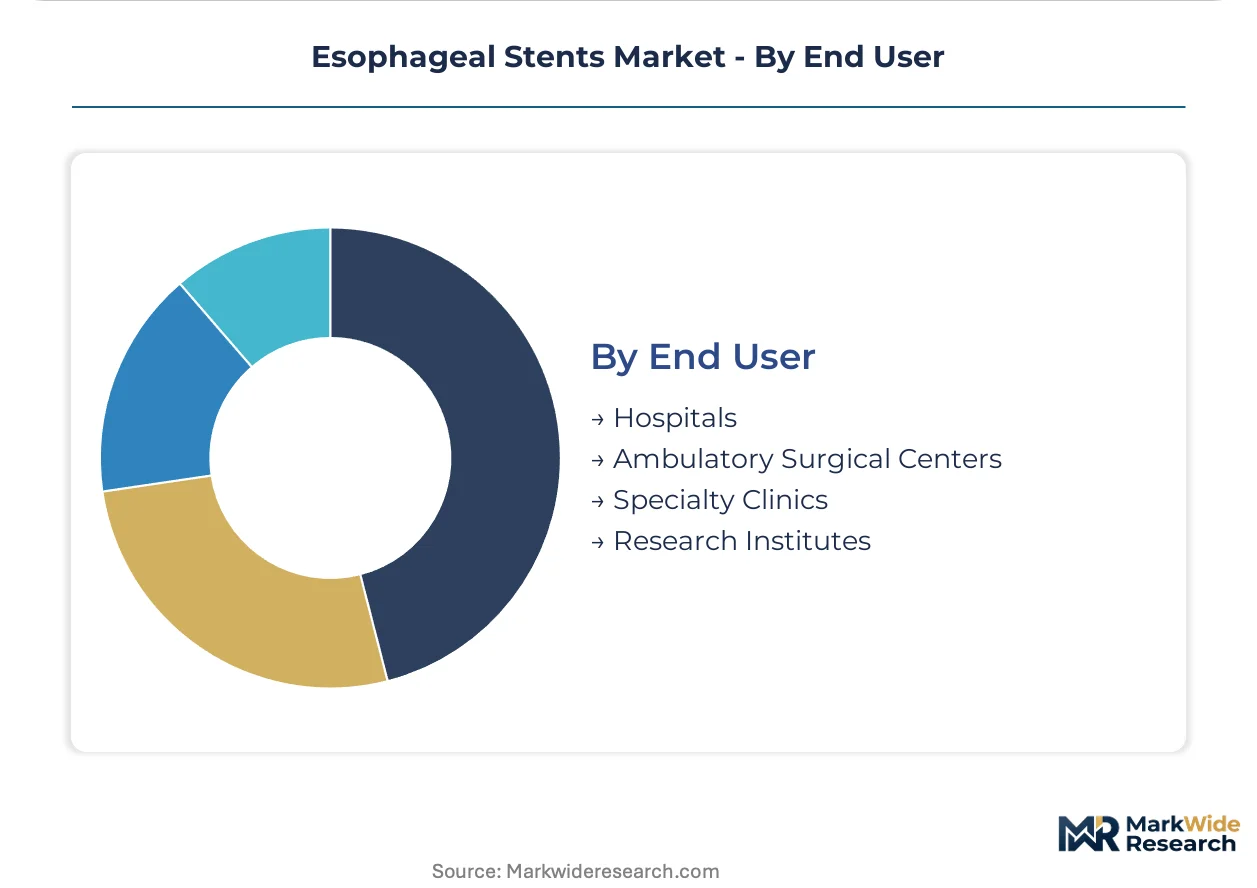
End User:
Capital equipment availability, reimbursement rates, and case complexity filter stent procurement across facility types.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts spanning interventional gastroenterology, interventional radiology, and thoracic surgery service lines. United States hospital systems leverage volume commitments to extract performance guarantees and consignment inventory terms.
- Ambulatory Surgical Centers:Outpatient endoscopy suites in Germany and Japan pursue same-day discharge protocols for uncomplicated stent placements. These facilities prioritize single-use delivery systems that minimize reprocessing overhead and infection control liability.
- Specialty Clinics:Dedicated esophageal disease centers concentrate expertise and attract complex referral patterns requiring specialized stent inventories.
- Research Institutes:Academic medical centers with active clinical trial programs source investigational devices and maintain registries for post-market surveillance obligations.
Hospitals absorb the majority of device value; ambulatory surgical centers are gaining share fastest as same-day reimbursement frameworks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan maintain parallel expansion trajectories in palliative esophageal care infrastructure, while the United States diverges toward outpatient delivery models. Procurement consolidation patterns vary sharply across these three markets.
United States
Integrated delivery networks in Texas and California concentrate stent purchasing through enterprise-wide contracts with group purchasing organizations. FDA's updated quality system regulations favor suppliers with established clinical documentation and long-term patency registries. The Cleveland Clinic and MD Anderson anchor complex case referral patterns that drive fluoroscopic-guided deployment volumes.
Germany
Post-radiation fibrosis centers in Bavaria and North Rhine-Westphalia specify connected stent platforms for long-segment stricture management. EU MDR conformity requirements mandate systematic clinical follow-up and patient registries for all permanent implantable devices. Berlin and Munich academic medical centers maintain active post-market surveillance programs that shape institutional formularies.
Japan
PMDA stent approval pathways with streamlined review for devices holding US or EU precedent accelerate market entry for qualified manufacturers. METI funding for palliative care infrastructure expansion concentrates in Tokyo and Osaka metropolitan areas. Kansai region tertiary centers lead procedural volume for endoscopic delivery in routine distal esophageal placements.
United Kingdom
NHS England's interventional gastroenterology service specifications concentrate complex stent procedures at designated cancer centers in London, Manchester, and Birmingham. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements elevates evidence thresholds for market access. The Royal Marsden and University College London Hospitals anchor referral networks for tracheoesophageal fistula management.
South Korea
MFDS medical device approval pathways emphasize clinical evidence from domestic patient populations for stent registration. Seoul National University Hospital and Asan Medical Center anchor interventional gastroenterology fellowship training that produces specialized operators for complex deployment. Busan-Ulsan manufacturing clusters support nitinol wire mesh component supply for regional stent fabricators.
Esophageal Stents Market Vendor Landscape
United States producers anchor the premium-tier contract position; Korean and Czech specialists hold differentiated niches in material platforms and connected configurations. Market structure tilts toward consolidated procurement leverage at integrated delivery networks, with three to four suppliers capturing majority volume in any given hospital system. Strategic archetypes include diversified endoscopy portfolio holders, interventional radiology cross-sellers, and biodegradable material specialists. Competitive moves center on regulatory fast-tracking through precedent approvals and service bundling around remote monitoring protocols.
Within the diversified portfolio tier, Boston Scientific Corporation and Cook Medical LLC represent established contract leverage with consolidated buyers, while Merit Medical Systems, Inc. occupies a position bridging interventional radiology and gastroenterology channels. Taewoong Medical Co., Ltd. exemplifies the Korean specialist archetype focused on nitinol platform refinement. Micro-Tech Endoscopy Co., Ltd. anchors Chinese manufacturing scale for delivery system components. Ella - CS, s.r.o. represents Central European engineering precision in connected stent geometries.
| Leading Market Players |
|---|
| Taewoong Medical Co., Ltd. |
| Micro-Tech Endoscopy Co., Ltd. |
| Boston Scientific Corporation |
| BD |
| Olympus Corporation |
| Cook Medical LLC |
| Merit Medical Systems, Inc. |
| Ella - CS, s.r.o. |
| Medtronic plc |
| Others |
Supply Flow & Price Mechanics
Specialized nitinol metallurgists in Busan-Ulsan manufacturing clusters anchor labor-cost differentials that widen pricing-tier spreads between premium FDA-cleared stents and economy-grade alternatives. This workforce concentration permits South Korean fabricators to undercut German and United States producers on standard nitinol mesh platforms while premium-tier manufacturers defend margins through clinical documentation investments.
Pricing Analysis
Capacity additions in Czech Republic precision engineering facilities are reshaping price floors for connected stent geometries. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and long-term patency data availability. Cost compression in the economy tier is intensifying because Chinese delivery system component manufacturers scale output. Ambulatory surgical centers exhibit the highest price sensitivity; academic medical centers with bundled reimbursement contracts show the least.
Supply Chain Analysis
Nitinol wire feedstock rests on nickel-titanium smelting operations concentrated in China, United States, and Japan. Shape-memory alloy ingots, laser-cutting equipment, and polymer coating chemistries constitute critical input dependencies. Single-source vulnerability in medical-grade nickel sourcing from specific metallurgical regions threatens input cost stability. Distribution runs through group purchasing organization contracts that consolidate hospital system procurement across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as biodegradable polymer specifications displace conventional metal platforms in benign indication protocols. Demand is concentrating toward stents with documented extraction-free outcomes and pediatric safety profiles.
For Market Incumbents: Acquire biodegradable polymer formulation expertise to counter displacement risk from metal stent commoditization. Secure backward integration into nitinol wire drawing to mitigate raw material cost volatility. Prioritize MDR technical documentation investments that compress vendor shortlists at European tertiary centers. For New Entrants and Emerging Players: Pediatric gastroenterology programs represent an underserved buyer archetype with unmet demand for absorbable stent platforms. White-space opportunities concentrate in post-radiation fibrosis centers requiring connected configurations for long-segment strictures. A reimbursement strategy bundling remote monitoring protocols offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale biodegradable material specialists lacking enterprise GPO contracts. Long-term viability over the analysis window hinges on regulatory fast-track capabilities through FDA-EU-Japan precedent approvals. Acquisition targets should demonstrate established PMDA submission pathways. The signal to watch is EU MDR certificate issuance rates as a forward indicator of competitive access compression.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer R&D Investment | Absorbable stent platforms eliminate extraction morbidity in pediatric gastroenterology protocols. |
| MDR Technical Documentation Buildout | Systematic clinical follow-up infrastructure secures European hospital formulary placement. |
| Integrated Delivery Network Partnership | Enterprise-wide GPO contracts consolidate purchasing power across United States hospital systems. |
| PMDA Fast-Track Submission | Streamlined Japanese approval for devices with FDA precedent accelerates market entry. |
| Remote Monitoring Software Development | Telemedicine-integrated follow-up reduces endoscopy burden and supports bundled reimbursement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with interventional gastroenterologists, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers informed demand-side dynamics. Secondary validation drew from FDA 510(k) filings, EU MDR certificate databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up stent placement volume estimates triangulated against top-down manufacturer revenue allocations.
Historical reference periods anchored the projection horizon through documented procedural growth trajectories and palliative care infrastructure expansion timelines. The analytical framework modeled segmentation across material permanence, delivery mode complexity, and end-user facility type. CAGRs derived from fitted growth curves incorporating regulatory approval lag effects and reimbursement policy shifts. Forecast inputs included nitinol supply elasticity and fellowship training program capacity constraints.
Underlying measurement precision varies by segment; self-expanding metal stent volumes carry tighter precision than biodegradable polymer adoption curves. Forecasts reflect assumptions about EU MDR implementation timelines and IDN consolidation velocity. Reimbursement recalibration for palliative versus curative-intent placement and surgical resection technique advances warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
Endoscopic Insufflators Market
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Automated Endoscopy Reprocessor Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Sigmoidoscope Market
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Video Laryngoscope Market
Endoscopy
Saudi Arabia Endoscopy Devices Market