
 Single Use Bronchoscopes Market | 2026-2036
Single Use Bronchoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Single Use Bronchoscopes Market Analytics
Digital imaging integration is tilting the single-use bronchoscope technology stack away from fiber-optic bundles toward CMOS sensor architectures with onboard LED illumination. Ambu A/S leverages its integrated manufacturing in Denmark to sustain cost leadership in high-volume flexible disposables. Boston Scientific Corporation anchors its position through channel control across US hospital purchasing networks. Olympus Corporation differentiates via optical heritage translated into premium digital single-use platforms with enhanced resolution specifications.
A single-use bronchoscope is a disposable endoscopic instrument comprising a flexible or rigid insertion tube, distal camera module, and working channel for suction or biopsy tools, manufactured from medical-grade polymers with sealed electronics to prevent fluid ingress; its primary purpose is to visualize airways and collect tissue samples without reprocessing between patients. Flexible bronchoscopes lead unit volume due to their utility across diagnostic and therapeutic procedures in critical care settings, while digital variants capture expanding margin pools as hospitals prioritize image quality for peripheral lesion navigation. Ambulatory surgery centers represent the fastest-growing end-user segment as outpatient pulmonary procedures shift away from traditional hospital infrastructure.
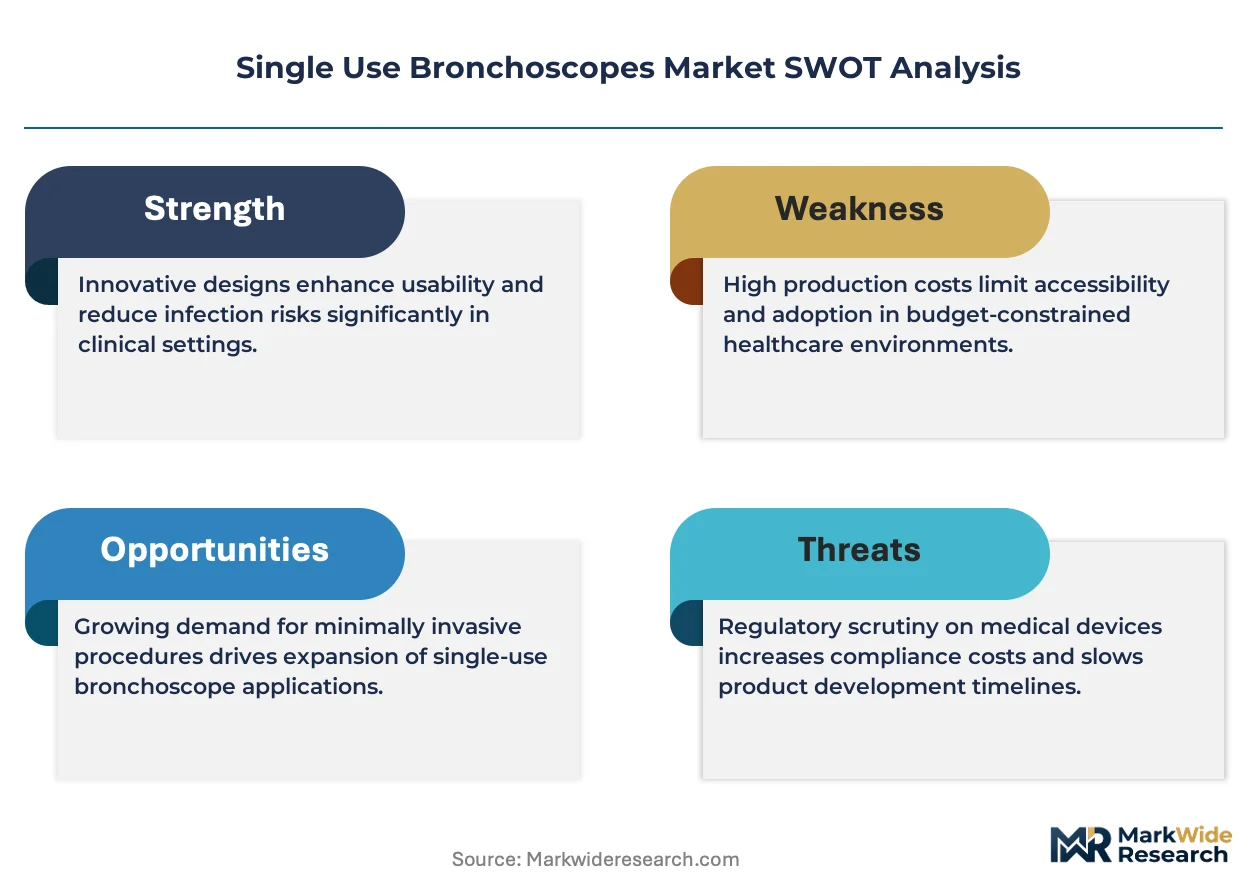
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and market access barriers for disposable bronchoscope manufacturers. The EPA regulates waste disposal volumes from single-use device accumulation, creating compliance obligations for hospital sustainability officers. Stakeholders must monitor evolving reimbursement codes for outpatient bronchoscopy procedures and their influence on ambulatory adoption economics.
Market Dynamics
The single-use bronchoscope market is pivoting on the tension between infection control mandates and waste accumulation liability, with procurement officers now weighting sterility guarantees against sustainability compliance costs.
Growth Catalysts
- EU MDR sterility mandates:Updated Class IIa certification requirements for factory-sterilized devices are accelerating hospital procurement toward disposable platforms over reprocessed alternatives.
- Immunocompromised patient volumes:Intensive care units are expanding single-use device adoption to eliminate cross-contamination risks in hematology-oncology and transplant wards.
- CMOS sensor maturation:Onboard digital imaging with LED illumination is virtualizing the traditional fiber-optic bundle architecture, enabling thinner insertion tubes and improved maneuverability.
Market Restraints
- Polymer input cost volatility:Medical-grade thermoplastic elastomer prices fluctuate with petrochemical feedstock markets, compressing margin stability for high-volume manufacturers.
- Danish manufacturing concentration:Integrated production of flexible disposables clusters in a single geography, creating geopolitical and logistics concentration risk.
- EPA waste disposal thresholds:Accumulation of single-use device volumes triggers hazardous waste classification obligations, adding compliance overhead for hospital sustainability officers.
Strategic Opportunities
- Ambulatory surgery center expansion:Outpatient pulmonary procedures are migrating from hospital infrastructure, creating demand for compact, portable disposable systems.
- Reimbursement code evolution:Updated outpatient bronchoscopy procedure codes are improving economics for same-day diagnostic interventions.
- Digital-therapeutic convergence:Integration of bronchoscopic navigation with electromagnetic tracking systems is opening precision biopsy applications in peripheral lesion targeting.
Industry Challenges
- FDA 510(k) pathway complexity:Substantial equivalence determinations for novel sensor architectures extend product development timelines and delay market entry.
- Biomedical engineering talent scarcity:Shortage of specialists fluent in both endoscopic mechanical design and CMOS electronics integration constrains R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Use Bronchoscopes Market |
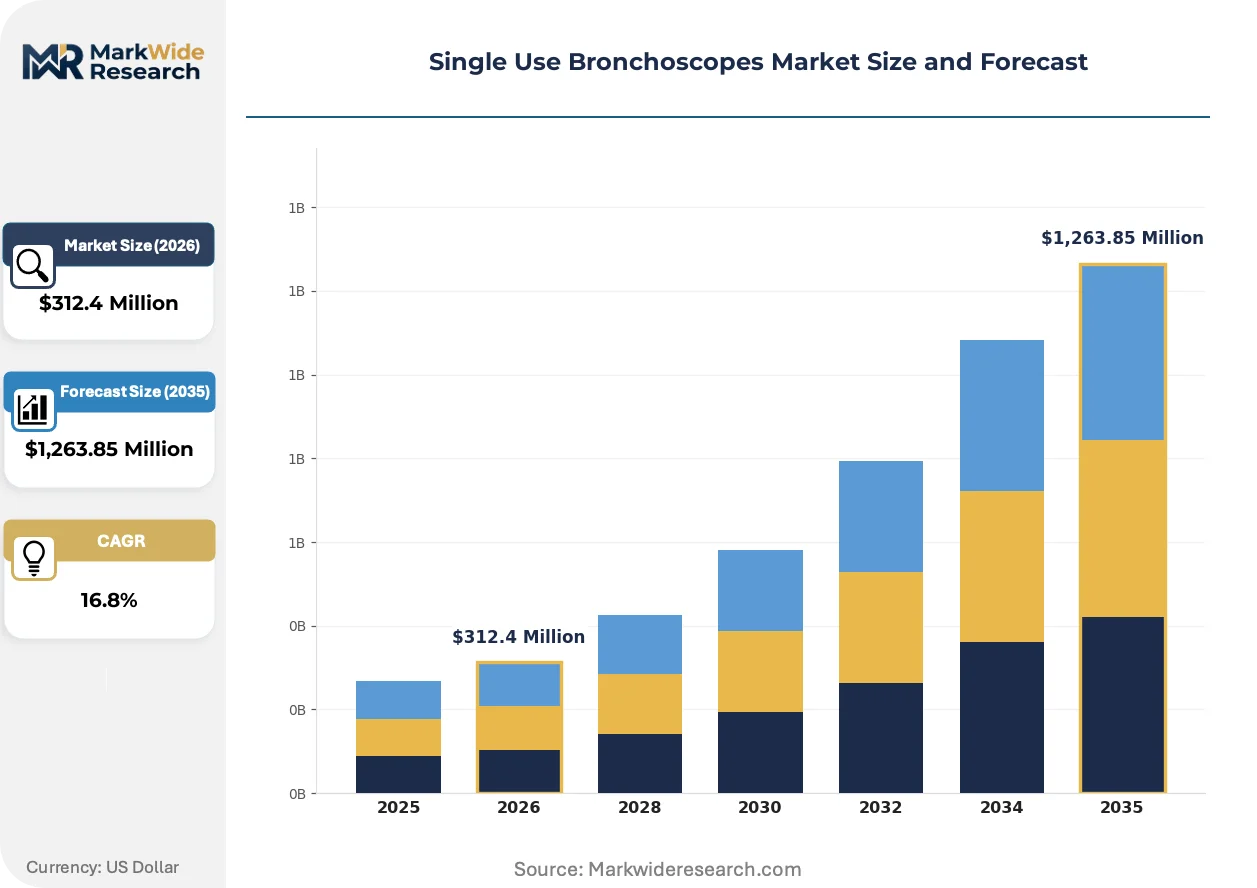
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,263.85 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Digital, Disposable End User: Hospitals, Clinics, Ambulatory Surgery Centers, Research Institutions Delivery Mode: Manual, Automated, Hybrid, Remote Application: Diagnostics, Therapeutics, Biopsy, Education |
| Companies Covered | Ambu A/S, Boston Scientific Corporation, Olympus Corporation, Fujifilm Holdings Corporation, Karl Storz GmbH & Co. KG, Pentax Medical, NeoScope Inc., Teleflex Incorporated, Smith & Nephew Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Use Bronchoscopes Market Evolving Landscape
Digital imaging architectures are virtualizing the fundamental technology stack of bronchoscopy, while regulatory frameworks and procurement behaviors recalibrate around sterility assurance and economic accountability.
CMOS-based distal sensor modules are virtualizing the traditional fiber-optic image transmission pathway in flexible bronchoscopes. Critical care departments are adopting these digital platforms for bedside procedures requiring rapid deployment. The technology is virtualizing capital equipment requirements by shifting image processing to disposable handpieces rather than dedicated processor towers.
EU MDR Class IIa certification timelines are compressing product development cycles for disposable bronchoscope manufacturers. The regulation mandates clinical evidence packages for factory-sterilized claims, raising documentation burdens. Smaller manufacturers are responding through notified body pre-submission consultations to de-risk certification delays.
Hospital purchasing networks are consolidating vendor relationships through integrated delivery network contracts that bundle single-use bronchoscopes with capital equipment service agreements. Independent ambulatory centers are resisting this consolidation by sourcing through specialty distributors with consignment inventory models. The behavioral shift is most pronounced in United States metropolitan markets where IDN penetration exceeds sixty percent of acute care beds.
Single Use Bronchoscopes Market Segmentation
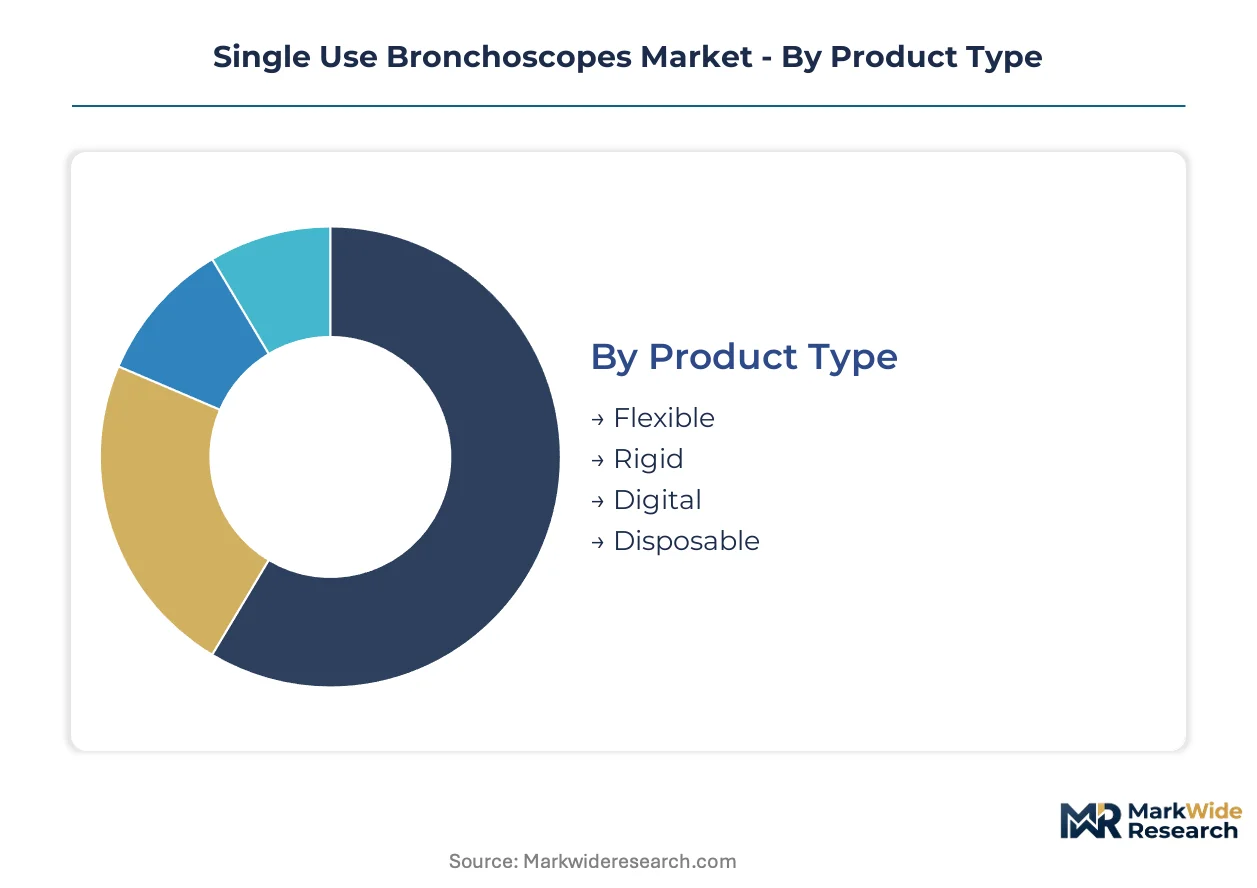
Segmentation in single-use bronchoscopes reveals how procurement priorities diverge across clinical settings. Cycle times, sterility requirements, and reimbursement economics create distinct demand profiles that manufacturers must address through targeted platform configurations.
Product Type:
Flexible bronchoscopes turn over fastest in critical care wards where bedside procedures demand immediate availability after each patient encounter; rigid and digital variants command longer replacement cycles tied to capital budgeting rhythms.
- Flexible:Polymer-based insertion tubes with steerable distal tips enable navigation through tortuous airway anatomy. Demand concentrates in United States intensive care units where hospital-acquired infection liability drives preference for guaranteed sterile deployment without reprocessing delays.
- Digital:CMOS sensor architectures with onboard LED illumination eliminate fiber-optic bundles, enabling thinner profiles and improved maneuverability. United States metropolitan hospitals prioritize these platforms for peripheral lesion navigation where image fidelity determines diagnostic yield.
- Rigid:Metal-sheathed construction suits therapeutic interventions requiring instrument stability.
- Disposable:Factory-sterilized sealed electronics prevent fluid ingress across all procedure types.
Flexible platforms anchor the volume base while digital variants gain share at the steepest rate.
End User:
Cost tier stratification separates high-volume hospital systems from capital-constrained outpatient settings, with procurement authority distributed across integrated delivery networks and independent specialty distributors.
- Hospitals:Acute care systems with dedicated pulmonary departments drive bulk purchasing through multi-year supply agreements. United States integrated delivery networks bundle single-use bronchoscopes with endoscopy suite service contracts, consolidating vendor relationships across affiliated facilities.
- Ambulatory Surgery Centers:Outpatient pulmonary procedures migrating from hospital infrastructure create demand for compact, portable systems with simplified workflow integration. These centers source through specialty distributors offering consignment inventory models to minimize capital commitment.
- Clinics:Lower procedure volumes favor flexible procurement with minimal minimum order requirements.
- Research Institutions:Academic medical centers prioritize platforms compatible with experimental navigation and sampling protocols.
Hospitals retain the dominant revenue share while ambulatory surgery centers expand most quickly as procedural migration accelerates.
Delivery Mode:
Application context determines whether manual control, automated assistance, or remote operation delivers optimal clinical outcomes, with hybrid configurations emerging at the intersection of precision and efficiency demands.
- Manual:Direct physician manipulation remains standard for diagnostic bronchoscopy where tactile feedback guides instrument passage. United States teaching hospitals maintain preference for manual platforms to preserve training pathways for interventional pulmonology fellows.
- Hybrid:Combines physician-directed navigation with automated tip stabilization or pre-programmed articulation sequences. United States community hospitals adopt these configurations to extend procedural capability without specialist-level technical expertise.
- Automated:Pre-programmed insertion pathways suit standardized screening protocols.
- Remote:Teleoperation capabilities enable specialist consultation across distributed care networks.
Manual systems anchor installed base volumes while hybrid configurations climb the fastest as workflow optimization priorities intensify.
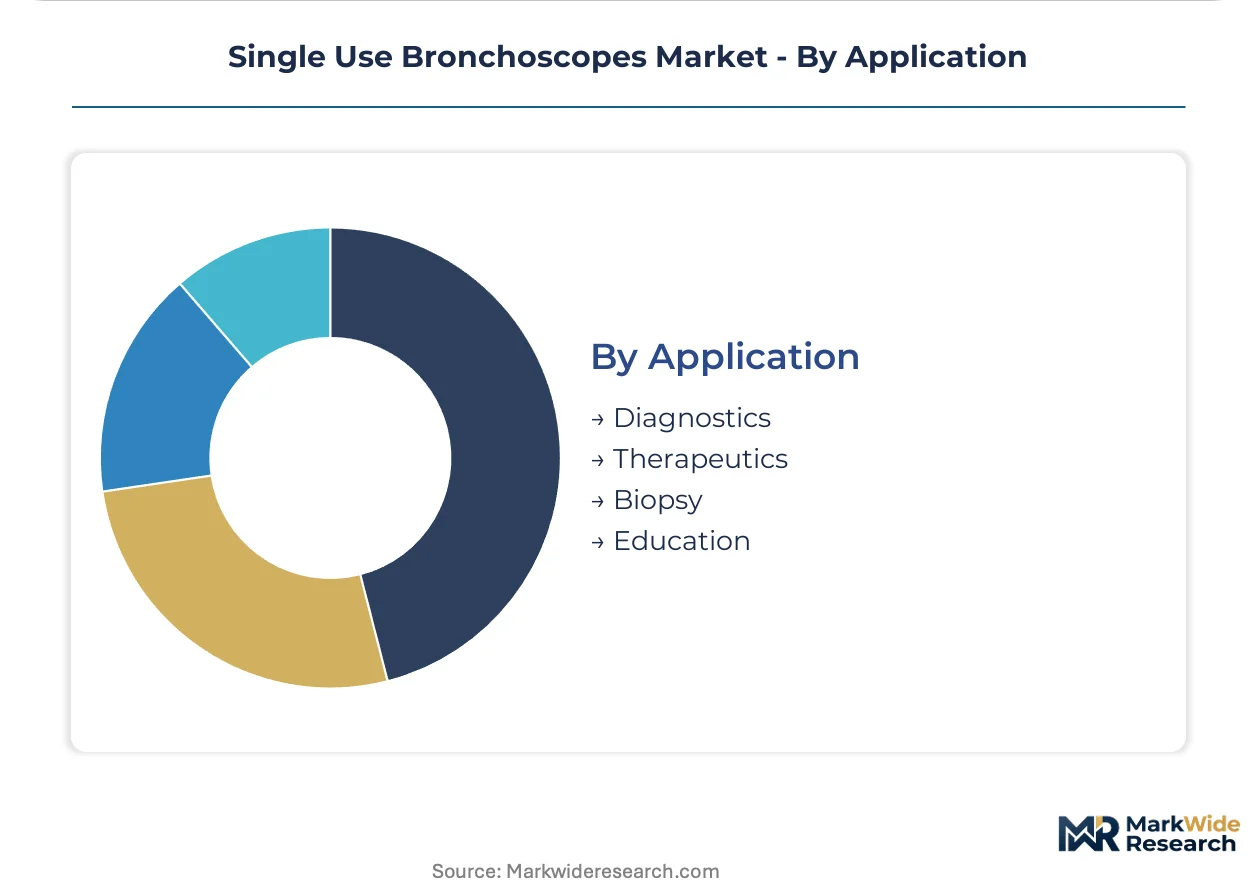
Application:
Margin structure separates high-yield therapeutic interventions from routine diagnostic screening, with reimbursement code evolution reshaping the economic viability of each use case.
- Diagnostics:Visual airway inspection and lavage sampling constitute the highest procedure frequency across all settings. United States outpatient reimbursement codes for diagnostic bronchoscopy have improved economics for same-day interventions, expanding addressable volume.
- Biopsy:Tissue acquisition for histopathological analysis demands platforms with working channel diameter and suction capability matched to sampling tool requirements. United States lung cancer screening program expansion drives biopsy procedure growth in community hospital settings.
- Therapeutics:Foreign body removal, stent deployment, and lesion ablation command premium platform specifications.
- Education:Training programs require cost-effective platforms with standardized handling characteristics.
Diagnostic applications anchor procedure volumes while biopsy platforms expand most quickly as early detection programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of single-use bronchoscopes concentrate in Danish manufacturing clusters serving United States hospital systems, while import dependency shapes procurement strategies across European and Asian markets. Trade balances reflect divergent regulatory timelines and sterility certification requirements.
United States
Hospital-acquired infection liability costs drive premium willingness for guaranteed sterile bronchoscopy in intensive care units. FDA 510(k) clearance pathways shape product development timelines for disposable platform manufacturers. Metropolitan integrated delivery networks in Chicago, Houston, and Atlanta consolidate procurement through multi-year supply agreements.
Germany
EU MDR Class IIa certification requirements accelerate hospital procurement toward factory-sterilized disposable platforms over reprocessed alternatives. The country's national medical device regulator enforces stringent clinical evidence packages for sterility claims. Industrial concentration in Baden-Württemberg hosts precision polymer processing for flexible insertion tube components.
Denmark
Integrated manufacturing of flexible disposables generates concentrated export supply serving North American and European hospital networks. Danish regulatory alignment with EU MDR streamlines certification for factory-sterilized platforms. Copenhagen-region production facilities sustain cost leadership in high-volume disposable architectures.
Japan
Optical heritage from fiber-optic endoscopy transitions toward CMOS sensor architectures in domestic hospital procurement. PMDA regulatory frameworks govern market access for novel digital imaging platforms. Manufacturing clusters in Nagoya and Osaka prefectures specialize in miniaturized distal camera module assembly.
United Kingdom
NHS procurement frameworks prioritize infection control mandates in critical care wards with immunocompromised patient populations. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating parallel certification requirements. London and Southeast England acute care systems pilot ambulatory surgery center bronchoscopy migration programs.
Single Use Bronchoscopes Market Competitive Landscape
On the supply side, the industry is consolidating around integrated manufacturing capabilities and channel control across hospital purchasing networks. Three strategic archetypes dominate: vertically integrated polymer processors with captive component supply, diversified medical device conglomerates leveraging endoscopy suite service contracts, and specialized disposable platform innovators focusing on CMOS sensor miniaturization. Competitive moves center on capacity expansion in Danish manufacturing clusters and strategic partnerships with integrated delivery networks for multi-year procurement lock-in.
Within the integrated manufacturing tier, Ambu A/S and Karl Storz GmbH & Co. KG exemplify divergent approaches to supply chain configuration. Among diversified conglomerates, Olympus Corporation and Fujifilm Holdings Corporation occupy positions translating optical heritage into digital single-use platforms. Boston Scientific Corporation represents the channel-control archetype through hospital purchasing network penetration. NeoScope Inc. sits within the specialized innovation tier focused on compact disposable architectures for ambulatory settings.
| Leading Market Players |
|---|
| Ambu A/S |
| Boston Scientific Corporation |
| Olympus Corporation |
| Fujifilm Holdings Corporation |
| Karl Storz GmbH & Co. KG |
| Pentax Medical |
| NeoScope Inc. |
| Teleflex Incorporated |
| Smith & Nephew Inc. |
| Others |
Value Network & Pricing Analysis
Trans-Atlantic freight corridors from Copenhagen to Port Newark absorb polymer cost volatility and concentrate supply chain leverage, amplifying price differentiation between CMOS-equipped digital platforms and legacy fiber-optic architectures across United States hospital procurement networks.
Pricing Analysis
Next-generation CMOS sensor platforms command substantial premiums over prior-generation fiber-optic bundles and economy-grade polymer-only devices. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared digital systems with electromagnetic navigation compatibility from basic flexible scopes and rigid therapeutic platforms. Cost compression in standard-tier flexible scopes is intensifying because Danish manufacturing concentration limits alternative sourcing for high-volume disposables. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while metropolitan integrated delivery networks prioritize sterility guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between Denmark and the United States dominates supply chain risk assessment for flexible disposable manufacturers. Production gravity centers on Denmark for integrated polymer processing and final assembly, with Japan contributing miniaturized CMOS distal camera modules and Germany supplying precision thermoplastic elastomer feedstock. Raw material dependencies include medical-grade polycarbonate resins, platinum-cured silicone elastomers, and gold-plated electrical contacts for sealed electronics. Single-source vulnerability concentrates in Copenhagen-region cleanroom facilities capable of CMOS-LED integration. Distribution runs through integrated delivery network consignment agreements and specialty medical device distributors serving independent ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as outpatient procedural migration splinters historically consolidated hospital procurement, creating specialized niches for compact digital platforms and regional service models.
For Market Incumbents: Pre-empt emerging entrant encroachment in ambulatory surgery centers by accelerating compact CMOS platform development and securing exclusive GPO contracts before reimbursement code stabilization. Channel control through multi-year integrated delivery network agreements remains the critical defensive lever against specialized disposable innovators.
For New Entrants and Emerging Players: Build out regional manufacturing partnerships outside Denmark to circumvent logistics concentration risk and capture ambulatory surgery center demand through consignment inventory models. United States metropolitan outpatient markets offer the most penetrable entry point given resistance to incumbent bundling practices.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized innovators with CMOS miniaturization capabilities over diversified conglomerates with legacy fiber-optic exposure. Long-term viability hinges on electromagnetic navigation integration and software-enabled procedure support. Monitor FDA 510(k) clearance velocity for novel sensor architectures as inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Platform Miniaturization | Thinner insertion tubes expand peripheral lesion navigation capability in community hospital settings. |
| Hospital System Partnership | Exclusive supply agreements with integrated delivery networks lock out competing disposable platforms. |
| Reimbursement Strategy | Outpatient bronchoscopy code optimization improves ambulatory surgery center procedure economics. |
| CE Marking Pathway | EU MDR Class IIa certification accelerates factory-sterilized platform adoption in German hospitals. |
| Software Companion Development | Electromagnetic tracking integration enables precision biopsy applications in lung cancer screening. |
Research Methodology
The analysis maps flexible, digital, and rigid disposable sub-sectors, each validated through procurement directors at integrated delivery networks, biomedical engineers specializing in endoscopic design, GPO contracts managers, and regulatory affairs leads at notified bodies. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR certification databases, hospital procurement records, and CMS reimbursement code updates. Bottom-up unit volume estimates triangulated against top-down market value reconstruction across product type, end user, and application dimensions.
Fixed assumptions held regulatory pathway timelines and polymer feedstock cost trajectories constant across the projection horizon, while varying ambulatory procedural migration rates and integrated delivery network consolidation patterns. Segmentation modeling incorporated product architecture, clinical setting, delivery mode sophistication, and regional certification cluster. CAGRs derived from logistic adoption curves fitted to sterilization mandate implementation schedules and CMOS sensor cost decline trajectories. Industry-specific inputs included hospital-acquired infection liability cost estimates and outpatient reimbursement code evolution.
Practitioners should monitor EU MDR certification backlog resolution and EPA waste disposal threshold enforcement for early signals of supply constraint or compliance cost escalation. Forecasts reflect assumptions about sterility mandate continuity and polymer cost stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Neuroendoscopy Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
United Kingdom Endoscopy Devices Market
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
Chip-On-The-Tip Endoscopes Market