
 Europe Defense Aircraft Aviation Fuel Market | 2026-2036
Europe Defense Aircraft Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Defense Aircraft Aviation Fuel Market Foresight
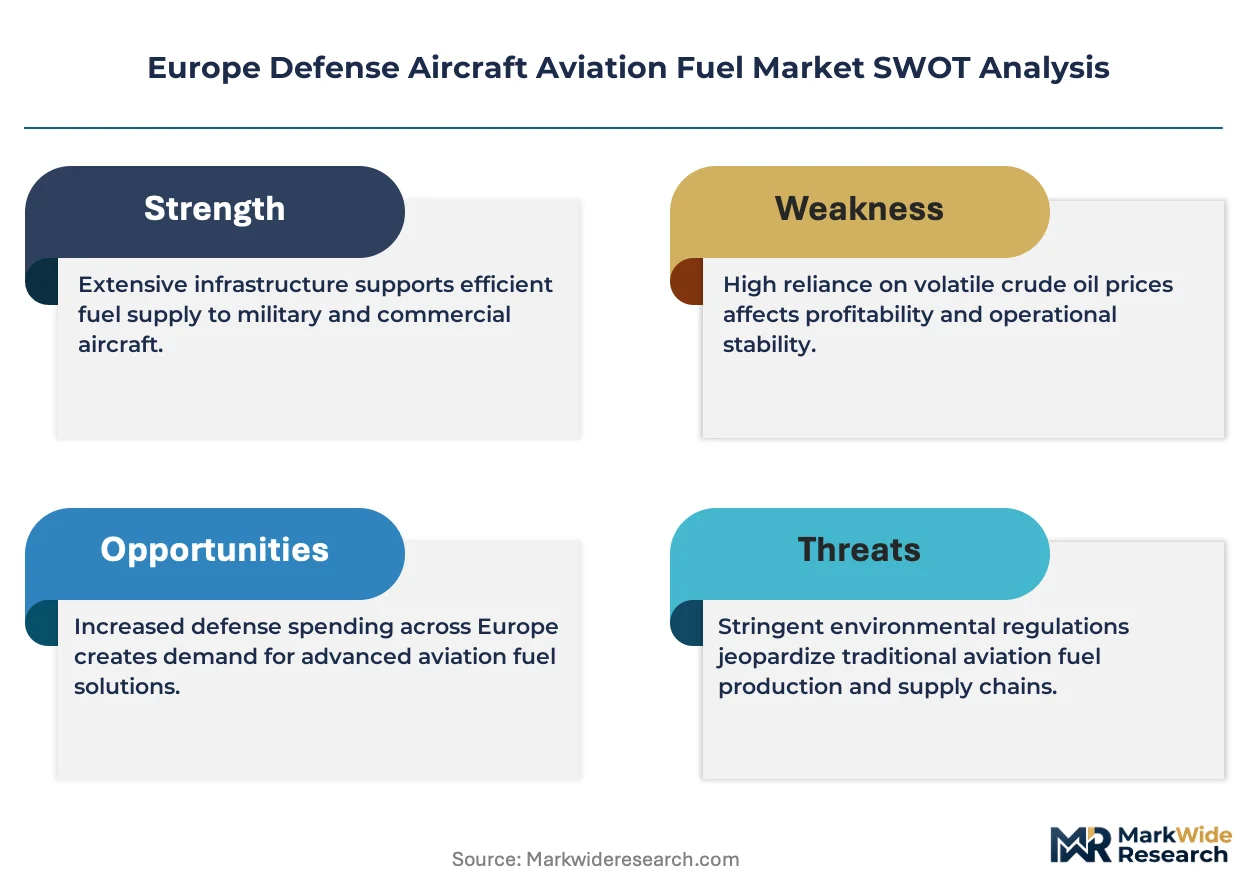
Aftermarket fuel logistics and bulk storage contracts is rewriting margin distribution across the European defense aviation supply chain. TotalEnergies SE leverages its integrated refining network to secure NATO-aligned supply agreements. Shell plc anchors its position through dedicated military fuel terminals at strategic airbases. Neste Oyj differentiates via renewable diesel co-processing capabilities that align with emerging defense decarbonization targets.
Europe Defense Aircraft Aviation Fuel encompasses refined petroleum products meeting NATO-standard specifications including JP-8 with freeze point below minus 47 degrees Celsius and flash point minimum of 38 degrees Celsius, formulated to ensure turbine engine performance across extreme operational altitudes and temperatures. The fuel type dimension shows Jet A-1 dominating commercial-military crossover procurement while JP-8 retains primacy in tactical fighter applications. Combat aircraft command the largest application share by volume, though surveillance platforms are gaining traction as unmanned systems expand endurance requirements.
EU Green Deal frameworks and the F-Gas Regulation constrain conventional kerosene pathways while EASA certification standards govern alternative fuel approvals for military airworthiness. The ReFuelEU Aviation mandate progressively raises sustainable aviation fuel blending obligations, compelling defense procurement agencies to renegotiate long-term supply contracts. Stakeholders must monitor how national military exemptions from civilian SAF mandates evolve across European Union member states.
Market Dynamics
The EU Green Deal and ReFuelEU Aviation mandates are forcing defense ministries across NATO allies to renegotiate long-term fuel supply contracts while evaluating sustainable aviation fuel pathways for tactical fighter applications.
Growth Catalysts
- Fleet Modernization:Fighter replacement programs in France, the United Kingdom, and Germany are accelerating volume commitments for NATO-standard JP-8 and Jet A-1 specifications.
- ReFuelEU Aviation:The mandate's progressive blending obligations compel defense procurement agencies to integrate sustainable aviation fuel into military supply chains ahead of civilian compliance deadlines.
- Unmanned Systems Expansion:Surveillance platforms and combat drones are extending endurance requirements, creating incremental demand for high-performance turbine fuels.
Market Restraints
- Crude Price Volatility:Jet fuel refining margins remain exposed to Brent crude fluctuations, compressing budget predictability for defense ministries operating multi-year procurement frameworks.
- Refining Concentration:Northwest European refining capacity consolidation leaves military buyers dependent on a narrowing supplier base for specialized kerosene cuts.
- SAF Production Bottlenecks:Hydroprocessed esters and fatty acids (HEFA) pathway limitations constrain near-term availability of drop-in sustainable fuels meeting NATO freeze-point specifications.
Strategic Opportunities
- Poland and Baltics:Eastern flank NATO posture enhancements are driving new bulk storage infrastructure and forward logistics contracts for expeditionary air operations.
- Renewable Diesel Co-processing:Neste Oyj's proprietary technology enables existing refineries to produce military-grade sustainable fuels without dedicated standalone facilities.
- Digital Fuel Tracking:Blockchain-verified supply chain documentation aligns with emerging EU Defense Procurement Directive transparency requirements.
Industry Challenges
- SAF Certification Timeline:EASA military airworthiness approvals for alternative fuels lag commercial aviation pathways, delaying operational deployment.
- Interoperability Standards:Variations in national military exemptions from civilian SAF mandates complicate multinational coalition fuel logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Defense Aircraft Aviation Fuel Market |
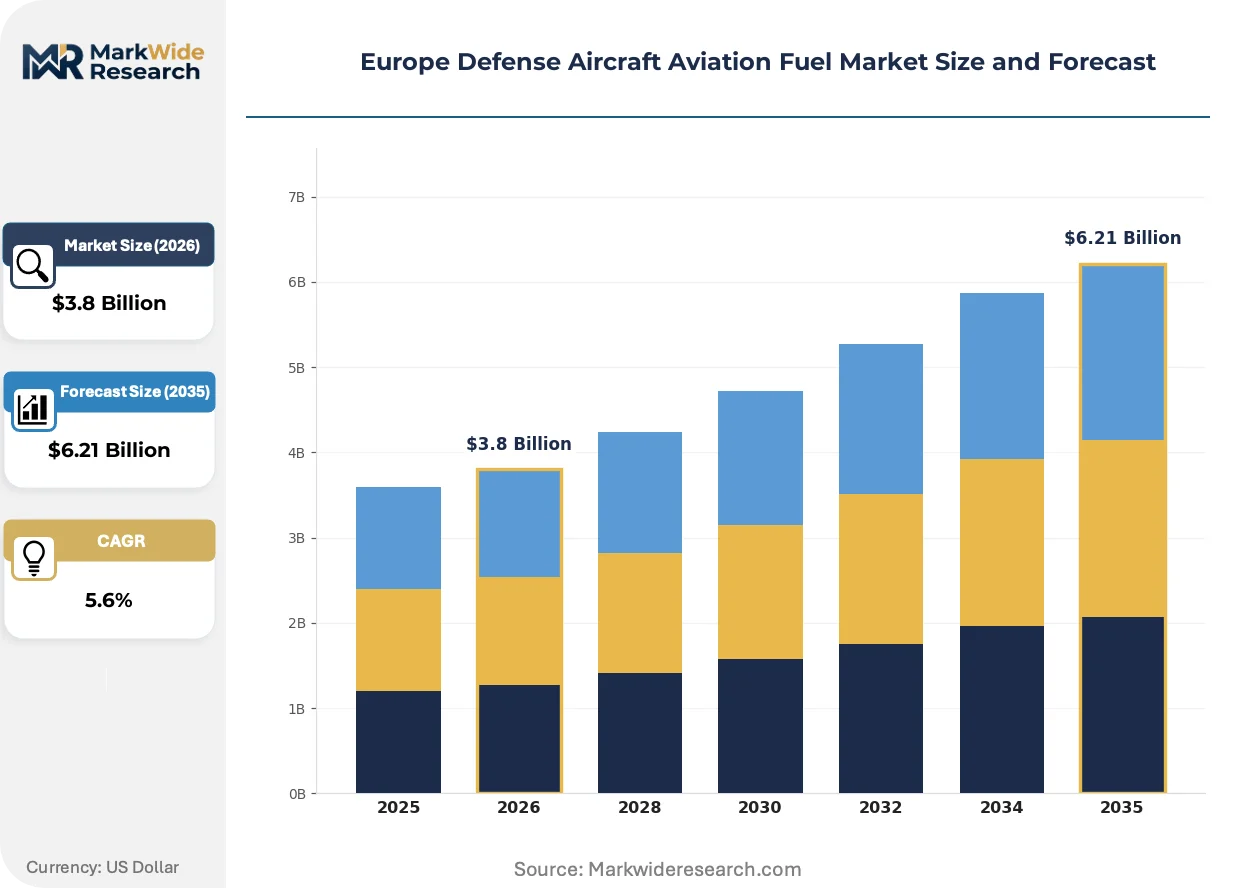
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: JP-5, JP-8, Jet A-1, RP-1 End User: Military Aviation, Air Force, Navy, Defense Contractors Distribution Channel: Direct Sales, Partnerships, Distributors, Online Retail Application: Combat Aircraft, Transport Aircraft, Surveillance Aircraft, Training Aircraft |
| Companies Covered | World Fuel Services Corp, TotalEnergies SE, Shell plc, BP plc, Eni SpA, Coryton Advanced Fuels Ltd, Neste Oyj, Repsol SA, Exxon Mobil Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Defense Aircraft Aviation Fuel Market Shifts & Advancements
Digital supply chain architectures and alternative fuel certification pathways are compressing traditional procurement cycles while reconfiguring how defense ministries manage fuel security and sustainability trade-offs.
Synthetic paraffinic kerosene (SPK) production via Fischer-Tropsch synthesis is virtualizing conventional crude-dependent refining for military applications. Defense procurement agencies in Sweden and Finland are piloting SPK blends for cold-weather operations. This virtualization is compressing the link between fuel security and geographic crude sourcing.
EU F-Gas Regulation constraints on fluorinated greenhouse gases are accelerating the phase-out of legacy fire suppression systems in fuel storage facilities. Military airbase operators must retrofit bulk storage terminals with alternative inerting technologies. German and French defense infrastructure managers are absorbing the highest compliance costs due to aging hardened aircraft shelter networks.
Long-term offtake agreements are displacing spot market exposure for defense fuel buyers. Ministries in Italy and Spain are locking in ten-year supply contracts with integrated energy majors to insulate budgets from refining margin volatility. This pattern is most visible in southern European markets where budget predictability outweighs price optimization in procurement criteria.
Europe Defense Aircraft Aviation Fuel Market Segmentation
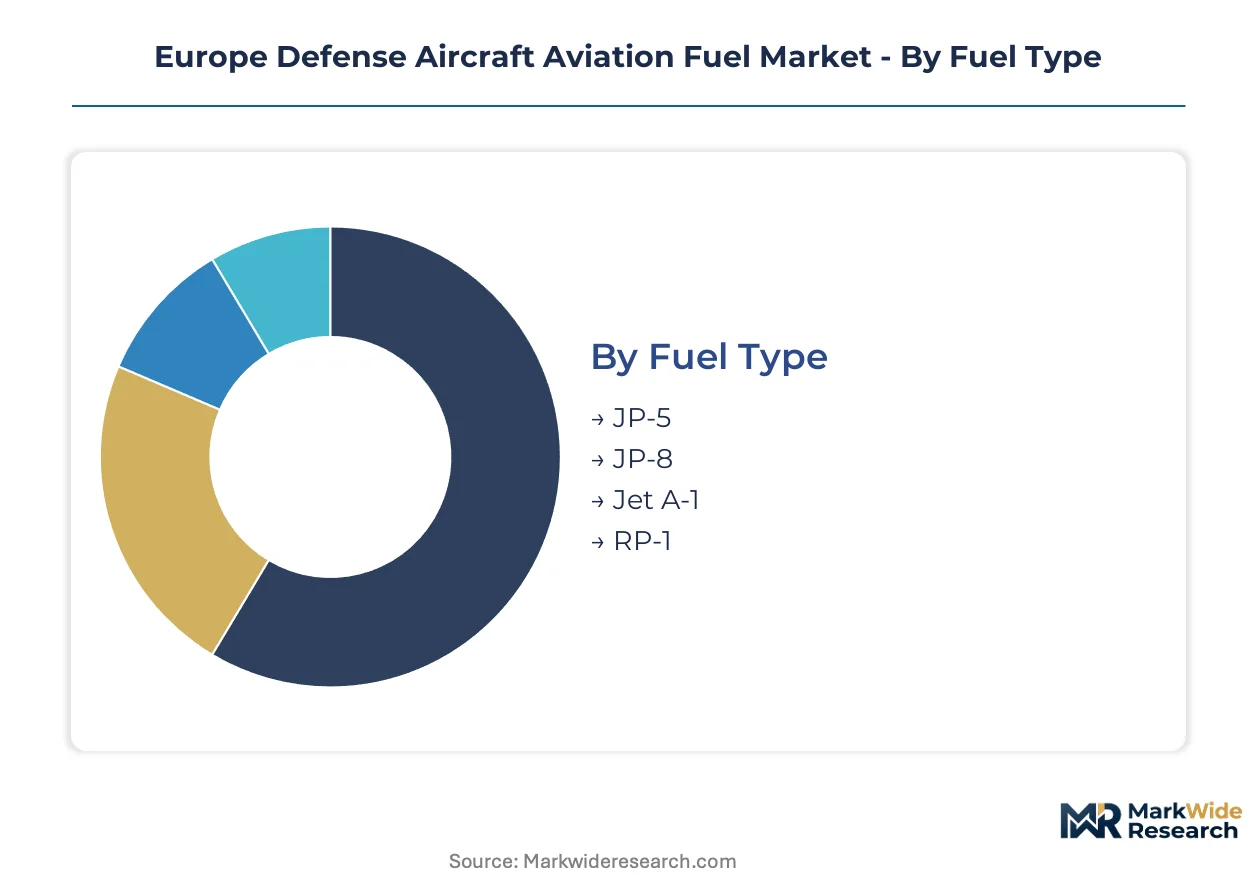
Defense aviation fuel segmentation reveals how NATO operational requirements, procurement centralization, and sustainability mandates reshape demand patterns across European military aviation. Fuel specifications, end-user hierarchies, and application-specific performance thresholds determine contract structures and supplier qualification pathways.
Fuel Type:
Operational altitude ranges and turbine engine compatibility requirements define the fuel type spectrum across European defense procurement.
- JP-8:NATO's single-fuel battlefield standard combines kerosene base stocks with corrosion inhibitors and icing inhibitors. French Rafale squadrons and German Eurofighter wings in Bavaria drive concentrated demand for tactical fighter applications requiring freeze points below minus 47 degrees Celsius.
- Jet A-1:Commercial-military crossover procurement dominates transport and tanker fleets. Royal Air Force Voyager refueling operations at Brize Norton anchor United Kingdom volume commitments for this civil aviation-certified grade with NATO additive injection capabilities.
- JP-5:Flash point specifications above 60 degrees Celsius serve carrier-based naval aviation. Italian Navy Harrier operations from the Cavour and future F-35B deployments sustain Mediterranean demand for this high-safety kerosene variant.
- RP-1:Rocket propulsion kerosene with low sulfur and aromatic content supports missile test programs. Swedish Space Corporation operations at Esrange and French DGA missile trials represent specialized aerospace applications.
Established volume favors JP-8; emerging adoption favors Jet A-1 as dual-use procurement rationalizes supply chains.
End User:
Budget authority concentration and operational tempo differentiate procurement patterns across European defense hierarchies.
- Military Aviation:Unified air commands in Spain and Italy consolidate fuel purchasing through national defense logistics agencies. Joint procurement frameworks aggregate fighter, transport, and rotary-wing demand under single contracting authorities.
- Air Force:Tactical fighter wings and strategic airlift squadrons represent the dominant volume concentration. Polish F-16 and future F-35A programs accelerate consumption as eastern flank NATO posture strengthens.
- Navy:Carrier aviation and maritime patrol requirements sustain specialized high-flash-point demand. Royal Netherlands Navy helicopter operations and French naval aviation from Landivisiau anchor North Sea and Atlantic procurement.
- Defense Contractors:Flight test programs and delivery operations for Airbus Defence and Space, Dassault Aviation, and Leonardo generate incremental demand outside military direct procurement channels.
Procurement consolidation favors Military Aviation; operational specificity favors Air Force for volume concentration.
Distribution Channel:
Supply security requirements and contract flexibility shape channel selection across European defense ministries.
- Direct Sales:Integrated energy majors contract directly with national defense fuel agencies. TotalEnergies SE maintains direct supply relationships with the French Direction du Ravitaillement en Carburant.
- Partnerships:Strategic alliances between refiners and military logistics commands secure dedicated storage capacity. Shell plc's partnerships with the United Kingdom Ministry of Defence anchor bulk terminal access.
- Distributors:Regional fuel specialists serve expeditionary and training operations requiring rapid deployment flexibility. Baltic states leverage distributors for forward airbase resupply.
- Online Retail:Digital procurement platforms support small-volume specialty fuel orders and additive procurement. This channel remains marginal for bulk aviation kerosene.
Security prioritization favors Direct Sales; operational flexibility favors Partnerships for integrated infrastructure.
Application:
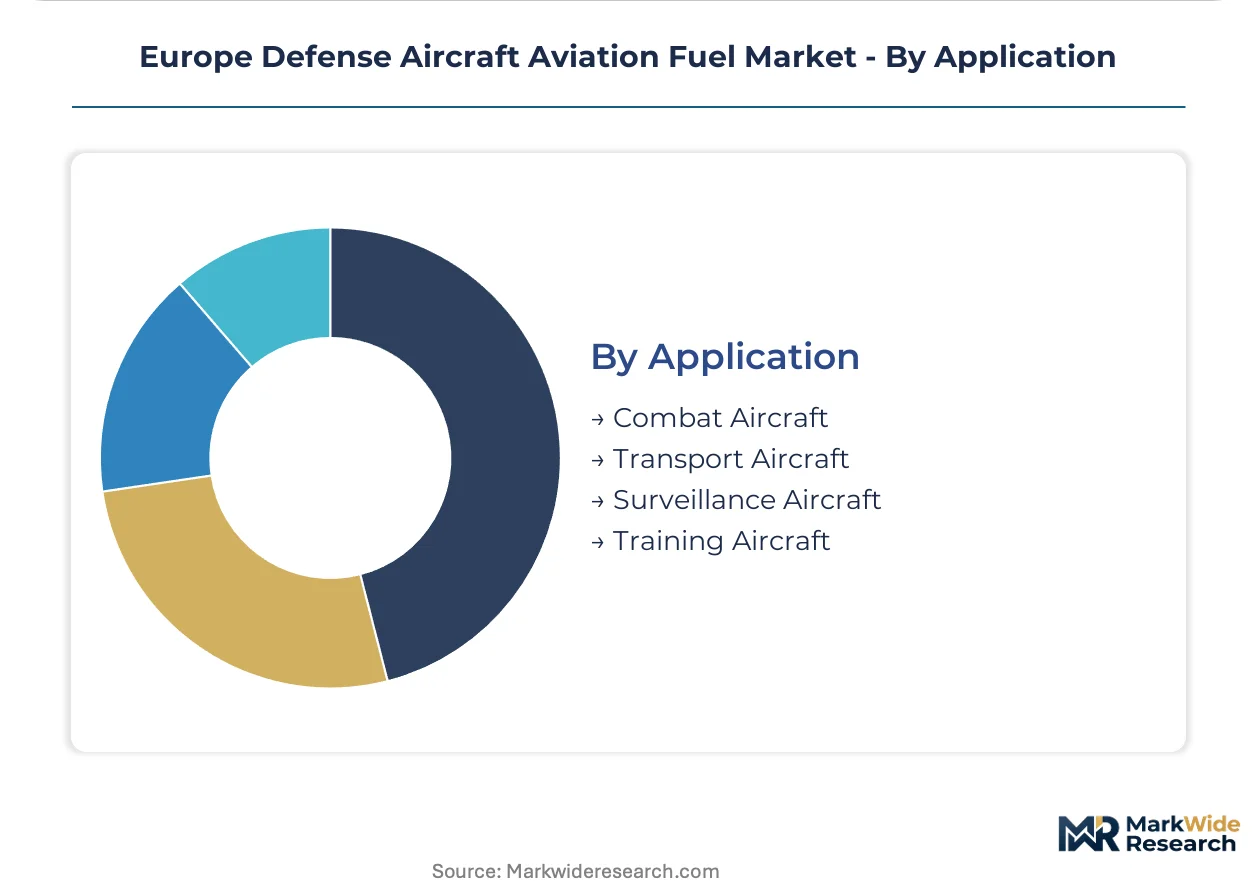
Mission profiles and endurance requirements segment demand across aircraft operational categories.
- Combat Aircraft:Afterburner-capable turbofans in fighter applications consume the highest specific fuel rates. Eurofighter Typhoon and Rafale operations sustain the dominant volume share across French and German airbases.
- Surveillance Aircraft:Unmanned systems and manned ISR platforms extend endurance requirements for high-altitude operations. NATO Alliance Ground Surveillance Global Hawk deployments in Sigonella drive incremental demand growth.
- Transport Aircraft:Strategic airlift and tactical transport fleets operate on Jet A-1 with military additive packages. Airbus A400M Atlas deliveries to multiple European air forces standardize procurement specifications.
- Training Aircraft:Jet trainer fleets consume lower volumes with less stringent freeze-point requirements. Pilatus PC-21 operations in Switzerland and France represent regional procurement concentration.
Operational intensity favors Combat Aircraft; endurance expansion favors Surveillance Aircraft for steepest demand trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense fuel procurement elasticity varies sharply across European NATO members. Eastern flank ministries prioritize supply security over unit cost, while Western European buyers leverage scale for price optimization. This divergence is reshaping contract structures and supplier relationships.
France
Rafale fighter fleet expansion and nuclear deterrence patrols sustain high-volume JP-8 demand. Direction du Ravitaillement en Carburant coordinates centralized procurement under EU Green Deal compliance frameworks. Toulouse-Blagnac aerospace cluster anchors military fuel logistics coordination for southwestern airbases.
Germany
Eurofighter Typhoon modernization and NATO air policing rotations drive steady consumption growth. KBA oversees transport fuel quality standards intersecting with military specifications. Bavarian airbases around Neuburg and Fürstenfeldbruck concentrate tactical fighter fueling infrastructure.
United Kingdom
Voyager tanker operations and F-35B Lightning deployments sustain dual Jet A-1 and JP-8 procurement. Ministry of Defence long-term supply agreements insulate budgets from refining margin volatility. RAF Brize Norton anchors strategic airlift fuel logistics for expeditionary operations.
Poland
F-16 Block 52+ sustainment and pending F-35A deliveries accelerate volume commitments on NATO's eastern flank. National defense fuel agency contracts prioritize supply security over cost minimization. Poznań-Ławica and Łask airbases concentrate forward fuel storage for rapid deployment readiness.
Italy
A400M Atlas deliveries and naval aviation from the Cavour carrier sustain diversified fuel demand. Difesa Servizi consolidates multi-service procurement under ten-year supply frameworks. Grottaglie naval air station anchors Mediterranean high-flash-point fuel distribution.
Europe Defense Aircraft Aviation Fuel Market Competitive Landscape
Capability concentration sits with integrated energy majors possessing NATO-aligned refining networks; scale advantage sits with specialized military fuel distributors with expeditionary logistics expertise. The vendor base stratifies into three tiers: multinational refiners with dedicated military terminals, regional distributors serving forward airbases, and renewable fuel specialists developing drop-in sustainable alternatives. Dominant competitive moves include long-term offtake agreements displacing spot market exposure and strategic partnerships securing bulk storage capacity at hardened airfield facilities.
Within the integrated energy major tier, TotalEnergies SE, Shell plc, and BP plc exemplify the refining-scale archetype. These London- and Paris-headquartered entities occupy positions anchored by NATO-standard specification expertise and dedicated military terminal networks. Their representation of the consolidated supplier segment contrasts with Neste Oyj's position exemplifying the renewable transition archetype through proprietary co-processing capabilities.
| Leading Market Players |
|---|
| World Fuel Services Corp |
| TotalEnergies SE |
| Shell plc |
| BP plc |
| Eni SpA |
| Coryton Advanced Fuels Ltd |
| Neste Oyj |
| Repsol SA |
| Exxon Mobil Corporation |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors anchor cost dynamics for NATO-standard fuel deliveries, concentrating pricing power among integrated refiners while downstream buyers face tiered premiums for freeze-point-certified kerosene grades.
Pricing Analysis
Aftermarket fuel logistics contracts drive lifetime value through ten-year bulk storage agreements that bundle terminal access with additive injection services. Contract-based long-term offtake dominates procurement as defense ministries trade price optimization for budget predictability. Price differentiation rests on NATO certification grade and volume scale, with tactical fighter squadrons absorbing premiums for JP-8 freeze-point guarantees. Cost compression in spot-exposed procurement tiers is intensifying because refining margin volatility compresses discretionary budget flexibility. Expeditionary air operations show highest price sensitivity; nuclear deterrence patrol commands demonstrate lowest.
Supply Chain Analysis
EU dual-use export controls on refining catalysts and corrosion inhibitor technologies constrain technology transfer to non-NATO aligned facilities, tightening supplier qualification pathways. Geographic supply concentrates in the Netherlands, Belgium, and Germany where Northwest European refining hubs process Urals-replacement crude slates. Raw material dependencies include kerosene base stocks, fuel system icing inhibitors, and static dissipator additives. Single-source vulnerability around specialized military additive packages threatens operational readiness. Distribution runs through dedicated military terminals at hardened airfields, with forward logistics contracts serving eastern flank expeditionary requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery as fighter fleet modernization programs across NATO allies accelerate volume commitments and renegotiate long-term supply frameworks.
For Market Incumbents: Pre-empt renewable fuel certification gaps by securing EASA military airworthiness approvals for synthetic paraffinic kerosene blends ahead of commercial aviation pathways. Deepen backward integration into biofeedstock sourcing to hedge HEFA pathway bottlenecks threatening drop-in sustainable fuel availability. Lock in exclusive terminal partnerships at Polish and Baltic forward airbases before infrastructure investment cycles peak. For New Entrants and Emerging Players: Eastern flank bulk storage underpenetration offers white-space access as NATO posture enhancements outpace incumbent infrastructure deployment. Target surveillance aircraft fuel logistics where unmanned systems expansion creates incremental demand without incumbent contract lock-in. Pursue digital fuel tracking certification to align with EU Defense Procurement Directive transparency requirements as a differentiated entry credential. For Investors and Strategic Acquirers: Renewable diesel co-processing specialists with proprietary military-grade qualification pathways represent the most defensible acquisition archetype for sustained margin capture. Long-term viability hinges on national military exemption durability from civilian SAF mandates across EU member states. Monitor EASA alternative fuel certification timeline acceleration as the critical inflection signal for operational deployment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Italian and Spanish defense ministries lock in ten-year contracts insulating budgets from refining margin volatility. |
| Backward Integration | Neste Oyj's proprietary co-processing technology enables existing refineries to produce military-grade sustainable fuels without standalone facilities. |
| Capacity Expansion | Polish and Baltic bulk storage infrastructure addresses eastern flank NATO posture enhancements for expeditionary air operations. |
| Green Certification Program | ReFuelEU Aviation blending obligations compel defense procurement agencies to renegotiate contracts ahead of civilian compliance deadlines. |
| Joint Venture | Strategic alliances between refiners and military logistics commands secure dedicated storage capacity at strategic airbases. |
Research Methodology
A standing panel of defense fuel procurement officers, refinery operations managers, NATO logistics commanders, and military airbase infrastructure directors provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Green Deal implementation reports, EASA certification bulletins, ReFuelEU Aviation mandate tracking databases, and national defense ministry budget disclosures. Bottom-up volume aggregation across fighter fleet modernization programs triangulated against top-down NATO fuel demand projections.
Scenario-bracketing framed low, baseline, and high cases across the analysis window, with CAGRs derived from segment-level volume trajectories for combat aircraft, surveillance platforms, transport fleets, and training aircraft. Fuel type specifications, end-user procurement consolidation patterns, and distribution channel security requirements anchored segmentation modeling. Brent crude price band assumptions and SAF production pathway maturity curves fed industry-specific forecast inputs.
Practitioners should monitor EASA military airworthiness approval acceleration, national SAF mandate exemption evolution, and eastern flank infrastructure investment cycles for early signals of forecast revision. Material shifts in NATO operational tempo, EU F-Gas Regulation enforcement stringency, or breakthrough synthetic fuel production economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
India LNG Market
Fuels
LNG Fueling Station Market
Fuels
Global Fuel Ethanol Market
Fuels
Aviation Fuel Market
Fuels
High Octane Racing Fuel Market
Fuels
Gasoline Market
Fuels
Mobile Gas Pumping System Market
Fuels
China LNG Bunkering Market
Fuels
Oil Dispensing Stations Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Germany Bunker Fuel Market
Fuels
Europe Aviation Fuel Market
Fuels
North America Aviation Fuel Market
Fuels
Gas Pooling Mechanism Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
Global Gas Treatment Market