
 Gas Pooling Mechanism Market | 2026-2036
Gas Pooling Mechanism Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Pooling Mechanism Market Foresight
Multi-source aggregation from domestic fields and LNG terminals is hardening as the dominant procurement pattern for Indian gas utilities. Saudi Aramco leverages its upstream scale to supply term LNG cargoes into pooled tenders. Gazprom anchors long-term contract volumes that feed into national balancing pools. TotalEnergies competes through flexible portfolio positions across Atlantic and Pacific supply basins.
A gas pooling mechanism technically denotes a regulatory-commercial arrangement where gas from multiple supply sources—domestic fields, spot LNG, and term imports—gets aggregated at a uniform delivered price to specific consumer categories, with physical balancing managed through pipeline nomination systems and storage buffer capacity. Its primary purpose is to revive stranded gas-based power and fertilizer assets by lowering feedstock cost volatility. The service type dimension shows balancing and transportation functions capturing the dominant margin pools, while trading services remain nascent. Smart metering and data analytics within the technology segment are displacing manual allocation systems as utilities seek real-time visibility into pool injections and withdrawals.
India's Petroleum and Natural Gas Regulatory Board mandates pipeline common carrier access and unified tariffs, while the Ministry of Petroleum and Natural Gas administers the gas pooling mechanism through administrative price orders for fertilizer and power sectors. These frameworks determine which plants qualify for subsidized pooled gas and how domestic and imported molecules commingle. Stakeholders must track how carbon border adjustments in key export markets reshape the cost competitiveness of gas-intensive Indian manufacturing.
Market Dynamics
The Petroleum and Natural Gas Regulatory Board's unified tariff regulations are compressing price spreads between domestic gas and imported LNG, forcing aggregators to rebuild margin structures around balancing services rather than molecule arbitrage.
Growth Catalysts
- Stranded asset revival mandates:India's administrative price orders for fertilizer and power sectors qualify specific plants for subsidized pooled gas, expanding addressable demand for aggregation services.
- Smart metering infrastructure:Real-time visibility into pool injections and withdrawals is displacing manual allocation systems, enabling utilities to optimize nomination cycles and reduce imbalance penalties.
- Gujarat industrial corridor concentration:Fertilizer manufacturers and ceramic clusters in this state anchor offtake volumes, creating density economies for pipeline operators and storage providers.
Market Restraints
- LNG price volatility:Spot cargo differentials against term contracts create margin compression when pooled prices must be held stable for qualified consumers.
- Pipeline access bottlenecks:Common carrier obligations under PNGRB regulations face implementation friction at inter-state connection points, limiting physical pooling flexibility.
- Domestic supply stagnation:Maturing fields in the Krishna-Godavari basin constrain domestic molecule availability, increasing import dependency for pool balancing.
Strategic Opportunities
- Green hydrogen blending pilots:Regulatory frameworks for hydrogen injection into natural gas pipelines could expand pool composition beyond fossil molecules, opening new service revenue streams.
- Carbon border adjustment readiness:EU CBAM compliance requirements for Indian fertilizer exports create demand for certified low-carbon gas pooling certificates.
- Small-scale LNG distribution:Satellite regasification units for industrial clusters beyond pipeline reach enable geographic expansion of pooling coverage.
Industry Challenges
- Nomination system integration:Legacy SCADA infrastructure at stranded power plants requires costly retrofitting to interface with centralized pool management platforms.
- Storage buffer optimization:Limited underground gas storage capacity forces aggregators to maintain expensive LNG inventory floats for demand surge coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Pooling Mechanism Market |
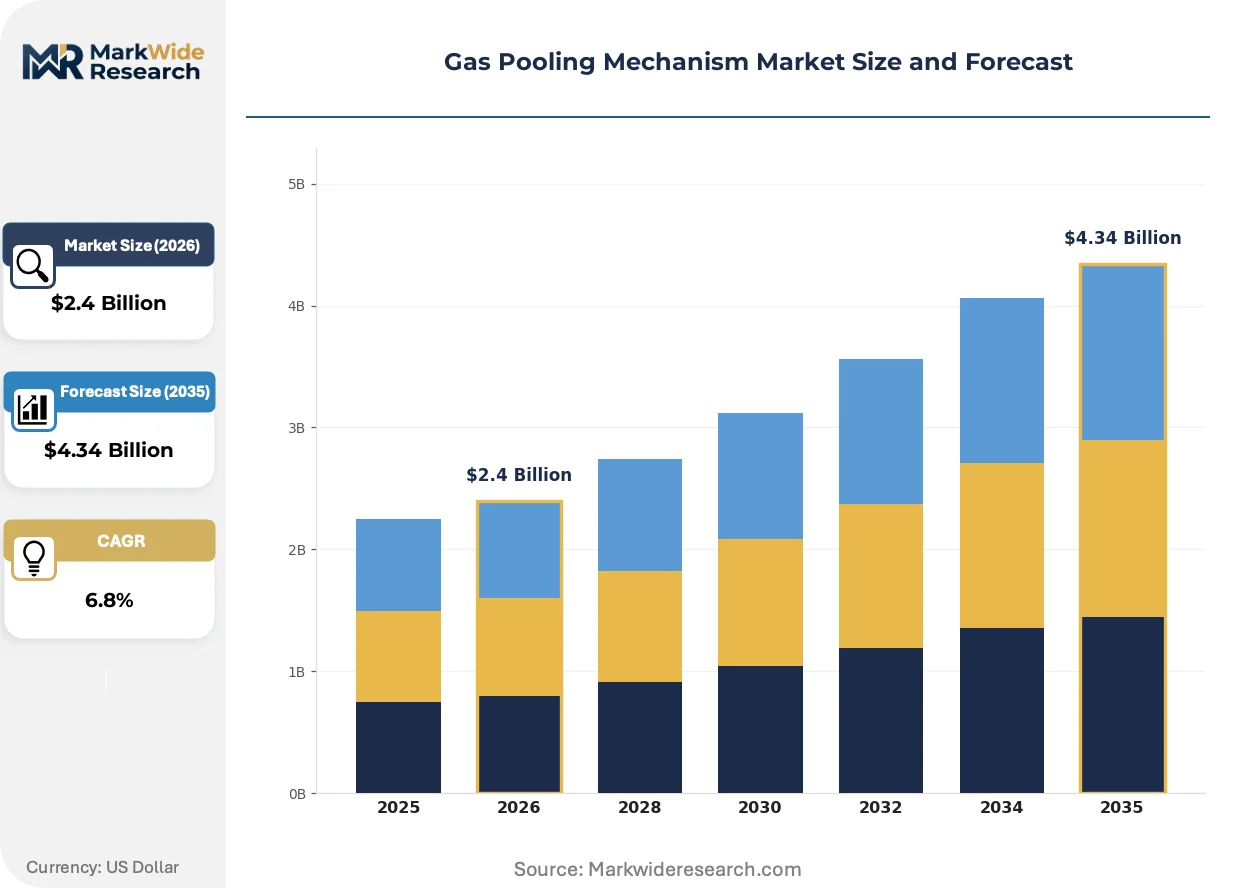
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Balancing, Transportation, Storage, Trading End User: Utilities, Industrial Users, Distributors, Aggregators Application: Power Generation, Manufacturing, Commercial Heating, Residential Heating Technology: Smart Metering, Data Analytics, Cloud Computing, IoT Solutions |
| Companies Covered | Saudi Aramco, ExxonMobil, Royal Dutch Shell, Chevron, PetroChina, Gazprom, Kuwait Petroleum Corporation, Oil & Natural Gas Corporation, TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Pooling Mechanism Market Shifts & Advancements
Digital orchestration platforms are replacing phone-and-fax nomination systems, compressing settlement cycles from monthly to daily intervals while exposing data architecture gaps at incumbent utilities.
Blockchain-based trade settlement is consolidating transaction verification across multiple supply sources into immutable ledger records. Major Indian gas utilities are piloting distributed ledger integration for LNG cargo documentation and customs clearance. This technology is consolidating counterparty risk management into automated smart contract execution, reducing dispute resolution overhead for pooled volume reconciliation.
The Petroleum and Natural Gas Regulatory Board's unified tariff regulations are mandating zonal pricing convergence across India's pipeline network. Industrial consumers in Maharashtra and Tamil Nadu now face reduced locational price disadvantages relative to Gujarat buyers. Stranded fertilizer plants in eastern states are responding by accelerating connection agreements under the new tariff framework.
Long-term offtake contracting is shortening as power utilities prefer quarterly nomination flexibility over annual minimum volume commitments. Spot-indexed pricing clauses are displacing oil-linked formulas in new supply agreements. This pattern is most visible among independent power producers in Rajasthan and Punjab seeking to optimize dispatch economics against renewable generation curves.
Gas Pooling Mechanism Market Segmentation
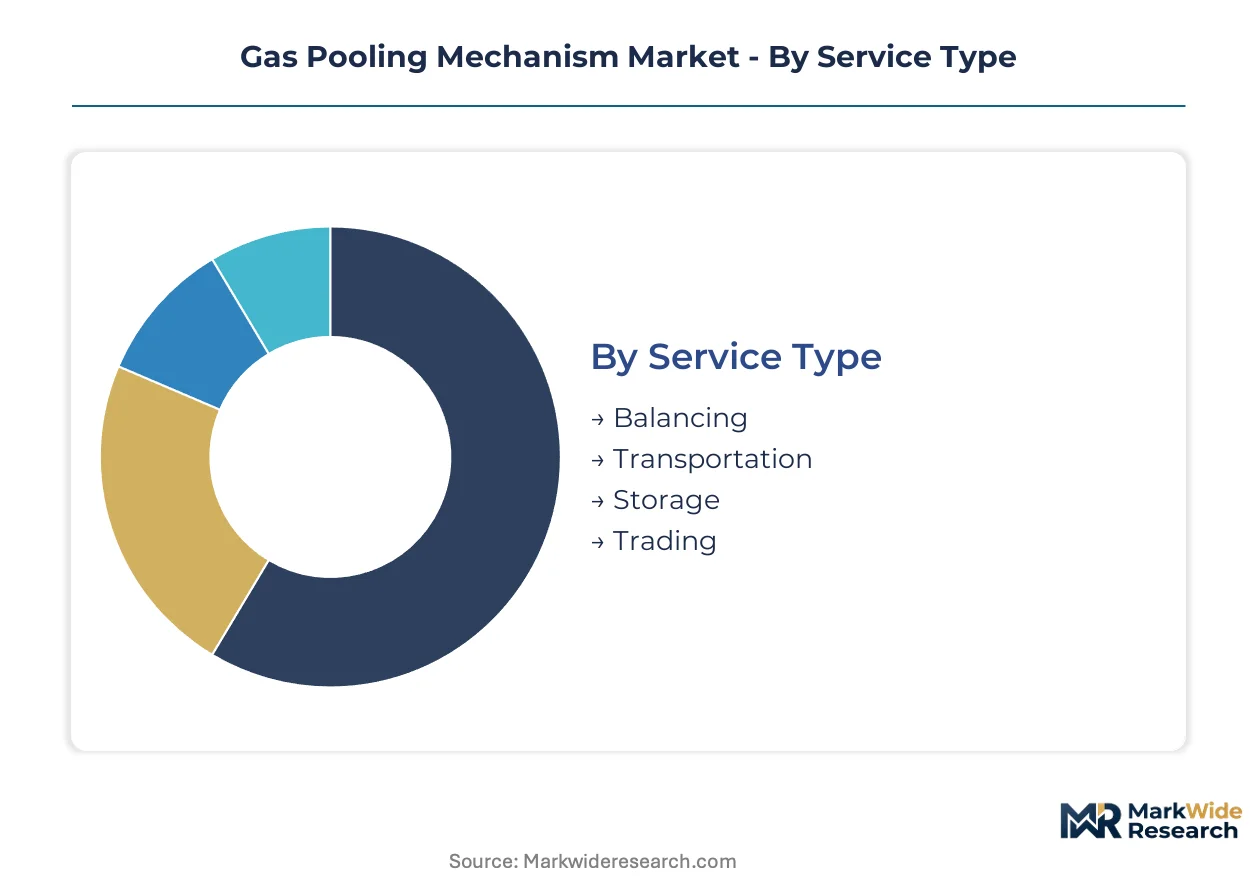
Gas pooling mechanisms require precise segmentation across service layers and technology stacks. Each dimension reveals distinct margin structures and infrastructure dependencies that determine aggregator competitiveness.
Service Type:
Balancing commands premium margins against commoditized transportation, while storage and trading occupy emerging revenue tiers with divergent capital intensity.
- Balancing:Physical aggregation of domestic and imported molecules through pipeline nomination systems. Gujarat's fertilizer manufacturers anchor demand as they require stable delivered prices despite supply source volatility. PNGRB unified tariffs compress arbitrage opportunities, forcing aggregators to monetize real-time imbalance management.
- Transportation:Pipeline common carrier access under regulated tariffs. Inter-state connection bottlenecks in Maharashtra and Tamil Nadu limit physical flexibility, creating locational premiums for corridor-adjacent assets.
- Storage:Buffer capacity management through LNG inventory floats and limited underground facilities. Krishna-Godavari basin constraints elevate import dependency for surge coverage.
- Trading:Secondary market transactions for pooled volume rights. Spot-indexed pricing clauses are displacing oil-linked formulas among independent power producers seeking dispatch optimization.
Today's leader: Balancing. Tomorrow's challenger: Storage.
End User:
Contract scale separates price-takers from price-makers, with volume concentration determining access to subsidized administrative pricing.
- Utilities:Power generation and distribution entities qualifying for subsidized pooled gas under Ministry of Petroleum and Natural Gas administrative orders. Stranded gas-based plants in Rajasthan and Punjab drive quarterly nomination flexibility preferences over annual commitments.
- Industrial Users:Fertilizer manufacturers and ceramic clusters in Gujarat's industrial corridor. These offtakers create density economies that reduce per-unit balancing costs for aggregators.
- Distributors:City gas distribution networks procuring pooled volumes for downstream fragmentation. Zonal pricing convergence under PNGRB regulations reduces historical locational disadvantages for Maharashtra and Tamil Nadu buyers.
- Aggregators:Intermediate procurement entities managing multi-source supply portfolios. These players face margin compression as unified tariffs eliminate domestic-imported price spreads.
Volume concentrates with Utilities. Margin expansion favors Aggregators.
Application:
Dispatch predictability varies by end-use, with power generation exposing aggregators to renewable generation curve volatility.
- Power Generation:Stranded gas-based plants seeking revival through pooled feedstock cost stability. Daily nomination cycles are replacing monthly settlements as smart metering enables real-time visibility.
- Manufacturing:Fertilizer and ceramic production with continuous process requirements. EU CBAM compliance requirements are creating demand for certified low-carbon gas pooling certificates among export-oriented fertilizer producers.
- Commercial Heating:Institutional and hospitality sector demand with seasonal load profiles. Small-scale LNG distribution through satellite regasification units extends coverage beyond pipeline reach.
- Residential Heating:City gas distribution networks serving household consumers. This segment remains marginal within pooling frameworks due to small individual offtake volumes.
Power Generation anchors volume. Manufacturing captures premium certification value.
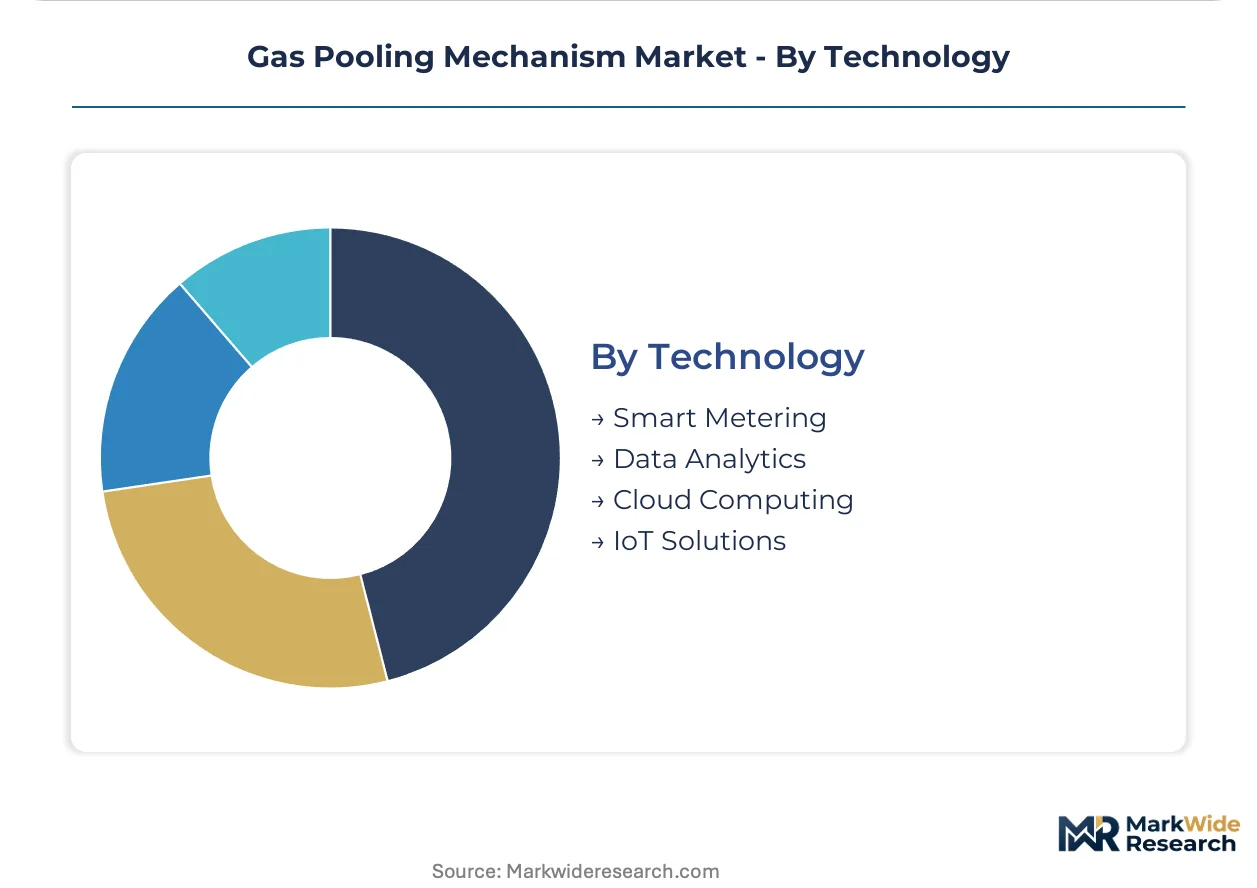
Technology:
Data architecture maturity separates legacy utilities from digital-first competitors, with cloud and IoT layers enabling new service revenue.
- Smart Metering:Real-time measurement infrastructure displacing manual allocation systems. Legacy SCADA retrofitting costs at stranded power plants create implementation friction for centralized pool management platforms.
- Data Analytics:Predictive modeling for demand surge coverage and inventory optimization. Limited underground gas storage capacity elevates algorithmic importance for LNG float timing decisions.
- Cloud Computing:Distributed ledger integration for LNG cargo documentation and customs clearance. Blockchain-based settlement is consolidating counterparty risk management into automated smart contract execution.
- IoT Solutions:Sensor networks for pipeline pressure monitoring and leak detection. These deployments support green hydrogen blending pilots by enabling composition tracking for regulatory compliance.
Smart Metering dominates deployment. IoT Solutions hold steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's industrial corridor anchors pooled gas demand through fertilizer manufacturers and ceramic clusters that require stable delivered prices despite supply source volatility.
India
The Petroleum and Natural Gas Regulatory Board mandates unified tariffs that compress domestic-imported price spreads, forcing aggregators to monetize balancing services rather than molecule arbitrage. Stranded gas-based power plants in Rajasthan and Punjab drive quarterly nomination flexibility preferences over annual commitments. The Krishna-Godavari basin's maturing fields constrain domestic molecule availability, increasing import dependency for pool balancing.
China
Dual carbon goals under MIIT direction accelerate gas demand substitution for coal in industrial heating applications. National pipeline operators aggregate domestic field output with term LNG imports through zonal pricing frameworks. The Yangtze River Delta's chemical manufacturing clusters anchor offtake volumes for regional balancing pools.
Saudi Arabia
Saudi Aramco leverages upstream scale to supply term LNG cargoes into pooled tenders across Asian markets. The Kingdom's gas master plan expands domestic distribution networks for industrial corridor development. NEOM's northwest development zone pilots green hydrogen blending into conventional gas infrastructure.
United States
FERC-regulated interstate pipelines enable multi-source aggregation from shale basins and LNG regasification terminals. Henry Hub-linked pricing formulas dominate contract structures for industrial offtakers. The Gulf Coast's petrochemical corridor concentrates demand for balancing services that manage supply source volatility.
Germany
The EU Green Deal's decarbonization mandates accelerate gas demand substitution for coal in power generation and industrial processes. REACH-compliant certification frameworks create requirements for low-carbon gas pooling documentation. The Ruhr industrial region's steel and chemical clusters anchor balancing pool participation.
Gas Pooling Mechanism Market Competitive Landscape
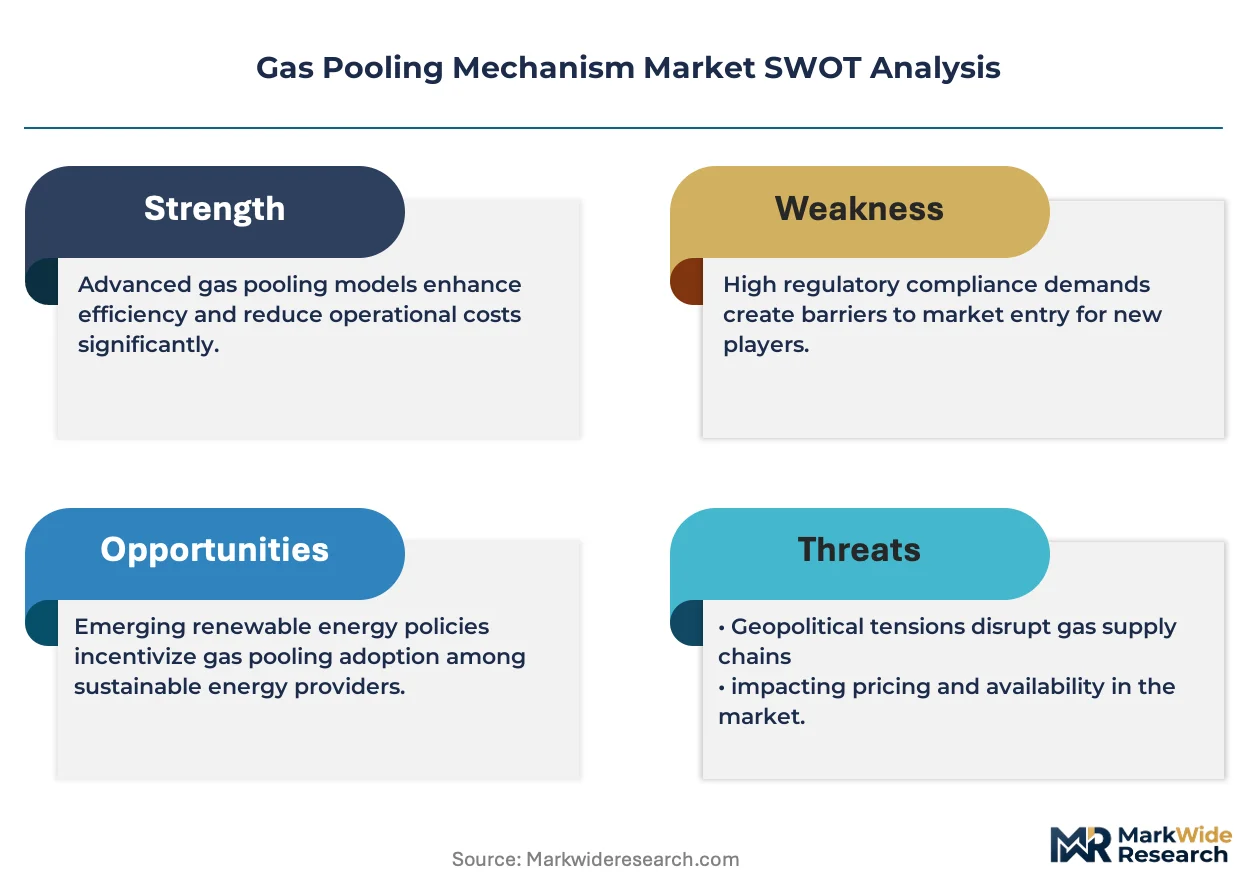
Global majors compete with regional champions across aggregation services and term supply contracting. The vendor base organizes around upstream-integrated suppliers, portfolio traders, and national oil companies with captive production. Three archetypes dominate: scale-driven term suppliers, flexible portfolio optimizers, and state-backed domestic aggregators. Competitive positioning hardens through strategic partnerships for storage access and technology licensing for nomination system integration.
Within the upstream-integrated tier, Saudi Aramco and Gazprom anchor term supply volumes that feed into national balancing pools. TotalEnergies occupies a position exemplifying flexible portfolio optimization across Atlantic and Pacific supply basins. These players represent divergent strategic postures—captive resource monetization versus merchant trading agility—within a market where unified tariffs compress traditional arbitrage margins.
| Leading Market Players |
|---|
| Saudi Aramco |
| ExxonMobil |
| Royal Dutch Shell |
| Chevron |
| PetroChina |
| Gazprom |
| Kuwait Petroleum Corporation |
| Oil & Natural Gas Corporation |
| TotalEnergies |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers anchor supply discipline across the gas pooling mechanism market, with Saudi Aramco and Gazprom leveraging upstream scale to enforce term-contract pricing rigidity while aggregators absorb spot volatility. This ownership pattern compresses margin capture at the balancing layer, forcing mid-tier aggregators to rebuild economics around nomination services rather than molecule arbitrage.
Pricing Analysis
Input-cost pass-through from LNG spot differentials against term contracts determines pooled price stability for qualified consumers under Ministry of Petroleum and Natural Gas administrative orders. Contract-based long-term offtake dominates procurement structures, with spot-indexed pricing clauses displacing oil-linked formulas among independent power producers in Rajasthan and Punjab. Price differentiation hinges on volume scale and qualification for subsidized administrative pricing. Cost compression in the balancing tier is intensifying because unified tariffs eliminate domestic-imported spreads. Utilities exhibit highest price sensitivity due to dispatch competition with renewable generation, while fertilizer manufacturers anchored in Gujarat's industrial corridor show greater tolerance for delivered price stability premiums.
Supply Chain Analysis
Reverse-logistics flows for LNG cargo documentation and customs clearance are consolidating through blockchain-based settlement platforms, reducing dispute resolution overhead for pooled volume reconciliation. Geographic supply concentration centers on Qatar, Australia, and the United States as primary LNG source markets feeding Indian pooling frameworks. Raw material dependencies include term LNG cargoes, domestic Krishna-Godavari basin output, and spot market supplements. Single-source vulnerability elevates risk exposure when maturing domestic fields constrain molecule availability. Distribution runs through PNGRB-regulated pipeline common carrier networks with inter-state connection bottlenecks limiting physical flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas pooling mechanism market functions as a regulatory compounder, with the Petroleum and Natural Gas Regulatory Board's unified tariff mandate driving demand for balancing services as traditional arbitrage margins compress.
For Market Incumbents: Deploy smart metering infrastructure as the primary defensive lever. Incumbents should accelerate legacy SCADA retrofitting at stranded power plants to lock in centralized pool management platform integration before digital orchestration platforms commoditize nomination services. Backward integration into LNG inventory float capacity addresses surge coverage gaps created by limited underground storage. Certification investment in EU CBAM-compliant documentation systems captures premium value from export-oriented fertilizer producers facing carbon border adjustment compliance requirements. For New Entrants and Emerging Players: Blockchain-enabled trade settlement platforms offer a technology-first wedge into transaction verification and counterparty risk management automation. White-space targets include small-scale LNG distribution through satellite regasification units for industrial clusters beyond pipeline reach in Maharashtra and Tamil Nadu, and green hydrogen blending pilot services for NEOM-type infrastructure developments. The most penetrable segment spans independent power producers seeking quarterly nomination flexibility. A direct go-to-market angle partners with city gas distribution networks for downstream fragmentation services. For Investors and Strategic Acquirers: Valuations sit cheapest among aggregators with stranded asset revival mandates and pipeline corridor-adjacent storage access. Long-term viability over the next decade rests on regulatory persistence of administrative price orders and unified tariff frameworks. Acquisition target archetypes include mid-tier balancing service providers with smart metering deployment capabilities and inter-state connection agreements. The signal to watch is PNGRB regulatory momentum on hydrogen injection standards, which would expand pool composition beyond fossil molecules and reset competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Metering Infrastructure Deployment | Real-time visibility into pool injections displaces manual allocation systems at stranded plants. |
| Backward Integration into LNG Float Capacity | Inventory timing optimization addresses Krishna-Godavari supply constraints for surge coverage. |
| Blockchain Trade Settlement Platform | Automated smart contract execution reduces dispute overhead for multi-source volume reconciliation. |
| EU CBAM Certification Program | Low-carbon gas pooling documentation captures premium from export-oriented fertilizer manufacturers. |
| Small-Scale LNG Satellite Network | Geographic expansion beyond pipeline reach extends pooling coverage to Maharashtra and Tamil Nadu clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with utility planning officers, gas aggregator procurement leads, pipeline operators, and Ministry of Petroleum and Natural Gas regulatory affairs specialists alongside secondary validation. Bottom-up triangulation drew from PNGRB tariff orders, LNG cargo tracking databases, FERC interstate pipeline filings, and IEA gas market reports. Top-down cross-checks anchored against Petroleum and Natural Gas Regulatory Board administrative data and Ministry petroleum sector disclosures.
Comparable-period anchoring linked projection assumptions to historical unified tariff implementation phases and stranded asset revival program enrollment curves across the analysis window. Segmentation dimensions modeled include service type, end-user category, application sector, and technology stack maturity. CAGRs were derived through demand elasticity modeling against power dispatch curves and fertilizer production schedules. Forecast inputs incorporated pipeline connection agreement velocity and smart metering deployment trajectories.
The model holds under sustained administrative price order eligibility and PNGRB unified tariff enforcement; deviation in regulatory rollback or domestic supply disruption would shift volume and value outputs. Forecasts reflect documented assumptions about nomination system integration timelines and LNG term contract renewal patterns. Practitioners should monitor green hydrogen blending pilot regulatory signals and EU CBAM implementation stringency for early indicators of pool composition expansion and certification premium capture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
North America LNG Bunkering Market
Fuels
Germany Bunker Fuel Market
Fuels
Bituminous Coal Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
Briquette Market
Fuels
Italy Automotive Engine Oils Market
Fuels
China Bunker Fuel Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Coal Briquette Box Market
Fuels
Brazil Bunker Fuel Market
Fuels
Liquid Propellants Market
Fuels
Wood Charcoal Market
Fuels
Global Charcoal Market
Fuels
Coal Gasification Market
Fuels
Fuel Analyzer Market