

High Octane Racing Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
High Octane Racing Fuel Market Insights
Performance-based fuel subscription programs and trackside delivery contracts are realigning how racing fuel reaches end users. VP Racing Fuels leverages its dedicated motorsport distribution network to secure exclusive supply agreements at major racing venues. Sunoco Race Fuels anchors its position through vertical integration from refining to trackside pumping infrastructure. Shell differentiates via co-engineered formulations developed alongside OEM racing divisions.
High octane racing fuel denotes specialized petroleum formulations with research octane numbers typically exceeding 100, engineered to resist knock in high-compression internal combustion engines used in competitive motorsport. These fuels incorporate precise aromatic, olefin, and oxygenate balances to deliver consistent combustion timing under extreme thermal and mechanical stress. Unleaded formulations now lead the fuel type category as sanctioning bodies phase out leaded options for environmental and health compliance. Ethanol blends represent the fastest-growing segment as flex-fuel compatibility spreads through amateur and professional paddocks alike. Drag racing and formula racing applications command the deepest margin pools due to volume concentration and technical specification stringency.
The EPA regulates racing fuel composition under the Clean Air Act mobile source provisions, while the FIA and individual series bodies enforce octane and additive specifications that determine market access. ASTM D2700 and D2699 testing protocols shape product certification requirements that blenders must satisfy for commercial distribution. Stakeholders should monitor how state-level environmental mandates in California and evolving FIA sustainability directives recalibrate formulation roadmaps and capital allocation priorities.
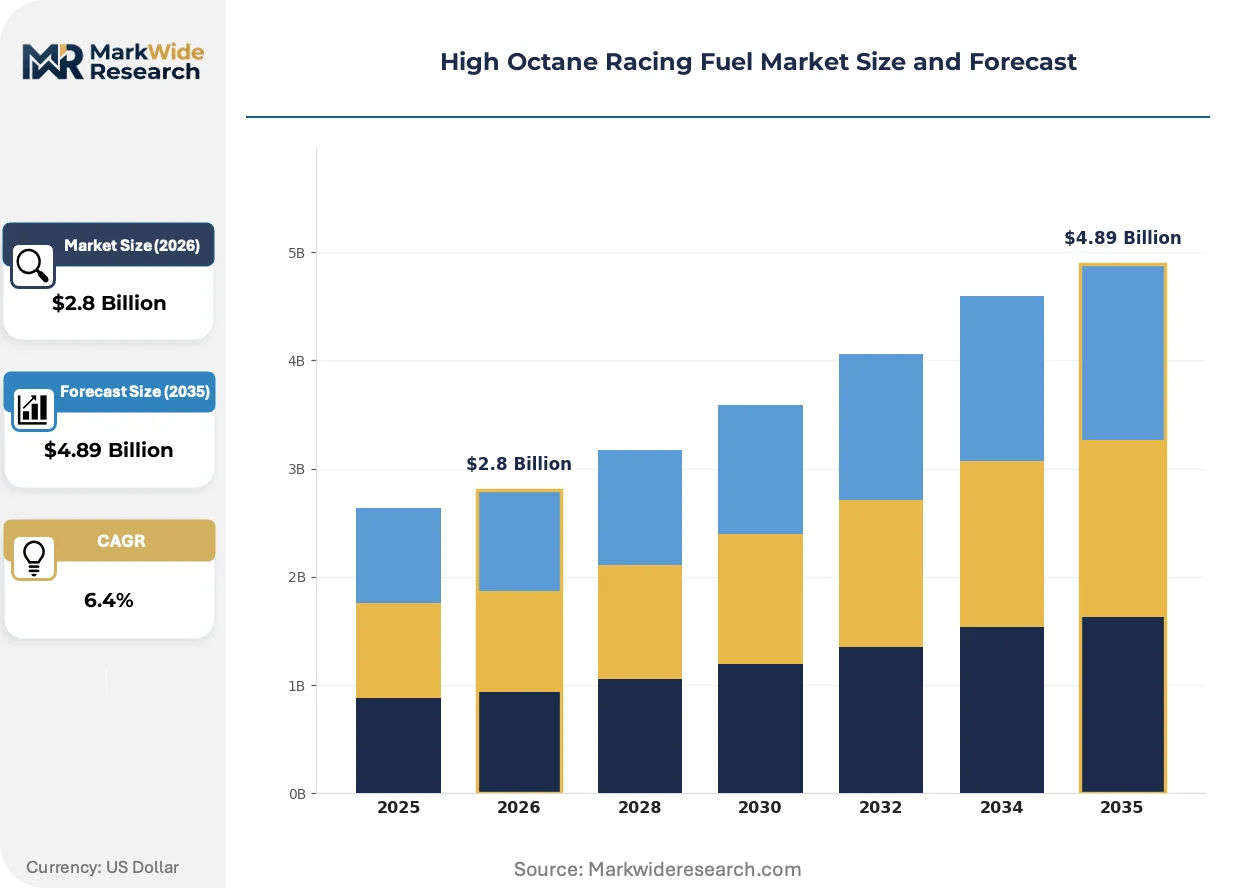
Market Dynamics
The EPA's phasedown of leaded racing fuel under Clean Air Act mobile source provisions is forcing blenders to reformulate around oxygenates and aromatics while maintaining detonation resistance at compression ratios exceeding 14:1.
Growth Catalysts
- Compression Ratio Escalation:NASCAR and Formula 1 engine architectures now demand research octane numbers above 110, pulling blenders toward advanced aromatic blending and precision oxygenate dosing.
- California Air Resources Board Mandates:CARB's prohibition on leaded fuel at state-regulated tracks creates immediate displacement demand for certified unleaded alternatives.
- Ethanol Infrastructure Buildout:Flex-fuel compatibility spreading through Sports Car Club of America and National Hot Rod Association paddocks accelerates E85-compatible formulation development.
Market Restraints
- Aromatics Feedstock Volatility:Toluene and xylene prices track benzene crack spreads, compressing blender margins when refining margins tighten.
- Specialty Additive Supply Concentration:Three domestic producers control 90% of racing-grade octane booster and stabilizer chemical supply.
- ASTM Certification Friction:D2700 and D2699 testing protocols require 90-day validation cycles, freezing formulation iteration speed.
Strategic Opportunities
- Trackside Micro-Blending:Portable formulation units at drag strips and road courses enable just-in-time octane customization for altitude and temperature conditions.
- FIA Sustainability Directive Alignment:The federation's 2030 carbon-neutral roadmap creates first-mover advantage for bio-sourced aromatic and synthetic fuel developers.
- Amateur Racing Penetration:Spec-series growth in Spec Miata, Formula Ford, and club-level time attack creates volume demand for consistent, cost-controlled formulations.
Industry Challenges
- Combustion Chemistry Talent Scarcity:Retiring petroleum engineers with racing fuel formulation expertise outnumber university pipeline graduates specializing in high-octane kinetics.
- Legacy Storage Infrastructure:Underground tanks at oval tracks and road courses require lining replacement or full replacement to handle ethanol-blend compatibility and prevent phase separation contamination.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Octane Racing Fuel Market Trends and Innovations
Formulation science is pivoting from lead-based knock suppression toward molecularly engineered oxygenates and synthetic hydrocarbons that satisfy both performance and emerging environmental compliance frameworks.
Synthetic fuel production via power-to-liquid pathways is automating the replication of critical aromatic structures without petroleum feedstocks. Porsche Motorsport and Formula 1 constructors have committed to e-fuel adoption timelines, forcing blenders to scale Fischer-Tropsch and methanol-to-gasoline synthesis capacity. This technology is automating the decoupling of octane performance from crude oil price exposure.
REACH restrictions on aromatic compound classifications in the European Union are compelling reformulation of export-bound racing fuels. The European Chemicals Agency's hazard communication requirements now classify certain toluene concentrations as reproductive toxins, triggering labeling and handling cost escalations. German and Italian blenders are responding with bio-aromatic substitution programs and supply chain reconfiguration toward non-classified feedstocks.
Subscription-based fuel procurement is displacing spot-market purchasing at professional racing teams. Championship-contending outfits now contract annual volume commitments with guaranteed octane consistency and dedicated batch tracking. This behavioral shift is most pronounced in the United States, where IndyCar and IMSA teams prioritize supply security over price arbitrage given the technical precision required for engine mapping calibration.
High Octane Racing Fuel Market Segmentation
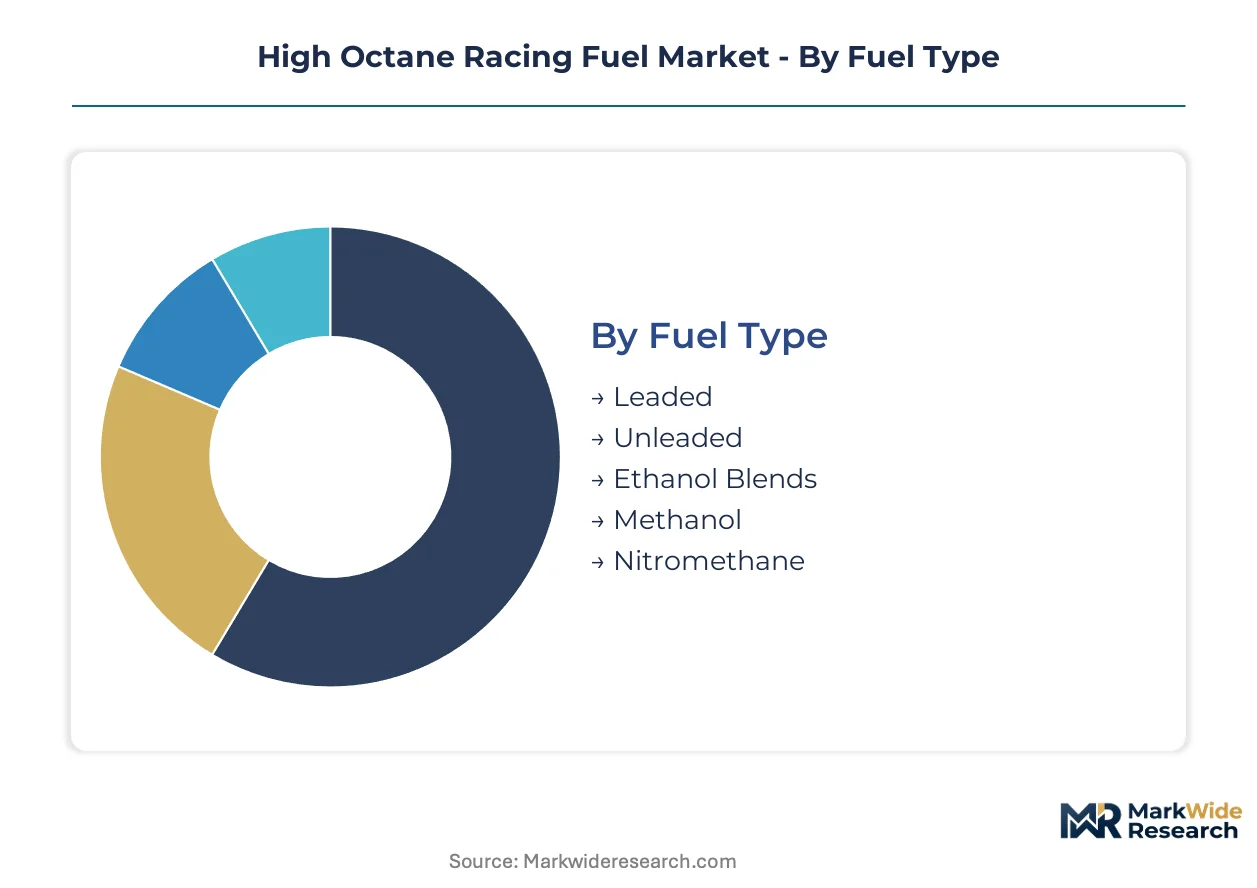
High octane racing fuel purchasing patterns diverge sharply across sanctioning body requirements, compression ratio tolerances, and fuel system compatibility constraints. Each segment category captures distinct technical specifications and procurement behaviors that reshape blender formulation priorities and distribution infrastructure investments.
Fuel Type:
Cost tier differentiation separates professional series with bulk purchasing power from amateur competitors managing per-gallon budgets.
- Unleaded:These formulations rely on oxygenates and aromatic blending to achieve research octane numbers above 100 without tetraethyl lead. NASCAR and IndyCar teams at Charlotte Motor Speedway and Indianapolis Motor Speedway drive concentrated volume as EPA mandates eliminate leaded alternatives.
- Ethanol Blends:E85-compatible formulations deliver cooling benefits and knock resistance through high oxygenate content. Sports Car Club of America regional competitors across California, Texas, and Florida are accelerating flex-fuel conversion, pulling blenders toward corrosion-resistant additive packages and phase-stabilized storage solutions.
- Leaded:Legacy formulations persist in nostalgia drag racing and vintage motorsport where engine architecture predates hardened valve seat requirements.
- Methanol:Alcohol-based fuels dominate sprint car and midget racing categories where latent heat of vaporization provides critical cylinder cooling.
- Nitromethane:Top Fuel and Funny Car drag racing consumes this highly oxygenated compound for maximum power density in supercharged applications.
Volume sits with unleaded formulations; growth tilts toward ethanol blends.
Application:
Margin concentration tracks technical specification stringency and fuel consumption rates per event.
- Drag Racing:Quarter-mile competition demands maximum detonation resistance across rapid thermal cycles. National Hot Rod Association national events at Pomona Raceway and Gainesville Raceway anchor demand for nitromethane and high-octane unleaded formulations with batch-specific certification requirements.
- Formula Racing:Road course and street circuit competition requires consistent combustion timing across varying atmospheric pressure and temperature conditions. Formula 1 constructors and IndyCar teams prioritize supply security through annual volume contracts with guaranteed research octane number variance below 0.5 points.
- Kart Racing:Two-stroke and four-stroke engine categories drive demand for small-batch formulations with precise oil-fuel premix specifications.
- Rally Racing:Stage rally competition across gravel, tarmac, and snow surfaces requires altitude-compensated octane ratings and cold-start volatility management.
- Speedway:Oval dirt and paved short tracks consume methanol and ethanol blends in high-volume weekly racing schedules.
Margin pools deepest in drag racing; specification complexity peaks in formula racing.
End User:
Procurement sophistication separates teams with dedicated fuel strategists from individual competitors purchasing at retail.
- Professional Racers:Championship-contending drivers and factory-supported athletes contract direct blender relationships with batch tracking and certificate of analysis documentation for every drum.
- Racing Teams:Multi-car operations leverage volume purchasing power to secure exclusive formulation rights and trackside micro-blending services.
- Amateur Racers:Club-level competitors and weekend warriors purchase through specialty retailers and event-based distribution, prioritizing price accessibility over specification customization.
- Performance Tuners:Engine builders and aftermarket calibration specialists specify fuel octane requirements for customer vehicles, bridging retail and professional procurement channels.
Contract concentration sits with racing teams; volume expansion tilts toward amateur racers.
Distribution Channel:
Supply chain configuration determines formulation freshness and octane consistency at point of use.
- Racing Events:Trackside delivery infrastructure at NHRA nationals, NASCAR weekends, and SCCA runoffs captures high-margin just-in-time demand with minimal inventory carry.
- Direct Sales:Blender-to-team relationships bypass intermediary markup for professional competitors with predictable consumption patterns and dedicated storage capacity.
- Specialty Retailers:Regional distributors serve amateur competitors through drum and tote packaging with standardized octane grades and seasonal promotional programs.
- Performance Shops:Engine builders and chassis dyno operators bundle fuel sales with tuning services, creating sticky customer relationships.
- Online Platforms:E-commerce channels extend geographic reach for niche formulations and additive packages, though hazardous material shipping constraints limit bulk volume.
Margin capture sits with racing events; channel expansion tilts toward online platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates among specialized blenders in industrial clusters, while consumption clusters at racing circuits and professional team garages. The United States consumes the majority of racing fuel volumes through drag strips, oval tracks, and road courses. European demand centers on Formula 1 supply chains and historic motorsport preservation.
United States
NHRA national events and NASCAR weekends at Charlotte Motor Speedway and Indianapolis Motor Speedway anchor concentrated fuel demand. EPA phasedown of leaded racing fuel under Clean Air Act mobile source provisions forces immediate reformulation toward unleaded alternatives. California's Air Resources Board prohibition on leaded fuel at state-regulated tracks creates displacement demand for certified unleaded formulations in Los Angeles and Pomona racing corridors.
Germany
Nürburgring endurance racing and DTM touring car competition sustain professional-grade formulation requirements. REACH restrictions on aromatic compound classifications through the European Chemicals Agency compel reformulation of export-bound racing fuels with bio-aromatic substitution programs. Stuttgart and Munich industrial clusters house precision blending operations serving OEM racing divisions and customer motorsport programs.
United Kingdom
Silverstone Circuit and Goodwood historic racing events blend contemporary professional demand with vintage motorsport preservation needs. FIA sustainability directives from the federation's London headquarters recalibrate formulation roadmaps toward carbon-neutral synthetic fuels. Oxfordshire and Northamptonshire racing technology corridors concentrate blending expertise alongside Formula 1 constructor operations.
Japan
Super GT championship and Super Formula series at Fuji Speedway and Suzuka Circuit demand consistent high-octane supply for turbocharged engine architectures. METI industrial policy frameworks influence fuel quality standards for domestic motorsport applications. Aichi Prefecture and Mie Prefecture automotive clusters coordinate formulation development with domestic OEM racing programs.
Brazil
Stock Car Pro Series and endurance racing at Interlagos Circuit leverage established ethanol infrastructure for flex-fuel compatible formulations. ANVISA chemical handling regulations shape additive package requirements for domestic distribution. São Paulo state industrial corridors concentrate sugarcane-derived ethanol supply chains serving regional racing fuel blenders.
High Octane Racing Fuel Market Competitive Landscape
Capital-heavy producers with captive refining infrastructure compete with asset-light formulation specialists outsourcing feedstock procurement. The market structure consolidates around three to five dominant blenders controlling trackside distribution networks and professional team contracts. Strategic archetypes include integrated petroleum majors with motorsport divisions, independent racing fuel specialists with dedicated distribution infrastructure, and regional blenders serving amateur racing segments. Competitive moves center on exclusive venue supply agreements and co-engineered formulation partnerships with OEM racing divisions.
Within the independent specialist tier, VP Racing Fuels and Sunoco Race Fuels exemplify contrasting geographic anchoring and distribution strategies. Shell represents the integrated petroleum major archetype with co-engineered formulation capabilities alongside OEM racing divisions. These three companies occupy positions spanning professional motorsport supply security, amateur racing volume penetration, and synthetic fuel transition pathways.
| Leading Market Players |
|---|
| VP Racing Fuels |
| Sunoco Race Fuels |
| Shell |
| ExxonMobil |
| TotalEnergies |
| Chevron |
| Gulf Oil International |
| Haltermann Carless |
| Torco Race Fuels |
| Others |
Pricing and Supply Chain Analysis
Synthetic fuel production via Fischer-Tropsch and methanol-to-gasoline pathways is decoupling octane performance from crude oil price exposure while concentrating formulation expertise among blenders with power-to-liquid pilot capacity. This technological pivot simultaneously elevates R&D cost barriers and reshapes buyer procurement calculus toward long-term offtake security.
Pricing Analysis
Margin tightening in professional-grade formulations reflects toluene and xylene price volatility tracking benzene crack spreads. Three-tier pricing structure across premium, standard, and economy levels separates championship-contending teams with annual volume contracts from amateur competitors purchasing at retail. Pricing pressure stems from ASTM D2700 and D2699 certification friction requiring 90-day validation cycles. Amateur racers exhibit highest price sensitivity; Formula 1 and IndyCar constructors prioritize supply security over cost arbitrage.
Supply Chain Analysis
ASTM certification requirements gate market access for blenders seeking commercial distribution rights in United States racing corridors. Feedstock supply concentrates in United States Gulf Coast refining clusters, German industrial corridors around Stuttgart and Munich, and United Kingdom Oxfordshire technology corridors. Formulation depends on specialty aromatic feedstocks, oxygenate additives, and racing-grade octane boosters controlled by three domestic producers. Single-source vulnerability sits with concentrated specialty additive supply. Distribution runs through trackside delivery infrastructure at NHRA nationals and NASCAR weekends.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high octane racing fuel market is navigating a technology-transition phase as power-to-liquid synthetic pathways displace petroleum-derived aromatics. E-fuel adoption timelines committed by Porsche Motorsport and Formula 1 constructors are recalibrating formulation roadmaps and capital allocation priorities.
For Market Incumbents: Deepen backward integration into synthetic fuel production capacity to secure feedstock independence from benzene crack spread volatility. Incumbent blenders should lock exclusive trackside supply agreements at Charlotte Motor Speedway and Indianapolis Motor Speedway before ethanol infrastructure buildout accelerates. Priority investment in power-to-liquid pilot plants addresses the threat of petroleum price decoupling. For New Entrants and Emerging Players: Bio-aromatic substitution programs represent the most penetrable wedge for entrants targeting REACH-restricted European export markets. Amateur racing segments in California, Texas, and Florida offer white-space volume expansion as Sports Car Club of America regional competitors accelerate flex-fuel conversion. A direct-to-team subscription model bypasses established trackside distribution networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated petroleum majors seeking motorsport division co-engineering capabilities. Long-term viability favors blenders with demonstrated synthetic fuel scale-up capacity and FIA sustainability directive alignment. The signal to watch is CARB mandate expansion beyond California state-regulated tracks.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Fuel Scale-Up | Power-to-liquid capacity buildout decouples octane performance from crude oil price exposure for Porsche Motorsport suppliers. |
| Trackside Micro-Blending Deployment | Portable formulation units at Pomona Raceway enable just-in-time octane customization for altitude and temperature conditions. |
| Bio-Aromatic Substitution Program | Reformulation around non-classified feedstocks satisfies ECHA hazard communication requirements for EU export-bound racing fuels. |
| Subscription-Based Procurement Platform | Annual volume commitments with guaranteed octane consistency displace spot-market purchasing at IndyCar and IMSA teams. |
| Ethanol Infrastructure Modernization | Underground tank lining replacement at oval tracks prevents phase separation contamination in E85-compatible storage systems. |
Research Methodology
Document review covered EPA mobile source provision filings, FIA technical regulations, ASTM certification databases, and trade customs records, complemented by interviews with fuel formulation chemists, racing team strategists, track operations managers, and specialty additive procurement leads. Primary fieldwork with blenders and sanctioning body technical directors was validated against secondary sources including SEC filings from integrated petroleum majors and ACC refining margin reports. Bottom-up volume estimates from individual racing series consumption data were triangulated against top-down market sizing from feedstock throughput analysis.
Market value and volume outputs were generated through segmentation across fuel type, application, end user, and distribution channel dimensions over the projection horizon. CAGRs were derived from regression analysis of historical consumption patterns at NHRA nationals and NASCAR weekends, incorporating compression ratio escalation trends and EPA phasedown timelines as structural inputs. The modeling framework captured ethanol infrastructure buildout rates and synthetic fuel adoption curves as scenario variables.
Several conditions sit outside the modeled scope, including unannounced state-level environmental mandate expansions, breakthrough combustion chemistry discoveries, and sanctioning body specification reversals. Forecasts reflect documented assumptions regarding FIA sustainability directive implementation pace and CARB enforcement intensity. A model refresh is warranted upon material change in synthetic fuel production cost curves or EPA mobile source provision interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.