
 Europe Cow Milk Minerals Market | 2026-2036
Europe Cow Milk Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cow Milk Minerals Market Foresight
Premium-grade mineral specifications is bifurcating the competitive landscape between commodity suppliers and high-purity specialists. Arla Foods amba leverages its Danish cooperative structure to sustain backward integration into milk mineral extraction. Koninklijke FrieslandCampina N.V. anchors its position through proprietary demineralization technology deployed across Dutch processing facilities. Groupe Lactalis competes by dominating whey and milk fractionation capacity across France and Italy.
Europe cow milk minerals comprise bioavailable calcium, magnesium, phosphorus, and potassium recovered from bovine milk through electrodialysis or ion exchange, typically achieving 20-25% calcium content in concentrated forms for food fortification. The primary commercial purpose centers on delivering label-friendly mineral fortification for infant formula, bone-health positioning, and clean-label dairy alternatives where synthetic salts face consumer resistance. Calcium leads product type demand due to entrenched bone-health positioning and broad compatibility across applications, while infant nutrition commands the fastest application growth as brands reformulate to reduce synthetic additive reliance. Functional foods represents a maturing margin pool where differentiation depends on EFSA-approved health claims rather than commodity mineral content alone.
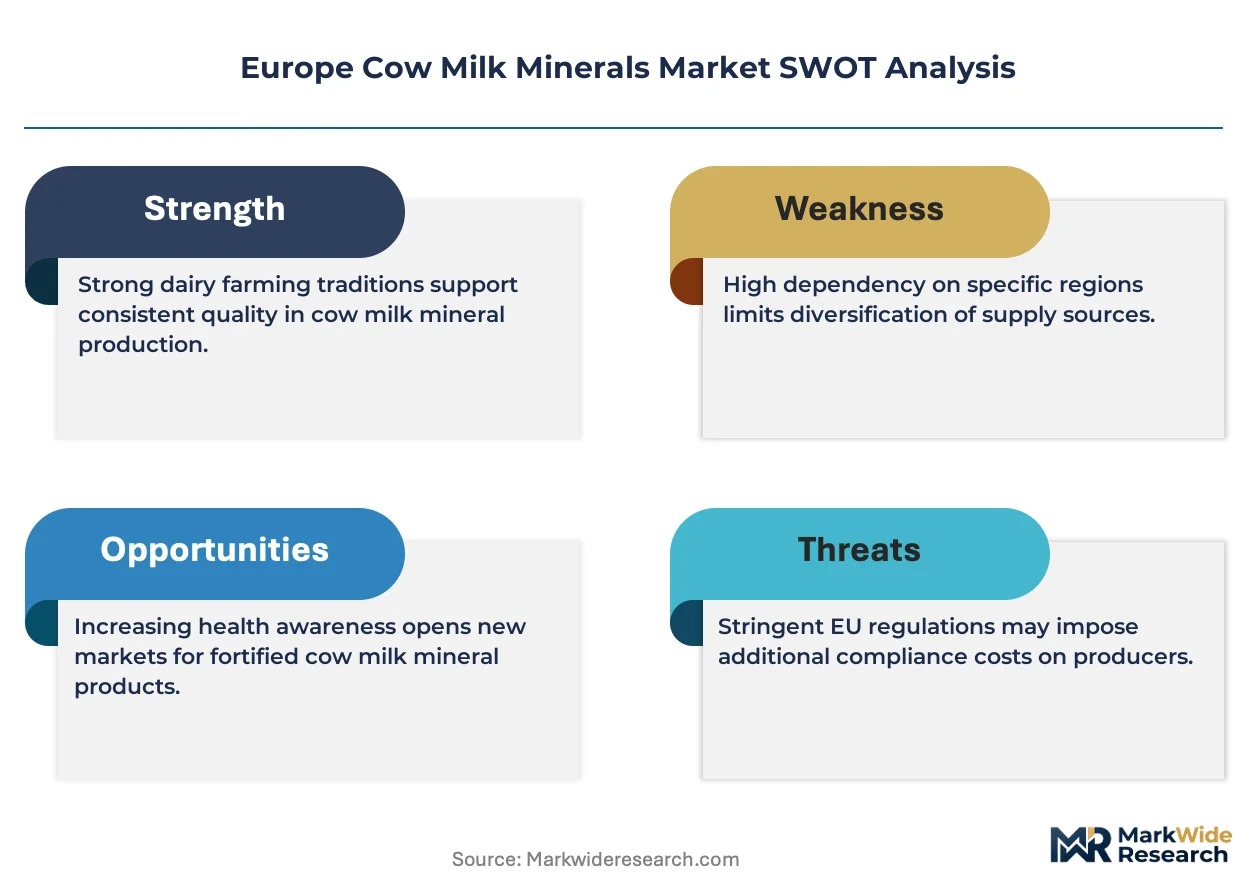
EFSA nutrition and health claims regulation shapes permissible marketing language for bone-density and growth-positioned products, directly constraining brand communication strategies. The EU Green Deal and REACH frameworks impose escalating sustainability and chemical safety thresholds on extraction processes and packaging materials. CSRD disclosure mandates will soon require mineral ingredient suppliers to document Scope 3 dairy sourcing emissions. Stakeholders must monitor evolving EFSA opinions on upper intake levels and prepare for potential reformulation thresholds that could reshape competitive advantage toward lower-dose, higher-bioavailability delivery formats.
Market Dynamics
EFSA's tightening purity benchmarks for dairy-derived mineral ingredients are compressing supplier margins while rewarding high-purity specialists with premium positioning. This regulatory pressure is accelerating capital deployment toward electrodialysis upgrades and ion-exchange optimization across Dutch and Danish processing clusters.
Growth Catalysts
- Clean-label infant formula reformulation:Brands are eliminating synthetic mineral salts to meet parent demand for recognizable ingredient lists. This pull is strongest in German and French manufacturing facilities.
- EU Green Deal sustainability mandates:REACH frameworks now require documented emission reductions from extraction processes. Suppliers demonstrating lower Scope 3 dairy sourcing emissions gain preferential procurement status.
- Bone-health positioning in functional foods:EFSA-approved health claims for calcium bioavailability are enabling premium pricing in aging-population segments across Italy and Spain.
Market Restraints
- Raw milk input cost volatility:Bovine milk prices fluctuate with feed grain markets and energy costs, compressing margin predictability for mineral concentrate producers.
- Supply concentration in Dutch processing:Electrodialysis capacity clusters disproportionately in the Netherlands, creating geographic vulnerability to regional energy price shocks or logistics disruptions.
- Plant-based mineral substitutes:Algae-derived and lithothamnion calcium sources are capturing share in dairy-alternative fortification, displacing bovine-origin minerals in vegan-positioned products.
Strategic Opportunities
- Polish and Romanian dairy expansion:Underdeveloped mineral recovery infrastructure in Eastern European milk processing creates first-mover openings for technology licensors.
- CSRD disclosure services:Mandatory Scope 3 emissions reporting positions mineral ingredient suppliers to monetize carbon-accounting expertise as a bundled service.
- Hybrid electrodialysis-nanofiltration systems:Converging membrane technologies enable simultaneous mineral concentration and lactose reduction, unlocking whey-side value streams previously uneconomical to recover.
Industry Challenges
- Electrodialysis membrane specialist scarcity:Few European technicians possess combined expertise in dairy chemistry and stack maintenance, lengthening downtime during equipment failures.
- EFSA novel food authorization timelines:New mineral delivery formats face 18-24 month safety evaluation periods, delaying product launches and freezing R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cow Milk Minerals Market |
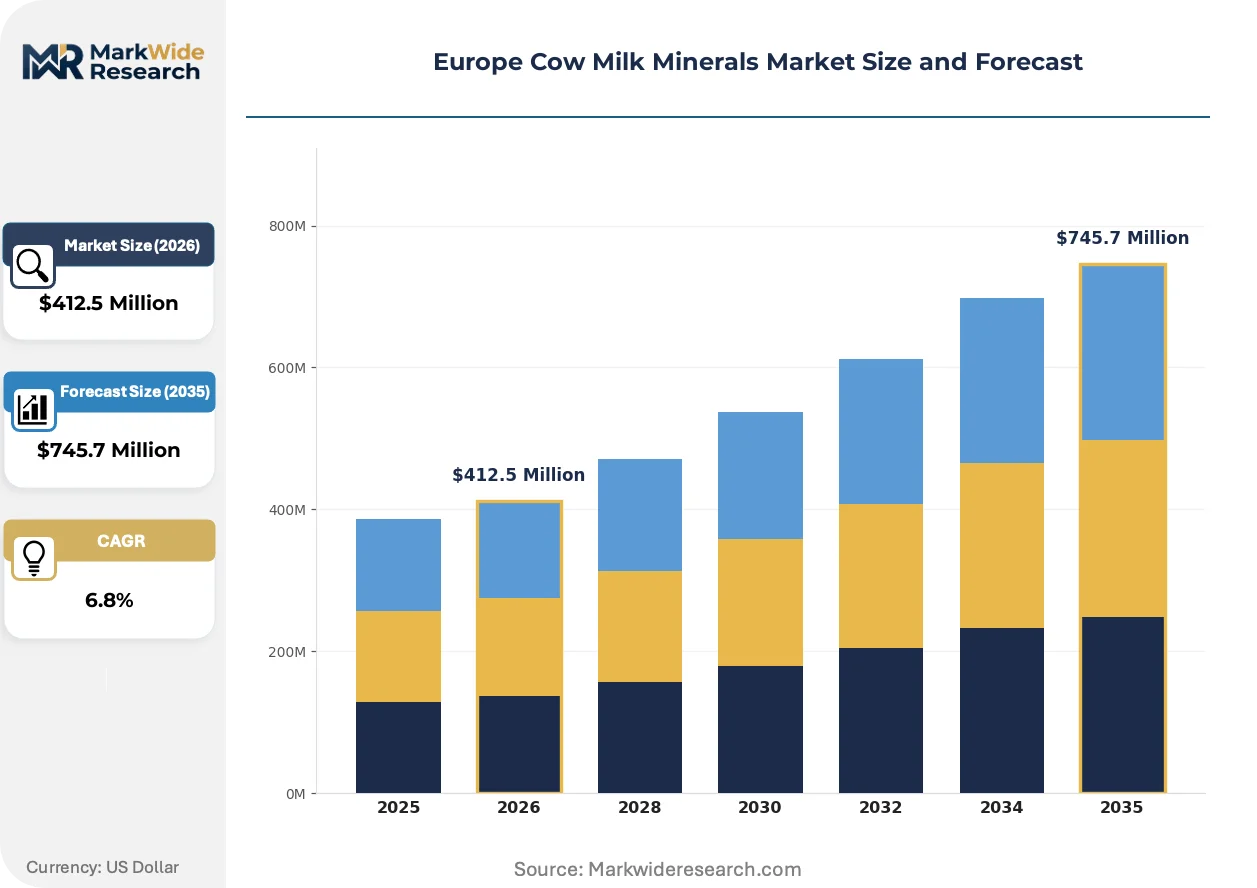
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium, Magnesium, Phosphorus, Potassium Application: Dairy Products, Infant Nutrition, Dietary Supplements, Functional Foods End User: Households, Food Manufacturers, Hospitals, Nutraceutical Companies Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Arla Foods amba, Koninklijke FrieslandCampina N.V., Groupe Lactalis, Nestlé S.A., Danone S.A., Saputo Inc., Fonterra Co-operative Group Limited, DMK Group, Emmi Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cow Milk Minerals Market Shifts & Advancements
Membrane separation technologies are fragmenting the competitive landscape between commodity mineral suppliers and precision-nutrition specialists. Three converging developments are compressing traditional extraction economics while opening premium-tier positioning.
Advanced electrodialysis with bipolar membranes is bifurcating the supplier base into high-purity specialists and commodity processors. Infant nutrition manufacturers in Germany and France are adopting this technology at accelerated cadence to achieve 24-26% calcium concentrates with reduced sodium carryover. The structural consequence is bifurcating contract terms, with premium processors commanding five-year supply agreements while commodity suppliers face annual price renegotiation.
EFSA's evolving opinions on upper intake levels for calcium and phosphorus are forcing reformulation across bone-health positioned products. The industrial consequence is a shift toward lower-dose, higher-bioavailability delivery formats that maintain label claim compliance. Functional food brands in Italy and Spain are responding fastest, pivoting from single-mineral fortification to multi-mineral complexes with synergistic absorption claims.
Ingredient buyers are consolidating supplier panels and demanding integrated carbon-accounting documentation. Dutch dairy processors are displacing fragmented mineral traders with direct cooperative partnerships that bundle mineral concentrate supply with verified Scope 3 emission data. This concentration is most visible in the Netherlands, where FrieslandCampina and Arla Foods amba have established captive mineral recovery operations that external traders cannot match on sustainability metrics.
Europe Cow Milk Minerals Market Segmentation
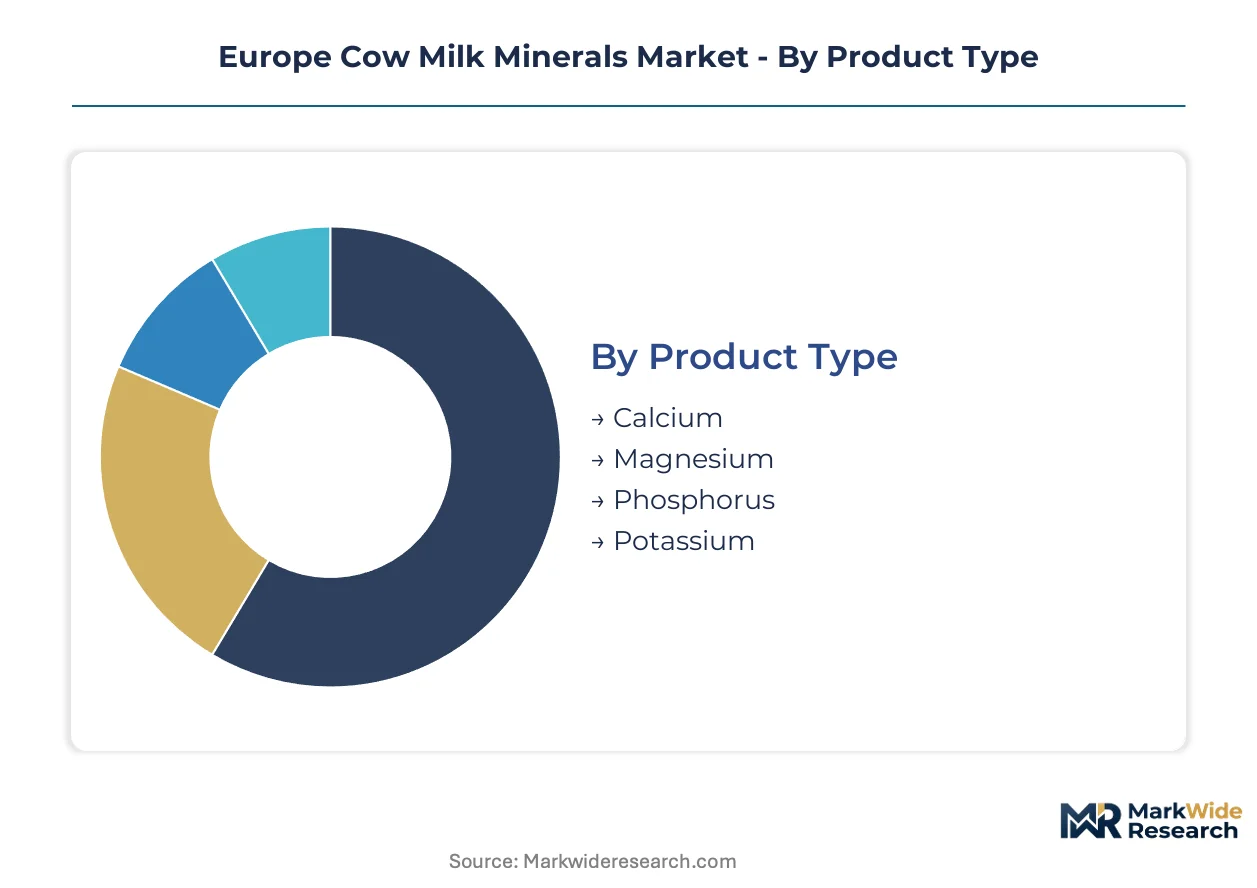
Mineral recovery economics and regulatory positioning vary sharply across product grades and buyer categories. Substitution threats from algae-derived and synthetic mineral salts are reshaping competitive dynamics within each segment tier.
Product Type:
Calcium concentrates face the strongest displacement pressure from lithothamnion and algae-sourced alternatives in vegan-positioned applications, while magnesium and phosphorus retain stronger technical moats due to bioavailability requirements in infant nutrition.
- Calcium:Concentrates achieving 20-26% calcium content through electrodialysis or ion exchange serve as the workhorse fortification mineral for bone-health positioning. German and French infant formula manufacturers are the primary demand anchors, though algae-derived calcium is capturing share in dairy-alternative applications where clean-label credentials outweigh bioavailability premiums.
- Magnesium:Milk-derived magnesium concentrates command specialized positioning in functional foods targeting muscle and nerve function claims. Italian aging-population segments and Spanish cardiovascular-positioned products drive procurement, with EFSA health claim constraints limiting permissible marketing language more severely than for calcium.
- Phosphorus:Recovered in mineral complexes rather than isolated concentrates due to processing economics, phosphorus serves structural roles in bone mineralization alongside calcium. Demand concentrates in clinical nutrition and hospital formulations where mineral ratio precision matters.
- Potassium:Lower-volume recovery stream primarily serving electrolyte-replacement applications and sports nutrition positioning. Dutch dairy processors dominate extraction due to integrated whey-side processing infrastructure.
Calcium retains volume leadership across European mineral recovery; magnesium holds the steepest expansion curve as functional food brands reformulate for multi-mineral absorption claims.
Application:
Cost tier stratification separates commodity mineral sales from premium-positioned concentrates, with infant nutrition commanding the highest specification premiums and functional foods facing the greatest margin compression from EFSA claim constraints.
- Infant Nutrition:Ultra-high purity specifications dominate this segment, with calcium concentrates requiring sub-100ppm sodium carryover and full allergen documentation. German and French manufacturing facilities are expanding procurement of electrodialysis-produced minerals to eliminate synthetic salt additives from parent-facing ingredient lists.
- Functional Foods:Bone-health and cardiovascular-positioned products in Italy and Spain drive demand, though EFSA-approved health claims are narrowing permissible marketing differentiation. Reformulation toward lower-dose, higher-bioavailability formats is compressing per-unit mineral volumes while sustaining value through complexed delivery systems.
- Dietary Supplements:Capsule and tablet applications favor spray-dried mineral concentrates with standardized particle size distribution. Direct-to-consumer brands in the Netherlands and Belgium are consolidating supplier panels to secure carbon-accounting documentation for CSRD compliance.
- Dairy Products:Fortified yogurts and drinking milks represent mature demand with limited growth upside, primarily serving aging-population calcium supplementation in Nordic markets where traditional dairy consumption remains entrenched.
Infant nutrition commands the highest purity premiums; functional foods are gaining share fastest as brands pivot toward multi-mineral positioning.
End User:
Customer type determines specification stringency and contract structure, with food manufacturers demanding multi-year supply agreements with embedded sustainability documentation while household buyers remain price-sensitive and specification-agnostic.
- Food Manufacturers:Large-scale dairy and infant formula producers in Germany, France, and the Netherlands dominate procurement volume. These buyers are consolidating supplier panels and requiring integrated Scope 3 emission data as CSRD disclosure mandates take effect.
- Nutraceutical Companies:Specialized supplement brands prioritize bioavailability documentation and EFSA-compliant health claim support over commodity pricing. Contract terms emphasize batch-specific certificate of analysis and traceability to dairy cooperative source.
- Hospitals:Clinical nutrition and enteral feeding applications demand mineral ratio precision for renal and metabolic patient populations. Procurement runs through centralized purchasing consortia with lengthy qualification timelines.
- Households:Direct consumer purchases through retail channels represent marginal volume, primarily powdered mineral supplements for home fortification. Price sensitivity limits premium positioning opportunities in this tier.
Food manufacturers dominate procurement volume; nutraceutical companies are expanding fastest as direct-to-consumer supplement brands proliferate.
Distribution Channel:
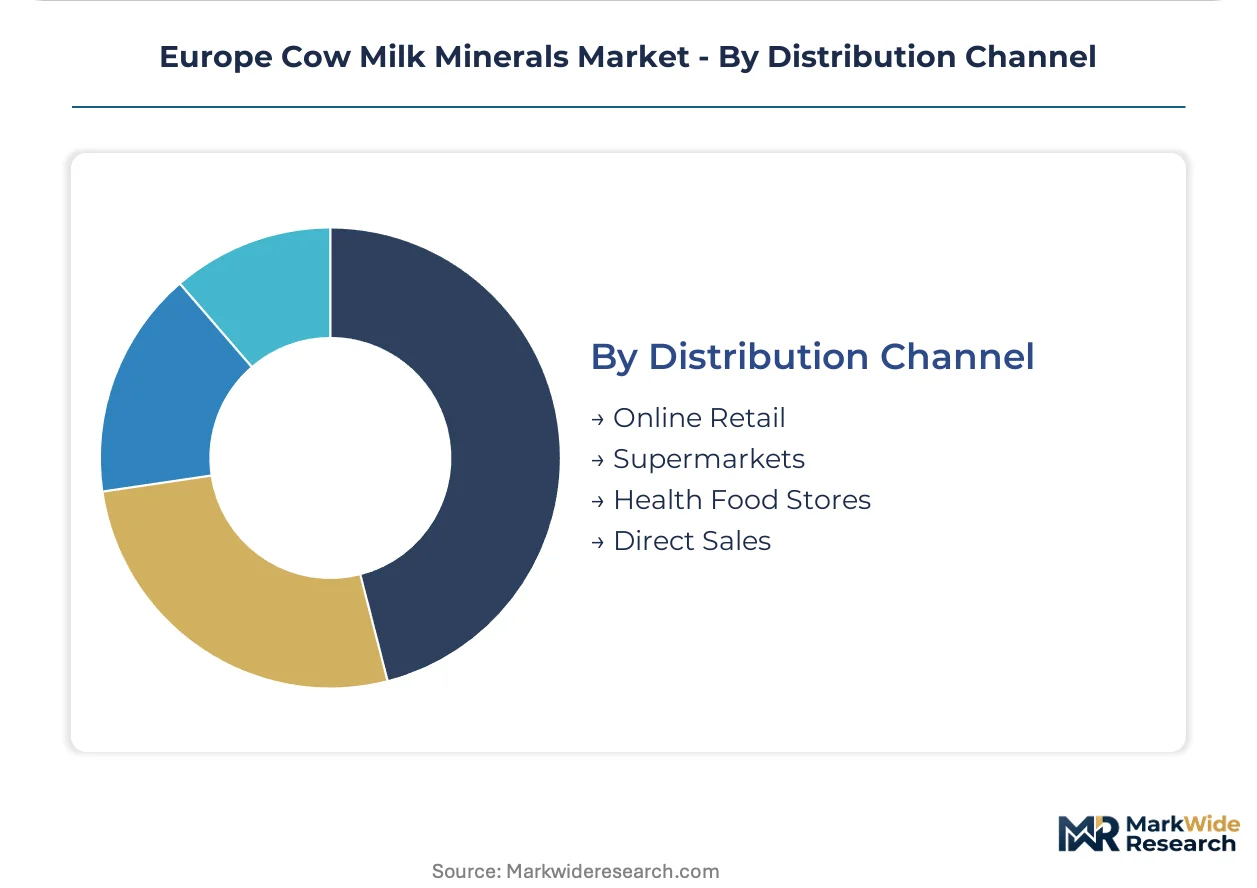
Supply concentration in Dutch processing clusters shapes channel economics, with direct sales from dairy cooperatives displacing fragmented mineral traders as large buyers demand verified sustainability documentation.
- Direct Sales:Long-term supply agreements between dairy processors and infant formula or functional food manufacturers now bundle mineral concentrates with carbon-accounting services. FrieslandCampina and Arla Foods amba leverage captive recovery operations to lock out external traders on sustainability metrics.
- Online Retail:Direct-to-consumer supplement brands in Germany and the Netherlands are building digital-first distribution for powdered mineral concentrates, though volumes remain small relative to B2B channels.
- Supermarkets:Mass-market fortified dairy products and basic supplements reach consumers through conventional grocery retail, with limited differentiation opportunity for mineral ingredient suppliers.
- Health Food Stores:Specialty retail channels serve niche demand for organic-positioned and grass-fed-sourced mineral supplements, primarily in German and Austrian markets with strong natural products retail infrastructure.
Direct sales channels command the largest transaction values; online retail is climbing the fastest as digital-native supplement brands scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European procurement clusters. German and French infant formula manufacturers absorb premium pricing for electrodialysis-grade minerals, while Italian and Spanish functional food brands negotiate aggressively on standard-grade contracts.
Germany
Infant nutrition manufacturers in Bavaria and North Rhine-Westphalia drive ultra-high purity demand, requiring sub-100ppm sodium carryover in calcium concentrates. EFSA nutrition claims regulations constrain permissible bone-health marketing language, forcing reformulation toward lower-dose formats. The Munich-Stuttgart corridor hosts dense clusters of dairy technology firms upgrading electrodialysis capacity.
France
Groupe Lactalis and independent processors in Brittany and Normandy dominate whey fractionation infrastructure, anchoring phosphorus and calcium recovery streams. ANSM and EFSA dual oversight tightens novel food authorization timelines for new mineral delivery formats. The Loire Valley processing belt is expanding ion-exchange optimization to meet clean-label infant formula procurement.
Netherlands
FrieslandCampina's captive mineral recovery operations in the Randstad region lock out external traders through bundled Scope 3 carbon-accounting services. REACH frameworks mandate documented emission reductions from extraction processes. Eindhoven-Brabant dairy technology clusters are deploying hybrid electrodialysis-nanofiltration systems for simultaneous mineral concentration and lactose reduction.
Italy
Aging-population functional food brands in Lombardy and Emilia-Romagna drive magnesium procurement for cardiovascular positioning claims. EFSA-approved health claims narrow permissible marketing differentiation, compressing margins on single-mineral fortification. The Po Valley dairy processing corridor is pivoting toward multi-mineral complex formulations to sustain premium pricing.
Poland
Underdeveloped mineral recovery infrastructure in Mazovia and Silesia creates first-mover openings for electrodialysis technology licensors. EU Green Deal sustainability mandates accelerate capital deployment toward emission-reducing extraction upgrades. The Warsaw-Łódź manufacturing belt is attracting Dutch and Danish dairy processors seeking lower-cost processing capacity with CSRD-compliant documentation.
Europe Cow Milk Minerals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European cow milk minerals sector. High-purity specialists command five-year supply agreements through electrodialysis mastery, while commodity processors compete on annual price renegotiation. The market structure bifurcates into backward-integrated dairy cooperatives, independent mineral concentrate specialists, and diversified nutrition conglomerates. Dominant competitive moves include captive recovery operation expansion and carbon-accounting service bundling.
Among backward-integrated dairy cooperatives, Arla Foods amba, Koninklijke FrieslandCampina N.V., and Groupe Lactalis occupy positions that external traders cannot replicate on sustainability metrics. Arla Foods amba represents the Danish cooperative archetype with upstream control over milk mineral extraction. FrieslandCampina anchors the Dutch processing cluster through proprietary demineralization technology deployment. Groupe Lactalis exemplifies the French-Italian fractionation capacity model across whey and milk mineral recovery.
| Leading Market Players |
|---|
| Arla Foods amba |
| Koninklijke FrieslandCampina N.V. |
| Groupe Lactalis |
| Nestlé S.A. |
| Danone S.A. |
| Saputo Inc. |
| Fonterra Co-operative Group Limited |
| DMK Group |
| Emmi Group |
| Others |
Supply & Pricing Matrix
Electrodialysis capacity utilization rates in Dutch processing clusters establish price floors that commodity suppliers in peripheral markets cannot match without sacrificing margin. Scale concentration around FrieslandCampina's Randstad facilities and Arla's Danish cooperative structure creates tiered procurement power, with infant formula manufacturers absorbing premiums while functional food brands drive standard-grade negotiations.
Pricing Analysis
EFSA nutrition claims regulation dictates the pricing tier structure across European mineral concentrate procurement. Three-tier pricing structure across premium, standard, and economy levels separates electrodialysis-grade calcium with sub-100ppm sodium carryover from ion-exchange standard grades and commodity spray-dried powders. Cost compression in standard-tier contracts is intensifying because Polish and Romanian processors are expanding capacity with lower labor and energy inputs. Functional food manufacturers in Italy and Spain exhibit highest price sensitivity, while German infant formula facilities accept five-year agreements with embedded sustainability premiums.
Supply Chain Analysis
Strategic stockpiling of membrane components and spare electrodialysis stacks characterizes inventory strategy among Dutch and Danish processors facing specialist technician scarcity. Supply concentrates in the Netherlands, Denmark, and France, with Poland emerging as a lower-cost processing alternative. Raw material dependencies center on bovine milk supply from cooperative farms, ion-exchange resins subject to REACH chemical safety thresholds, and electrodialysis membranes sourced from specialized polymer suppliers. Single-source vulnerability runs through membrane stack maintenance expertise concentrated in Eindhoven-Brabant technology clusters. Distribution runs through direct cooperative partnerships that bundle mineral concentrates with verified Scope 3 emission documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of technicians possessing combined dairy chemistry and electrodialysis stack maintenance expertise constrains capacity expansion and sustains incumbent pricing power. This capability gap shapes competitive dynamics across all strategic archetypes operating in European mineral recovery.
For Market Incumbents: Fortify captive recovery operations through backward integration into Polish and Romanian dairy processing infrastructure before technology licensors establish presence. Expand hybrid electrodialysis-nanofiltration deployment to unlock whey-side value streams and defend margin position against commodity displacement from algae-derived calcium substitutes. For New Entrants and Emerging Players: Differentiate on carbon-accounting service bundling to meet CSRD disclosure mandates that incumbent cooperatives are slow to productize. Target underdeveloped mineral recovery infrastructure in Mazovia and Silesia with technology licensing partnerships, leveraging Dutch processor reluctance to expand into lower-margin Eastern European markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrodialysis-grade specialists with five-year infant nutrition supply agreements and embedded sustainability documentation services. Long-term viability rests on acquisition of membrane technology firms or dairy processors with verified Scope 3 data infrastructure. Watch EFSA opinions on upper intake levels as the signal indicating reformulation-driven demand shifts toward lower-dose, higher-bioavailability delivery formats.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Electrodialysis-Nanofiltration Deployment | Simultaneous mineral concentration and lactose reduction unlocks whey-side value streams previously uneconomical to recover. |
| CSRD-Compliant Carbon-Accounting Service Bundling | Suppliers monetize emission documentation expertise as procurement differentiator against commodity traders lacking verification infrastructure. |
| Eastern European Technology Licensing | Polish and Romanian dairy expansion creates first-mover openings for electrodialysis licensors before incumbent cooperatives establish presence. |
| Membrane Stack Maintenance Capability Building | Specialist scarcity in combined dairy chemistry and electrodialysis expertise lengthens downtime during equipment failures. |
| Multi-Mineral Complex Formulation Pivot | EFSA upper intake level constraints force shift from single-mineral fortification toward synergistic absorption claims in functional foods. |
Research Methodology
The analysis maps calcium, magnesium, phosphorus, and potassium concentrate sub-sectors, each validated through electrodialysis plant managers, infant formula procurement leads, dairy cooperative technical directors, and EFSA regulatory affairs specialists. Primary interview findings were cross-referenced with secondary sources including REACH chemical safety registrations, EU Green Deal implementation documents, CSRD disclosure guidance, and dairy processing trade association capacity surveys. Bottom-up mineral recovery volume estimates were triangulated against top-down infant formula and functional food production data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled mineral type, application purity tier, end-user procurement structure, and regional processing cluster as segmentation dimensions. CAGRs were derived from supply-side capacity expansion timelines and demand-side reformulation trends in infant nutrition and functional foods. Forecast inputs incorporated EFSA opinion evolution on mineral upper intake levels and CSRD disclosure mandate implementation pacing.
The analysis sits within stated boundaries; outcomes outside stable EFSA regulatory frameworks and continued EU Green Deal enforcement would require recalibration. Forecasts reflect assumptions around electrodialysis technology diffusion rates and cooperative dairy sourcing patterns. Practitioners should keep alternative scenarios live as algae-derived mineral substitute cost curves and Eastern European processing capacity buildouts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Buttermilk Powder Market
Dairy Products
Nonfat Dry Milk Market
Dairy Products
Halloumi Cheese Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Ghee Market
Dairy Products
A2 Protein Milk Market
Dairy Products
Goat Milk Powder Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
White Cheese Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
GCC Dairy Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Sour Cream Market