
 Low Fat Yogurt Market | 2026-2036
Low Fat Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Yogurt Market Intelligence
Value-added product development, particularly in probiotic and Greek yogurt formats, is reconfiguring the margin landscape away from traditional flavored yogurts. Chobani leads this shift in the United States with its strong brand identity in the Greek yogurt category. Danone leverages extensive R&D to fortify its market position in probiotic-rich offerings globally. Fage International differentiates through its focus on authentic, high-protein Greek yogurt formulations, commanding a premium price point.
Low fat yogurt is a fermented dairy product created by the bacterial fermentation of milk, specifically formulated to contain less than 3 grams of fat per standard serving. Its primary commercial purpose is to provide a nutrient-dense, lower-calorie alternative to full-fat dairy, often enriched with probiotics. Within product types, Greek yogurt commands a significant value share due to its higher protein content, while drinkable yogurt represents the fastest-growing segment. Supermarkets remain the dominant distribution channel, though online stores are rapidly expanding their reach for specialty and bulk purchases.
Product formulations and marketing claims are governed by strict nutritional labeling standards from regulators like the United States FDA and the European Food Safety Authority (EFSA). In emerging economies like India, the FSSAI sets comparable guidelines for fat content and dairy product safety, influencing market entry. Producers must continually balance consumer demand for clean-label ingredients against the technical challenges of maintaining taste and texture in low-fat formulations.
Market Dynamics
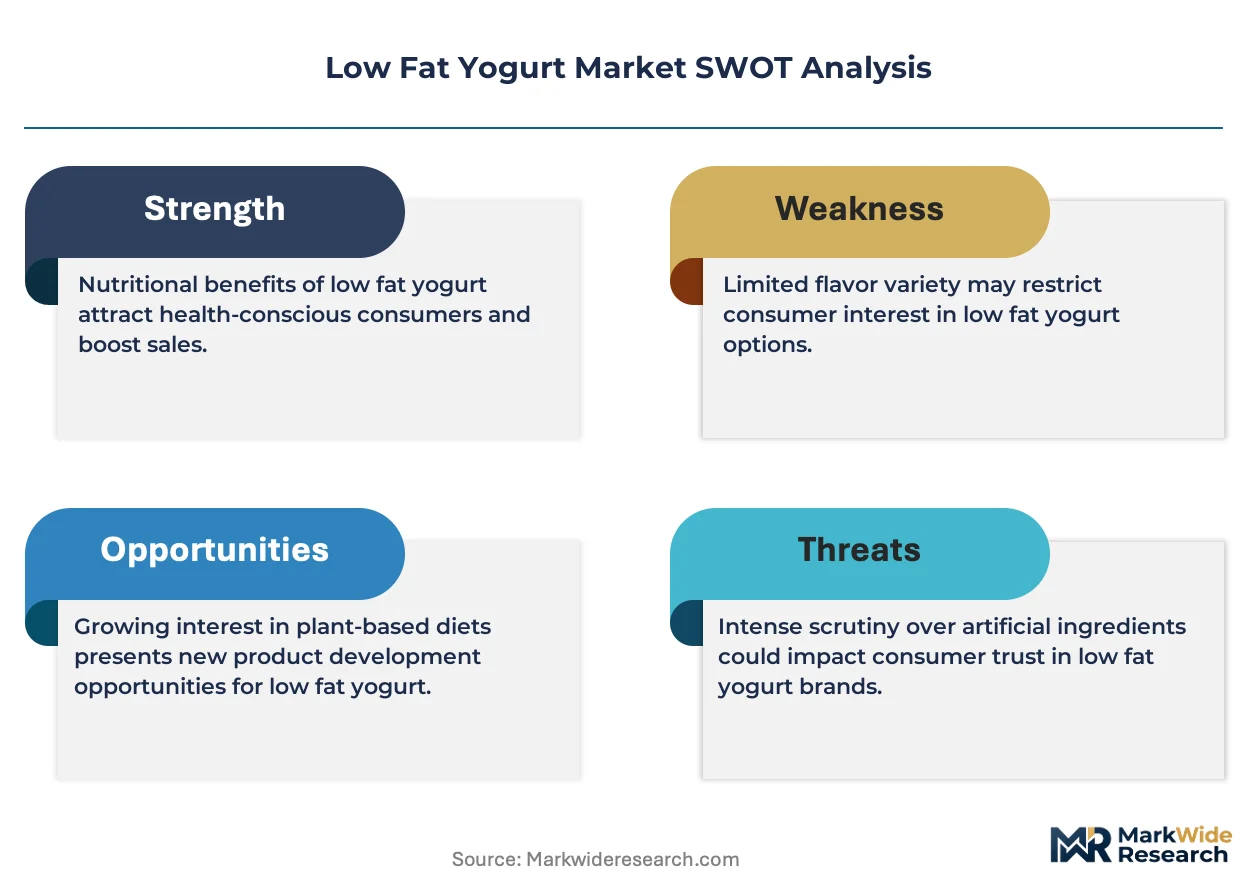
The central tension between consumer demand for clean-label, functional ingredients and the technical challenges of maintaining taste in low-fat formulations defines the market. This pressure forces constant R&D investment to meet evolving wellness expectations without sacrificing sensory appeal.
Growth Catalysts
- Consumer Health Focus:Intensifying consumer preference for foods that support digestive health and weight management propels demand, particularly for products high in protein and probiotics and low in sugar.
- Regulatory Clarity:The European Food Safety Authority's structured framework for health claims allows manufacturers to communicate the benefits of probiotic content more effectively, building consumer trust and justifying premium pricing.
- Infrastructure Expansion:The build-out of cold chain logistics in developing economies like Brazil and India enables the distribution of perishable yogurt products to a wider, previously inaccessible consumer base.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of raw milk, a primary input, create margin pressure and introduce unpredictability into the production cost structure for yogurt manufacturers.
- Plant-Based Substitution:The growing popularity and improving quality of dairy-free yogurt alternatives made from almond, soy, and oat milk present a direct substitution threat, capturing health-conscious consumers.
- Formulation Hurdles:Achieving a creamy texture and rich flavor in low-fat yogurt without using sugar or artificial additives remains a significant technical challenge, affecting product acceptance.
Strategic Opportunities
- Geographic Expansion:Significant white space exists in Southeast Asian markets where rising disposable incomes, urbanization, and a nascent focus on wellness create fertile ground for market entry.
- Targeted Formulations:There is an opportunity to develop specialized products catering to specific dietary needs, such as ketogenic, lactose-intolerant, or plant-fortified low-fat yogurt lines.
- Functional Ingredient Innovation:Incorporating novel ingredients beyond probiotics, such as adaptogens, nootropics, or plant-based fibers, can create new value-added categories targeting mental and physical well-being.
Industry Challenges
- Cold Chain Management:Ensuring temperature integrity across increasingly complex and extended supply chains is a critical operational hurdle that requires significant investment in logistics and monitoring technologies.
- Regulatory Navigation:Adhering to disparate and evolving nutritional labeling standards from bodies like the US FDA and India's FSSAI complicates product development and international market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Yogurt Market |
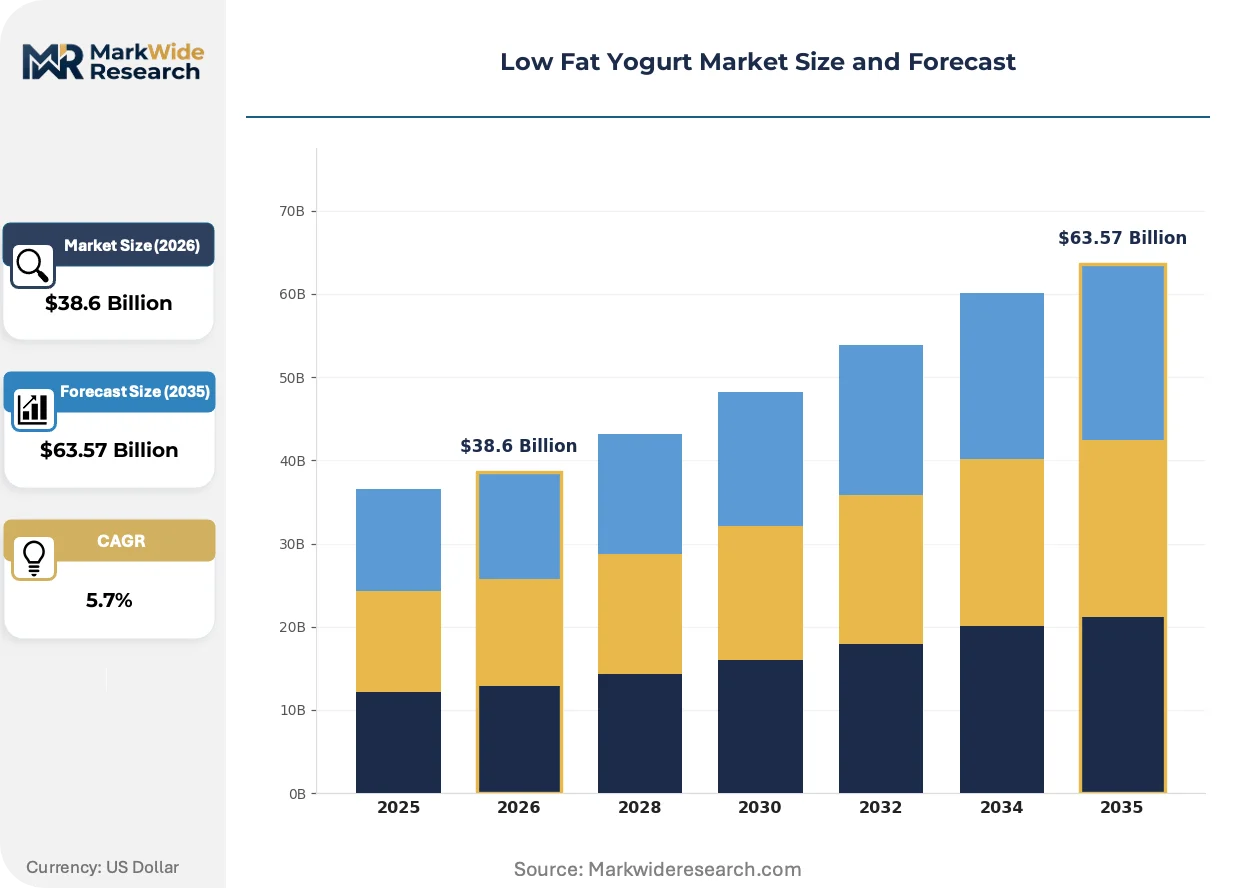
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $63.57 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Drinkable Yogurt, Probiotic Yogurt, Organic Yogurt, Flavored Yogurt Packaging Type: Plastic Cups, Tetra Pak Cartons, Glass Bottles, Sachets, PET Bottles Distribution Channel: Supermarkets, Convenience Stores, Specialty Retailers, Online Stores, Wholesale Clubs Consumer Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | Danone, Chobani, Nestlé, General Mills, Fage International, CP-Meiji Company, Muller UK & Ireland Group, Tillamook, Juhayna Food Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Yogurt Market Strategic Shifts & Innovations
Product development is increasingly influenced by the intersection of food science and data-driven personalization. This convergence allows for the creation of yogurt with specific functional benefits, supported by transparent sourcing and clear nutritional information that resonates with discerning consumers.
Precision fermentation technology enables the creation of specific dairy proteins and functional ingredients using engineered microorganisms. Food-tech firms and established dairy companies are adopting this process to develop novel components, such as whey and casein, without animal inputs. This innovation is digitizing the ingredient supply chain, allowing for on-demand production of customized, high-purity components independent of traditional agricultural cycles.
New "healthy" claim rules from the United States FDA are reshaping product formulation. The regulation mandates that foods using the claim contain a meaningful amount of a key food group while limiting sodium, added sugars, and saturated fat. This policy directly impacts the low-fat yogurt category, compelling manufacturers to reduce sugar content to qualify for this valuable on-package marketing designation.
Consumer purchasing habits are moving away from large, weekly supermarket trips toward smaller, on-demand buys through quick-commerce platforms. This behavioral shift disrupts the traditional retail model where multi-packs dominated, creating an opening for single-serve products on delivery apps and in urban convenience stores. The trend is most visible in dense metropolitan areas across North America and Western Europe.
Low Fat Yogurt Market Segmentation
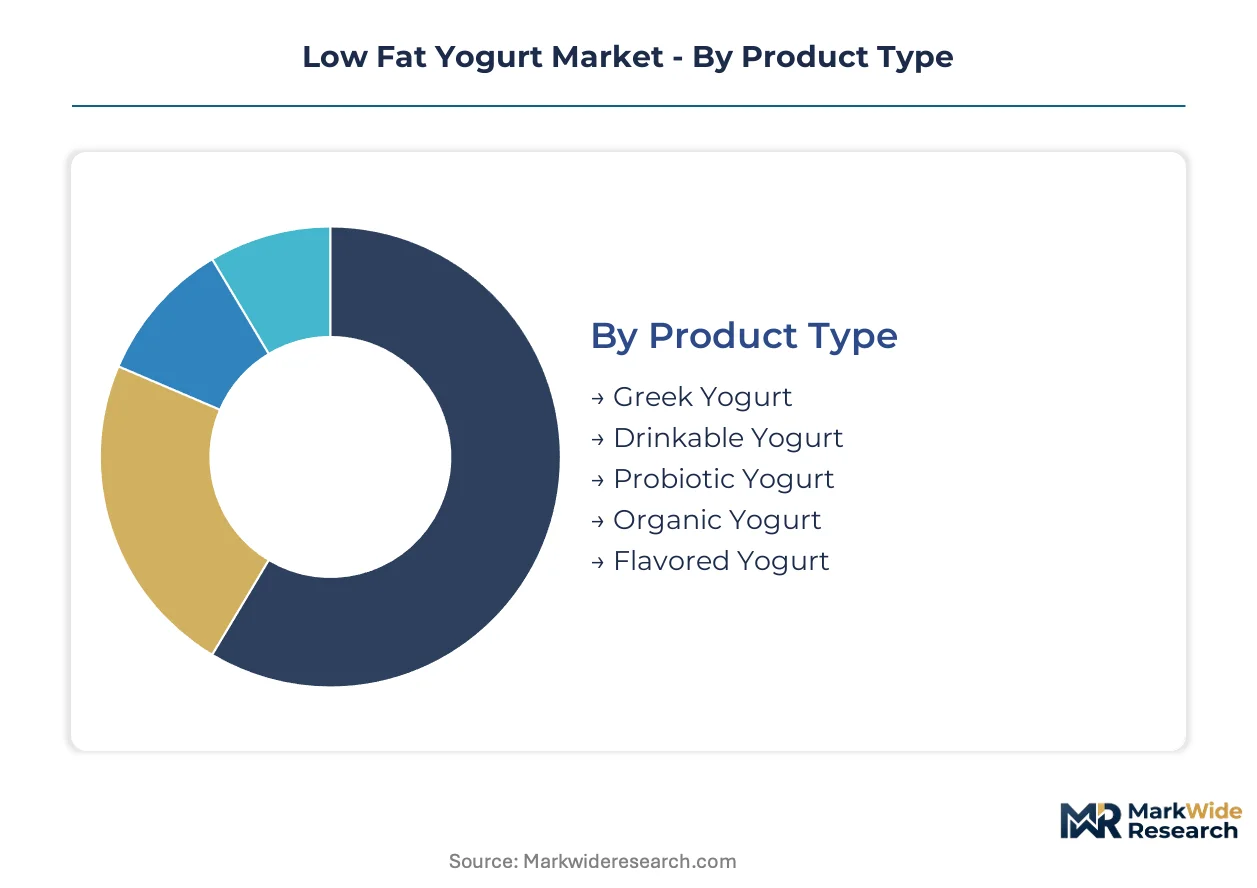
Market segmentation offers a granular view of the Low Fat Yogurt industry, revealing distinct consumer preferences and operational dynamics across various product types, packaging formats, distribution channels, and consumer demographics. Understanding these segments is critical for manufacturers to tailor product development, optimize marketing strategies, and allocate resources effectively for sustained growth.
Product Type:
Product type segmentation highlights how different formulations exhibit varying consumer adoption cycles, from rapid innovation to established staples.
- Greek Yogurt:This product is characterized by a thicker texture and higher protein content, achieved through a straining process. Demand concentrates in developed markets like the United States, driven by consumer wellness trends prioritizing satiety and muscle health.
- Drinkable Yogurt:These liquid formulations offer convenience for on-the-go consumption, often enriched with probiotics for digestive benefits. Demand is expanding rapidly across North America and Western Europe, propelled by busy lifestyles and preference for functional beverages.
- Probiotic Yogurt:Formulations containing live active cultures specifically target digestive health, appealing to health-conscious consumers globally.
- Organic Yogurt:Produced from milk sourced from organic-certified farms, this segment appeals to consumers prioritizing natural ingredients and sustainable practices.
- Flavored Yogurt:These products incorporate various fruit, vanilla, or chocolate flavors, primarily targeting younger demographics and consumers seeking indulgent options.
Flavored Yogurt anchors the volume base while Drinkable Yogurt gains share at the steepest rate.
Packaging Type:
Packaging type dictates storage efficiency and consumer convenience, with high-volume formats often prioritizing cost-effectiveness and shelf stability.
- Plastic Cups:These ubiquitous containers offer cost-effective packaging for single-serve and multi-serve yogurt portions, ensuring product integrity and extended shelf life. High volume demand exists across all retail channels in Europe and the United States, driven by manufacturing efficiency and consumer familiarity.
- PET Bottles:Made from clear, lightweight polyethylene terephthalate, these bottles are primarily used for drinkable yogurt, offering portability and resealability. Consumer preference in Brazil and India for on-the-go dairy options drives significant growth in this segment.
- Tetra Pak Cartons:These multi-layered aseptic cartons provide extended shelf life without refrigeration, particularly for ambient yogurt drinks in emerging markets.
- Glass Bottles:Offering a premium aesthetic and perceived purity, glass bottles cater to niche markets and specialty brands emphasizing natural or organic ingredients.
- Sachets:Single-serving flexible pouches provide an ultra-affordable and convenient option, widely adopted in cost-sensitive Asian and African markets.
Plastic Cups dominate primary packaging applications, while PET Bottles demonstrate rapid expansion driven by convenience trends.
Distribution Channel:
Distribution channel segmentation reflects distinct purchasing behaviors, from routine grocery shopping to impulse buys and specialty product sourcing.
- Supermarkets:These large-format retail stores remain the primary point of sale, offering a wide selection of brands and product types to mass-market consumers. Supermarkets in Germany and the UK drive significant sales volume due to extensive cold chain infrastructure and established shopping habits.
- Online Stores:E-commerce platforms provide convenience and access to specialty or bulk purchases, increasingly catering to urban consumers seeking home delivery. Demand is accelerating in the United States and China as digital retail infrastructure matures and consumer comfort with online grocery grows.
- Convenience Stores:These smaller retail outlets cater to impulse purchases and immediate consumption needs, particularly for single-serve drinkable yogurts.
- Specialty Retailers:Health food stores and organic markets offer curated selections of premium, organic, or niche low-fat yogurt products to discerning consumers.
- Wholesale Clubs:These membership-based stores sell bulk quantities at discounted prices, appealing to large families and businesses seeking value.
Supermarkets maintain a stronghold on market volume, while Online Stores are quickly reconfiguring access for niche and bulk purchases.
Consumer Age Group:
Consumer age group segmentation reveals varying price sensitivities and willingness to pay for specific functional benefits, influencing product margin potential.
- Adults:This segment represents the largest consumer base, driven by health consciousness, weight management goals, and demand for probiotic-rich products. High-margin product innovation targets adults in Japan and France, where functional food adoption is advanced.
- Seniors:Older adults seek low-fat yogurt for digestive health, bone strength, and protein intake, often preferring fortified or easy-to-consume formats. The aging populations in Italy and Canada represent a growing market for specialized, high-value formulations tailored to their nutritional needs.
- Children:Young consumers primarily drive demand for flavored and fruit-infused low-fat yogurts, often in appealing packaging formats.
- Adolescents:This group seeks convenient, on-the-go options and protein-rich yogurts for energy and muscle recovery, often influenced by peer trends.
Adults constitute the largest and most diverse consumer base, while Seniors demonstrate the highest potential for specialized, value-added products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The low fat yogurt market exhibits varied demand elasticity across geographies. Developed markets often show lower price sensitivity for premium, functional products, reflecting a willingness to pay for specific health benefits. Emerging economies, conversely, exhibit higher price sensitivity, prioritizing affordability and basic nutrition in their purchasing decisions.
United States
United States consumers prioritize functional benefits such as high protein and probiotics for digestive health and weight management. The United States FDA's updated "healthy" claim rules compel manufacturers to reduce sugar content for valuable on-package marketing designations. California's health and wellness industry sees significant product innovation, particularly in Greek yogurt and probiotic formulations.
Germany
German consumers seek organic products and clean-label ingredients, driving demand for sustainably sourced low-fat yogurt. The European Food Safety Authority (EFSA) provides a structured framework for health claims, enabling clear communication of probiotic benefits. Munich's food manufacturing cluster actively develops specialized dairy formulations meeting these stringent consumer preferences.
India
India's market expansion is driven by rising disposable incomes, urbanization, and a nascent focus on digestive health. The FSSAI sets comparable guidelines for fat content and dairy product safety, influencing market entry and product formulation. Mumbai and Delhi metros experience increasing adoption of packaged yogurt, supported by improving cold chain logistics.
Brazil
Brazilian demand for low-fat yogurt is fueled by a preference for convenient, on-the-go dairy options and functional beverages. ANVISA, the national health surveillance agency, establishes food safety and labeling standards for dairy products. São Paulo's dynamic consumer market drives significant growth in drinkable yogurt formats, catering to busy lifestyles.
Japan
Japanese consumers demonstrate advanced functional food adoption, particularly for products supporting senior nutrition and probiotic benefits. The Ministry of Economy, Trade and Industry (METI) promotes research and development in health-focused food products. Tokyo's food science institutes collaborate on novel ingredient integration, enhancing the nutritional profile of low-fat yogurt offerings.
Low Fat Yogurt Market Key Industry Players
Capability concentration sits with one tier of specialized producers focused on functional ingredients; scale advantage sits with another tier of diversified food conglomerates. The market structure is tiered, featuring established mass-market producers, agile value-added specialists, and regional players with strong local distribution networks. Dominant competitive moves include portfolio diversification into new product formats and strategic geographic expansion into underserved markets.
Specialists in probiotic and Greek yogurt formats often anchor market innovation. Danone, a global food company, exemplifies a player with extensive R&D dedicated to fortifying probiotic-rich offerings. Chobani, a United States-based brand, represents a strong identity in the Greek yogurt category, emphasizing its strained, high-protein formulations. Fage International, with its focus on authentic, high-protein Greek yogurt, commands a premium price point, differentiating through traditional formulations and perceived quality.
| Leading Market Players |
|---|
| Danone |
| Chobani |
| Nestlé |
| General Mills |
| Fage International |
| CP-Meiji Company |
| Muller UK & Ireland Group |
| Tillamook |
| Juhayna Food Industries |
| Others |
Cost & Logistics Intelligence
Raw milk supply fluctuations significantly influence both producer behavior and market pricing for low-fat yogurt. Overcapacity in dairy regions can depress input costs, while processing bottlenecks for specialized formats create pricing power for manufacturers.
Pricing Analysis
Premium product segments, particularly organic and high-protein Greek yogurt, drive significant value beyond basic offerings. The dominant pricing model combines value-based pricing for functional formulations with transactional pricing for conventional products. Price differentiation stems from organic certification and established brand premiums like Fage International. Pricing softness affects traditional flavored yogurts due to plant-based substitution, while input cost volatility creates margin pressure. Consumers buying for specific health benefits, such as seniors, exhibit lower price sensitivity compared to those purchasing flavored options for children.
Supply Chain Analysis
Dairy processing capacity concentrates in established markets like the United States and Germany, alongside emerging hubs in India. The supply chain relies heavily on raw milk, specific probiotic cultures, and fruit purees as key inputs. Cold chain management across increasingly complex distribution networks represents a critical structural risk for perishable low-fat yogurt products. Distribution primarily runs through supermarkets for mass-market offerings, while online stores facilitate specialty and bulk purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-fat yogurt market is experiencing a cyclical recovery, driven by renewed consumer focus on health and wellness as disposable incomes rebound. This shift favors functional food categories offering specific nutritional benefits.
For Market Incumbents: Insulate core market share by investing heavily in R&D to overcome formulation hurdles for taste and texture in low-fat products. Diversify product portfolios to include high-quality plant-based alternatives, directly countering the substitution threat from almond and oat milk yogurts. Strengthen cold chain logistics and distribution networks to maintain competitive advantage in perishable product delivery. Leverage established brand equity to launch new functional formats, reinforcing consumer trust.
For New Entrants and Emerging Players: Southeast Asian markets, characterized by rising disposable incomes and nascent wellness trends, represent a penetrable entry point for low-fat yogurt. Target specialized dietary needs with formulations for ketogenic or lactose-intolerant consumers. A compelling go-to-market angle involves incorporating novel functional ingredients like adaptogens or nootropics, creating distinct value propositions beyond probiotics. Focus on convenient single-serve formats for urban consumers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across specialized processing for functional ingredients within the low-fat yogurt market. The sector demonstrates strong long-term viability, particularly for brands excelling in functional and premium segments. Acquisition targets should include agile value-added specialists with strong R&D in novel ingredients or established regional players with robust distribution. Watch for regulatory updates from the United States FDA or European Food Safety Authority on health claims as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Diversify into Plant-Based Formulations | Mitigates substitution threat from dairy-free alternatives and expands consumer reach. |
| Invest in Cold Chain Logistics | Ensures product integrity and extends market access, particularly in emerging economies. |
| Focus on Functional Ingredient R&D | Creates new value-added categories and addresses evolving consumer health demands. |
| Geographic Expansion into Southeast Asia | Captures growth from rising disposable incomes and increasing wellness focus in underserved markets. |
| Optimize for "Healthy" Claim Compliance | Unlocks valuable on-package marketing designations and builds consumer trust in nutritional benefits. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association reports, and retail scanner data. This study conducted in-depth interviews with R&D directors, procurement leads, brand managers, and retail buyers across key geographies. The analysis employed both bottom-up and top-down triangulation to ensure comprehensive data validation and accuracy.
Forecast inputs considered include historical market performance, macroeconomic indicators, and evolving consumer preferences across the analysis window. The analytical framework modeled segmentation dimensions such as product type, packaging type, distribution channel, consumer age group, and regional regulatory clusters. Compound Annual Growth Rates were derived from a multi-factor regression analysis, integrating raw milk price trends and health claim adoption rates.
Practitioners should monitor significant regulatory changes, input cost volatility, and disruptive plant-based innovations for early signals of market shifts. This analysis reflects assumptions based on current market dynamics and available data. Quarterly review of consumer trends and competitive landscape adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Kuwait Dairy Products Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Concentrated Milk Fat Market
Dairy Products
Halal Cheese Market
Dairy Products
Organic Cheese Market
Dairy Products
Organic Dairy Market
Dairy Products
Green Tea Butter Market
Dairy Products
Citrus Yogurt Market
Dairy Products
South America Flavored Milk Market
Dairy Products
Dairy Products Market
Dairy Products
Evaporated Milk Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
China Milk Protein Market
Dairy Products
Global Milk Powder Market