
 Nonfat Dry Milk Market | 2026-2036
Nonfat Dry Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Nonfat Dry Milk Market Analysis
Multi-source procurement among large dairy processors is restructuring supply relationships across the nonfat dry milk value chain. Glanbia Ingredients Ireland Limited leverages its Irish processing base to sustain European supply contracts for nutritional applications. DairyAmerica Inc. anchors North American volume through cooperative member networks across California and the Upper Midwest. Hilmar Cheese Company differentiates via whey and milk protein specialization that extends into adjacent dry milk product lines.
Nonfat dry milk is skim milk dehydrated to remove nearly all moisture, yielding a shelf-stable powder with protein content typically exceeding 36% and moisture below 5%, produced through spray-drying or roller-drying processes for reconstitution or ingredient use. The powder serves as a functional protein and solids source in formulated foods where liquid milk logistics prove uneconomical. Instant nonfat dry milk dominates retail and HoReCa channels where rapid reconstitution determines purchasing decisions, while spray-dried nonfat milk captures food manufacturer volume through superior solubility and consistent particle size. Infant formula applications command premium positioning within the application mix due to stringent protein standard and microbiological specifications.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that govern dry milk plant sanitation and pathogen testing protocols for interstate commerce. USDA dairy grading programs create quality tiers that influence export eligibility and price formation in international tenders. Stakeholders must monitor evolving EU MDR-aligned nutritional labeling requirements and Codex Alimentarius revisions that could reshape compositional standards for cross-border dry milk trade.
Market Dynamics
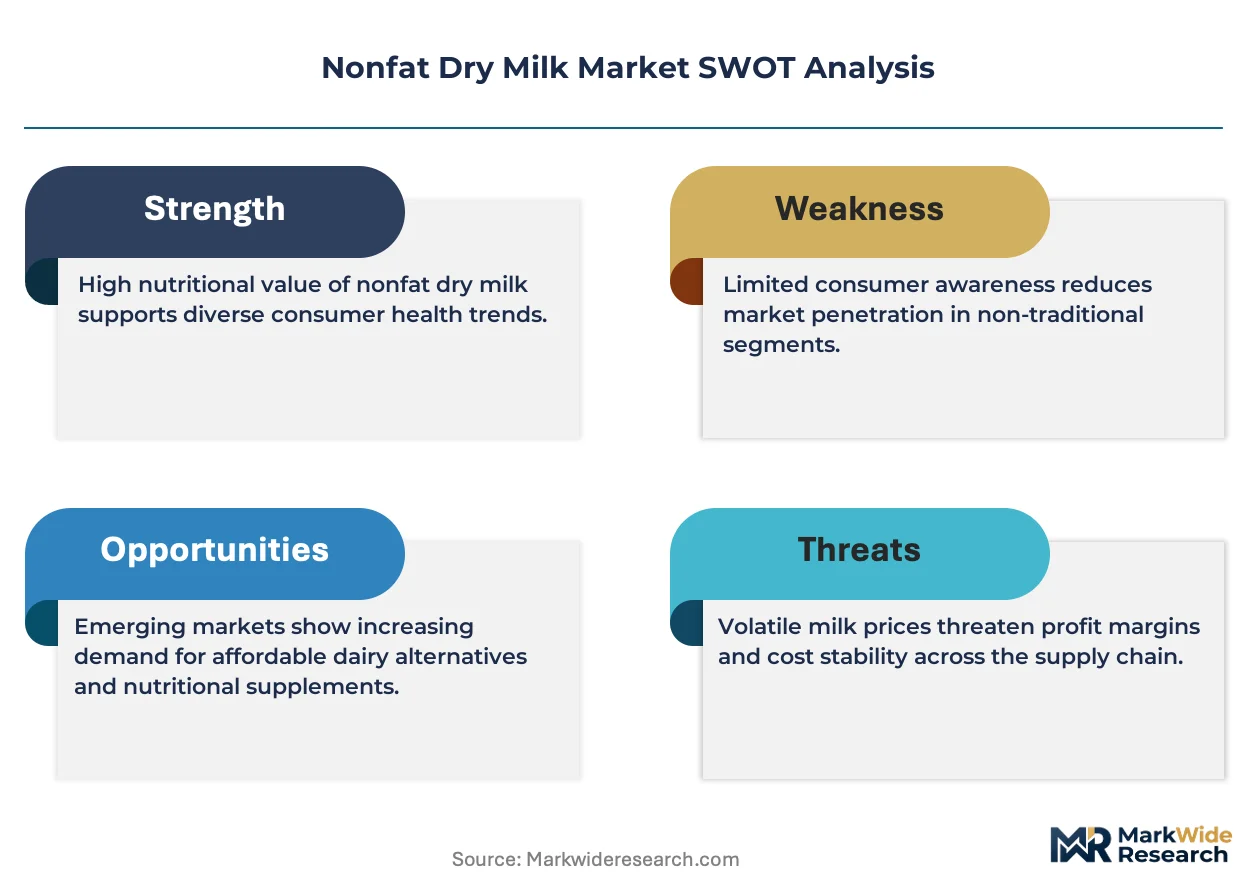
Spray-drying technology improvements are compressing moisture specifications below 3.5% while expanding particle size control, forcing processors to retool or exit commodity-grade production entirely.
Growth Catalysts
- ASEAN dairy processing expansion:Vietnam and Indonesia are building import-dependent powder-to-liquid reconstitution plants to bypass cold-chain limitations for bakery and confectionery supply.
- FDA Grade A Pasteurized Milk Ordinance enforcement:Interstate commerce rules now mandate enhanced pathogen testing protocols that favor large-scale processors with in-house laboratory capacity.
- Instantization technology:Agglomeration processes that improve cold-water solubility are unlocking HoReCa channel penetration where rapid reconstitution determines supplier selection.
Market Restraints
- Skim milk concentrate input volatility:Raw fluid milk price swings in California and Wisconsin cooperative networks transmit directly to nonfat dry milk production economics.
- EU MDR-aligned nutritional labeling complexity:Cross-border dry milk trade faces compositional standard revisions that threaten existing export eligibility tiers for non-EU processors.
- Whey protein concentrate substitution:Sports nutrition and clinical formula manufacturers are reformulating with higher-protein whey isolates that displace nonfat dry milk in performance positioning.
Strategic Opportunities
- Infant formula microbiological premiumization:Stringent protein standard specifications create pricing separation from commodity-grade powder for processors achieving Codex Alimentarius-compliant certification.
- USDA dairy grading program tier exploitation:Extra Grade designation unlocks Japanese and South Korean tender eligibility where import specifications exceed domestic US requirements.
- E-commerce direct-to-baker procurement:Small-scale bakery clusters in Indonesia are bypassing traditional distributor markups through platform-based bulk ordering of instantized powder.
Industry Challenges
- Spray-dryer thermal efficiency retrofitting:Natural gas-fired operations face decarbonization pressure requiring capital deployment for heat-recovery system integration without margin recovery mechanisms.
- Microbiological testing timeline compression:Hold-and-release protocols for Salmonella and Listeria screening extend working capital cycles for exporters targeting multiple regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonfat Dry Milk Market |
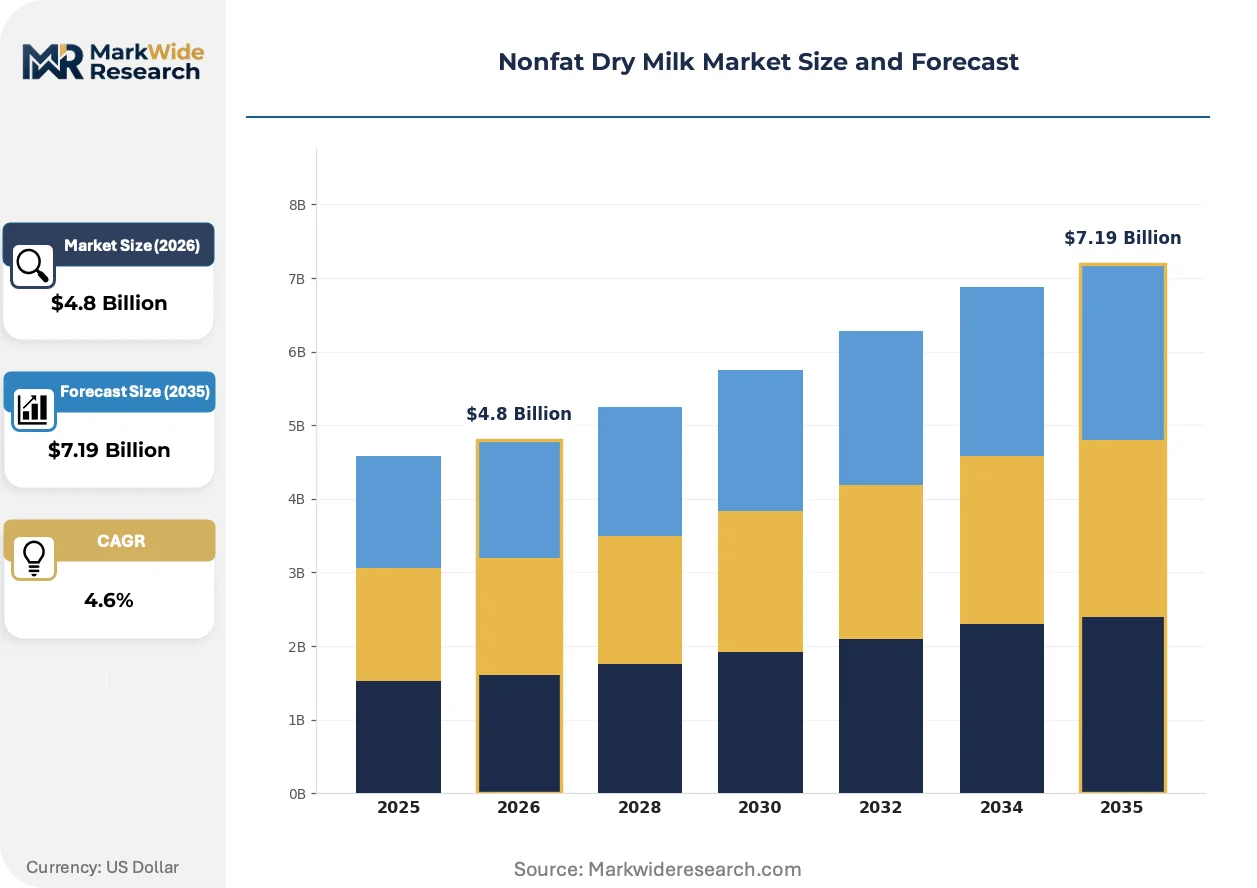
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Nonfat Dry Milk, Non-instant Nonfat Dry Milk, Spray-dried Nonfat Milk, Roller-dried Nonfat Milk Application: Baking, Infant Formula, Confectionery, Dairy Products End User: Food Manufacturers, Retailers, HoReCa, Nutritional Companies Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Nestlé SA, Glanbia Ingredients Ireland Limited, DairyAmerica Inc., California Dairies, Inc., All American Foods Inc., Hilmar Cheese Company, Danone SA, Agropur Cooperative, Arla Foods AMBA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonfat Dry Milk Market Emerging Trajectories
Processing technology convergence with sustainability mandates is redrawing capital allocation priorities across dehydration equipment procurement and energy-intensive drying operations.
Membrane filtration pre-concentration is rewriting energy economics in spray-drying operations by reducing water load prior to thermal dehydration. European processors in Ireland and the Netherlands are retrofitting reverse osmosis and nanofiltration stages to cut natural gas consumption per metric ton of powder output. This technology compression is enabling margin defense against volatile energy input costs while meeting emerging Scope 3 emissions reporting requirements.
The EU Green Deal Farm to Fork strategy is tightening nitrogen and phosphorus discharge limits for dairy processing effluent. Irish and Danish plants now face nutrient recovery mandates that add tertiary wastewater treatment capital burdens. Export-oriented processors are responding by co-locating biogas digesters that convert whey permeate into captive energy, turning regulatory compliance into operational cost hedging.
Food manufacturers in Southeast Asia are consolidating supplier relationships around processors offering integrated technical service rather than commodity spot supply. Vietnamese and Indonesian bakery chains now demand customized particle size distribution and protein standard certificates bundled with logistics coordination. This specification-driven procurement compression favors processors with regional warehousing presence over distant exporters relying on broker intermediation.
Nonfat Dry Milk Market Segmentation
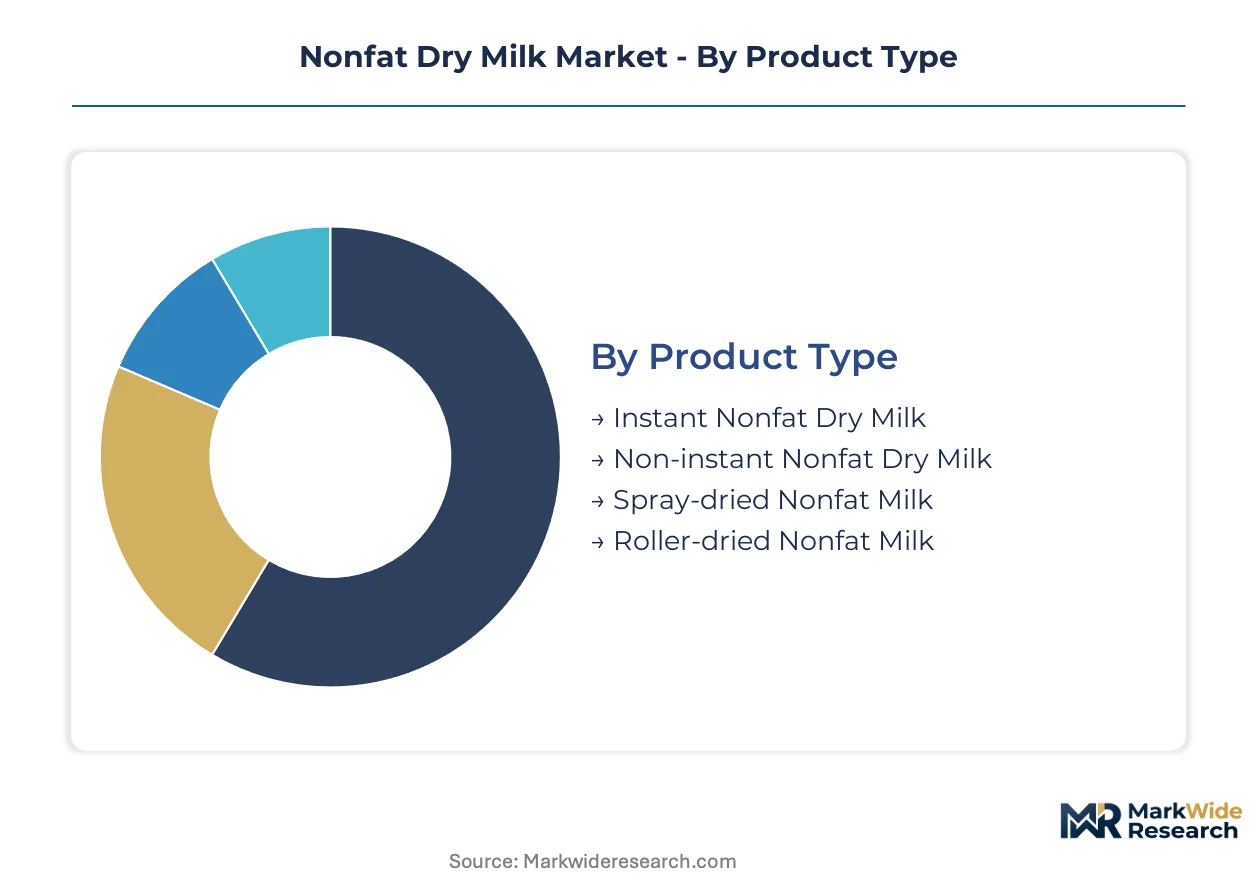
Nonfat dry milk processors compete across distinct technical specifications and channel economics that determine margin capture. Segmentation reveals where spray-drying investments concentrate versus where roller-drying legacy capacity still commands price premiums.
Product Type:
Integration depth varies sharply: instant and spray-dried variants embed directly into food manufacturing workflows, while non-instant and roller-dried powders often serve standalone reconstitution or specialized applications.
- Instant Nonfat Dry Milk:Agglomerated particles achieve cold-water solubility through steam-leaching processes that create porous structures. HoReCa operators in Vietnam and Indonesia specify instantized powder for rapid beverage preparation where equipment minimization drives procurement. Regulatory compliance with FDA Grade A Pasteurized Milk Ordinance sanitation protocols separates qualified suppliers from commodity exporters.
- Spray-dried Nonfat Milk:Atomized milk droplets dried in heated air columns yield consistent particle size distribution prized by confectionery formulators. Southeast Asian bakery chains consolidate procurement around processors offering integrated technical service bundled with spray-dried specifications. Membrane filtration pre-concentration is compressing energy economics for European operators retrofitting Irish and Dutch plants.
- Non-instant Nonfat Dry Milk:Standard spray-dried powder requiring warm-water agitation for reconstitution. Retail channel concentration in price-sensitive developing markets where instantization premiums prove uneconomical.
- Roller-dried Nonfat Milk:Drum-dried flakes with distinct Maillard flavor profiles for caramel and chocolate applications. Legacy European capacity serves niche confectionery demand as thermal efficiency retrofits lag spray-dryer economics.
Instant nonfat dry milk leads volumes today; spray-dried nonfat milk is gaining share fastest.
Application:
Cost tier stratification separates premium-positioned infant formula from commodity baking and confectionery volume, with dairy products occupying intermediate value positioning.
- Baking:Functional protein and solids source in bread, pastry, and biscuit formulations where liquid milk logistics fail. Indonesian bakery clusters bypass traditional distributors through platform-based bulk ordering of instantized powder.
- Infant Formula:Stringent protein standard and microbiological specifications command premium positioning within the application mix. Codex Alimentarius-compliant certification creates pricing separation from commodity-grade powder for processors achieving bacterial and Salmonella screening protocols.
- Confectionery:Milk solids and lactose for chocolate, caramel, and fudge applications. Vietnamese processors demand customized particle size distribution certificates bundled with logistics coordination.
- Dairy Products:Reconstitution base for yogurt, ice cream, and cheese production in import-dependent markets. Cold-chain limitations in Southeast Asia drive powder-to-liquid reconstitution plant construction.
Infant formula captures highest margins; baking applications expand most quickly.
End User:
Customer type determines specification intensity, with nutritional companies and food manufacturers driving technical requirements while retailers and HoReCa prioritize logistics flexibility.
- Food Manufacturers:Large-scale procurement with embedded quality assurance and continuous supply contracts. Multi-source procurement restructuring supply relationships across the value chain.
- Nutritional Companies:Clinical formula and sports nutrition applications where protein standard documentation determines supplier qualification. Whey protein concentrate substitution is displacing nonfat dry milk in performance positioning segments.
- HoReCa:Rapid reconstitution requirements favor instantized powder with cold-water solubility. Platform-based procurement penetration in Indonesian small-scale bakery clusters.
- Retailers:Private-label and branded packaged goods for consumer reconstitution. Price sensitivity concentrates demand in non-instant standard grades.
Food manufacturers dominate volume today; nutritional companies are climbing the fastest.
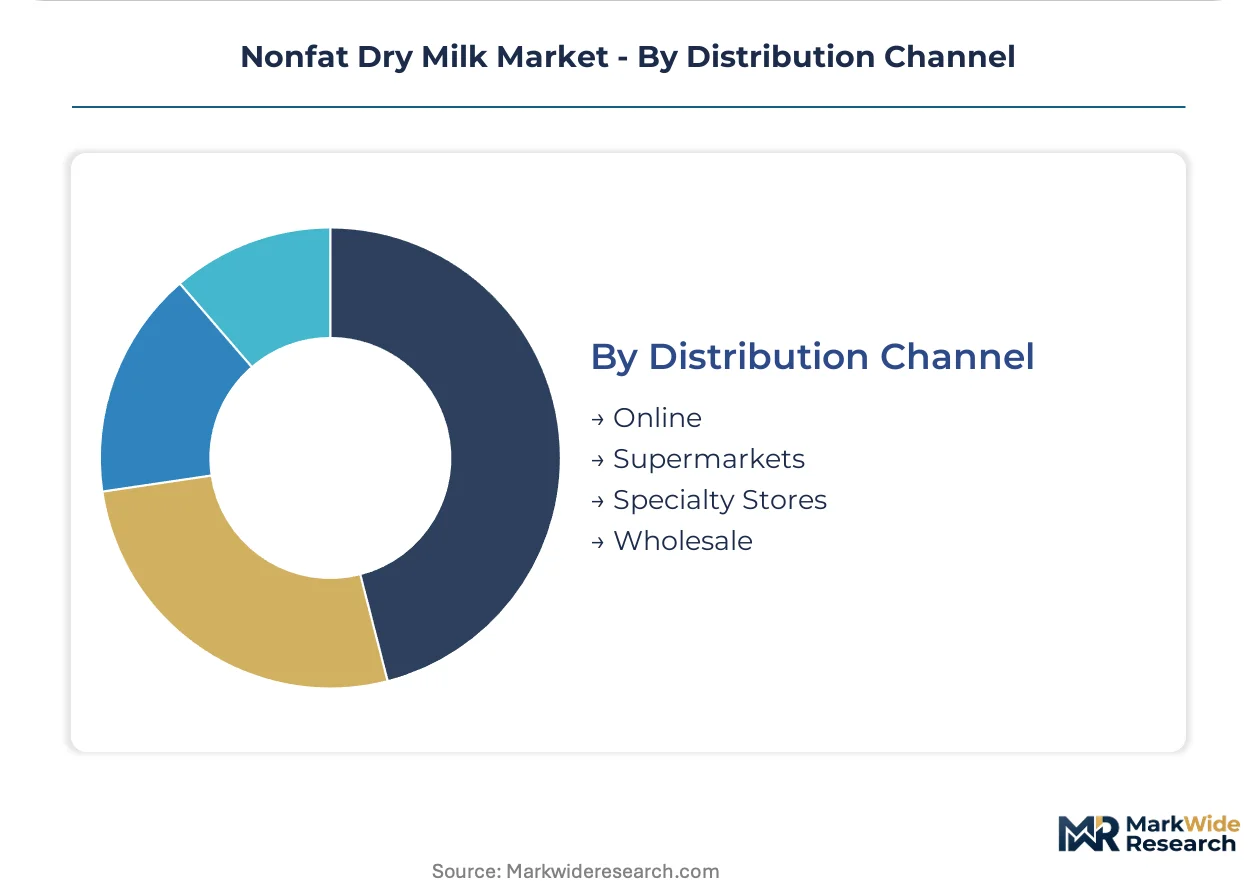
Distribution Channel:
Supply concentration in wholesale and supermarket channels is fragmenting as e-commerce direct procurement and specialty store technical service gain traction.
- Wholesale:Bulk volume movement to food manufacturers and dairy processors with established credit terms and logistics coordination. Cooperative member networks across California and the Upper Midwest anchor North American volume.
- Online:Direct-to-baker platform penetration in Indonesia and Vietnam bypassing traditional distributor markups. Small-scale procurement consolidation around specification transparency.
- Supermarkets:Packaged retail formats for consumer reconstitution in developed markets. Private-label concentration in price-competitive segments.
- Specialty Stores:Technical service bundling for artisan bakeries and confectioners requiring customized particle size distribution. Regional warehousing presence favors processors over distant exporters relying on broker intermediation.
Wholesale channels lead volumes today; online distribution is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting nonfat dry milk processing capacity toward jurisdictions where energy costs and environmental compliance burdens diverge most sharply. Processors with access to lower-cost natural gas and streamlined USDA or FDA inspection protocols capture margin advantages that reshape export competitiveness.
United States
California and Wisconsin cooperative networks anchor North American spray-drying capacity for bakery and confectionery supply chains. The FDA's Grade A Pasteurized Milk Ordinance enforcement tightens pathogen testing protocols that favor large-scale processors with in-house laboratory capacity. Upper Midwest dairy processing clusters around Madison and Twin Cities metro areas are consolidating procurement relationships through cooperative member networks.
Ireland
Irish processors leverage EU Green Deal Farm to Fork nutrient recovery mandates to co-locate biogas digesters converting whey permeate into captive energy. The EPA Ireland enforces nitrogen and phosphorus discharge limits that add tertiary wastewater treatment capital burdens for export-oriented plants. Cork and Limerick processing zones are retrofitting membrane filtration pre-concentration stages to cut natural gas consumption per metric ton of powder output.
Vietnam
Import-dependent powder-to-liquid reconstitution plants are expanding around Ho Chi Minh City and Hanoi to bypass cold-chain limitations for bakery supply. The country's national food safety regulator aligns with Codex Alimentarius revisions that reshape compositional standards for cross-border dry milk trade. Vietnamese bakery chains now demand customized particle size distribution certificates bundled with logistics coordination from regional warehousing presence.
Indonesia
Small-scale bakery clusters in Jakarta and Surabaya are bypassing traditional distributor markups through platform-based bulk ordering of instantized powder. The national food and drug regulator enforces microbiological specifications that create pricing separation from commodity-grade powder for processors achieving bacterial screening protocols. E-commerce direct procurement penetration favors specification transparency over distant exporter broker intermediation.
Netherlands
Dutch plants face EU MDR-aligned nutritional labeling complexity that threatens existing export eligibility tiers for cross-border dry milk trade. The Netherlands Food and Consumer Product Safety Authority enforces compositional standard revisions affecting international tender participation. Rotterdam and Groningen processing zones are retrofitting reverse osmosis and nanofiltration stages to meet emerging Scope 3 emissions reporting requirements.
Nonfat Dry Milk Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent nutritional and functional ingredient spaces where protein standard premiums apply. The vendor base concentrates around cooperative structures in North America and integrated dairy groups in Europe, with tiering driven by spray-dryer scale and in-house laboratory capacity. Strategic archetypes include commodity-grade volume processors, infant formula specialists with Codex certification, and diversified dairy groups with whey protein adjacencies. Dominant competitive moves center on membrane filtration retrofitting for energy cost defense and regional warehousing expansion for Southeast Asian technical service bundling.
Within the cooperative-anchored tier, DairyAmerica Inc. and California Dairies, Inc. exemplify North American volume concentration through member network structures. Glanbia Ingredients Ireland Limited occupies a position representing European export-oriented processing with Irish base advantages for nutritional applications. Hilmar Cheese Company anchors the diversification archetype, with company nomenclature suggesting whey and milk protein specialization extending into adjacent dry milk product lines.
| Leading Market Players |
|---|
| Nestlé SA |
| Glanbia Ingredients Ireland Limited |
| DairyAmerica Inc. |
| California Dairies, Inc. |
| All American Foods Inc. |
| Hilmar Cheese Company |
| Danone SA |
| Agropur Cooperative |
| Arla Foods AMBA |
| Others |
Supply Flow & Price Mechanics
Membrane filtration pre-concentration retrofitting across Irish and Dutch processing plants is simultaneously compressing energy input costs and consolidating procurement relationships around large-scale operators with capital deployment capacity. This technology transition rewards processors achieving FDA Grade A Pasteurized Milk Ordinance compliance while marginalizing commodity-grade competitors lacking laboratory infrastructure for pathogen testing protocols.
Pricing Analysis
Distributor margin compression in Indonesian and Vietnamese bakery channels is forcing processors to absorb logistics coordination costs or cede volume to direct-platform competitors. Three-tier pricing structure across premium, standard, and economy levels separates Codex Alimentarius-compliant infant formula grades from commodity baking powders. Price differentiation hinges on microbiological certification tiers and regional warehousing presence. Cost compression in standard-grade segments is intensifying because whey protein concentrate substitution is displacing nonfat dry milk in sports nutrition applications.
Supply Chain Analysis
FDA Grade A Pasteurized Milk Ordinance certification gates interstate commerce eligibility, concentrating qualified supply among California and Wisconsin cooperative networks with in-house laboratory capacity. Raw fluid milk from Upper Midwest dairy clusters feeds spray-drying operations tethered to natural gas pricing volatility. Single-source vulnerability concentrates in California processing zones exposed to drought-induced feed cost transmission. Distribution runs through wholesale cooperative channels anchored by DairyAmerica member networks and specialized technical service providers serving Southeast Asian bakery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where infant formula microbiological premiums and Codex Alimentarius certification separate viable processors from commodity-grade exiters. Vietnamese and Indonesian bakery procurement consolidation toward specification-transparent suppliers validates premium positioning for compliant operators.
For Market Incumbents: Deploy membrane filtration retrofitting to defend energy cost position against Irish and Dutch competitors meeting EU Green Deal Scope 3 emissions reporting requirements. Consolidate regional warehousing presence in Ho Chi Minh City and Jakarta to capture technical service bundling premiums from platform-direct bakery procurement. Whey protein concentrate substitution in sports nutrition segments demands infant formula certification investment as defensive margin protection.
For New Entrants and Emerging Players: EU MDR-aligned nutritional labeling complexity in the Netherlands opens a window for Southeast Asian processors to capture displaced European export volume into Japanese and South Korean tenders. Target Indonesian e-commerce direct procurement channels where small-scale bakery clusters bypass distributor markups through platform-based bulk ordering. Lead with instantization technology and cold-water solubility specifications as technical differentiation against legacy spray-dried commodity suppliers.
For Investors and Strategic Acquirers: Valuations sit cheapest among roller-dried legacy operators lacking spray-dryer thermal efficiency retrofit capital. Long-term viability centers on processors with integrated whey permeate biogas digestion converting EU Green Deal nutrient recovery mandates into captive energy cost hedging. Acquisition focus should concentrate on Irish and Danish plants with tertiary wastewater treatment infrastructure already deployed. The signal to watch is Codex Alimentarius revision timing affecting cross-border dry milk trade eligibility tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofitting | Reverse osmosis pre-concentration cuts natural gas consumption per metric ton for Irish processors. |
| Regional Warehousing Expansion | Ho Chi Minh City logistics coordination captures Vietnamese bakery chain specification-driven procurement. |
| Biogas Digester Co-location | Whey permeate conversion into captive energy hedges EU Green Deal nitrogen discharge compliance costs. |
| Instantization Technology Investment | Agglomeration processes unlock Indonesian HoReCa channel penetration through cold-water solubility. |
| Codex Certification Achievement | Salmonella and bacterial screening protocols enable Japanese and South Korean tender eligibility premiums. |
Methodological Framework
Coverage spans the United States, Ireland, Vietnam, Indonesia, and the Netherlands, with primary inputs from each regional cluster combining interviews with spray-dryer operations managers, dairy cooperative procurement leads, Southeast Asian bakery chain technical buyers, infant formula quality assurance directors, and regulatory affairs specialists at export-oriented processors. Secondary validation draws from FDA Grade A Pasteurized Milk Ordinance enforcement records, USDA dairy grading program documentation, EU Green Deal Farm to Fork strategy filings, Codex Alimentarius revision drafts, and Indonesian national food and drug regulator microbiological specification releases. Bottom-up volume modeling triangulates against top-down value chain analysis across the projection horizon.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, application, end user, and distribution channel segmentation dimensions. CAGRs derive from regression analysis against fluid milk input cost trajectories, energy price scenarios, and regulatory compliance timeline assumptions. Infant formula protein standard premiums and bakery sector platform procurement penetration serve as industry-specific demand-side forecast inputs alongside spray-dryer capacity utilization rates by processing zone.
Revisions become necessary when FDA pathogen testing protocol amendments, EU MDR-aligned nutritional labeling enforcement delays, or ASEAN dairy processing capacity expansion timelines materialize differently than modeled assumptions. A model refresh is warranted upon material change in natural gas pricing volatility affecting spray-drying energy economics or Codex Alimentarius bacterial screening standard adoption rates across target export markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Sour Cream Market
Dairy Products
Canada Milk Protein Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
North America Fluid Milk Market
Dairy Products
Natural Cheese Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Global Milk Protein Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
Fluid Milk Market