
 Goat Milk Powder Market | 2026-2036
Goat Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Goat Milk Powder Market Analysis
Precision spray-drying automation is rewriting manufacturing economics across the goat milk powder value chain, cutting moisture variance to under 3.5% and extending shelf stability. Ausnutria Dairy Corporation Ltd leverages vertical integration from herd management to finished powder, sustaining cost advantages in bulk ingredient supply. Dairy Goat Co-operative anchors premium organic output from New Zealand, while Hochdorf Swiss Nutrition AG competes through pharmaceutical-grade fractionation capabilities.
Goat milk powder consists of dehydrated caprine milk solids, typically retaining 26-30% protein and 30-35% fat on a dry basis, produced via spray-drying or roller-drying for shelf-stable nutritional applications. Infant Formula commands the dominant value share as parents seek A2 beta-casein alternatives to bovine-sourced products, with margin pools concentrating in organic-certified supply. Nutritional Supplements represent the fastest-growing application as aging populations in East Asia adopt goat milk peptides for digestive tolerance, while Dairy Alternatives extend into barista-grade formulations where foaming stability differentiates premium positioning.
EFSA novel food approvals and EU organic certification (EC 834/2007) shape product standards and market access across European retail channels, while China's SAMR infant formula registration requirements filter import eligibility for offshore manufacturers. FDA GRAS notifications and USDA organic seals govern US positioning, with FSMA preventive controls adding compliance depth for powder importers. Stakeholders must monitor divergence between Codex Alimentarius protein minimums and national additive permissibility lists as formulation strategies cross jurisdictions.
Market Dynamics
Precision spray-drying automation is compressing moisture variance below 3.5% and extending shelf stability, forcing capital upgrades across manufacturing footprints while concentrating margin pools among processors with captive herd supply.
Growth Catalysts
- EFSA novel food pathway:Streamlined approvals for hypoallergenic infant formula ingredients accelerate European commercialization timelines for A2 beta-casein alternatives.
- East Asian nutritional supplement demand:Aging demographics in Japan and South Korea adopt goat milk peptides for digestive tolerance, expanding addressable consumer base beyond infant nutrition.
- Pharmaceutical-grade fractionation:Advanced protein separation technologies enable medical nutrition applications with higher purity thresholds and pricing power.
Market Restraints
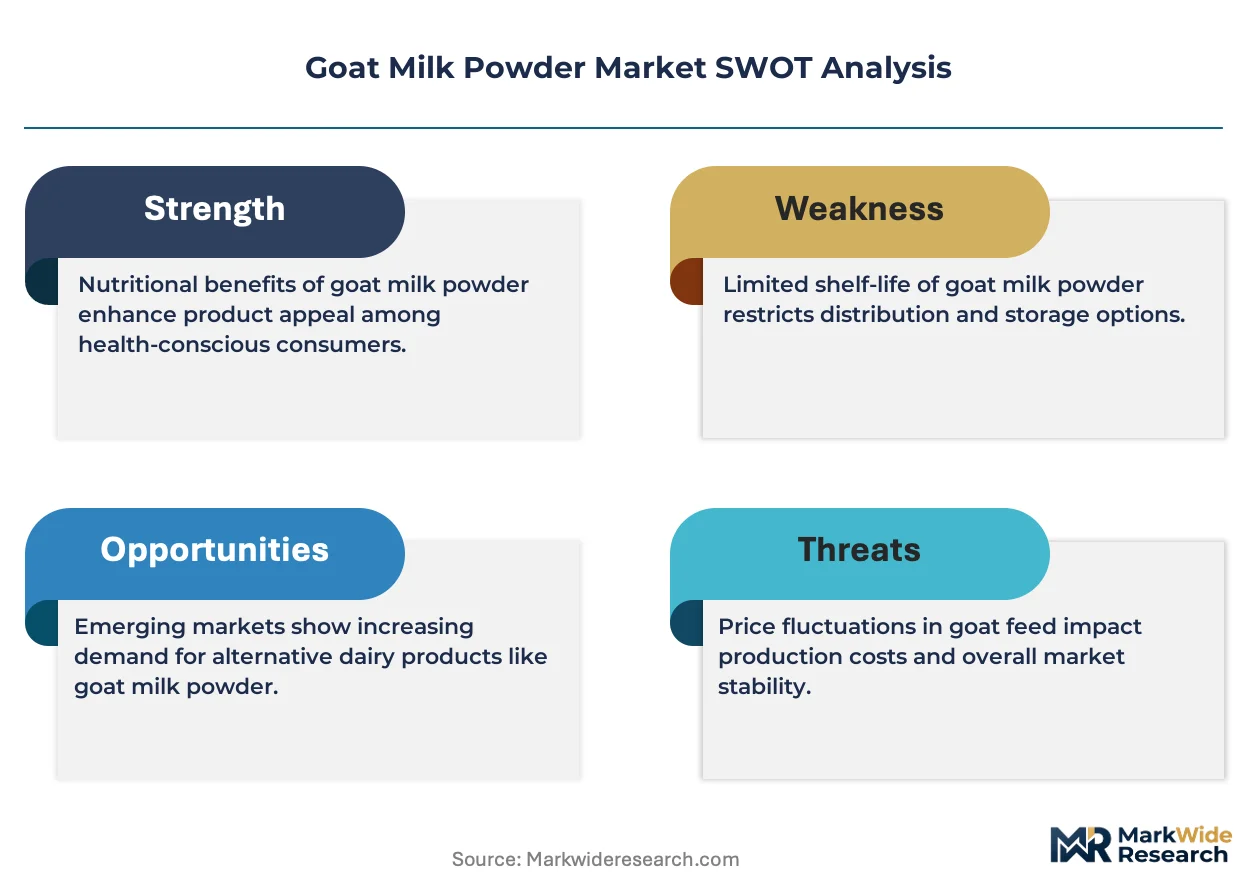
- Input cost volatility:Fodder and veterinary input prices fluctuate with climate patterns, squeezing processor margins during drought cycles in major grazing regions.
- Supply concentration risk:Herd ownership concentrates among cooperative structures in New Zealand, creating single-source dependency for premium organic output.
- Substitution pressure:Oat and pea protein isolates improve foaming stability and nutritional parity, threatening barista-grade and adult nutritional positioning.
Strategic Opportunities
- SAMR registration arbitrage:China's infant formula import requirements filter competitor eligibility, creating protected market access for compliant offshore manufacturers.
- Barista-grade formulation expansion:Specialty coffee channels in Australia and United States seek stable microfoam alternatives to bovine milk, opening premium positioning.
- Organic certification convergence:EU EC 834/2007 and USDA organic seal alignment enables dual-label products with expanded retail distribution.
Industry Challenges
- Specialized dairy technician scarcity:Caprine herd health management and precision drying operations require skills distinct from conventional dairy, constraining facility expansion.
- Dual certification timeline compression:Simultaneous pursuit of pharmaceutical-grade and organic credentials extends validation cycles and delays revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Goat Milk Powder Market |
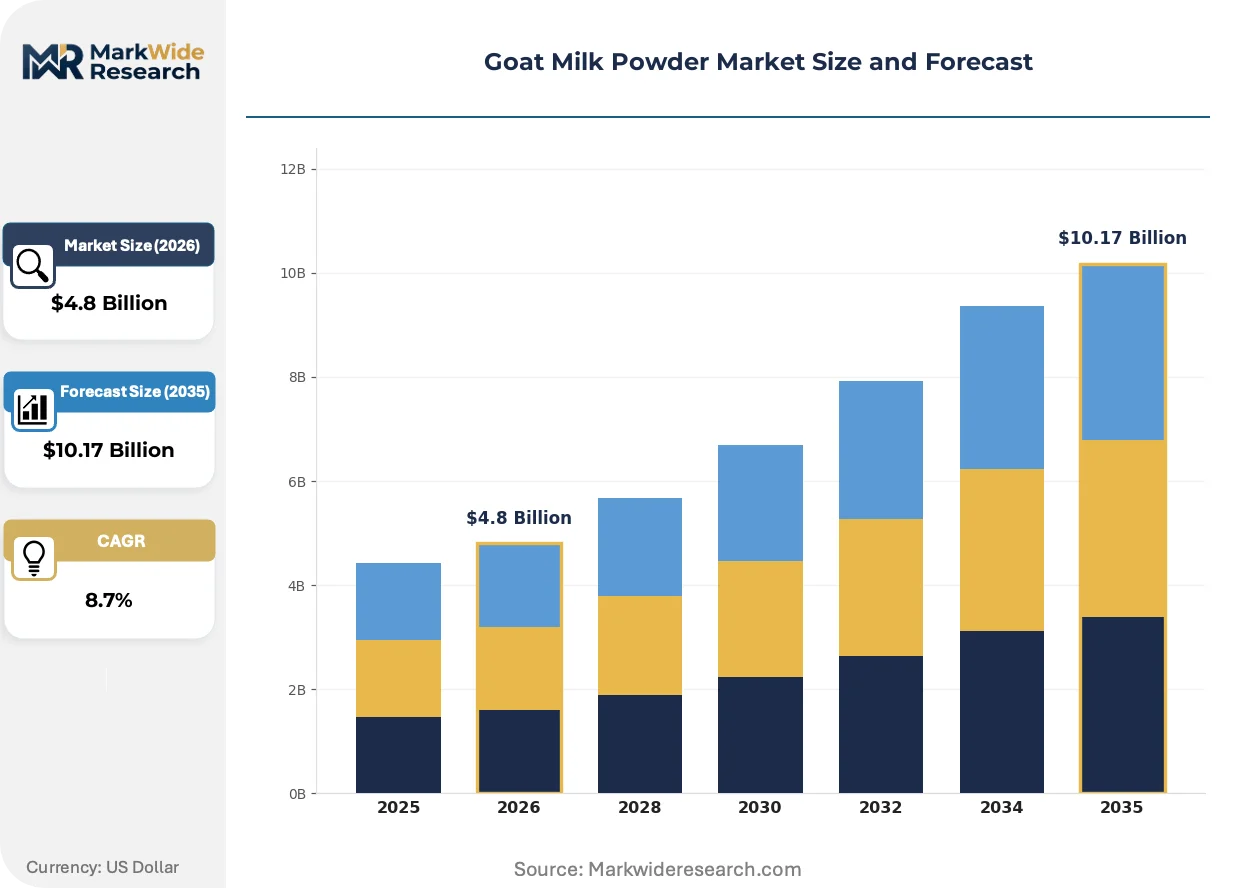
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Powder, Non-Instant Powder, Organic Powder, Conventional Powder Application: Infant Formula, Nutritional Supplements, Bakery Products, Dairy Alternatives End User: Households, Food Service Providers, Healthcare Institutions, Retailers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Ausnutria Dairy Corporation Ltd, Dairy Goat Co-operative, Hochdorf Swiss Nutrition AG, Goat Partners International, Meyenberg Goat Milk Products, Emmi Group, Holle Baby Food AG, Xi'an Baiyue Goat Dairy Group Co. Ltd, FIT Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Goat Milk Powder Market Emerging Trajectories
Automation and regulatory harmonization are compressing production economics while fragmenting demand across medical, specialty food, and functional nutrition channels.
Membrane filtration coupled with computational moisture control is virtualizing quality assurance protocols previously requiring batch sampling. Infant formula manufacturers in Germany and Netherlands deploy these systems for real-time protein standardization. The technology is virtualizing legacy laboratory testing infrastructure and reducing release-cycle delays.
EU F-Gas Regulation phase-down mandates are accelerating adoption of CO2-based refrigeration in spray-drying facilities. Processors face retrofit capital requirements or facility replacement decisions. Organic-certified operations in France and Ireland absorb compliance costs fastest due to existing sustainability investment frameworks.
Direct-to-clinic sampling programs in South Korea and Taiwan bypass traditional retail pharmacy channels for medical nutrition products. Hospital purchasing committees consolidate supplier lists around traceability-verified sources. This channel compression is most visible in oncology and geriatric care verticals where digestive tolerance drives formulary decisions.
Goat Milk Powder Market Segmentation
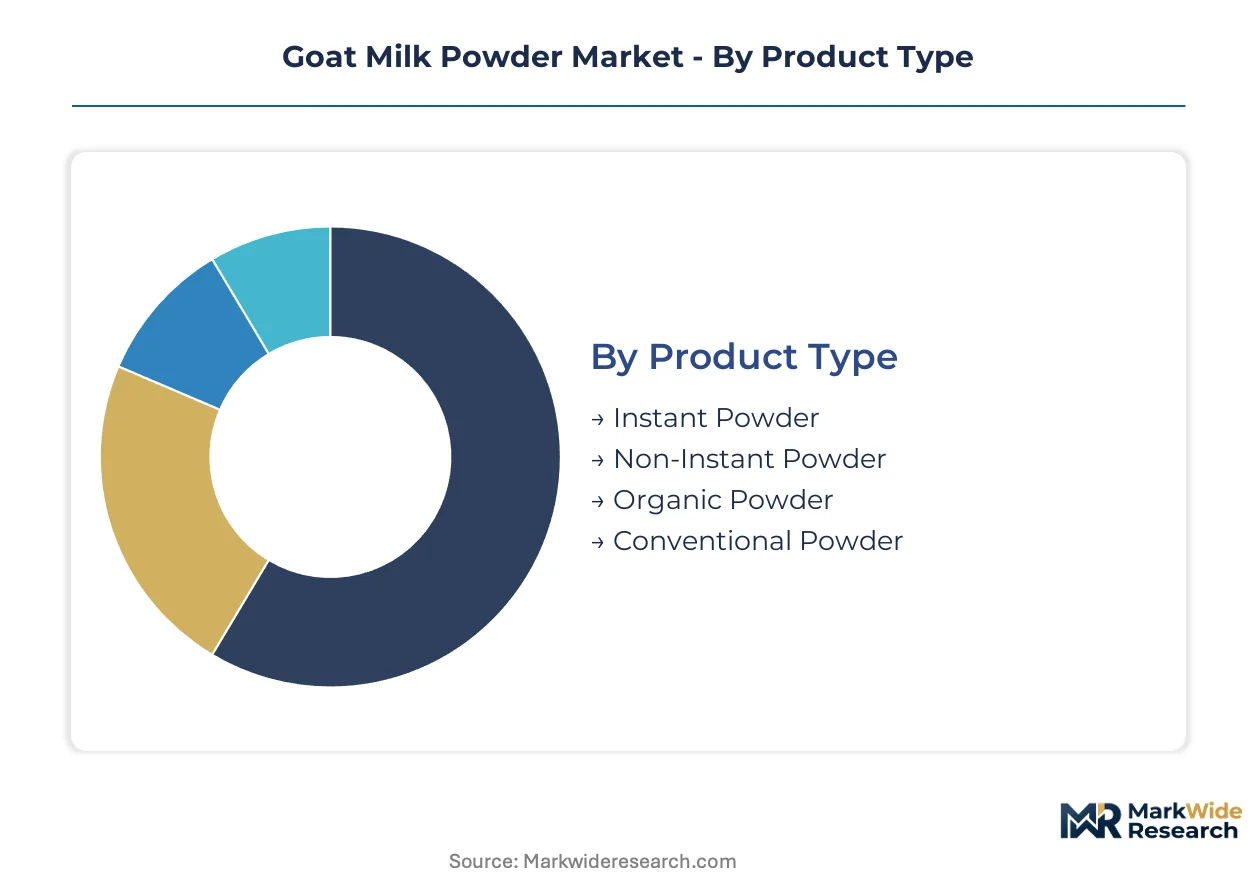
Goat milk powder segmentation reflects divergent technical requirements across instantization protocols, regulatory certification tiers, and channel-specific packaging formats. Manufacturers configure production lines around these divides, with cycle times and margin structures varying sharply between commodity bulk supply and pharmaceutical-grade output.
Product Type:
Instant Powder commands the shortest production cycles through agglomeration pre-processing, while Organic Powder faces extended validation timelines for dual-certification compliance.
- Instant Powder:Agglomerated particles disperse in cold water without mechanical agitation, meeting the convenience thresholds of food service operators in Australia and household consumers across East Asia. Demand concentrates in single-serve sachet formats where reconstitution speed drives repeat purchase.
- Organic Powder:EC 834/2007 and USDA organic seal compliance requires pasture-verified herd management and segregated processing infrastructure, limiting eligible suppliers to cooperative structures in New Zealand and certified operations in France. Premium positioning sustains margin pools despite throughput constraints.
- Non-Instant Powder:Standard spray-dried particles require warm water and mechanical mixing, serving industrial bakery applications where dissolution equipment is captive to manufacturing lines.
- Conventional Powder:Non-certified output from mixed grazing operations supplies bulk ingredient markets with price-sensitive procurement protocols.
Conventional Powder dominates installed base. Organic Powder is where expansion concentrates.
Application:
Formulation complexity and regulatory burden segment applications by margin tier, with medical nutrition commanding price multiples over commodity dairy alternatives.
- Infant Formula:A2 beta-casein protein profiles and hypoallergenic positioning require SAMR registration in China and EFSA novel food pathway completion in Europe, filtering competitor eligibility and protecting compliant manufacturers. Regulatory timelines extend 18-36 months for new market entrants.
- Nutritional Supplements:Peptide fractions targeting digestive tolerance in aging populations across Japan and South Korea are climbing the fastest, with direct-to-clinic distribution bypassing traditional retail pharmacy markups.
- Bakery Products:Fat-protein ratios optimized for dough conditioning and browning reactions serve industrial manufacturers in Germany and artisan producers in Italy.
- Dairy Alternatives:Barista-grade foaming stability specifications drive specialty coffee channel adoption in Melbourne and Los Angeles, where microfoam texture differentiates premium positioning.
Infant Formula anchors revenue concentration. Nutritional Supplements are gaining share fastest.
End User:
Procurement scale and quality assurance protocols separate institutional buyers from fragmented household demand.
- Healthcare Institutions:Hospital purchasing committees in South Korea and Taiwan consolidate supplier lists around traceability-verified sources for oncology and geriatric nutrition, with formulary decisions driven by digestive tolerance clinical evidence.
- Food Service Providers:Specialty coffee chains and premium bakery networks in Australia specify barista-grade foaming performance and consistent fat-protein ratios for menu standardization.
- Households:Direct-to-consumer organic certified SKUs concentrate in New Zealand and Netherlands retail channels where parental preference for A2 beta-casein alternatives sustains premium pricing.
- Retailers:Private label programs in German and French supermarket chains source conventional powder for economy-tier positioning against branded organic alternatives.
Households dominate transaction volume. Healthcare Institutions concentrate margin expansion.
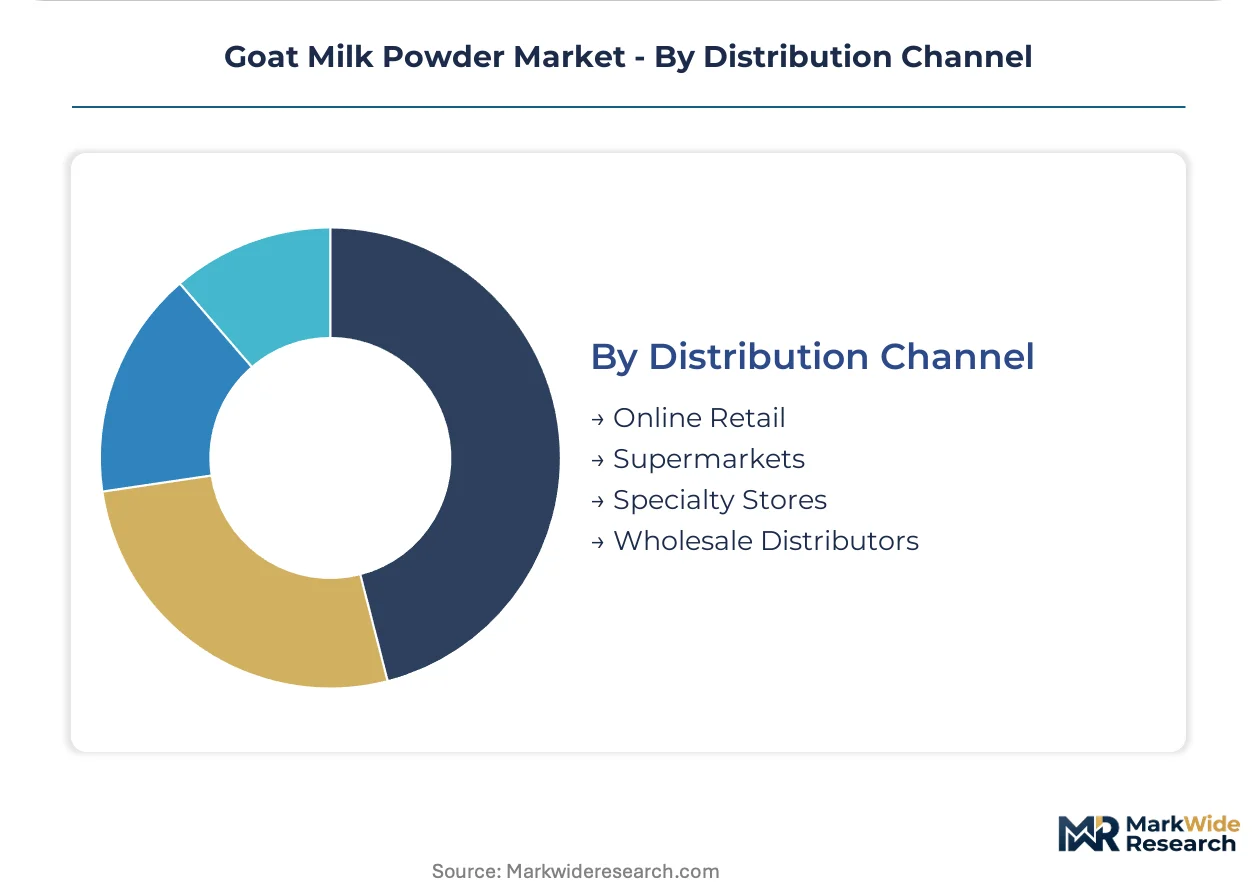
Distribution Channel:
Channel selection determines certification display, temperature control requirements, and traceability documentation depth.
- Online Retail:Cross-border e-commerce platforms serving Chinese consumers require SAMR registration documentation and Mandarin-language labeling compliance, with logistics partners handling customs clearance and cold chain integrity.
- Specialty Stores:Organic and natural products retailers in France and Switzerland provide certification narrative space and staff training for premium positioning, justifying price multiples over mass retail.
- Supermarkets:Mass retail placement in New Zealand and Netherlands demands promotional slotting fees and volume guarantees that favor processors with captive herd supply.
- Wholesale Distributors:Industrial ingredient supply to bakery and dairy alternative manufacturers runs through regional distributors with bulk handling infrastructure and lot-traceability systems.
Supermarkets dominate installed base. Online Retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household buyers in New Zealand and institutional purchasers in East Asia anchor procurement volumes, while regulatory divergence between EFSA novel food pathways and SAMR registration requirements fragments commercialization timelines across jurisdictions.
New Zealand
Organic-certified herd cooperatives supply premium A2 beta-casein powder to Asia-Pacific infant formula manufacturers. The country's national food safety regulator enforces strict dairy export certification protocols. Waikato region processors concentrate spray-drying capacity serving Chinese cross-border e-commerce channels.
China
SAMR registration requirements filter import eligibility for offshore goat milk powder manufacturers, protecting compliant suppliers. The national market regulator mandates Mandarin-language labeling and traceability documentation for infant formula distribution. Shanghai and Guangzhou logistics hubs handle customs clearance and cold chain integrity for cross-border platforms.
Germany
Industrial bakery manufacturers and pharmaceutical-grade fractionators drive differentiated demand across protein purity tiers. EFSA novel food approvals under EU regulation accelerate hypoallergenic infant formula commercialization. Bavarian processors deploy membrane filtration systems for real-time protein standardization.
United States
Specialty coffee chains in Los Angeles and Melbourne-source barista-grade formulations seek stable microfoam alternatives to bovine milk. FDA GRAS notifications and USDA organic seals govern positioning, with FSMA preventive controls adding compliance depth for powder importers. California-based distributors consolidate supply for West Coast food service networks.
South Korea
Hospital purchasing committees in Seoul consolidate supplier lists around traceability-verified sources for oncology and geriatric nutrition. MFDS medical nutrition regulations shape formulary decisions where digestive tolerance drives procurement. Direct-to-clinic sampling programs bypass traditional retail pharmacy markups in the capital region.
Goat Milk Powder Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base spans cooperative herd structures, vertically integrated nutrition conglomerates, and regional dairy processors. Three archetypes dominate: captive-supply cooperatives with organic certification, pharmaceutical-grade fractionators with medical nutrition positioning, and cross-border e-commerce enablers with SAMR registration compliance. Competitive moves concentrate on herd capacity expansion and dual-certification pursuit for organic and pharmaceutical-grade credentials.
Among Asia-Pacific-based nutrition conglomerates, Ausnutria Dairy Corporation Ltd exemplifies vertical control from herd management through finished powder production. Dairy Goat Co-operative occupies the premium organic tier with pasture-verified supply chains. Hochdorf Swiss Nutrition AG anchors European pharmaceutical-grade positioning through advanced protein separation capabilities.
| Leading Market Players |
|---|
| Ausnutria Dairy Corporation Ltd |
| Dairy Goat Co-operative |
| Hochdorf Swiss Nutrition AG |
| Goat Partners International |
| Meyenberg Goat Milk Products |
| Emmi Group |
| Holle Baby Food AG |
| Xi'an Baiyue Goat Dairy Group Co. Ltd |
| FIT Company |
| Others |
Supply Flow & Price Mechanics
Spray-drying capacity utilization above 85% in New Zealand's Waikato region compresses processor margins and amplifies fodder cost pass-through to infant formula manufacturers. Buyers face take-or-pay clauses indexed to dairy commodity benchmarks, while suppliers prioritize SAMR-registered offtake agreements over spot market exposure.
Pricing Analysis
Cost-plus contracts with Global Dairy Trade indexation dominate procurement between New Zealand cooperatives and Asia-Pacific infant formula manufacturers. Price differentiation rests on organic certification tier and A2 beta-casein verification status, with EC 834/2007-compliant output commanding substantial premia over conventional bulk supply. Pricing pressure stems from oat and pea protein substitution in barista-grade applications, squeezing mid-tier goat milk positioning. Industrial bakery buyers exhibit highest price sensitivity due to commodity dairy alternative availability, while hospital purchasing committees in Seoul show lowest sensitivity given formulary lock-in around digestive tolerance clinical evidence.
Supply Chain Analysis
Contract manufacturing concentrates among Dairy Goat Co-operative and Ausnutria Dairy Corporation Ltd facilities in New Zealand, with secondary capacity in France and Netherlands. Raw material dependencies center on pasture-verified goat herds, alfalfa fodder supply, and pharmaceutical-grade packaging films. Single-source vulnerability concentrates in Waikato region spray-drying infrastructure exposed to drought-driven milk volume volatility. Distribution runs through cross-border e-commerce platforms serving Chinese consumers, with cold chain integrity managed by Shanghai and Guangzhou logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as traceability-verified supply chains become interoperable across infant formula, medical nutrition, and specialty coffee channels, with EFSA-SAMR regulatory convergence enabling multi-jurisdiction product passports.
For Market Incumbents: Entrench SAMR registration moats through accelerated dual-certification pursuit for organic and pharmaceutical-grade credentials, while expanding captive herd capacity in New Zealand's South Island to dilute Waikato concentration risk. Defensive consolidation should target membrane filtration technology providers in Bavaria to secure real-time protein standardization capabilities against emerging precision fermentation substitutes.
For New Entrants and Emerging Players: Pursue barista-grade formulation white space in Australian specialty coffee channels, where foaming stability specifications remain underpenetrated by established infant formula processors. Direct-to-clinic distribution in South Korean oncology and geriatric verticals offers the most penetrable entry vector, with go-to-market execution anchored by MFDS medical nutrition compliance and hospital purchasing committee traceability documentation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade fractionation sub-segments, favoring asset-light contract manufacturing platforms over integrated herd ownership. Long-term viability over the coming decade rests on regulatory arbitrage capture and channel control consolidation. Acquisition targets should display dual EFSA-SAMR registration completion and established direct-to-clinic sampling programs. The signal to watch is membrane filtration equipment order backlogs from German and Dutch processors as real-time quality assurance virtualization accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous EC 834/2007 organic and pharmaceutical-grade pursuit opens protected hospital formulary access. |
| Membrane Filtration Deployment | Bavarian processor adoption of real-time protein standardization reduces batch release cycle delays. |
| Cross-Border E-Commerce Expansion | SAMR-registered SKUs on Chinese platforms bypass traditional import distributor markups. |
| Direct-to-Clinic Sampling Programs | Seoul hospital purchasing committee engagement consolidates supplier lists around traceability-verified sources. |
| Barista-Grade Formulation Development | Melbourne and Los Angeles specialty coffee channel specification meets stable microfoam demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association publications. Primary interviews engaged spray-drying operations managers, infant formula procurement directors, hospital purchasing committee members, and cross-border e-commerce platform operators. Secondary validation drew from EFSA novel food registers, SAMR infant formula approval databases, Global Dairy Trade auction records, and EU organic certification directories. Bottom-up capacity and production estimates triangulated against top-down consumption and import statistics.
Forecast inputs span product type segmentation by instantization protocol, application tier by regulatory burden, and distribution channel by certification display requirements. Value projections incorporate price premia differentials across organic, pharmaceutical-grade, and conventional output tiers. CAGRs derive from regression analysis of historical volume trajectories against demographic, regulatory, and substitution elasticity assumptions. Herd expansion timelines and spray-drying capacity commissioning schedules inform supply-side constraints across the projection horizon.
Sensitivities concentrate around SAMR registration timeline extensions, EFSA novel food pathway revisions, and drought-induced fodder cost spikes in New Zealand grazing regions. Forecasts reflect assumptions regarding regulatory harmonization momentum and precision fermentation substitution rates. Quarterly review of membrane filtration equipment order flows, Global Dairy Trade price indices, and SAMR approval queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
North America Sour Cream Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
Recombined Milk Market
Dairy Products
Halal Cheese Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Nonfat Dry Milk Market
Dairy Products
Butter Concentrate Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Low Fat Butter Market
Dairy Products
Citrus Yogurt Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Natural Cheese Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
Cheese Shreds Market