
 GCC Dairy Market | 2026-2036
GCC Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Dairy Market Intelligence
The price gap between premium organic dairy and commodity fluid milk is hardening across Gulf retail shelves. Almarai Company leverages its integrated feed-to-shelf operations to sustain cost leadership in standardized milk and yogurt lines. Koita FZE differentiates through extended-shelf-life UHT formulations that anchor premium positioning in UAE and Qatar convenience channels.
GCC dairy encompasses fluid milk, fermented products, and fat-based derivatives processed through pasteurization, homogenization, and microbial culturing to deliver specified protein and fat content for direct consumption and food manufacturing. Milk remains the volume foundation while yogurt commands expanding shelf space due to perceived digestive health benefits among Gulf consumers. The food service channel is capturing disproportionate margin pools as hotels and restaurants in Dubai and Riyadh upgrade their ingredient specifications for bakery and beverage applications.
Saudi Food and Drug Authority (SFDA) standards, UAE Ministry of Climate Change and Environment import protocols, and Gulf Standardization Organization (GSO) technical regulations collectively determine product entry criteria, labeling language, and shelf-life claims across member states. Compliance costs favor larger operators with dedicated regulatory affairs teams and in-house laboratory testing capabilities. Stakeholders must monitor evolving halal certification harmonization talks between national bodies, as unified standards would reshape competitive access across the six-member economic bloc.
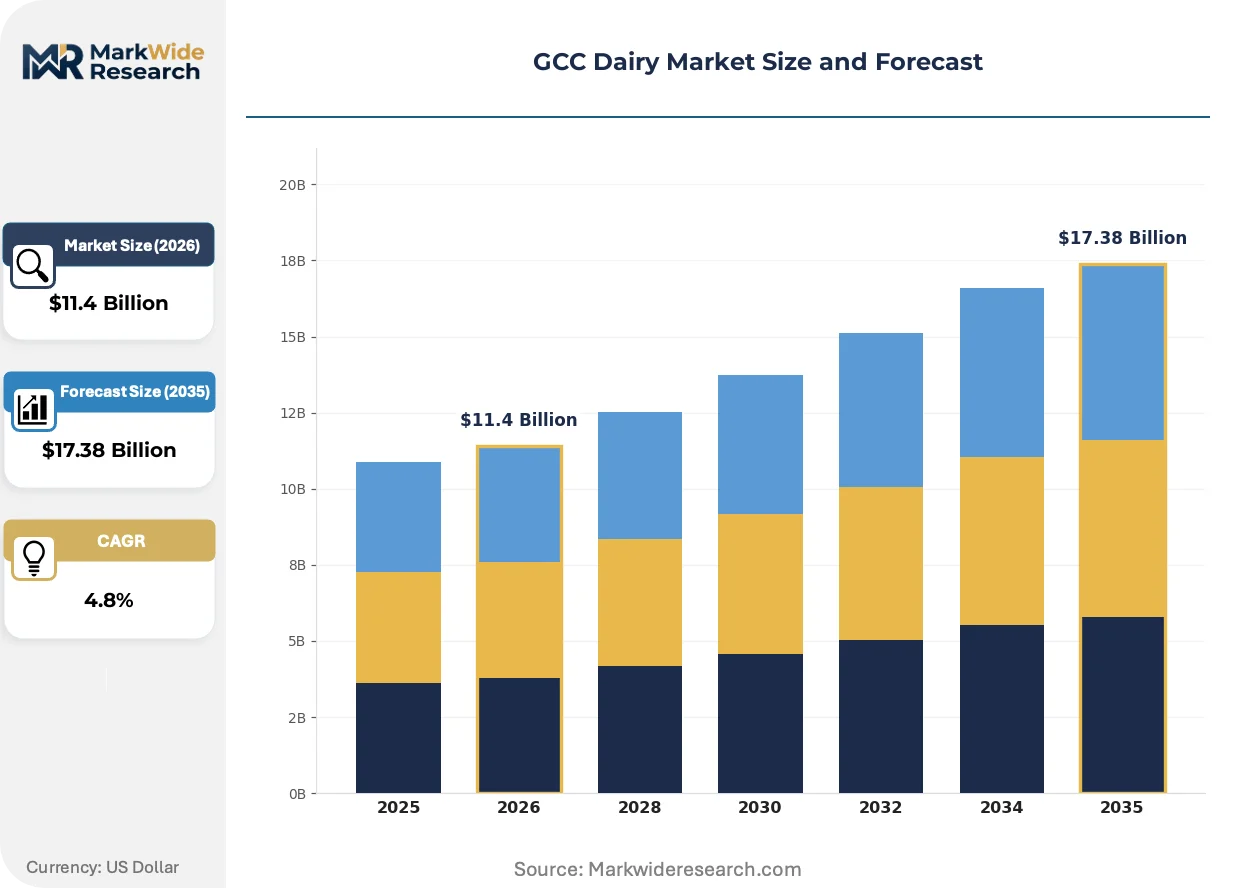
Market Dynamics
Foodservice procurement specifications across Saudi Arabia and UAE are tightening protein and fat content tolerances for fluid milk and fermented products, forcing processors to recalibrate homogenization and microbial culturing lines to maintain hotel and cafe contracts.
Growth Catalysts
- SFDA Labeling Mandates:Saudi Arabia's tightened dairy import standards are prompting domestic reformulation investments that upgrade processing capabilities and create competitive moats for compliant operators.
- Hotels and Cafes:Beverage and dessert menu expansion across Dubai and Riyadh foodservice channels is pulling higher-margin dairy derivatives through specialized procurement contracts.
- Extended-Shelf-Life UHT:Convenience channel penetration in UAE and Qatar is accelerating demand for ambient-stable formulations that reduce cold-chain dependency.
Market Restraints
- Feed Cost Volatility:Alfalfa and soybean meal price swings compress margin predictability for integrated feed-to-shelf operators dependent on captive dairy herd nutrition.
- Import Concentration Risk:Reliance on foreign-origin starter cultures and packaging substrates exposes processors to shipping lane disruptions through the Strait of Hormuz.
- Fresh Fluid Milk Perishability:Seven-day maximum shelf life under GSO technical regulations limits distribution radius and necessitates dense chilling infrastructure.
Strategic Opportunities
- Oman and Bahrain Underpenetration:Smaller GCC states lack indigenous dairy processing scale, creating white space for exporters with halal certification and Arabic-labeling capabilities.
- Digestive Health Positioning:Fermented product lines targeting perceived gut wellness benefits can capture shelf space expansion in Saudi retail pharmacy and convenience channels.
- GSO Harmonization Talks:Unified halal certification standards across the six-member bloc would eliminate redundant testing costs and accelerate cross-border product registration timelines.
Industry Challenges
- Regulatory Affairs Talent Scarcity:SFDA, UAE Ministry of Climate Change and Environment, and GSO filing requirements demand specialized compliance personnel that mid-scale processors struggle to recruit and retain.
- In-House Laboratory Capex:Pathogen screening, fat-protein verification, and shelf-life validation equipment requires capital deployment that strains operators without dedicated testing facilities.
- Legacy Chilling Infrastructure:Cold-chain reconfiguration to accommodate extended-shelf-life ambient distribution creates stranded asset risk for warehouse operators invested in conventional refrigeration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Dairy Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Customer Type: Households, Restaurants, Hotels, Cafes End Use Application: Baking, Cooking, Snacking, Beverages |
| Companies Covered | Al Rawabi Dairy, Koita FZE, Almarai Company, Nestlé, Danone, Saudia Dairy & Foodstuff Co Ltd (SADAFCO), Al Ain Dairy, Arla Foods, National Agricultural Development Company (NADEC), Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Dairy Market Strategic Shifts & Innovations
Processing technology and procurement specifications are diverging across the GCC dairy landscape as foodservice buyers demand ingredient-grade precision while retail channels prioritize ambient stability and Arabic-language packaging compliance.
Membrane filtration systems for protein standardization and fat separation are converging with automated microbial culturing controls to enable batch-level consistency that satisfies hotel and cafe procurement audits in Riyadh and Dubai. Large-scale processors are retrofitting pasteurization lines with real-time compositional sensors. This convergence is compressing quality variance windows and reducing rejection rates on foodservice contracts.
Gulf Standardization Organization technical regulations on shelf-life claims and labeling language are tightening enforcement timelines across member states, compelling importers to pre-validate Arabic packaging and halal chain-of-custody documentation before port entry. Compliance costs are favoring operators with dedicated regulatory affairs teams. Dairy derivatives with complex ingredient decks face the steepest revalidation burdens.
Foodservice buyers in Saudi Arabia are consolidating procurement decisions into centralized technical specifications that specify exact protein percentages and microbial thresholds, displacing spot-market purchasing relationships that dominated historical dairy sourcing. Hotel chains in Jeddah and Riyadh now require supplier laboratory certification as a contract precondition. This concentration of buying power is compressing supplier margins while raising technical entry barriers.
GCC Dairy Market Segmentation
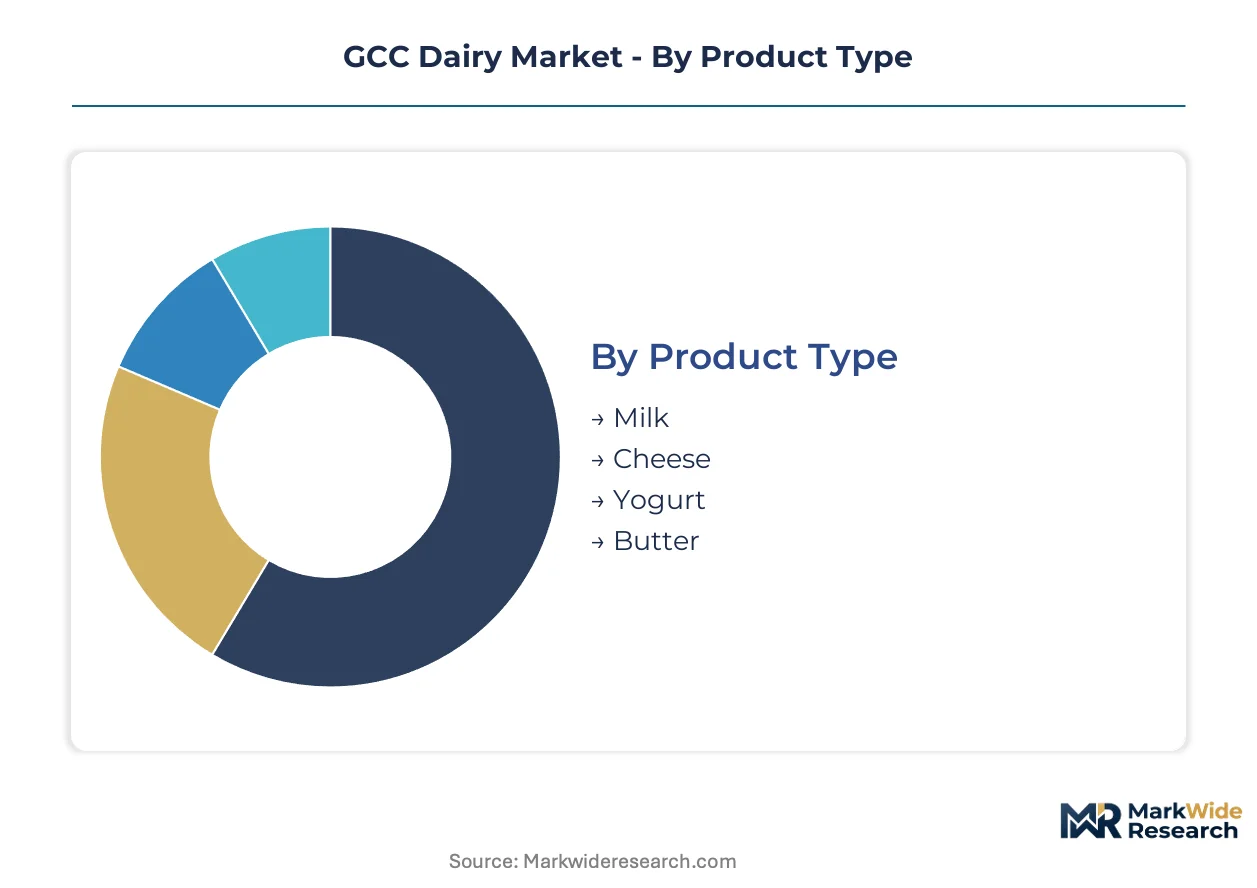
GCC dairy procurement splits sharply between standardized retail formats and precision-specified foodservice contracts. Processing investments and cold-chain configurations diverge meaningfully across these segment boundaries, determining which operators capture margin pools.
Product Type:
Processing technology and shelf-life specifications create divergent margin structures across fluid and fermented categories.
- Milk:Pasteurized and UHT variants dominate volume flows, with protein standardization through membrane filtration now baseline for hotel and cafe procurement in Riyadh. Seven-day fresh limits under GSO regulations compress distribution economics for non-UHT lines.
- Yogurt:Microbial culturing precision for texture and probiotic counts commands expanding shelf space in Saudi retail pharmacy channels. Ambient-stable drinking yogurt formats are gaining traction in UAE convenience stores seeking reduced refrigeration dependency.
- Cheese:Processed and natural varieties serve distinct end-uses, with shredded and sliced formats pulling through foodservice centralized procurement.
- Butter:Fat-based derivatives anchor bakery and confectionery manufacturing specifications across Dubai and Jeddah industrial kitchens.
Mature deployment sits with Milk. Newer deployment is concentrated in Yogurt.
Distribution Channel:
Cost-to-serve economics and Arabic-labeling compliance burdens reshape competitive access across retail and institutional pathways.
- Supermarkets:Chilled dairy cabinets in Saudi Arabia and UAE hypermarkets demand continuous cold-chain integrity and bilingual packaging validation. Almarai and regional majors dominate through direct store delivery networks with captive fleet assets.
- Convenience Stores:Extended-shelf-life UHT formats reduce refrigeration footprint for small-format UAE and Qatar outlets. Koita FZE and similar specialists target this channel with premium ambient-stable positioning.
- Online Retail:Temperature-controlled last-mile logistics constrain fresh fluid milk penetration, though yogurt and processed cheese move through grocery delivery platforms.
- Food Service:Centralized technical specifications in Dubai and Riyadh hotel chains now mandate laboratory certification and exact compositional tolerances as contract preconditions.
Volume concentrates in Supermarkets. Margin expansion is steepest in Food Service.
Customer Type:
Application precision requirements separate spot-market purchasers from integrated supply relationships.
- Households:Price-sensitive bulk purchasing of standardized milk and yogurt drives private-label and economy-tier competition in Saudi retail.
- Restaurants:Ingredient-grade specifications for cooking and baking applications pull processed cheese and butter derivatives through distributor networks.
- Hotels:Jeddah and Riyadh properties now consolidate procurement into technical audits specifying protein percentages and microbial thresholds, displacing historical spot relationships.
- Cafes:Beverage menu expansion across Dubai specialty coffee chains is pulling higher-margin barista milk and flavored yogurt derivatives through specialized contracts.
Procurement standardization is most advanced with Hotels. Relationship fragmentation persists with Households.
End Use Application:
Functional performance requirements determine formulation investments and certification burdens.
- Baking:Fat content tolerances and emulsification properties in butter and processed cheese formulations are specified in Dubai industrial bakery procurement contracts.
- Cooking:Heat stability and flavor retention in fluid milk and cream products serve Saudi Arabian and UAE restaurant kitchen applications.
- Snacking:Portion-controlled yogurt and cheese formats target convenience-oriented consumption in Qatar and Kuwait retail channels.
- Beverages:Protein standardization and foaming characteristics in milk and fermented drinks support cafe menu innovation across Riyadh and Dubai.
Specification tightening runs deepest in Baking. Format innovation is most active in Beverages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors GCC dairy demand through its dense foodservice corridor and expanding retail pharmacy networks. The kingdom's procurement specifications now exceed neighboring states in technical precision.
Saudi Arabia
Hotel chains in Jeddah and Riyadh mandate laboratory-certified protein percentages for fluid milk contracts. SFDA labeling mandates drive reformulation investments among domestic processors. The Eastern Province dairy cluster concentrates feed-to-shelf operations with captive herd infrastructure.
United Arab Emirates
Dubai's specialty cafe segment pulls barista-grade milk through specialized procurement channels. UAE Ministry of Climate Change and Environment import protocols enforce Arabic-labeling validation before port entry. Abu Dhabi industrial zones host ambient-stable UHT processing for convenience store distribution.
Qatar
Doha's hospitality sector upgrades dessert menu specifications for fermented dairy derivatives. The country's national food safety regulator maintains strict cold-chain documentation requirements for fresh imports. Lusail development corridors attract regional dairy distributors seeking premium positioning.
Kuwait
Retail pharmacy chains in Kuwait City expand probiotic yogurt shelf space for digestive health positioning. Import dependency on foreign-origin starter cultures creates supply vulnerability through regional shipping lanes. The Shuwaikh industrial area processes re-export volumes for Iraqi and Iranian border trade.
Oman
Muscat's underpenetrated processing landscape offers white space for halal-certified exporters with Arabic-labeling capabilities. The country's national standards body aligns with GSO technical regulations for shelf-life claims. Sohar port free zones enable regional re-export without domestic manufacturing scale.
GCC Dairy Market Key Industry Players
Capital-heavy integrated producers compete with asset-light brand marketers across procurement and distribution tiers. Market structure concentrates around three operator archetypes: feed-to-shelf integrators controlling captive dairy herds, extended-shelf-life formulators targeting convenience channels, and multinational brand licensors leveraging regional manufacturing partnerships. Consolidation pressures favor operators with dedicated regulatory affairs teams and in-house laboratory testing capabilities. Dominant competitive moves include backward integration into alfalfa and soybean meal supply chains and strategic partnerships with hotel procurement consortia.
Among Saudi-based integrated operators, Almarai Company and National Agricultural Development Company occupy positions defined by captive herd scale and direct store delivery networks. Koita FZE represents the extended-shelf-life formulation archetype through UHT positioning in UAE and Qatar convenience channels. Nestlé and Danone exemplify multinational brand licensing approaches with regional manufacturing partnerships.
| Leading Market Players |
|---|
| Al Rawabi Dairy |
| Koita FZE |
| Almarai Company |
| Nestlé |
| Danone |
| Saudia Dairy & Foodstuff Co Ltd (SADAFCO) |
| Al Ain Dairy |
| Arla Foods |
| National Agricultural Development Company (NADEC) |
| Others |
Cost & Logistics Intelligence
Chicago Mercantile Exchange Class III milk futures volatility cascades through GCC dairy supply chains, compressing margins for processors locked into long-dated hotel contracts while rewarding operators with captive alfalfa and soybean meal sourcing. The resulting cost asymmetry stratifies pricing tiers between integrated feed-to-shelf producers and import-dependent formulators.
Pricing Analysis
Yield-based pricing anchors foodservice contracts in Riyadh and Dubai, where hotel procurement teams specify protein percentages and microbial thresholds as performance guarantees. Three-tier pricing structure across premium organic, extended-shelf-life UHT, and economy fluid milk segments reflects certification grade and cold-chain investment depth. Price compression runs through economy tiers as Saudi retail private-label competition intensifies. Households in Jeddah and Riyadh hypermarkets exhibit highest price sensitivity, while Dubai hotel chains prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Saudi hotel procurement consortia mandate qualified backup suppliers for fluid milk and fermented products, forcing processors to maintain redundant production lines. Feed inputs draw from Argentina, the United States, and domestic Saudi alfalfa cultivation. Starter cultures and aseptic packaging substrates hinge on European and Asian manufacturing. Single-source vulnerability concentrates in specialty probiotic strains shipped through the Strait of Hormuz. Distribution runs through direct store delivery networks for chilled retail and ambient-stable logistics for convenience channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC dairy sector sits in a processing-technology transition, where membrane filtration and automated microbial culturing displace legacy batch-homogenization systems. UHT extended-shelf-life formats are displacing seven-day fresh fluid milk in convenience and hospitality channels.
For Market Incumbents: Extend laboratory certification capabilities to meet Riyadh hotel chain technical audit requirements, consolidating procurement relationships that smaller competitors cannot service. Deepen backward integration into Saudi Eastern Province alfalfa cultivation to buffer Chicago Mercantile Exchange feed cost volatility. SFDA labeling mandate compliance creates defensive moats against import-dependent challengers. For New Entrants and Emerging Players: Begin with halal-certified ambient-stable UHT formulations targeting Oman and Bahrain underpenetration, where indigenous processing scale remains limited. Muscat retail and Sohar free zone re-export channels offer lowest competitive density. Anchor initial presence through Arabic-labeling pre-validation and GSO shelf-life claim alignment. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale processors with stranded chilling infrastructure in UAE industrial zones, where legacy refrigeration assets face obsolescence from ambient-stable format adoption. Long-term viability centers on regulatory affairs team depth and in-house pathogen screening capabilities. Watch SFDA-UAE Ministry of Climate Change and Environment harmonization progress as inflection signal for cross-border margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Supply | Captive alfalfa and soybean meal sourcing insulates Almarai and NADEC from CME futures volatility. |
| Extended-Shelf-Life UHT Capacity Expansion | Abu Dhabi industrial zones enable Koita FZE to reduce cold-chain dependency in Qatar convenience channels. |
| Regulatory Affairs Team Buildout | SFDA and GSO filing specialization creates competitive exclusion against mid-scale processors. |
| Hotel Procurement Consortium Partnerships | Riyadh and Jeddah chain technical specifications lock in multi-year volume commitments. |
| Arabic-Labeling Pre-Validation Investment | UAE Ministry of Climate Change and Environment port-entry compliance accelerates product registration timelines. |
Research Approach
Document review covered SFDA regulatory filings, GSO technical regulations, UAE Ministry of Climate Change and Environment import protocols, and Saudi foodservice procurement specifications, complemented by interviews with dairy processing plant managers, hotel procurement directors, retail category buyers, regulatory affairs consultants, and cold-chain logistics operators. Secondary sources included customs and trade flow databases, SEC 10-K disclosures from listed processors, and hospitality industry procurement surveys. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Projected market values across the analysis window reflect segment-level modeling of product type, distribution channel, customer category, and end-use application dimensions. CAGRs derive from historical trajectory analysis adjusted for regulatory mandate implementation timelines and foodservice channel expansion rates. Forecast inputs incorporated alfalfa and soybean meal price scenario testing, Strait of Hormuz shipping lane risk weighting, and halal certification harmonization probability assessments.
Underlying measurement precision varies by segment; fluid milk and yogurt volume flows carry tighter precision than fermented specialty derivatives where probiotic count standardization remains emergent. Forecasts reflect documented assumptions regarding SFDA enforcement timelines and hotel procurement consolidation velocity. A model refresh is warranted upon material change in GSO halal certification harmonization talks or Saudi feed import tariff adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Yogurt Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Fruit Yogurt Market
Dairy Products
Middle East Dairy Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Recombined Milk Market
Dairy Products
Sour Cream Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Green Tea Butter Market
Dairy Products
Cheese Packaging Market
Dairy Products
Japan Casein Market