
 Real Estate (Property) Management Market | 2026-2036
Real Estate (Property) Management Market Size, Share, and Industry Trends Forecast 2026-2036
Real Estate (Property) Management Market Analysis
Property-level ancillary revenue is fragmenting as owners unbundle leasing, maintenance, and amenity operations into specialized contracts. Greystar Real Estate Partners dominates the build-to-rent management vertical across major US metros. Cushman & Wakefield anchors its competitive position through integrated facilities and project management for commercial office portfolios. Avenue5 Residential differentiates via technology-led operating platforms targeting workforce housing assets.
Real estate property management encompasses the operational oversight, financial administration, and physical maintenance of income-producing properties, typically governed by lease structures, local housing codes, and asset-level performance benchmarks such as net operating income and occupancy velocity. The discipline exists to preserve capital value, optimize rental yields, and ensure regulatory compliance across diverse property portfolios. Property management services within the service-type dimension command the deepest margin pools due to recurring fee structures and tenant relationship intensity, while cloud-based solutions in the technology dimension are expanding fastest as operators replace legacy on-premise systems. Residential property types sustain the largest absolute volume base, though mixed-use assets are gaining management share as developers seek operational synergies across combined retail and living spaces.
The US Department of Housing and Urban Development shapes fair housing enforcement and subsidy program compliance, directly affecting property manager training costs and liability exposure. In Europe, the EU Energy Performance of Buildings Directive mandates building-level energy transparency, forcing managers to adopt IoT-enabled monitoring systems or face restricted market access. Stakeholders must monitor how fragmented local rent-control ordinances and evolving carbon-disclosure requirements will reshape fee structures and technology procurement priorities.
Market Dynamics
Smart building platform mandates from the EU Energy Performance of Buildings Directive are compressing technology procurement timelines across European portfolios and forcing asset owners to replace legacy operational systems with IoT-enabled infrastructure.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Mandates building-level energy transparency and IoT monitoring adoption, creating compliance-driven demand for integrated property management platforms across Germany, France, and the Netherlands.
- Suburban mixed-use developments:Developers in Australia, the United Kingdom, and Germany are consolidating retail and residential operations under single management contracts to capture operational synergies.
- Cloud-based solutions:Operators are replacing legacy on-premise systems with SaaS platforms, reducing capital expenditure requirements and accelerating deployment cycles across multifamily portfolios.
Market Restraints
- Fragmented local rent-control ordinances:Municipal-level caps on rental increases in California, New York, and Oregon compress fee revenue predictability for third-party managers.
- Skill concentration in Sun Belt metros:Experienced property management talent clusters in Texas, Florida, and Arizona, creating wage inflation and recruitment friction for operators expanding into secondary markets.
- Technical debt in legacy HVAC systems:Pre-2010 building stock across Southern Europe lacks sensor infrastructure compatible with mandated energy monitoring platforms.
Strategic Opportunities
- Workforce housing technology platforms:Avenue5 Residential's operating model demonstrates scalable deployment of automated leasing and maintenance workflows for Class B multifamily assets.
- Integrated facilities and project management:Commercial office owners are consolidating vendor relationships, creating demand for single-source providers capable of spanning routine operations and capital improvements.
- Carbon disclosure alignment:The EU Green Deal's corporate sustainability reporting requirements position property managers with certified emissions tracking capabilities to capture institutional capital mandates.
Industry Challenges
- Cross-functional talent scarcity:Property managers must now combine traditional lease administration expertise with data analytics and IoT platform administration, a skill intersection with limited training pathways.
- Integration complexity with legacy accounting systems:Cloud-based property management platforms require custom API development to synchronize with entrenched owner financial reporting infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real Estate (Property) Management Market |
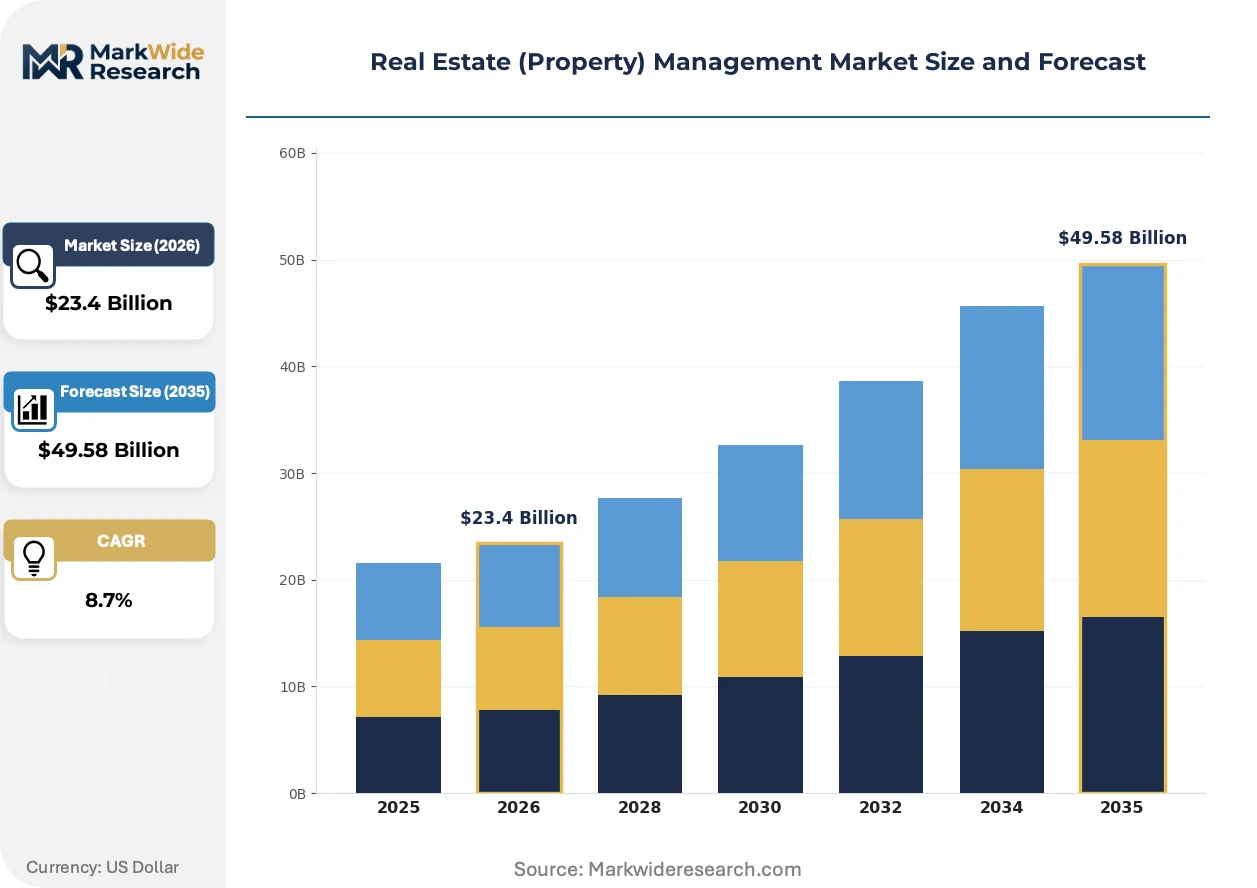
| Market Size in 2026 | $23.4 Billion |
| Market Size in 2035 | $49.58 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Property Management, Facilities Management, Financial Management, Project Management Property Type: Residential, Commercial, Industrial, Mixed-Use Technology: Property Management Software, Cloud-Based Solutions, Mobile Applications, IoT Solutions Client Type: Landlords, Real Estate Companies, Tenants, Investors |
| Companies Covered | Greystar Real Estate Partners, Asset Living, RPM Living, Willow Bridge Property Company, Cushman & Wakefield, FPI Management, BH Management Services, Avenue5 Residential, Apartment Management Consultants, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real Estate (Property) Management Market Emerging Trajectories
Operational technology convergence is compressing the traditional separation between physical building systems and financial management software, creating unified platforms that span tenant experience, energy monitoring, and investor reporting.
Digital twin technology is collapsing the cost structure of predictive maintenance across large multifamily portfolios. Asset operators in the United States and Germany are deploying building information modeling integrated with real-time sensor feeds to anticipate HVAC and plumbing failures before tenant impact. This capability is collapsing the traditional reactive maintenance model and shifting vendor relationships toward outcome-based service level agreements.
The EU Energy Performance of Buildings Directive mandates granular energy disclosure at the individual building level by 2030. Commercial landlords across France, Germany, and Spain must install sub-metering infrastructure or face restricted leasing authority to corporate tenants with net-zero commitments. Office properties with poor energy ratings are experiencing accelerated obsolescence as institutional investors divest from non-compliant assets.
Institutional owners are unbundling property management contracts into specialized components. Separate agreements now govern leasing, facilities maintenance, and amenity programming, with each function awarded to niche operators demonstrating superior performance in specific metrics. This fragmentation is most visible in build-to-rent assets across London, Sydney, and Dallas, where owners optimize each operational layer independently.
Real Estate (Property) Management Market Segmentation
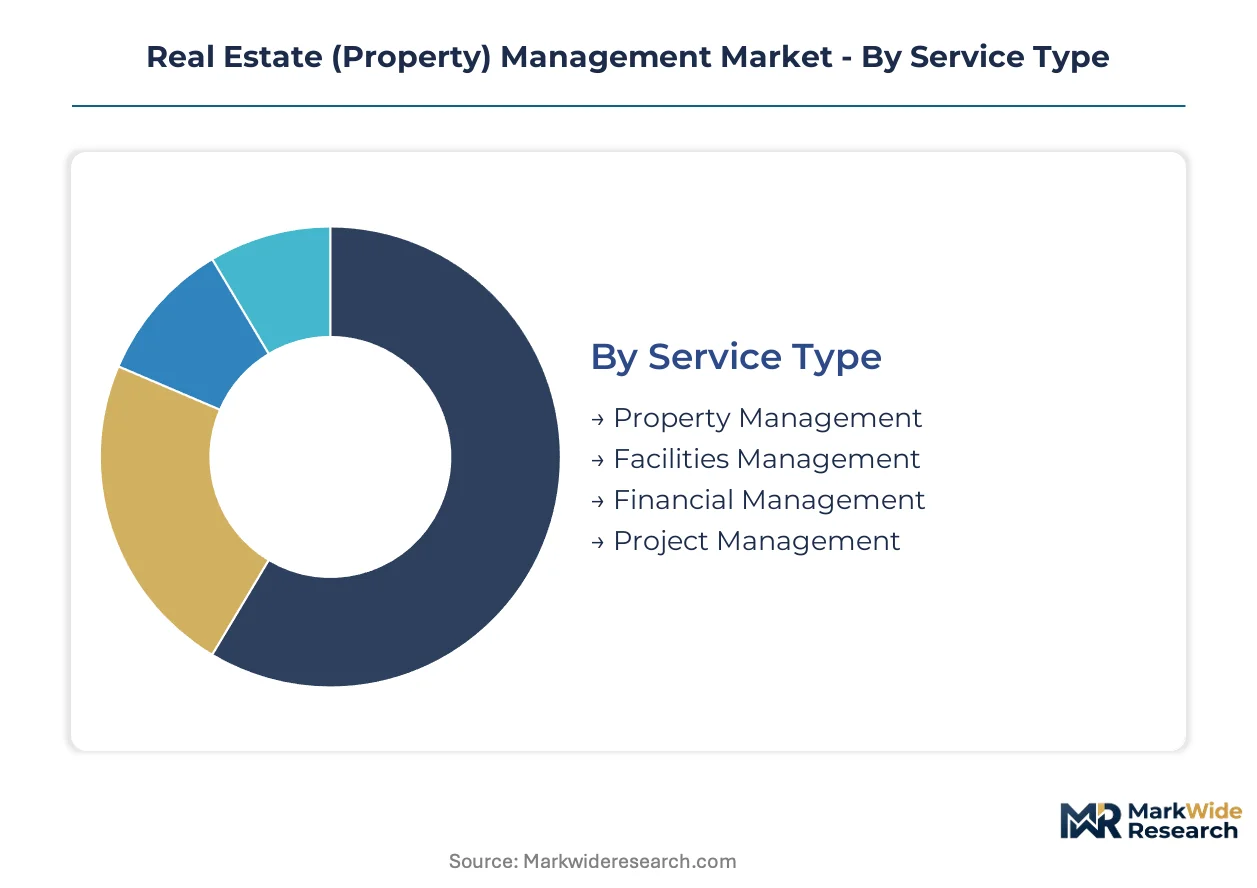
Segmentation in property management reveals how fee structures, technology procurement, and client relationships fragment across operational models. Each dimension carries distinct margin profiles and competitive dynamics that shape vendor positioning.
Service Type:
Use cases span from routine tenant relations to complex capital project oversight, with fee predictability varying by contract structure.
- Property Management:Core operational oversight encompassing lease administration, tenant screening, and rent collection. Demand concentrates in Sun Belt multifamily portfolios where institutional owners outsource day-to-day operations to third-party specialists. Recurring fee structures generate the deepest margin pools due to relationship intensity and renewal predictability.
- Facilities Management:Physical asset maintenance spanning HVAC, plumbing, and common area upkeep. European commercial office portfolios drive procurement as EU Energy Performance of Buildings Directive mandates force upgrades to legacy building systems. Integrated facilities contracts are consolidating vendor relationships across Germany and the Netherlands.
- Financial Management:Budgeting, investor reporting, and compliance documentation for asset-level performance tracking.
- Project Management:Capital improvement planning and construction oversight for value-add repositioning strategies.
The dominant share belongs to Property Management, while Facilities Management is closing the gap fastest.
Property Type:
Cost tiers separate premium institutional-grade assets from workforce housing and light industrial facilities with thinner operating margins.
- Residential:Multifamily apartment communities and single-family rental portfolios requiring intensive tenant turnover management. Suburban mixed-use developments in Australia and the United Kingdom are consolidating retail and living operations under unified management contracts. Build-to-rent verticals across Dallas and London attract specialized operators.
- Commercial:Office, retail, and hospitality assets governed by complex lease structures and CAM reconciliation. US Department of Housing and Urban Development fair housing enforcement shapes training costs and liability exposure for managers handling federally subsidized properties. Cushman & Wakefield anchors market position through integrated facilities and project management capabilities.
- Industrial:Warehouse and distribution facilities with minimal tenant services and lower management intensity.
- Mixed-Use:Combined retail, residential, and office developments seeking operational synergies across asset classes.
Residential assets command the largest absolute volume base, though Mixed-Use is expanding most quickly as developers pursue integrated operational models.
Technology:
Maturity curves separate legacy on-premise installations from cloud-native platforms with accelerated deployment cycles.
- Property Management Software:Comprehensive platforms spanning accounting, leasing, and maintenance workflows. Cloud migration is displacing legacy systems across US multifamily portfolios as operators reduce capital expenditure requirements. Avenue5 Residential demonstrates scalable deployment of automated workflows for Class B assets.
- Cloud-Based Solutions:SaaS delivery models enabling remote access and rapid feature updates without infrastructure investment. European portfolios face compressed procurement timelines as EU Energy Performance of Buildings Directive mandates drive technology substitution. Germany and France lead continental adoption.
- Mobile Applications:Tenant-facing interfaces for rent payment, maintenance requests, and amenity booking.
- IoT Solutions:Sensor infrastructure for energy monitoring, predictive maintenance, and building automation.
Property Management Software retains the largest installed base, while Cloud-Based Solutions are gaining share fastest among mid-market operators.
Client Type:
Customer concentration varies from dispersed individual landlords to consolidated institutional investors with standardized procurement requirements.
- Landlords:Individual and small-portfolio owners seeking outsourced operational expertise. Fragmented local rent-control ordinances in California, New York, and Oregon compress fee revenue predictability for managers serving this segment. Municipal-level caps constrain pricing flexibility.
- Real Estate Companies:Development and investment firms with captive management arms or preferred vendor relationships. Greystar Real Estate Partners dominates build-to-rent management verticals across major US metros through vertical integration of development and operations.
- Tenants:Corporate and residential end-users purchasing amenity and service packages directly.
- Investors:Institutional capital deploying capital into managed vehicles with certified emissions tracking requirements.
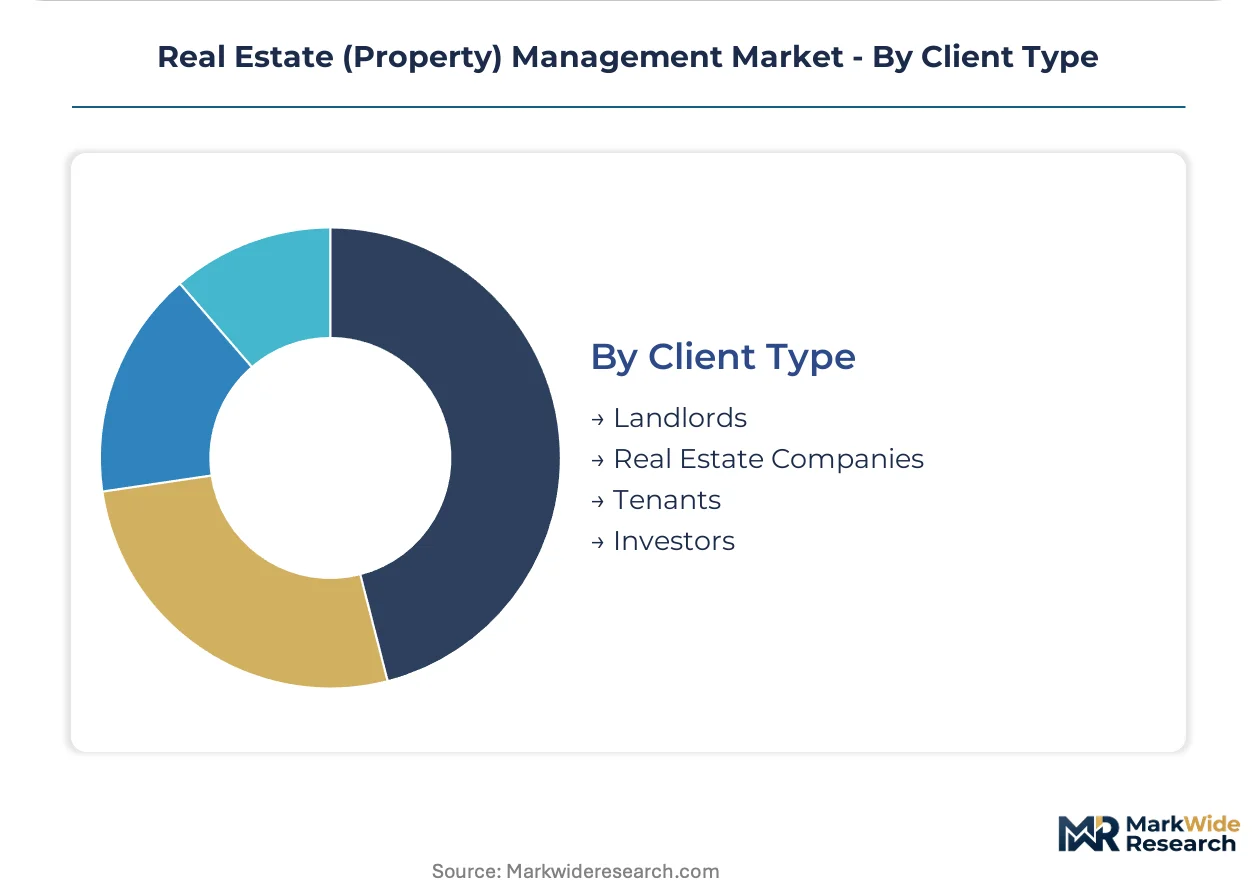
Real Estate Companies represent the most concentrated revenue source, while Investors are driving the steepest expansion trajectory through ESG-mandated procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes property management services through institutional third-party outsourcing, while Germany and Australia emphasize technology-integrated compliance platforms, and the United Kingdom pursues fragmented specialization across build-to-rent verticals.
United States
Sun Belt metros drive third-party management expansion as institutional owners consolidate multifamily portfolios. The Department of Housing and Urban Development enforces fair housing compliance, elevating training costs and liability exposure. Dallas and Phoenix anchor build-to-rent concentration, where Greystar Real Estate Partners dominates vertical integration of development and operations.
Germany
Commercial office portfolios accelerate IoT-enabled infrastructure replacement under EU Energy Performance of Buildings Directive mandates. The country's federal building energy regulations enforce granular disclosure requirements by 2030. Frankfurt and Munich concentrate facilities management procurement as landlords face restricted leasing authority without sub-metering compliance.
United Kingdom
London developers unbundle management contracts into specialized leasing, maintenance, and amenity components. The UK's net-zero building standards pressure office owners toward certified emissions tracking capabilities. Build-to-rent assets across Greater London attract niche operators optimizing each operational layer independently.
Australia
Suburban mixed-use developments consolidate retail and residential operations under unified management contracts. The country's National Construction Code advances energy efficiency benchmarks for commercial building stock. Sydney and Melbourne lead technology platform adoption as operators capture operational synergies across combined living and retail spaces.
France
Commercial landlords deploy sub-metering infrastructure to retain corporate tenants with net-zero commitments. The EU Green Deal's corporate sustainability reporting requirements shape institutional capital mandates. Paris office properties with poor energy ratings experience accelerated obsolescence as investors divest from non-compliant assets.
Real Estate (Property) Management Market Vendor Landscape
Capability concentration sits with technology-led specialists; scale advantage sits with vertically integrated operators. The market structure fragments across three tiers: institutional platforms with captive development pipelines, third-party specialists targeting asset-class niches, and regional operators serving fragmented landlord bases. Dominant competitive moves include portfolio diversification across property types and geographic expansion into secondary Sun Belt metros.
Within the institutional platform tier, Greystar Real Estate Partners and Cushman & Wakefield exemplify divergent scale strategies. Greystar anchors build-to-rent concentration through vertical integration of development and operations across major US metros. Cushman & Wakefield occupies a position spanning integrated facilities and project management for commercial office portfolios. Avenue5 Residential represents the technology-led specialist archetype, demonstrating automated leasing and maintenance workflows for workforce housing assets.
| Leading Market Players |
|---|
| Greystar Real Estate Partners |
| Asset Living |
| RPM Living |
| Willow Bridge Property Company |
| Cushman & Wakefield |
| FPI Management |
| BH Management Services |
| Avenue5 Residential |
| Apartment Management Consultants |
| Others |
Supply Flow & Price Mechanics
EU Energy Performance of Buildings Directive compliance deadlines compress technology procurement timelines across European portfolios, forcing asset owners to absorb accelerated IoT infrastructure costs while simultaneously widening spreads between compliant and non-compliant property management fee tiers.
Pricing Analysis
Long-term management contracts anchor revenue predictability for institutional operators, while spot-market leasing services and project-based capital improvement oversight introduce pricing volatility. Three-tier pricing structure across premium, standard, and economy levels separates technology-enabled full-service operators from legacy maintenance-only providers and fragmented landlord self-management. Pricing pressure stems from municipal rent-control ordinances in California, New York, and Oregon that compress fee revenue ceilings. Workforce housing landlords exhibit highest price sensitivity, while institutional investors prioritize compliance capabilities over cost minimization.
Supply Chain Analysis
Cloud infrastructure providers including Amazon Web Services, Microsoft Azure, and Google Cloud Platform concentrate data center capacity for property management SaaS platforms across the United States, Ireland, and Germany. Software development draws from specialized IoT sensor manufacturers, API integration specialists, and legacy accounting system vendors. Single-source vulnerability sits with concentrated cloud provider ecosystems facing regulatory data localization requirements. Distribution runs through direct enterprise sales teams and channel partnerships with real estate investment firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment—EU Energy Performance of Buildings Directive mandates create compliance switching costs that institutionalize incumbent relationships and deter price-based competition.
For Market Incumbents: Build regulatory compliance moats through certified emissions tracking capabilities and pre-negotiated IoT infrastructure partnerships. Deepen backward integration into smart building platform development to capture technology substitution margins. Consolidate secondary Sun Belt metro presence before wage inflation erodes workforce housing returns. Threat vector: cloud-native entrants with automated leasing workflows. For New Entrants and Emerging Players: Pursue workforce housing technology platforms in secondary US metros where incumbent coverage remains thin. Target suburban mixed-use developments across Australia and Germany seeking unified retail-residential management contracts. White-space opportunity: IoT-enabled predictive maintenance for pre-2010 Southern European building stock lacking sensor infrastructure. Go-to-market angle: outcome-based service level agreements with guaranteed energy compliance. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors vertically integrated operators with captive development pipelines. Long-term viability across the analysis window hinges on carbon disclosure alignment capabilities. Acquisition target archetype: technology-led specialists with automated workflow deployment for Class B multifamily assets. Signal to watch: institutional capital mandates shifting toward certified emissions tracking as EU Green Deal reporting requirements mature.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | EU Energy Performance of Buildings Directive mandates force sensor infrastructure adoption across German and French commercial portfolios. |
| Backward Integration into Development | Greystar's build-to-rent model demonstrates margin capture through unified development and operations control. |
| Workforce Housing Technology Deployment | Avenue5 Residential validates scalable automated leasing workflows for Class B multifamily assets. |
| Facilities Management Consolidation | Cushman & Wakefield anchors position through single-source contracts spanning routine operations and capital improvements. |
| Carbon Disclosure Certification | EU Green Deal reporting requirements position certified operators to capture institutional capital mandates. |
Methodological Framework
Initial hypotheses were tested against primary input from property management executives, asset-level operations directors, institutional investor portfolio managers, and smart building technology vendors and refined through secondary validation against SEC 10-K filings, EU regulatory directive texts, commercial real estate transaction databases, and industry association benchmark reports. Bottom-up triangulation across service-type segmentation combined with top-down macroeconomic scenario modeling anchored volume and value estimates.
Demand-supply balance framing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type, property type, technology deployment model, and client concentration tier. CAGRs were derived through iterative convergence of historical trajectory analysis and forward-looking scenario weighting. Industry-specific forecast inputs incorporated EU Energy Performance of Buildings Directive compliance timelines and Sun Belt multifamily absorption velocity.
Sensitivities concentrate around fragmented local rent-control ordinance expansion, cloud infrastructure cost volatility, and cross-functional talent scarcity. Forecasts reflect assumptions regarding technology substitution rates and institutional outsourcing penetration. Quarterly review of municipal regulatory filings, cloud provider pricing announcements, and multifamily development permit data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
Property Management Software Market
Property Management
Spain Warehousing Market
Property Management
Qatar Flexible Office Space Market
Property Management
Space Planning and Space Management Solutions Market
Property Management
United States Property Management Market
Property Management
Real Estate Management Software Market
Property Management
Hungary Warehousing Sector Market
Property Management
Property Management Service Market
Property Management
Europe Self Storage Market
Property Management
South Korea Self-Storage Market
Property Management
Residential Property Management Market
Property Management
US Property Management Software Market