
 Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market | 2026-2036
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market Insights
The waterproof concrete admixture market is pivoting on a widening divergence between premium crystalline systems and commodity silane-based pore blockers. Sika leverages its integrated supply chain for silane precursors to sustain margin capture across European infrastructure tenders. Master Builders Solutions anchors its position through specialized injection-grade formulations for below-grade applications. Kryton International differentiates via crystalline technology leadership that commands specification preference in marine exposure zones.
Hydrophobic pore-blocking agents are surface-active or integral chemical admixtures that reduce water absorption in hardened concrete by modifying capillary pore surfaces, typically achieving hydrophobic contact angles above 90 degrees through silane or siloxane chemistry. These compounds serve primarily to extend structural service life in chloride-laden or freeze-thaw environments by blocking liquid water ingress while permitting vapor transmission. Silane-based formulations occupy the mature volume tier where price competition compresses margins, whereas fluoropolymer-modified systems represent the fastest-growing premium segment driven by specification upgrades in marine structures. Application demand concentrates beneath bridge decks and within tunnel linings where hydrostatic pressure cycling accelerates degradation of untreated substrates.
REACH registration requirements in Europe, EPA toxicity evaluations under TSCA in the United States, and China's GB standards for construction chemicals collectively shape formulation disclosure burdens and substitution timelines for hydrophobic admixtures. ECHA's evolving restrictions on per- and polyfluoroalkyl substances are forcing reformulation roadmaps for fluoropolymer-containing products ahead of sunset date uncertainties. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D commitments.
Market Dynamics
EU Green Deal mandates and F-Gas Regulation restrictions are forcing wholesale reformulation of hydrophobic admixtures, compressing timelines for fluoropolymer substitution while elevating silane-based alternatives in infrastructure specifications.
Growth Catalysts
- EU Green Deal decarbonization targets:Infrastructure tenders in Germany now specify hydrophobic admixtures exceeding baseline waterproofing requirements for bridge deck applications.
- Chloride-laden marine exposure:Tunnel lining specifications in coastal China mandate integral pore-blocking chemistry to extend structural service life under hydrostatic pressure cycling.
- Freeze-thaw durability mandates:United States state DOTs are embedding hydrophobic contact angle requirements into below-grade concrete standards for northern climates.
Market Restraints
- Silane precursor supply concentration:European silane manufacturing clusters face input volatility from energy-intensive chlorosilane production.
- ECHA PFAS restriction uncertainty:Fluoropolymer-containing formulations face stranded inventory risk ahead of evolving sunset date timelines.
- Crystalline waterproofing substitution:Self-healing cementitious systems command specification preference in high-exposure marine zones, compressing premium fluoropolymer volumes.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and metro rail construction create first-mover positioning for silane-based pore blockers in below-grade specifications.
- Digital specification platforms:Building information modeling integration enables real-time admixture performance validation, shortening approval cycles for new formulations.
- Carbon border adjustment mechanism:EU CBAM incentivizes low-emission hydrophobic chemistry, rewarding producers with integrated bio-based silane feedstocks.
Industry Challenges
- Formulation chemist talent scarcity:Cross-disciplinary expertise spanning concrete mineralogy and organosilicon chemistry remains concentrated among legacy European specialists.
- Multi-jurisdiction registration synchronization:REACH disclosure timelines, EPA TSCA evaluation queues, and China's GB standard updates create misaligned market entry windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market |
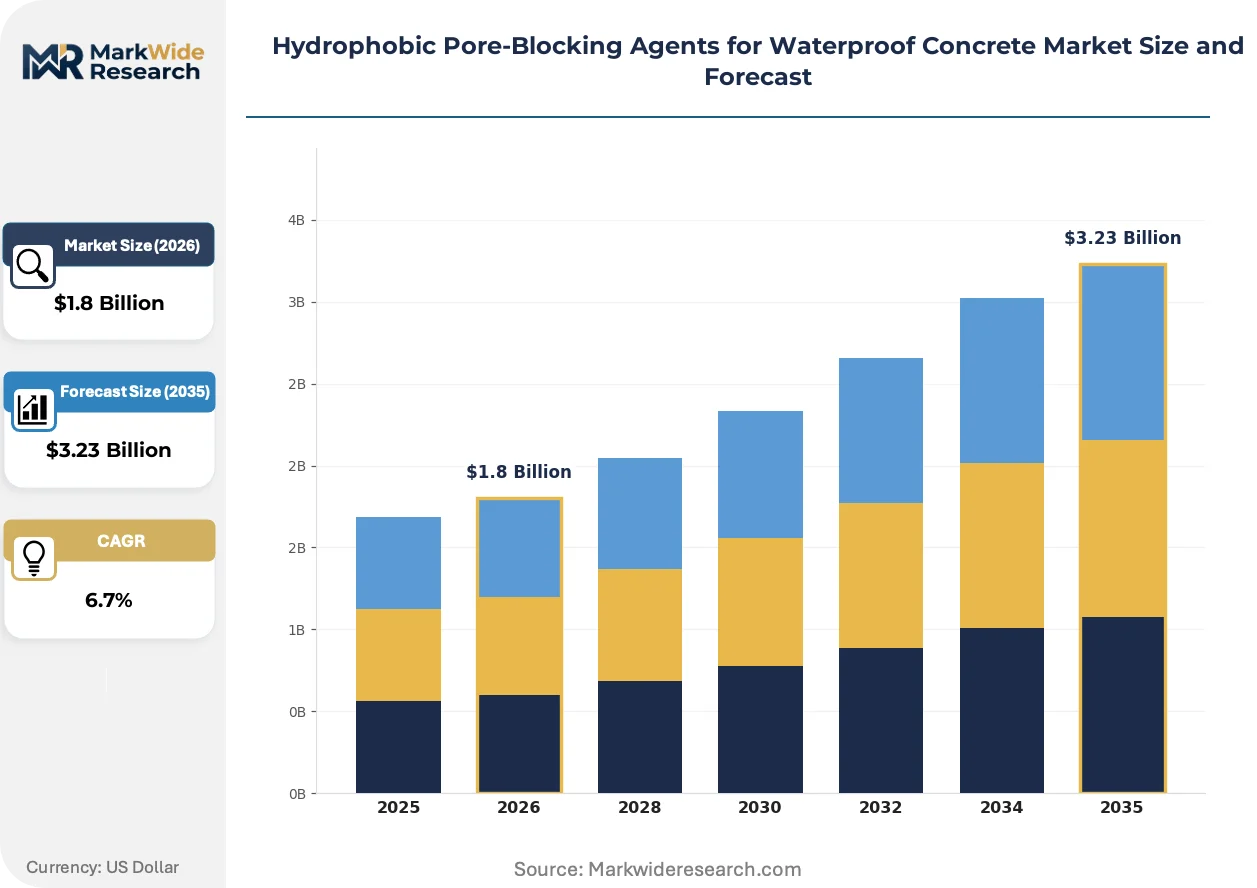
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silane, Siloxane, Siliconate, Fluoropolymer, Acrylic, Polyurethane Application: Bridge Decks, Parking Structures, Tunnel Linings, Marine Structures, Water Treatment Plants, Foundation Walls End User: General Contractors, Specialty Contractors, Infrastructure Developers, Municipal Authorities, Industrial Fabricators, Residential Builders Deployment Method: Spraying, Brushing, Rolling, Injection, Dipping, Flood Coating |
| Companies Covered | Sika, Master Builders Solutions, Mapei, Kryton International, Penetron International, Xypex Chemical, Fosroc, W. R. Grace, Hycrete, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market Trends and Innovations
Formulation science is pivoting toward bio-derived hydrophobic precursors and digital performance verification tools that compress specification cycles while satisfying tightening emissions frameworks.
Silane-fluoropolymer hybrid chemistry is converging with nanostructured surface modification techniques to achieve superhydrophobic contact angles above 150 degrees. Marine infrastructure engineers in the Netherlands are piloting these systems for tidal zone applications. The convergence is compressing addressable market boundaries between commodity silane volumes and premium fluoropolymer positioning.
ECHA's evolving PFAS restriction roadmap is forcing disclosure of perfluorinated content across construction chemical supply chains. Formulators face reformulation deadlines ahead of potential 2027 sunset dates for long-chain fluoropolymers. Marine specification holders in Germany and Denmark are accelerating silane-alternative validation to preempt compliance exposure.
Performance-based procurement contracts now dominate European infrastructure tenders, unbundling material supply from durability guarantees. Contractors assume risk for 50-year service life outcomes, shifting specification authority from general contractors to specialty admixture suppliers. This restructuring is most visible in German autobahn bridge deck projects and Swiss alpine tunnel programs.
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market Segmentation
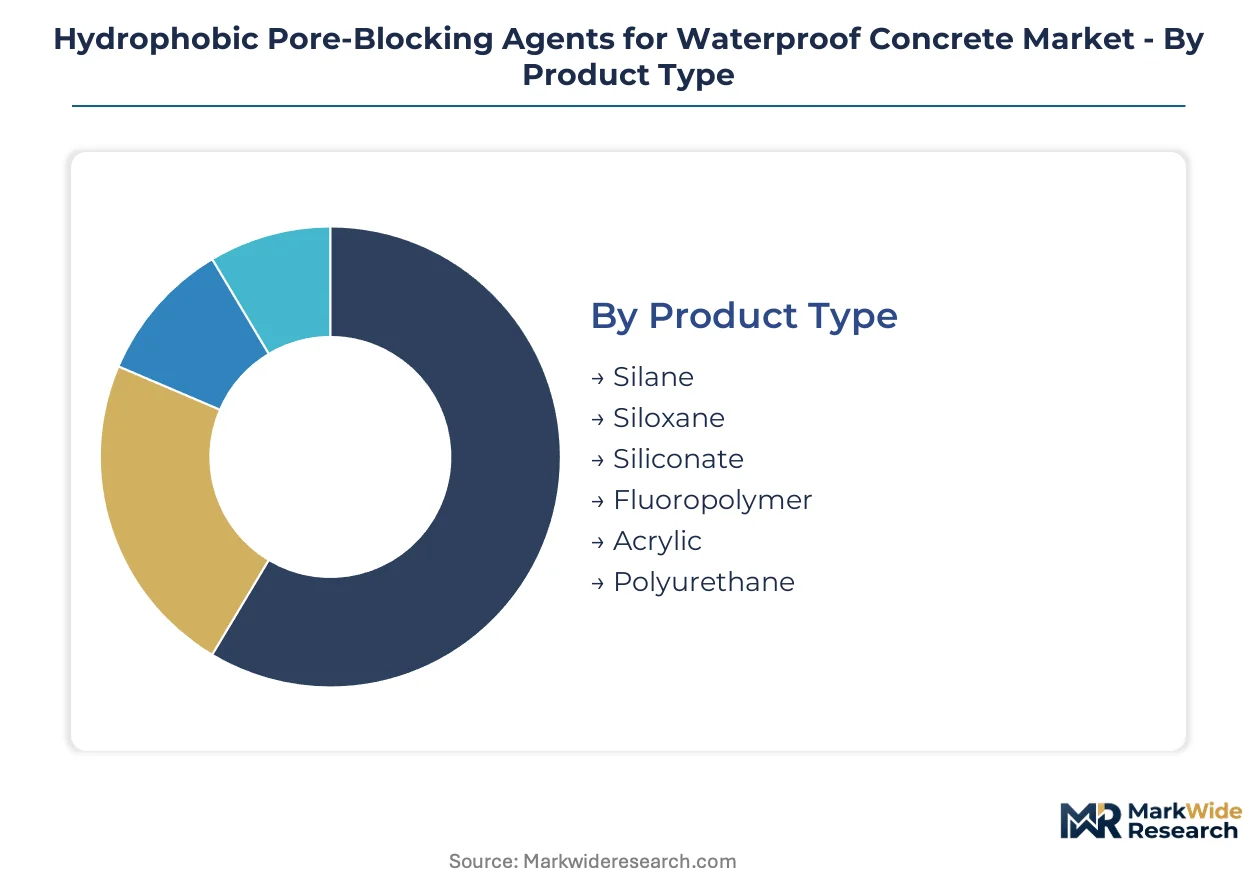
Segmentation in hydrophobic pore-blocking agents reveals divergent margin structures across chemistry families and application environments. Specification authority varies sharply between infrastructure tenders and private construction, reshaping vendor targeting priorities.
Product Type:
Silane precursor supply concentrates in European chlorosilane manufacturing clusters, creating input cost volatility that cascades through formulation economics.
- Silane:Organosilicon compounds with hydrolyzable alkoxy groups form covalent bonds with mineral substrates. German bridge deck specifications now mandate silane-based integral admixtures exceeding baseline waterproofing requirements under EU Green Deal procurement rules.
- Siloxane:Oligomeric silicon-oxygen backbones deliver deeper penetration than monomeric alternatives. Demand concentrates in Chinese tunnel lining projects where hydrostatic pressure cycling accelerates degradation of untreated concrete.
- Siliconate:Water-reactive sodium or potassium silicates suited for alkaline substrates.
- Fluoropolymer:Perfluorinated chains achieving contact angles above 150 degrees face ECHA PFAS restriction uncertainty.
- Acrylic:Film-forming emulsions offering surface-level protection at lower cost tiers.
- Polyurethane:Elastomeric membranes bridging cracks in dynamic substrates.
Silane absorbs the bulk of installed capacity; fluoropolymer is expanding most quickly ahead of potential regulatory sunset dates.
Application:
Cost tier differentiation separates specification-grade marine exposure systems from commodity below-grade treatments.
- Bridge Decks:Cyclic loading and chloride exposure demand hydrophobic contact angles above 90 degrees. United States state DOTs embed these requirements into northern climate standards for freeze-thaw durability.
- Tunnel Linings:Permanent hydrostatic pressure mandates integral pore-blocking chemistry rather than surface coatings. Coastal China infrastructure tenders specify crystalline or silane-hybrid systems for 100-year design lives.
- Parking Structures:De-icing salt exposure drives specification in urban environments.
- Marine Structures:Tidal zone applications pilot superhydrophobic nanostructured surfaces in the Netherlands.
- Water Treatment Plants:Chemical resistance requirements favor fluoropolymer-modified formulations.
- Foundation Walls:Below-grade damp proofing represents volume tier with compressed margins.
Tunnel linings command premium specification authority; bridge decks represent the largest addressable volume pool.
End User:
Customer type determines procurement complexity, with performance-based contracts shifting risk from general contractors to specialty admixture suppliers.
- Infrastructure Developers:Long-durability guarantees dominate EU Green Deal tenders. German autobahn projects now unbundle material supply from 50-year service life outcomes.
- Specialty Contractors:Injection-grade formulation expertise anchors positioning in below-grade repair markets. Swiss alpine tunnel programs specify these suppliers for hydrostatic pressure environments.
- General Contractors:Price-sensitive procurement in residential and commercial construction.
- Municipal Authorities:Public tender compliance with evolving environmental regulations.
- Industrial Fabricators:Prefabricated concrete element producers seeking batch-consistent admixture integration.
- Residential Builders:Commodity silane treatments for basement waterproofing.
Infrastructure developers concentrate specification authority; specialty contractors are gaining share fastest through performance-based contracting.
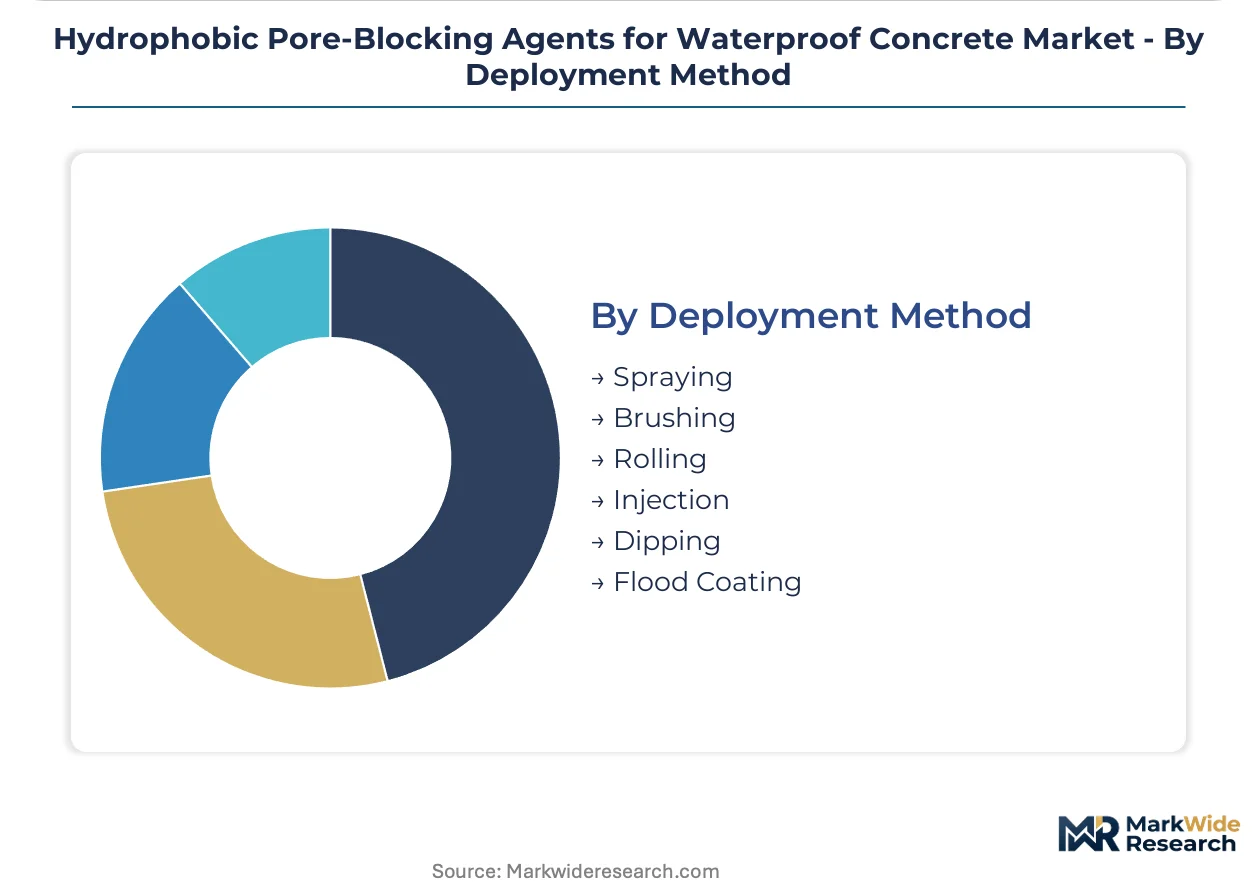
Deployment Method:
Volume scale separates field-applied surface treatments from factory-integrated integral admixtures.
- Injection:Pressure-impregnation of hardened concrete for remedial waterproofing. Master Builders Solutions anchors market position through specialized injection-grade formulations for below-grade applications.
- Spraying:High-volume field application of solvent or water-based formulations. Sika leverages integrated silane precursor supply chains for margin capture in European infrastructure tenders.
- Brushing:Detail work and small-area touch-up applications.
- Rolling:Horizontal surface treatment in parking structures.
- Dipping:Prefabricated element pre-treatment in controlled factory environments.
- Flood Coating:Immersion applications for complex geometries.
Spraying absorbs the bulk of field-installed volume; injection is climbing the fastest as remedial markets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European hydrophobic admixture production, with Düsseldorf-based formulation clusters supplying chlorosilane precursors to infrastructure projects across the continent.
Germany
Autobahn bridge deck specifications now mandate hydrophobic contact angles above 90 degrees under EU Green Deal procurement rules. ECHA's evolving PFAS restrictions are accelerating silane-alternative validation in marine infrastructure tenders. The Bavarian construction chemical cluster around Munich is piloting bio-derived hydrophobic precursors for alpine tunnel applications.
China
Coastal infrastructure buildout in Guangdong and Fujian provinces drives specification for 100-year design life tunnel linings. GB standards for construction chemicals are tightening disclosure requirements for fluorinated content in hydrophobic formulations. The Yangtze River Delta manufacturing belt around Shanghai dominates domestic siloxane production capacity.
United States
State DOTs in Minnesota, Wisconsin, and Michigan are embedding freeze-thaw durability mandates into below-grade concrete standards. EPA toxicity evaluations under TSCA are extending registration timelines for novel organosilicon chemistries. The Houston-Galveston petrochemical corridor supplies silane precursors to Gulf Coast marine construction projects.
Netherlands
Tidal zone infrastructure in the Rotterdam port complex is piloting superhydrophobic nanostructured surfaces for marine exposure applications. The EU F-Gas Regulation is compressing reformulation timelines for fluoropolymer-containing admixtures. Delft-based research institutes are validating silane-fluoropolymer hybrid chemistry for North Sea wind foundation specifications.
India
National highway expansion and metro rail construction in Maharashtra and Karnataka are creating first-mover positioning for silane-based pore blockers. BIS standards for construction chemicals are aligning with international disclosure frameworks for perfluorinated substances. The Delhi-Mumbai Industrial Corridor is concentrating demand for below-grade waterproofing in logistics infrastructure.
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market Competitive Landscape
Premium-margin players sit above commodity-margin players across chemistry family differentiation, with silane-based specialists capturing volume tiers while fluoropolymer formulators defend premium positioning ahead of regulatory sunset dates. The vendor base stratifies into three archetypes: integrated silane precursor producers, specialized injection-grade formulators, and crystalline technology specialists. Consolidation pressure is mounting as performance-based procurement contracts shift 50-year durability risk onto admixture suppliers. Dominant competitive moves include backward integration into chlorosilane feedstocks and technology licensing partnerships for bio-derived hydrophobic chemistry.
Within the integrated supply chain tier, Sika anchors positioning through captive silane precursor production serving European infrastructure tenders. Master Builders Solutions exemplifies the specialized formulator archetype through injection-grade expertise for below-grade hydrostatic pressure environments. Kryton International occupies the crystalline technology vector, commanding specification preference in high-exposure marine zones where self-healing cementitious systems compete with hydrophobic alternatives.
| Leading Market Players |
|---|
| Sika |
| Master Builders Solutions |
| Mapei |
| Kryton International |
| Penetron International |
| Xypex Chemical |
| Fosroc |
| W. R. Grace |
| Hycrete |
| Others |
Pricing and Supply Chain Analysis
Chlorosilane spot price volatility in the Ruhr corridor cascades through formulation economics, compressing margins for silane-based admixtures while amplifying pricing power for producers with captive precursor supply. EU carbon border adjustment mechanisms and energy-intensive production costs are bifurcating the market into premium-anchored and commodity-pressured tiers.
Pricing Analysis
Value-based pricing anchored to 50-year durability guarantees dominates EU infrastructure tenders, unbundling material supply from performance outcomes. Certification under ECHA REACH and alignment with EU Green Deal procurement rules command premium positioning, while commodity silane volumes face cost compression from energy-price volatility and crystalline waterproofing substitution. State DOTs in northern United States climates exhibit highest price sensitivity, whereas German autobahn specifications prioritize performance tier over unit cost.
Supply Chain Analysis
Freight cost escalation from European chlorosilane clusters to Chinese coastal infrastructure sites is reshaping regional sourcing strategies. Supply concentrates in Germany, China, and the United States, with feedstock dependencies spanning chlorosilane precursors, fluoropolymer resins, and bio-derived hydrophobic agents. Single-source vulnerability in European energy-intensive manufacturing feeds supply chain risk. Distribution runs through specialty chemical distributors and direct specification relationships with infrastructure developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward control over chlorosilane feedstocks to secure margin capture against input volatility and regulatory compliance costs.
For Market Incumbents: Extend specification authority through performance-based contracting that assumes 50-year durability risk, locking out commodity competitors. Deepen captive silane precursor production in the Ruhr corridor to defend margin structures against energy-price volatility and ECHA PFAS restriction uncertainty. Prioritize bio-derived hydrophobic chemistry R&D to preempt carbon border adjustment exposure. For New Entrants and Emerging Players: Enter via India's national highway expansion and metro rail construction, where BIS standards alignment creates first-mover positioning before specification consolidation. Target below-grade waterproofing in the Delhi-Mumbai Industrial Corridor, where silane-based pore blockers face limited crystalline substitution pressure. Lead with digital specification platform partnerships to compress approval cycles against entrenched European suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized injection-grade formulators with hydrostatic pressure expertise in Swiss and German alpine tunnel markets. Long-term viability over the next decade hinges on regulatory navigation capability across REACH, EPA TSCA, and China's GB standards. Watch ECHA PFAS sunset date clarity as the inflection signal for fluoropolymer asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Feedstocks | Sika's captive precursor supply secures margin capture in EU infrastructure tenders against energy-price volatility. |
| Performance-Based Contracting | German autobahn projects now unbundle material supply from 50-year service life outcomes, shifting risk to admixture suppliers. |
| Bio-Derived Hydrophobic Chemistry | Bavarian construction chemical clusters pilot plant-based precursors to satisfy EU Green Deal decarbonization mandates. |
| Digital Specification Platform Integration | Building information modeling validation shortens approval cycles for new formulations in competitive infrastructure tenders. |
| Regulatory Pre-Compliance Investment | Marine specification holders in Denmark accelerate silane-alternative validation ahead of ECHA PFAS restriction deadlines. |
Research Methodology
Multi-period observation of hydrophobic contact angle specifications, ECHA regulatory filings, and infrastructure tender awards anchored the trend analysis, supplemented by interviews with formulation chemists, procurement leads at German infrastructure developers, technical directors at specialty admixture suppliers, and regulatory affairs specialists. Secondary validation drew from customs trade data, SEC construction chemical segment disclosures, EU tender databases, and GB standard update bulletins. Bottom-up volume modeling triangulated against top-down spending projections from national infrastructure plans.
Input-output matrices mapped silane precursor supply through formulation tiers to end-use applications across bridge decks, tunnel linings, and marine structures. Segmentation dimensions included chemistry family, deployment method, and specification authority level. CAGRs were derived from regression analysis of historic tender volumes against projected infrastructure spending trajectories. Forecast inputs incorporated EU Green Deal procurement penetration rates and ECHA PFAS restriction scenario weighting.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS sunset timelines or crystalline waterproofing technology breakthroughs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Ocular Adhesives and Sealants Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Japan Adhesives Market