
 Global Cannabis Industry Software Market | 2026-2036
Global Cannabis Industry Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cannabis Industry Software Market Foresight
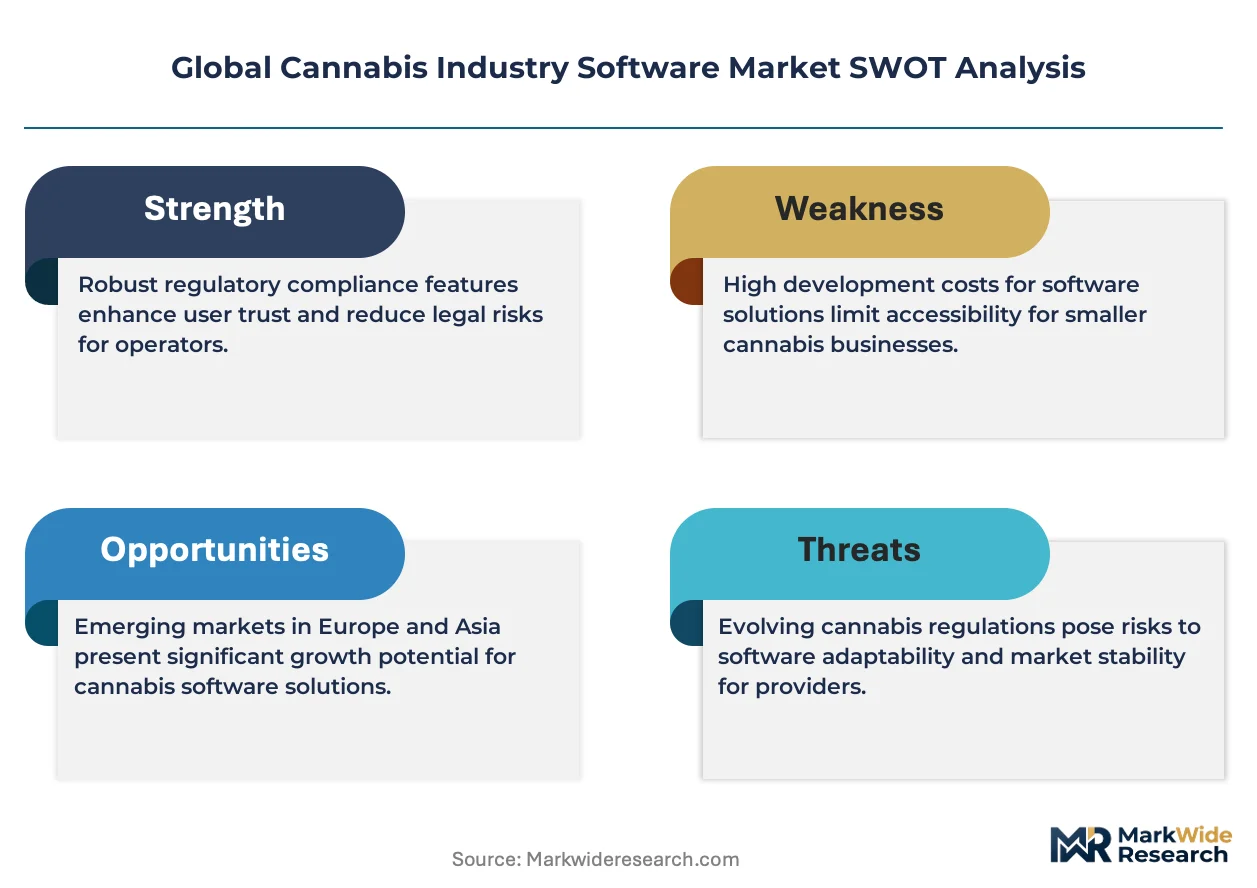
ISO/IEC 27001 certification for data security is collapsing as a baseline requirement for vendor selection in cannabis software procurement. LeafLink leverages its wholesale marketplace dominance to anchor B2B transaction flows across multi-state operators. Flowhub sustains retail point-of-sale leadership through deep integration with state traceability systems. Dutchie competes aggressively on user experience design for dispensary staff workflows.
Cannabis industry software comprises integrated digital platforms that manage regulatory compliance, inventory tracking, and commercial operations across licensed cannabis supply chains, typically incorporating real-time state reporting APIs and batch-level traceability protocols to satisfy jurisdictional audit requirements. Seed-to-sale tracking dominates solution spending as governments mandate granular product lineage documentation, while cloud-based deployment captures the fastest expansion due to lower capital barriers for small cultivators and dispensaries. Business intelligence applications increasingly concentrate margin pools by converting compliance-mandated data into operational analytics for yield optimization and demand forecasting.
FDA oversight of CBD product claims, alongside state-level cannabis regulators in California, Colorado, and Canada, creates fragmented compliance architectures that force software vendors to maintain jurisdiction-specific rule engines. The EU Green Deal's emerging sustainability disclosure requirements and REACH chemical tracking standards are beginning to influence European cannabis software specifications as markets liberalize. Stakeholders must monitor how federal rescheduling debates in the United States reshape banking access and corresponding payment processing module demand across platform providers.
Market Dynamics
Seed-to-sale traceability mandates are forcing software vendors to rebuild core architectures around real-time state reporting APIs, compressing development cycles and elevating compliance engineering to the center of product strategy.
Growth Catalysts
- State-level track-and-trace mandates:California, Colorado, and Canada require batch-level lineage documentation, compelling licensed operators to adopt integrated platforms. This regulatory scaffolding creates sticky, recurring revenue for compliant vendors.
- Cloud infrastructure maturation:Small cultivators and dispensaries bypass capital-intensive on-premise deployments. Subscription models lower barriers to entry across tier-two and tier-three license holders.
- Business intelligence module expansion:Compliance-mandated data reservoirs convert into yield optimization and demand forecasting tools. Operators monetize regulatory overhead into operational advantage.
Market Restraints
- Interstate banking prohibition:US federal restrictions on cannabis-related financial services force software platforms to build redundant payment processing modules. Cash-heavy operations limit enterprise-grade feature adoption.
- Jurisdiction-specific rule engine maintenance:Vendors must sustain parallel compliance codebases for fragmented state and provincial regimes. Engineering overhead scales linearly with geographic expansion.
- CBD regulatory ambiguity:FDA enforcement posture on hemp-derived product claims creates liability exposure. Software providers face indemnification demands from operators in uncertain compliance zones.
Strategic Opportunities
- German market liberalization:The BfArM licensing framework for adult-use cannabis creates demand for EU-GMP-compliant traceability platforms. First-mover vendors capture regulatory design influence.
- AI-powered predictive cultivation:Machine learning models applied to environmental sensor data enable real-time harvest timing optimization. This convergence differentiates platforms beyond baseline compliance functionality.
- EU Green Deal alignment:REACH chemical tracking standards and emerging sustainability disclosure requirements position carbon accounting modules as competitive differentiators in European procurement decisions.
Industry Challenges
- ISO/IEC 27001 certification timelines:Data security audits stretch 12-18 months, delaying vendor qualification for enterprise and government contracts. Certification gaps exclude smaller providers from tier-one operator RFPs.
- Legacy ERP integration complexity:State traceability systems demand real-time API connectivity with established agricultural and retail management platforms. Custom middleware development consumes disproportionate implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cannabis Industry Software Market |
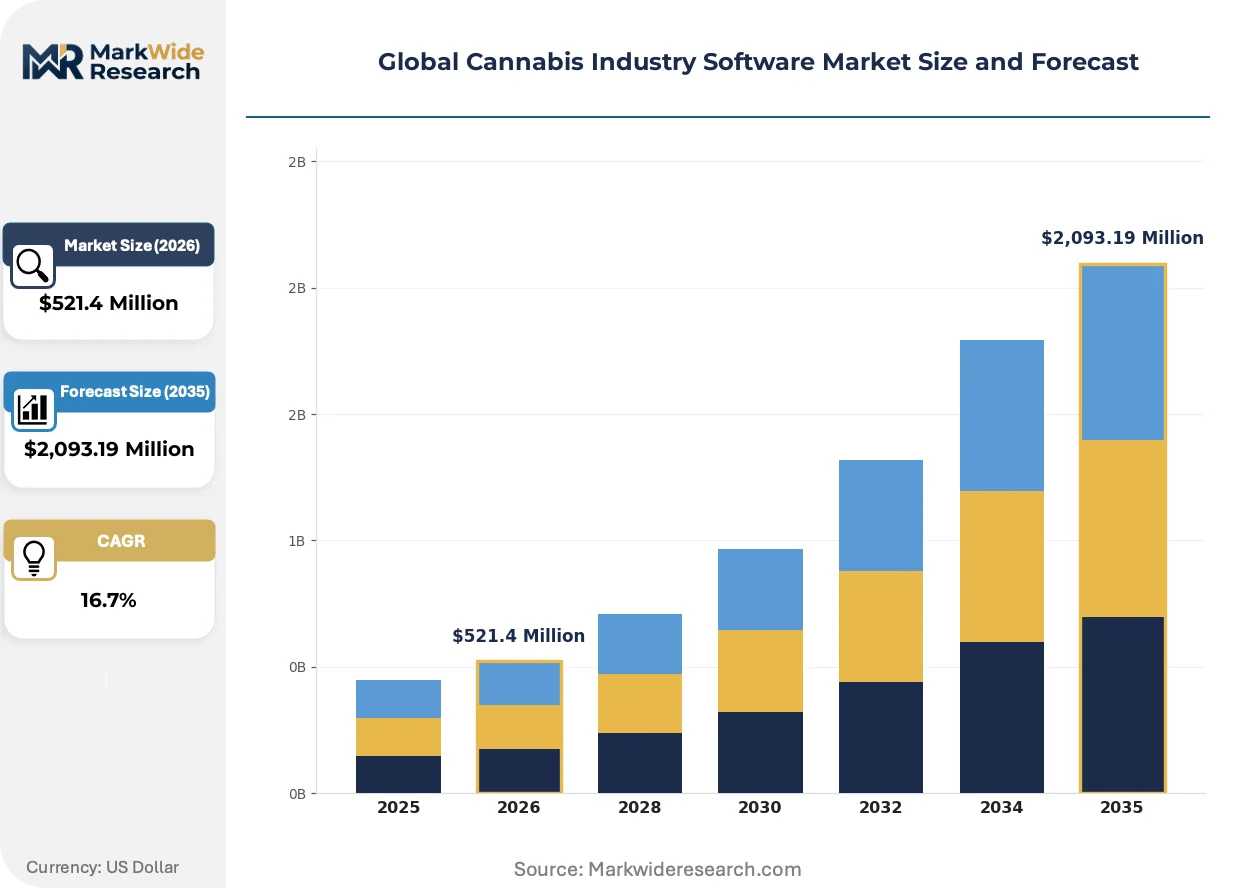
| Market Size in 2026 | $521.4 Million |
| Market Size in 2035 | $2,093.19 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Seed-to-Sale Tracking, Inventory Management, Regulatory Compliance, Customer Relationship Management, Business Intelligence, E-Commerce Platforms Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Application: Cultivation Management, Retail Operations, Compliance Reporting, Supply Chain Optimization, Patient Management End User: Dispensaries, Growers, Processors, Laboratories, Testing Facilities, Distribution Centers |
| Companies Covered | LeafLink, Flowhub, Treez, Dutchie, Jane Technologies, Canix, Distru, Flourish Software, MJ Freeway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cannabis Industry Software Market Shifts & Advancements
Blockchain-anchored provenance systems are disrupting established audit trails, while sustainability reporting modules and embedded financial services reshape how operators evaluate platform value beyond compliance checkboxes.
Blockchain-based certificate-of-origin systems are fragmenting traditional batch-documentation workflows. Multi-state operators in California and Colorado pilot distributed ledger architectures to preempt cross-jurisdictional audit disputes. This technology is fragmenting vendor market share by rewarding specialized compliance-native providers over generalized agricultural software incumbents.
REACH chemical tracking standards are extending into European cannabis cultivation licensing requirements. The ECHA substance database integration forces software platforms to embed hazard communication modules previously absent from North American product roadmaps. German and Dutch operators now prioritize platforms with pre-built EU regulatory rule engines over US-centric alternatives.
Embedded banking and payment orchestration services are displacing standalone financial service relationships. Dispensary operators consolidate vendor relationships by selecting platforms with native cashless payment compliance and automated tax remittance. This consolidation pattern concentrates most visibly in Canadian provincial retail monopolies and US multi-state operator networks seeking treasury standardization.
Global Cannabis Industry Software Market Segmentation
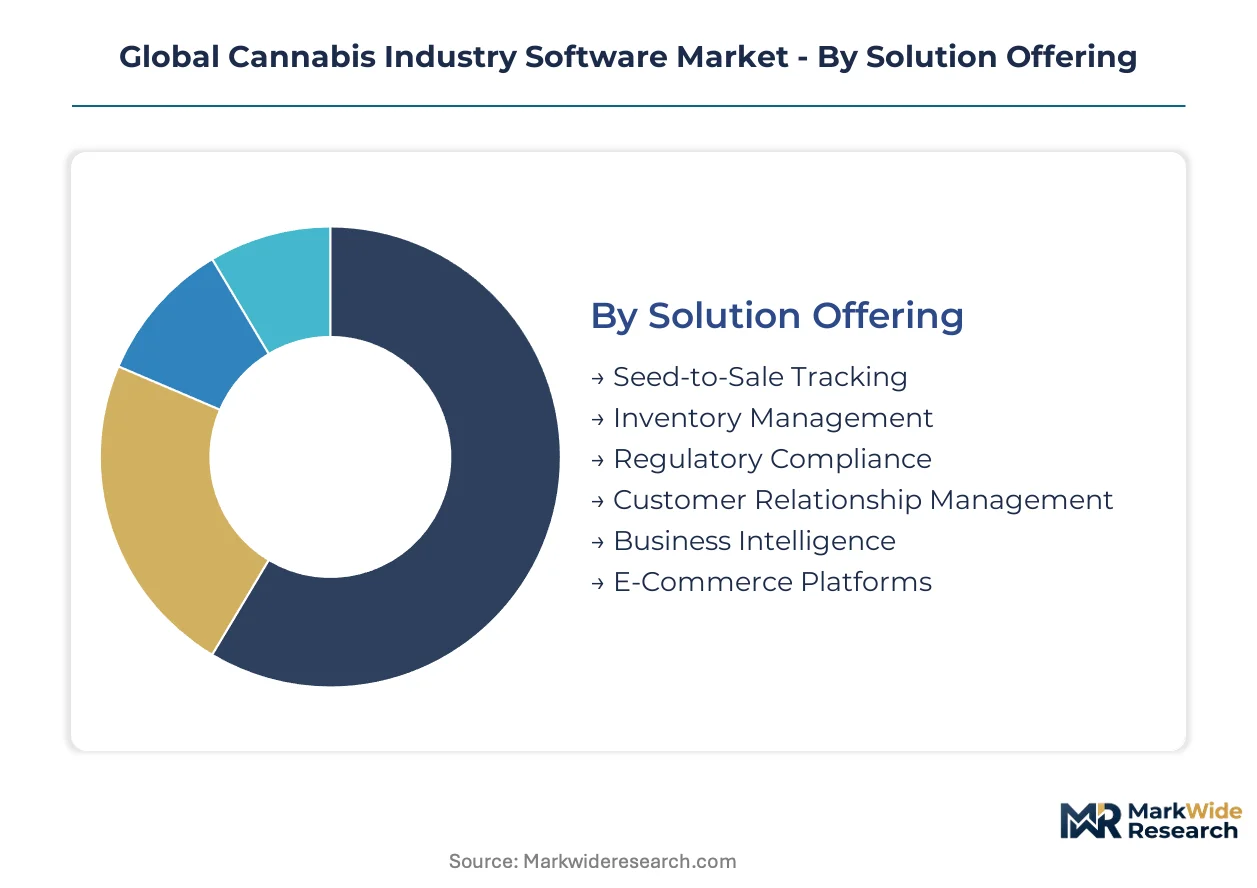
Cannabis software procurement patterns diverge sharply across operational archetypes. Cultivators prioritize traceability depth while retailers optimize for transaction velocity. This structural misalignment forces vendors to maintain parallel product architectures rather than unified platforms.
Solution Offering:
Seed-to-sale tracking platforms face acute substitution pressure from generalized agricultural ERP systems as compliance APIs standardize across jurisdictions.
- Seed-to-Sale Tracking:These systems enforce batch-level lineage documentation through direct state regulatory API integration. California and Colorado operators mandate real-time data transmission, creating vendor lock-in through compliance dependency.
- Inventory Management:Real-time stock reconciliation across cultivation, processing, and retail nodes prevents diversion violations. Canadian licensed producers prioritize these modules for excise tax precision.
- Regulatory Compliance:Jurisdiction-specific rule engines automate reporting to state traceability systems like Metrc and BioTrackTHC. Engineering overhead scales with each new market entry.
- Customer Relationship Management:Dispensary loyalty programs and purchase history tracking navigate strict privacy constraints. Canadian provincial retailers deploy these tools for consumer behavior analytics.
- Business Intelligence:Compliance-mandated data reservoirs convert into yield forecasting and demand planning assets. Multi-state operators monetize regulatory overhead into operational advantage.
- E-Commerce Platforms:Age-verification workflows and delivery logistics coordination address last-mile regulatory complexity. California delivery operators demand route optimization with real-time driver tracking.
Seed-to-Sale Tracking retains volume leadership; Business Intelligence holds the steepest expansion curve.
Deployment:
Capital constraints and IT staffing limitations concentrate demand in lower-touch delivery models among tier-two and tier-three license holders.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance burdens for small dispensaries. Subscription pricing aligns costs with license renewal cycles.
- On-Premise:Air-gapped installations satisfy security requirements for large cultivation facilities. Upfront capital expenditure deters adoption outside enterprise operators.
- Hybrid:Sensitive cultivation data remains local while retail transactions sync to cloud dashboards. Processor facilities in Colorado deploy this architecture for competitive isolation.
- SaaS:Standardized feature bundles accelerate implementation timelines for new market entrants. Vendor consolidation pressure favors platforms with native compliance modules.
- Private Cloud:Dedicated infrastructure instances address data residency requirements for Canadian provincial wholesalers. Premium pricing limits penetration to government-contracted operators.
Cloud-Based deployment captures the dominant share; Private Cloud is climbing the fastest as European markets impose stricter data sovereignty rules.
Application:
Regulatory enforcement intensity varies by supply chain position, concentrating software investment where audit scrutiny is most severe.
- Cultivation Management:Environmental sensor integration and harvest scheduling optimize biomass output per square foot. California outdoor growers deploy these systems for water use compliance.
- Retail Operations:Point-of-sale workflows embed age verification and purchase limit enforcement. Colorado dispensaries prioritize speed-to-transaction during peak hours.
- Compliance Reporting:Automated submission to state traceability systems eliminates manual data entry errors. Laboratory facilities in Canada depend on these modules for COA generation.
- Supply Chain Optimization:Route planning and excise tax stamping coordination streamline distribution logistics. Third-party distributors in California leverage these tools for multi-brand consolidation.
- Patient Management:Medical registry integration and dosage tracking serve regulated therapeutic markets. Canadian medical cannabis producers maintain these systems alongside recreational operations.
Cultivation Management retains volume leadership; Supply Chain Optimization is gaining share fastest as distribution complexity increases.
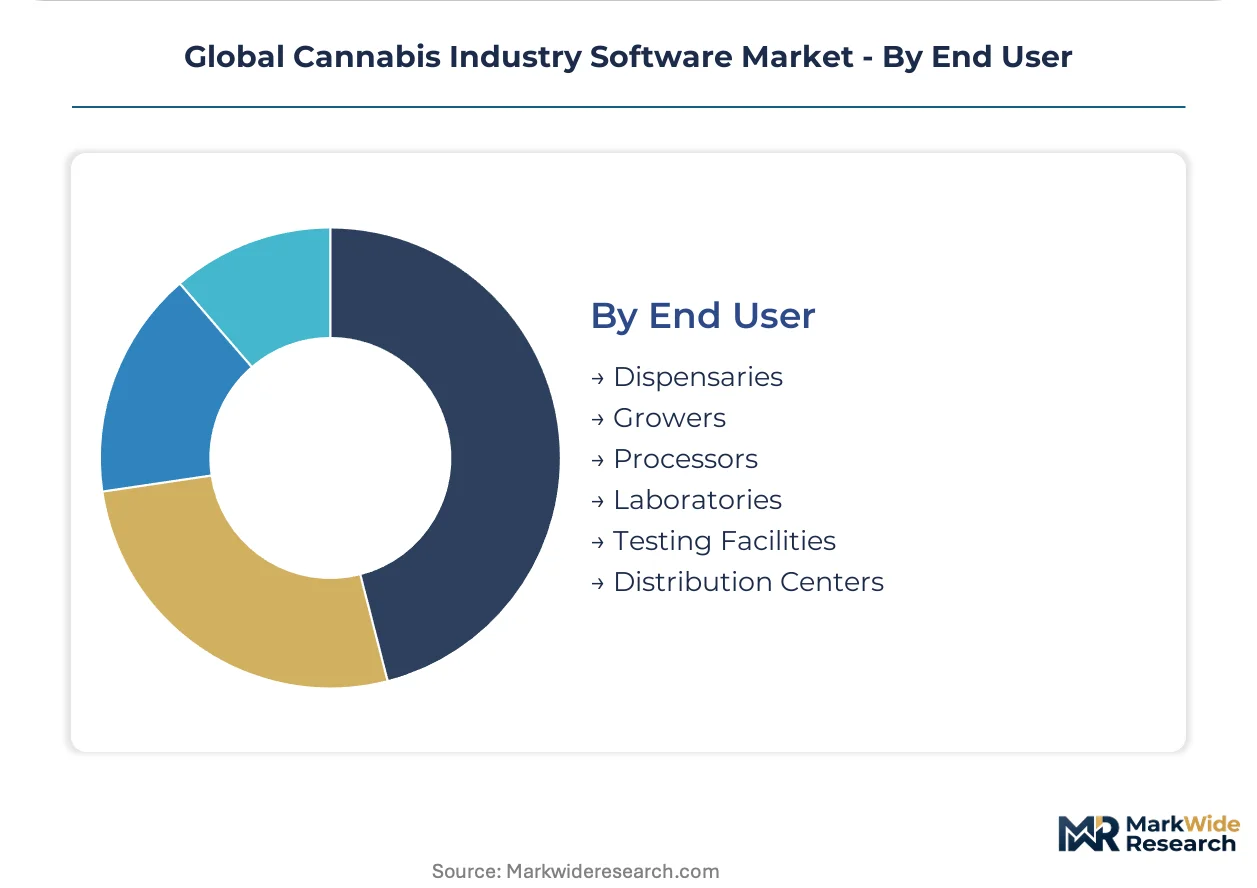
End User:
Operational scale and regulatory exposure determine willingness to pay for integrated platform capabilities versus point solutions.
- Dispensaries:High transaction volumes and strict compliance exposure drive investment in retail-centric platforms. California and Colorado operators demand seamless state traceability integration.
- Growers:Batch documentation requirements and environmental monitoring needs prioritize cultivation-specific tools. Large Canadian licensed producers build in-house compliance teams.
- Processors:Extraction workflow tracking and potency testing coordination require specialized modules. Concentrate manufacturers in Colorado face heightened product liability scrutiny.
- Laboratories:ISO/IEC 17025 quality management and COA generation workflows demand LIMS integration. Third-party testing facilities in California compete on turnaround speed.
- Testing Facilities:Contaminant screening protocols and regulatory submission automation protect operator licenses. State-mandated testing regimes in Colorado create steady demand.
- Distribution Centers:Excise tax stamping and multi-brand logistics coordination require warehouse management specialization. California distributors navigate complex interstate quarantine rules.
Dispensaries retain volume leadership; Distribution Centers hold the steepest expansion curve as wholesale markets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Pacific fiber optic cable networks and cloud region interconnects between Oregon, Singapore, and Frankfurt underpin software delivery architectures for cannabis compliance platforms.
United States
Multi-state operators in California and Colorado drive platform standardization through Metrc and BioTrackTHC API mandates. The FDA's shifting enforcement posture on hemp-derived CBD claims forces compliance module updates. Denver and Los Angeles host the densest vendor engineering clusters serving state-traceability integration.
Canada
Provincial retail monopolies in Ontario and Quebec consolidate procurement power for integrated seed-to-sale systems. Health Canada excise tax stamping requirements shape software specifications for licensed producers. Toronto's technology corridor anchors domestic platform development alongside Vancouver's cannabis startup ecosystem.
Germany
The BfArM adult-use licensing framework creates demand for EU-GMP-compliant traceability architectures. REACH chemical tracking standards from ECHA influence cultivation software specifications. Berlin and Cologne emerge as regulatory technology development hubs serving emerging European markets.
Australia
TGA medical cannabis prescribing protocols drive patient management module requirements. State-level licensing variations between New South Wales and Victoria fragment compliance rule engines. Sydney's health technology sector adapts North American platforms for Therapeutic Goods Administration reporting.
Netherlands
The Wietexperiment pilot program for regulated adult-use cultivation tests traceability system scalability. Dutch greenhouse automation heritage influences environmental sensor integration priorities. Eindhoven's ag-tech cluster collaborates with software vendors on precision agriculture modules.
Global Cannabis Industry Software Market Competitive Landscape
Listed leaders compete with private specialists across compliance engineering depth, creating a tiered structure where scale advantages clash with regulatory agility. The vendor base organizes around three archetypes: wholesale marketplace operators anchoring B2B transaction flows, retail-centric platforms optimizing dispensary workflows, and cultivation-native systems embedding environmental sensor networks. Dominant competitive moves include geographic expansion through jurisdiction-specific rule engine development and strategic partnerships with state traceability system providers.
Within the retail-centric tier, Flowhub and Dutchie exemplify divergent positioning strategies—one anchoring deep state-system integration, the other competing on staff-facing user experience design. LeafLink occupies a distinct wholesale marketplace position, leveraging transaction volume concentration across multi-state operator networks. These three companies represent the primary competitive vectors shaping procurement decisions among tier-one licensed operators.
| Leading Market Players |
|---|
| LeafLink |
| Flowhub |
| Treez |
| Dutchie |
| Jane Technologies |
| Canix |
| Distru |
| Flourish Software |
| MJ Freeway |
| Others |
Supply & Pricing Matrix
Platform scale economies in multi-tenant cloud architectures compress marginal delivery costs below $50 per seat monthly, concentrating pricing power among vendors serving California and Colorado's densest operator clusters while marginalizing smaller rule-engine specialists.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise multi-state operators, mid-tier regional chains, and single-license dispensaries. SaaS subscription models dominate, with price differentiation resting on state API integration depth and ISO/IEC 27001 certification status. Cost compression in the mid-market intensifies as generalized agricultural ERP vendors add compliance modules. Single-license dispensaries exhibit highest price sensitivity; multi-state operators prioritize integration reliability over unit cost.
Supply Chain Analysis
Inventory lead times for specialized compliance hardware—RFID scanners, environmental sensors, label printers—stretch 8-14 weeks from Taiwan and China manufacturing hubs. Software development draws from engineering talent pools in Denver, Los Angeles, and Toronto. Single-source vulnerability concentrates in state traceability API middleware providers. Distribution runs through direct vendor sales teams and value-added resellers serving provincial Canadian retail monopolies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-powered cultivation analytics and shifting FDA enforcement posture on hemp-derived claims are accelerating platform consolidation beyond baseline compliance functionality.
For Market Incumbents: Shield recurring revenue streams by deepening Metrc and BioTrackTHC API integration moats. Acquire specialized environmental sensor analytics firms to preempt AI-native entrants. Prioritize EU-GMP certification investment for German market entry before regulatory design influence solidifies. For New Entrants and Emerging Players: Differentiate on carbon accounting modules aligned with EU Green Deal disclosure requirements. Target Australian and Dutch operators where incumbent penetration remains shallow. Pursue white-label partnerships with greenhouse automation hardware vendors in Eindhoven's ag-tech cluster. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with embedded payment orchestration and automated tax remittance modules. Long-term viability favors platforms with jurisdiction-agnostic rule engine architectures. Monitor German BfArM licensing velocity as the primary inflection signal for European expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep state traceability API connectivity locks in multi-state operator switching costs. |
| Geographic Expansion | EU-GMP rule engine development captures BfArM licensing framework design influence. |
| Acquisition of Specialist Firm | Environmental sensor analytics targets AI-powered yield optimization differentiation. |
| Strategic Partnership | Greenhouse automation vendor alliances embed software into Dutch cultivation infrastructure. |
| Product Launch | Carbon accounting modules address REACH chemical tracking and CSRD sustainability disclosure. |
Research Methodology
Desk research of SEC filings, state regulatory API documentation, and Health Canada excise tax guidelines preceded structured interviews with CTOs at multi-state operators, compliance officers at Canadian licensed producers, and integration specialists at state traceability system vendors. Bottom-up sizing of seed-to-sale platform deployments triangulated against top-down cloud infrastructure spending estimates across California, Colorado, and Canadian provincial markets.
Variance-decomposition across deployment models, license holder tiers, and regional regulatory frameworks shaped the analytical architecture. CAGRs derived from cohort-based adoption curves and jurisdiction-specific mandate implementation timelines. Modeled inputs included state track-and-trace API penetration rates and cloud migration velocity among tier-two cultivators.
Material uncertainties—federal rescheduling debates, FDA CBD enforcement shifts, German licensing velocity—sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory mandate expansion and platform consolidation dynamics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
Medical Marijuana Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
Global Cannabis Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market