
 Europe CBD Patch Market | 2026-2036
Europe CBD Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Europe CBD Patch Market Foresight
Market Context
Pharmacological formulation expertise is reorganizing competitive dynamics across the Europe CBD Patch landscape as laboratories race to stabilize cannabinoid bioavailability in adhesive matrices. Cannacares leverages proprietary encapsulation methods to sustain shelf-life consistency across varying European climates. Always Pure Organics anchors its position through UK-based manufacturing that navigates post-Brexit regulatory divergence from EU frameworks. CS MEDICA specializes in Scandinavian pharmacy distribution, dominating shelf access in Denmark and Sweden.
Technical Definition and Segment Structure
Europe CBD Patch denotes a transdermal or topical delivery system incorporating cannabidiol extract within a pressure-sensitive adhesive layer, typically releasing active compounds over 8-24 hours through controlled skin permeation for localized or systemic therapeutic effect. The transdermal product category leads volume deployment due to superior bioavailability compared to oral alternatives, while pain relief applications capture the deepest margin pools as reimbursement discussions progress in several EU member states. Online retail channels represent the fastest-growing distribution vector, though pharmacies retain structural control over prescription-adjacent formulations and clinician trust.
Regulatory Framework and Outlook
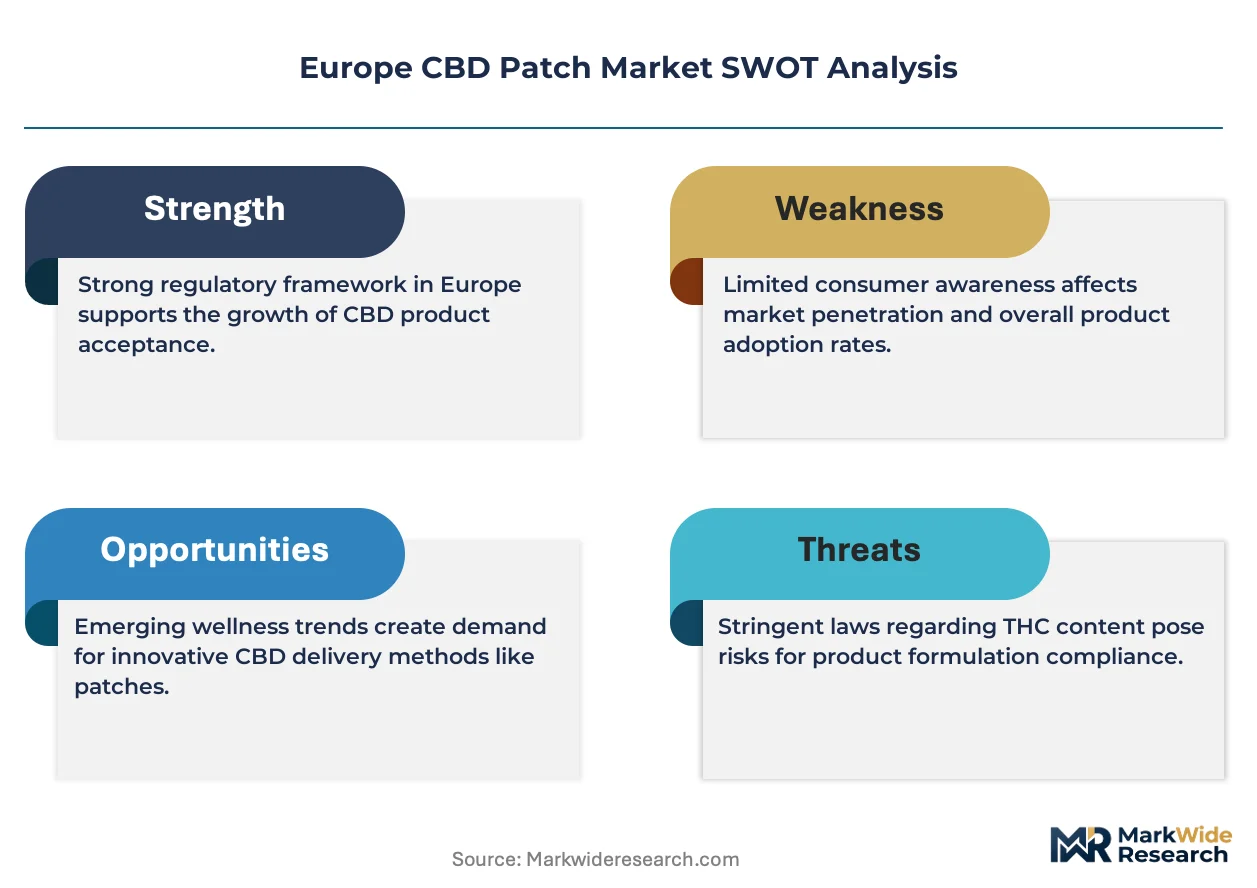
EMA guidance on cannabis-derived medicines, EFSA novel food assessments, and national pharmaceutical regulators in Germany and France collectively determine market access timelines and label claims for CBD patches. The EU Cosmetics Regulation restricts certain dermal marketing language, forcing manufacturers to position products between wellness and medical device classifications. Stakeholders must monitor pending THC threshold harmonization and member-state-specific extraction origin requirements that will determine which suppliers qualify for cross-border distribution.
Market Dynamics
EFSA novel food assessments and member-state pharmaceutical classifications are compressing go-to-market timelines for CBD patch developers, forcing simultaneous compliance with cosmetic, medical device, and borderline medicine frameworks across multiple national regulators.
Growth Catalysts
- Transdermal bioavailability advances:Pressure-sensitive adhesive matrices incorporating permeation enhancers now deliver sustained cannabinoid release profiles matching oral pharmacokinetics. Pain management clinics in Germany are integrating these patches into multimodal therapy protocols.
- EMA guidance harmonization:The European Medicines Agency's cannabis-derived medicines pathway provides clarity for prescription-adjacent positioning, enabling pharmacy channel expansion in France and Italy.
- Chronic pain patient demand:Arthritis and neuropathy populations in the United Kingdom are shifting from oral NSAIDs toward localized CBD delivery to avoid gastrointestinal side effects.
Market Restraints
- THC threshold fragmentation:Member states maintain divergent maximum THC limits for hemp-derived extracts, forcing SKU proliferation and inventory complexity for cross-border distributors.
- Extraction origin requirements:France and Italy mandate EU-sourced biomass, constraining supply flexibility when Scandinavian or North American hemp harvests undercut continental pricing.
- Novel food authorization delays:EFSA's pending CBD safety assessments freeze ingestible positioning, pushing manufacturers toward costlier medical device certification routes.
Strategic Opportunities
- Spanish pharmacy channel:Underdeveloped CBD patch penetration in community pharmacies creates first-mover shelf access before regulatory clarity attracts multinational competitors.
- Veterinary applications:Pet owners in the Netherlands and Belgium are seeking transdermal alternatives to oral CBD for companion animal anxiety and joint health.
- Wellness center integration:Spa and physiotherapy chains across Austria and Switzerland are building private-label patch programs to differentiate service offerings.
Industry Challenges
- Formulation chemist scarcity:Cannabinoid stability expertise in adhesive polymer science commands premium compensation, constraining R&D velocity for mid-tier manufacturers.
- Clinical evidence generation:Randomized controlled trials for specific pain indications require multi-year investment before national reimbursement discussions can commence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe CBD Patch Market |
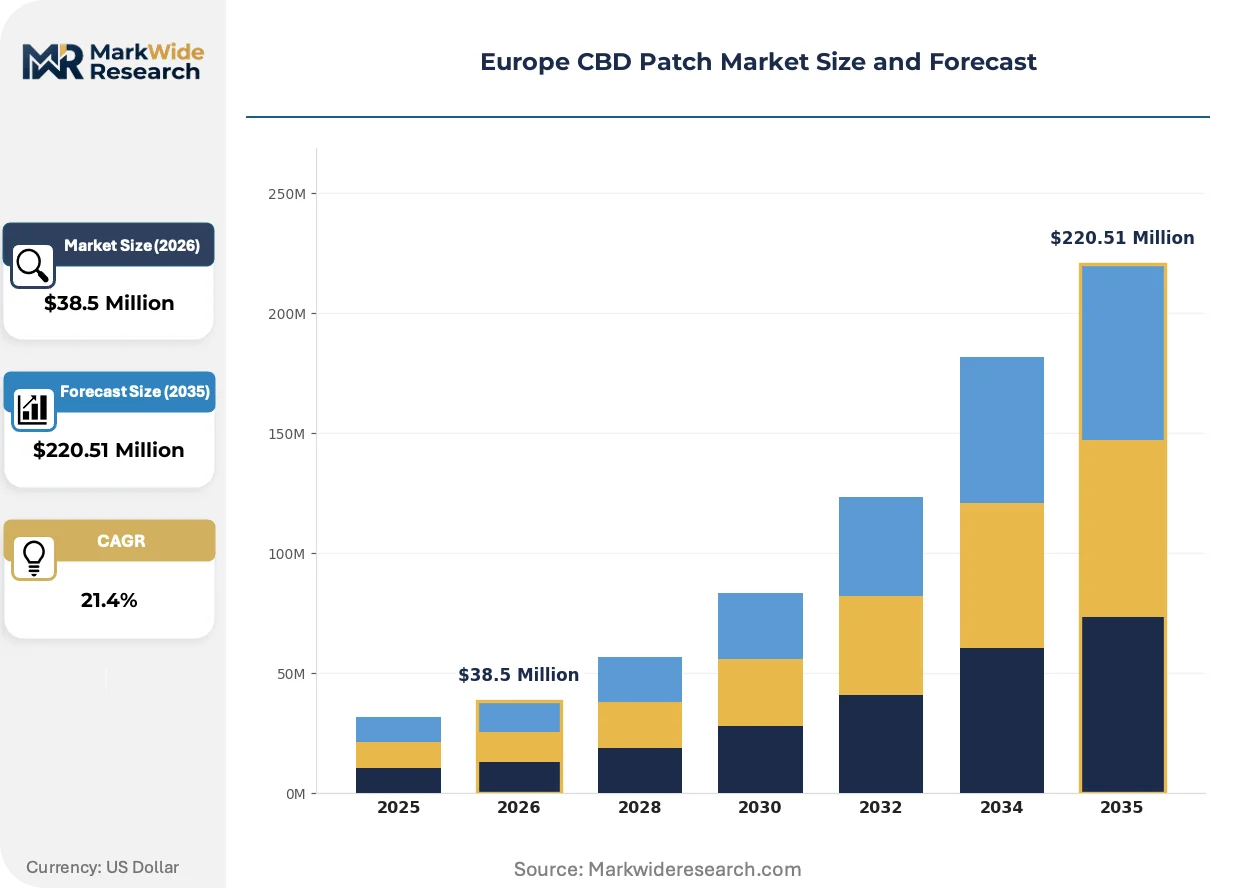
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $220.51 Million |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transdermal, Topical, Edible, Beverage Application: Pain Relief, Anxiety Management, Sleep Aid, Skin Health Distribution Channel: Online Retail, Pharmacies, Health Stores, Specialty Shops Customer Type: Individuals, Healthcare Professionals, Wellness Centers, Retailers |
| Companies Covered | Cannacares, Always Pure Organics, CBD One Ltd, CS MEDICA, Pure Ratio Wellness, Mary's Medicinals, CBD Living, Medterra, HempFusion, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe CBD Patch Market Shifts & Advancements
Microencapsulation and hydrogel matrix technologies are fragmenting competitive positioning, enabling smaller laboratories to challenge established pharmaceutical adhesive suppliers through differentiated release kinetics and skin tolerance profiles.
Hydrogel-based CBD reservoirs with iontophoretic compatibility are fragmenting the traditional transdermal patch category. Dutch and German dermatology clinics are piloting these systems for patients with adhesive sensitivities. The technology is fragmenting procurement patterns as hospitals evaluate capital equipment against disposable patch economics.
EFSA's ongoing novel food safety assessments are forcing manufacturers to bifurcate product lines between cosmetic wellness positioning and medical device pathways. German and French national regulators are interpreting the pending guidance differently, creating divergent labeling requirements. Pain relief applications in these markets face the steepest compliance cost escalation as clinical evidence thresholds rise.
Direct-to-patient subscription models are displacing traditional pharmacy stocking for maintenance-dose CBD patches. Chronic pain patients in the United Kingdom and Netherlands are prioritizing convenience and dosage consistency over immediate retail availability. This channel rotation is most pronounced among fibromyalgia and arthritis demographics seeking predictable monthly supply chains.
Europe CBD Patch Market Segmentation
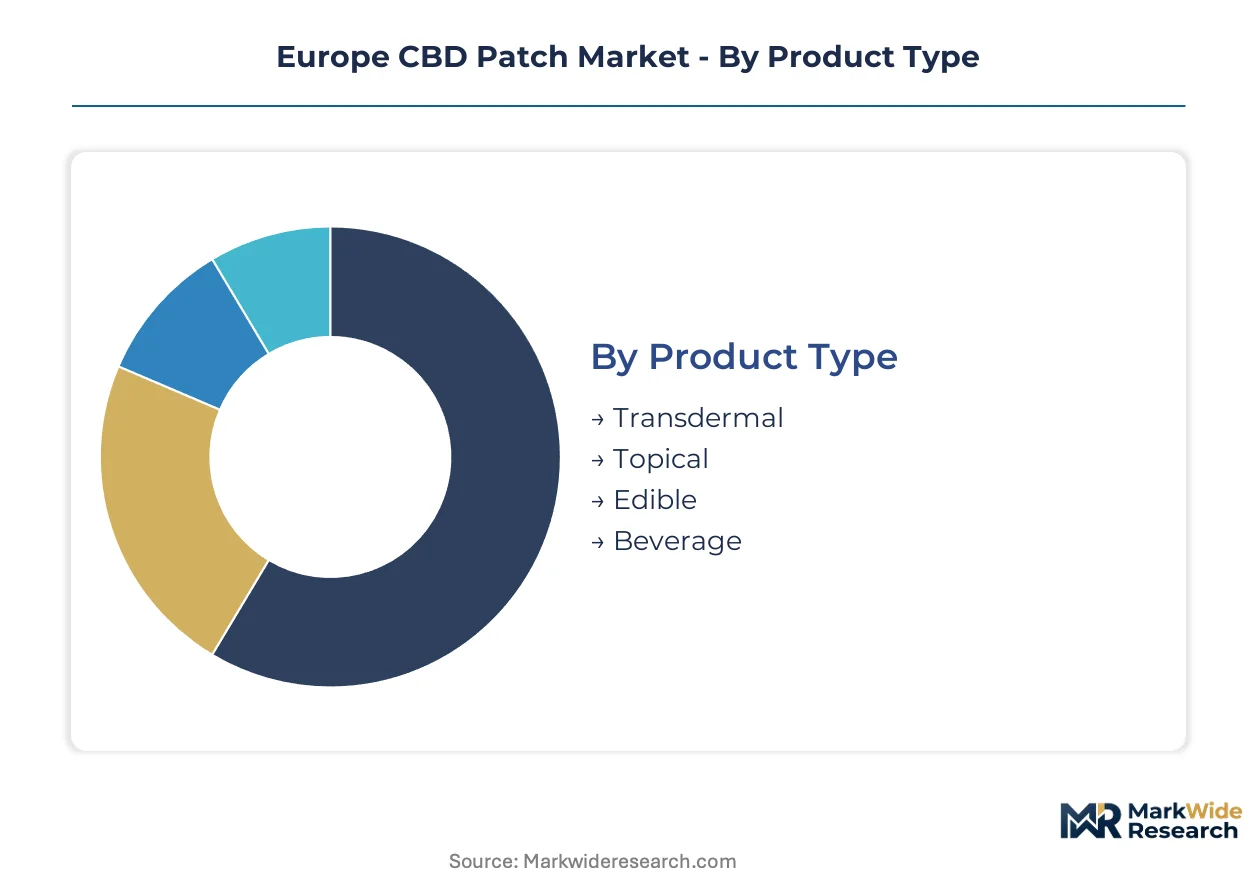
Segmentation in the Europe CBD Patch market reveals where formulation investments concentrate and which patient populations drive reimbursement negotiations. Distinct product architectures face diverging regulatory pathways across EMA, EFSA, and national pharmaceutical frameworks.
Product Type:
Transdermal patches face intensifying substitution pressure from oral CBD oils and vaporization devices as patients seek faster onset times for acute symptom relief.
- Transdermal:Multi-layer adhesive matrices with permeation enhancers enable systemic cannabinoid absorption over 8-24 hours. German pain clinics are incorporating these into opioid-sparing protocols for chronic neuropathy patients. EMA's cannabis-derived medicines guidance is accelerating pharmacy channel placement in France and Italy.
- Topical:Localized CBD delivery through creams and gels targets dermatological and musculoskeletal applications without systemic absorption. UK wellness centers are bundling these with physiotherapy services to differentiate premium service tiers. The EU Cosmetics Regulation restricts therapeutic claims, forcing positioning around general skin wellness.
- Edible:Gummies and capsules face EFSA novel food authorization delays that freeze market expansion across most EU member states.
- Beverage:CBD-infused drinks confront the strictest THC threshold enforcement in Germany and France, limiting cross-border formulation standardization.
Transdermal patches anchor the volume base while topical formats gain share at the steepest rate as wellness centers expand service bundling across Austria and Switzerland.
Application:
Pain relief applications command the deepest margin pools as clinicians seek alternatives to NSAID gastrointestinal risks and opioid dependency pathways.
- Pain Relief:Arthritis, fibromyalgia, and neuropathy indications dominate clinical trial investment. UK rheumatology practices are piloting patch-based CBD as adjunct therapy for osteoarthritis patients. Reimbursement discussions in Germany hinge on randomized controlled trial completion for specific pain scores.
- Anxiety Management:Sustained-release patches target generalized anxiety and PTSD populations seeking predictable dosing without sedation peaks. Dutch mental health clinics are evaluating transdermal delivery against oral CBD for panic disorder maintenance therapy.
- Sleep Aid:Melatonin-CBD combination patches are penetrating pharmacy shelves in Spain and Portugal where regulatory ambiguity around cannabinoid positioning remains highest.
- Skin Health:Eczema and psoriasis applications leverage anti-inflammatory claims within cosmetic regulatory boundaries, avoiding medical device certification costs.
Pain relief anchors the volume base while anxiety management climbs the fastest as psychiatric practices in the Netherlands and Belgium expand cannabinoid prescribing authority.
Distribution Channel:
Pharmacy channel control is fragmenting as direct-to-patient subscription models capture chronic users seeking dosage consistency.
- Online Retail:Subscription platforms are displacing traditional stocking for maintenance-dose patients. UK fibromyalgia demographics prioritize predictable monthly supply chains over immediate retail availability. Regulatory divergence post-Brexit creates separate UK and EU warehousing requirements.
- Pharmacies:Community and hospital pharmacies retain structural control over prescription-adjacent formulations and clinician trust. CS MEDICA dominates shelf access in Denmark and Sweden through Scandinavian distribution specialization.
- Health Stores:Natural product retailers in Germany and Austria face margin compression from online price transparency.
- Specialty Shops:Cannabis dispensaries and wellness boutiques in the Netherlands and Spain offer education-intensive purchasing environments for novice users.
Pharmacies anchor the volume base while online retail expands most quickly as chronic pain patients prioritize convenience over immediate availability.
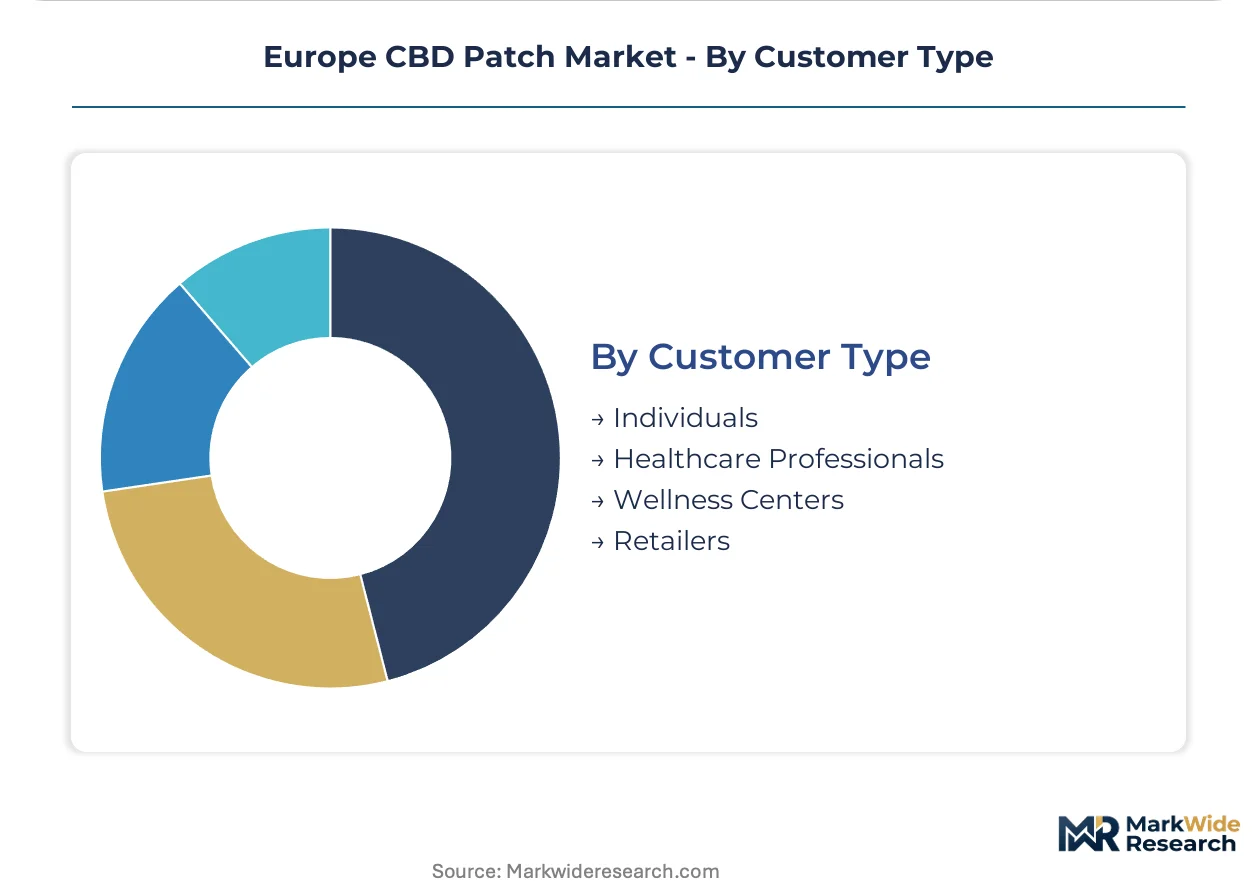
Customer Type:
Healthcare professional adoption determines reimbursement trajectory and clinical evidence generation priorities for patch manufacturers.
- Individuals:Direct consumer purchases concentrate in online channels and wellness retail. UK arthritis patients are shifting from oral NSAIDs toward localized CBD delivery to avoid gastrointestinal side effects. Price sensitivity varies sharply across member state income levels.
- Healthcare Professionals:Physicians, pharmacists, and physiotherapists drive institutional adoption and formulary placement. German pain management clinics are integrating patches into multimodal therapy protocols. Clinical trial investment targets this segment's evidence requirements.
- Wellness Centers:Spa and physiotherapy chains across Austria and Switzerland are building private-label patch programs. These facilities seek product differentiation through exclusive formulation partnerships.
- Retailers:Pharmacy chains and health store networks negotiate volume discounts and exclusive distribution agreements. Procurement concentration in France and Germany creates supplier dependency risks.
Individual consumers anchor the volume base while healthcare professionals gain influence fastest as reimbursement discussions progress in Germany and France.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BfArM, Germany's federal pharmaceutical regulator, anchors the dominant geography through its early mover framework for cannabis-derived medicines. EMA guidance harmonization and divergent national THC thresholds are fragmenting go-to-market pathways across member states.
Germany
Chronic pain clinics in Berlin and Munich are integrating CBD patches into opioid-sparing protocols for neuropathy patients. BfArM's cannabis agency provides prescription-adjacent pathways that accelerate pharmacy channel placement. The North Rhine-Westphalia industrial corridor hosts adhesive polymer laboratories supplying permeation-enhanced matrices to domestic patch manufacturers.
United Kingdom
Arthritis and fibromyalgia populations are shifting from oral NSAIDs toward transdermal CBD delivery to avoid gastrointestinal complications. The Medicines and Healthcare products Regulatory Agency maintains stricter novel food interpretations than EFSA, forcing separate UK-EU warehousing post-Brexit. London wellness centers are building private-label patch programs for physiotherapy service differentiation.
France
ANSM, the national pharmaceutical regulator, enforces EU-sourced biomass mandates that constrain supply flexibility when Scandinavian hemp undercuts continental pricing. Lyon and Paris pharmacy chains are piloting reimbursement discussions for pain relief indications pending clinical evidence completion. The Île-de-France region concentrates dermatology clinics evaluating hydrogel reservoir compatibility.
Netherlands
Dutch mental health clinics in Amsterdam and Rotterdam are evaluating transdermal CBD against oral delivery for panic disorder maintenance therapy. The Office for Medicinal Cannabis maintains distinct THC thresholds from neighboring Belgium, complicating cross-border distribution. Eindhoven-based polymer scientists are developing iontophoretic-compatible hydrogel matrices for adhesive-sensitive patients.
Spain
Underdeveloped CBD patch penetration in Barcelona and Madrid community pharmacies creates first-mover shelf access before regulatory clarity attracts multinational competitors. Melatonin-CBD combination patches are penetrating pharmacy shelves where cannabinoid positioning ambiguity remains highest. The Valencia region hosts spa chains building exclusive formulation partnerships for wellness service differentiation.
Europe CBD Patch Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with formulation chemist scarcity constraining R&D velocity for mid-cap manufacturers. The vendor base separates between pharmaceutical adhesive suppliers with polymer science heritage and cannabis-native entrants leveraging cultivation relationships. Three archetypes dominate: laboratory-driven encapsulation specialists, pharmacy distribution anchor tenants, and wellness channel private-label builders. Competitive moves concentrate on M&A for adhesive technology access and strategic partnerships with pain management clinic networks.
Among UK-based fabricators, Always Pure Organics and CBD One Ltd occupy positions navigating post-Brexit regulatory divergence from EU frameworks. CS MEDICA exemplifies the pharmacy distribution archetype through Scandinavian specialization. Cannacares anchors the encapsulation-technology tier with proprietary shelf-life stabilization methods.
| Leading Market Players |
|---|
| Cannacares |
| Always Pure Organics |
| CBD One Ltd |
| CS MEDICA |
| Pure Ratio Wellness |
| Mary's Medicinals |
| CBD Living |
| Medterra |
| HempFusion |
| Others |
Supply & Pricing Matrix
EMA cannabis-derived medicines guidance gates both supply qualification and price differentiation simultaneously, as manufacturers must secure pharmacy channel access through medical device certification or retreat to cosmetic wellness positioning with compressed margins. This regulatory bifurcation concentrates pricing power among laboratories with polymer science heritage capable of navigating dual compliance pathways.
Pricing Analysis
Long-term offtake agreements between patch manufacturers and Scandinavian hemp biomass suppliers dominate contract structures, insulating premium-tier producers from spot-market volatility in CBD isolate pricing. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by EMA pathway completion, permeation-enhancer sophistication, and clinical evidence depth. Cost compression in economy-tier wellness positioning is intensifying because online retail price transparency erodes brand premiums. Chronic pain patients in pharmacy channels demonstrate lowest price sensitivity, while wellness-center individual consumers drive volume through discount-seeking behavior.
Supply Chain Analysis
France and Italy anchor EU-sourced hemp biomass cultivation for compliant extraction, while Scandinavian suppliers in Denmark and Sweden provide secondary sourcing when harvest yields fluctuate. Adhesive polymer matrices and permeation enhancers draw from German and Dutch specialty chemical producers, with hydrogel reservoir components resting on Eindhoven-based polymer science clusters. Single-source vulnerability concentrates in EU-certified hemp biomass, where extraction origin mandates restrict substitution flexibility. Distribution runs through pharmacy wholesale networks for prescription-adjacent formulations, while direct-to-patient subscription platforms bypass traditional retail stocking for maintenance-dose patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe CBD Patch Market expansion sits in early-cycle penetration as chronic pain clinics in Germany and the United Kingdom accelerate opioid-sparing protocol adoption. Transdermal bioavailability advances and EMA guidance harmonization provide structural tailwinds for institutional channel placement.
For Market Incumbents: Compound formulation expertise advantages by acquiring adhesive polymer laboratories in the North Rhine-Westphalia corridor, securing captive supply of permeation-enhanced matrices before raw material scarcity intensifies. Deepen clinical evidence generation for specific pain indications to preempt reimbursement discussions in France and Germany, defending against oral CBD oil substitution pressure from faster-onset competitors. For New Entrants and Emerging Players: Anchor in Spanish community pharmacy shelf access before regulatory clarity attracts multinational competitors, exploiting underdeveloped CBD patch penetration in Barcelona and Madrid. Target veterinary applications in the Netherlands and Belgium through transdermal formats for companion animal anxiety, leveraging lower regulatory barriers and premium pricing tolerance among pet owners. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrogel reservoir and iontophoretic-compatible formulation segments as dermatology clinic pilot programs expand. Laboratories with proprietary microencapsulation methods and Scandinavian pharmacy distribution contracts represent priority acquisition archetypes. Monitor EFSA novel food authorization timelines as signal for competitive repositioning between cosmetic wellness and medical device pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Laboratory Acquisition | Secures captive adhesive matrix supply and permeation-enhancer R&D velocity for German manufacturers. |
| Clinical Trial Advancement | Generates randomized controlled evidence for German BfArM reimbursement discussions in neuropathy indications. |
| Pharmacy Channel Partnership | Locks shelf access in Denmark and Sweden through CS MEDICA-type distribution specialization. |
| Private-Label Program Launch | Captures wellness center demand in Austria and Switzerland through exclusive formulation partnerships. |
| Regulatory Pathway Diversification | Hedges EFSA novel food delays by pursuing parallel medical device certification in France and Italy. |
Research Methodology
Desk research of EMA guidance documents, BfArM cannabis agency filings, and EFSA novel food assessment records preceded structured interviews with pain management clinic directors, pharmacy procurement managers, adhesive polymer R&D leads, and regulatory affairs specialists at CBD patch manufacturers. Secondary validation drew from national pharmaceutical regulator databases, EU Cosmetics Regulation enforcement notices, and customs trade data for hemp-derived extract flows. Bottom-up patient population sizing and top-down channel revenue estimates were triangulated against manufacturer production disclosures.
Variance decomposition across product type, application indication, distribution channel, and customer archetype segments structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EMA guidance implementation timelines, member-state THC threshold harmonization probability, and permeation-enhancer technology diffusion curves through German and Dutch dermatology clinics.
Decision-makers should treat outputs as directional under assumptions of continued EMA guidance stability and no radical THC threshold convergence; material deviation in novel food authorization timelines or reimbursement policy would warrant model refresh. Recalibration cycles align with material shifts in regulatory guidance, clinical evidence publication, and pharmacy channel access negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabis Cultivation Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
Europe Medical Cannabis Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
North America Legal Cannabis Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
Hemp Derivatives Market
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
CBD Infused Cosmetics Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
North America Legal Marijuana Market