
 CBD Edibles Market | 2026-2036
CBD Edibles Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Edibles Market Analysis
Current Good Manufacturing Practice certification is redrawing competitive boundaries for CBD edibles producers. Kiva Confections leverages precision dosing technology to sustain premium positioning across state-licensed dispensaries. Wyld anchors its market presence through fruit-forward formulations that dominate the Pacific Northwest retail channel.
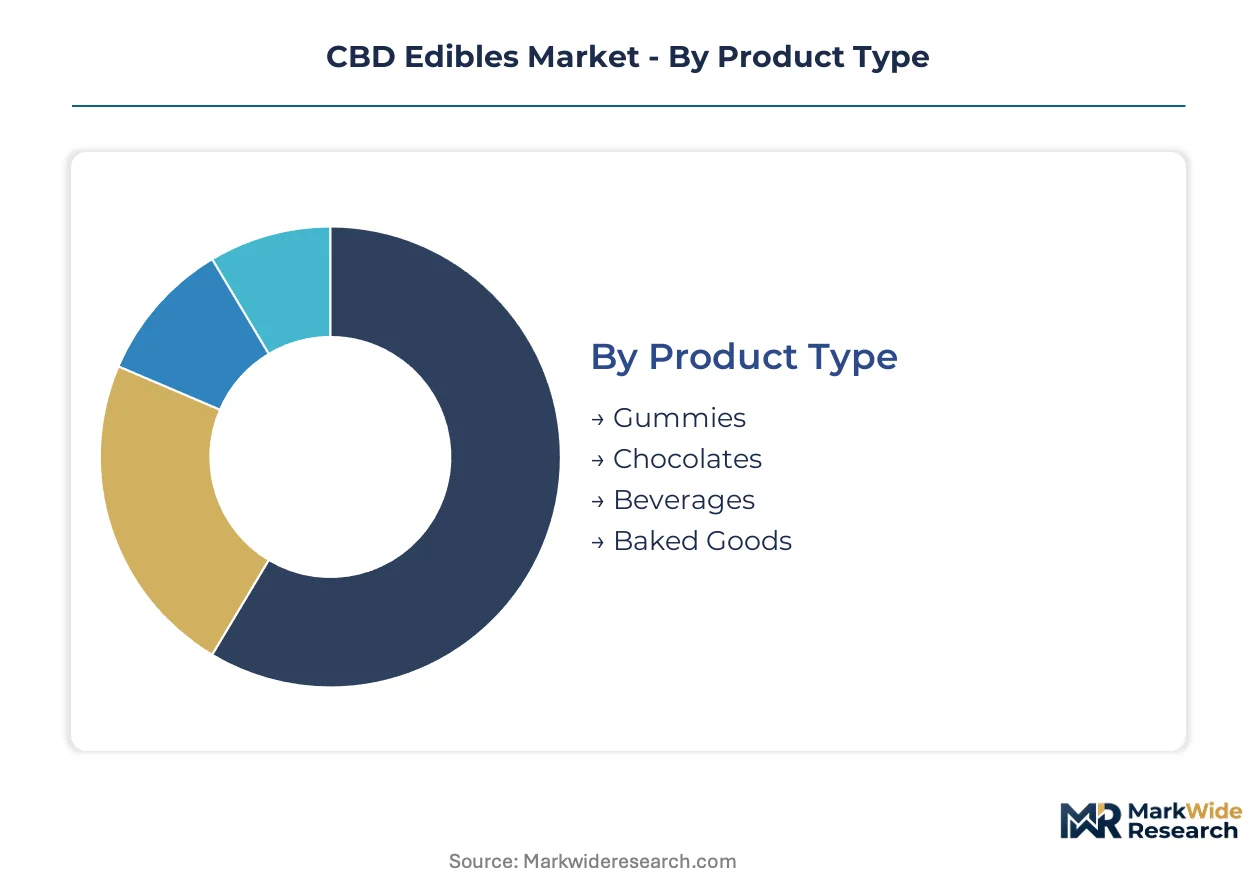
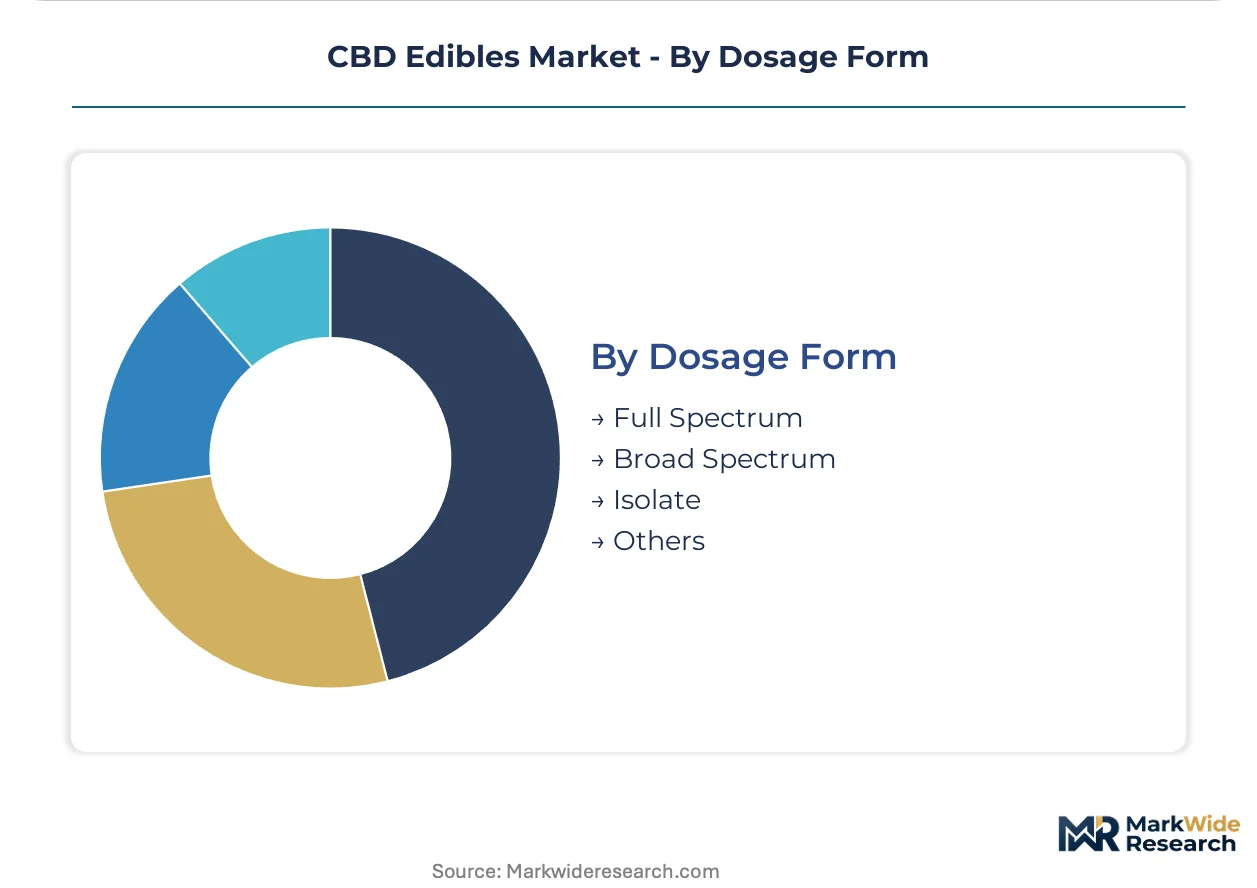
CBD edibles comprise food and beverage products infused with cannabidiol extract, typically containing measured doses per serving unit. Manufacturers employ lipid-based emulsification or nanoencapsulation to enhance bioavailability and ensure homogenous cannabinoid distribution. Gummies command the largest product type share due to shelf stability and precise portion control, while beverages represent the fastest-expanding category as liquid formats attract wellness-oriented consumers. Full spectrum dosage forms capture premium margin pools, whereas isolate-based products compete on standardization and THC-free claims.
FDA oversight of CBD as a food ingredient, state-level cannabis licensing regimes, and USDA hemp cultivation rules collectively shape product legality and interstate commerce feasibility. The 2018 Farm Bill established hemp-derived CBD's federal legality, yet state-by-state variance in edible regulations forces multi-jurisdictional compliance strategies. Stakeholders must monitor pending FDA rulemaking on CBD food additives while building flexible manufacturing footprints that adapt to evolving state enforcement priorities.
Market Dynamics
FDA's pending CBD food additive rulemaking is fragmenting manufacturer compliance strategies while state-level THC variance forces multi-jurisdictional formulation architectures.
Growth Catalysts
- USDA hemp cultivation rules:Interstate hemp biomass commerce expands raw material sourcing pools for extraction facilities.
- Wellness retail channel expansion:Health food chains in California and Colorado dedicate incremental shelf space to third-party tested SKUs.
- Nanoencapsulation:Lipid-based emulsification technology improves bioavailability metrics that drive repeat purchase behavior.
Market Restraints
- Extract input cost volatility:Hemp biomass pricing fluctuates with weather-driven yield variance across Kentucky and Oregon cultivation zones.
- FDA food additive prohibition:Interstate commerce of ingestible CBD remains legally ambiguous pending final rulemaking.
- THC-free isolate demand:Workplace drug testing sensitivity drives substitution toward broad spectrum alternatives that compress margin pools.
Strategic Opportunities
- Canadian retail integration:Health Canada's cannabis regulations permit edibles in provincial distribution networks underserved by US suppliers.
- Beverage format expansion:Ready-to-drink CBD infusions capture wellness-oriented consumers outside traditional dispensary channels.
- Current Good Manufacturing Practice certification:FDA-aligned quality systems create defensible positioning against uncertified competitors.
Industry Challenges
- Analytical chemistry talent scarcity:Cannabinoid quantification and stability testing require specialized laboratory personnel in short supply.
- Multi-state licensing complexity:Separate manufacturing permits for California, Colorado, and Oregon operations fragment production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Edibles Market |
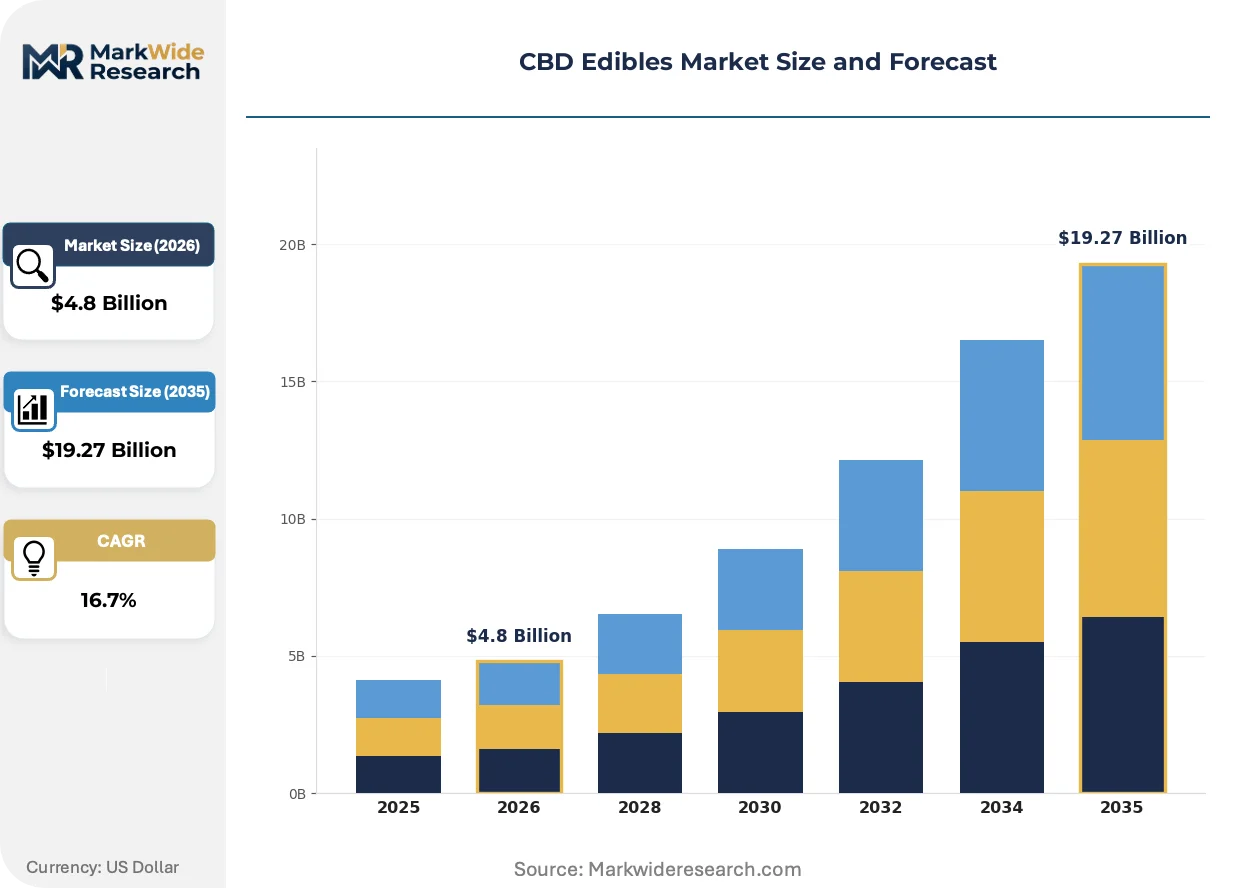
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummies, Chocolates, Beverages, Baked Goods End User: Individuals, Retailers, Restaurants, Health Stores Packaging Type: Bags, Bottles, Boxes, Tins Dosage Form: Full Spectrum, Broad Spectrum, Isolate, Others |
| Companies Covered | Kiva Confections, Wyld, Wana Brands, Dixie Elixirs, Coda Signature, Charlotte's Web, Medterra CBD, CBD American Shaman, CBDfx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Edibles Market Emerging Trajectories
Nanoencapsulation and precision dosing systems are compressing formulation differentiation cycles while regulatory clarity efforts in North America and Europe reshape commercialization pathways.
Lipid-based nanoemulsion technology is miniaturizing cannabinoid particle size to enhance water compatibility and absorption kinetics. Beverage manufacturers in California and Colorado adopt these systems to achieve homogenous suspension without phase separation. The technology is miniaturizing the functional gap between oil-based tinctures and ready-to-drink formats, enabling shelf-stable liquid products that previously required refrigeration.
EFSA's novel food assessment pathway for hemp-derived CBD establishes a compliance template that manufacturers seeking European market access must replicate. The evaluation framework requires toxicological dossiers and stability data that extend product development timelines by eighteen to thirty-six months. Isolate-based formulations face stricter scrutiny than full spectrum alternatives, redirecting R&D investment toward botanical matrix preservation.
Direct-to-subscription models are displacing dispensary-dependent distribution for hemp-derived SKUs with THC levels below detection thresholds. Wellness-focused consumers in urban coastal markets prefer automated replenishment of consistent-dose gummies over variable-potency retail purchases. This channel rotation concentrates customer lifetime value metrics with brands that invest in compliance documentation and third-party certificate transparency.
CBD Edibles Market Segmentation
Channel architecture determines which CBD edible formats reach consumers. Dispensary networks favor shelf-stable formats with precise dosing, while wellness retail channels prioritize packaging transparency and third-party verification. Manufacturers must align formulation and packaging choices with the regulatory requirements of each distribution pathway.
Product Type:
Dispensary channels concentrate gummy and chocolate SKUs, while beverage formats penetrate convenience retail through nanoencapsulation technology.
- Gummies:Gelatin or pectin matrices suspend measured cannabinoid doses in shelf-stable, portion-controlled units. California and Colorado dispensaries allocate premium shelf space to precision-dosed gummy lines. By volume, gummies lead. By growth pace, beverages are climbing the fastest.
- Chocolates:Lipid-based cocoa butter serves as an effective cannabinoid carrier, masking hemp-derived terpene profiles. Pacific Northwest health stores prioritize fair-trade chocolate SKUs with full-spectrum certification. By volume, gummies lead. By growth pace, beverages are climbing the fastest.
- Beverages:Ready-to-drink formats leverage nanoemulsion technology for water-compatible, homogenous suspension.
- Baked Goods:Cookies and brownies face shorter shelf life constraints that limit interstate distribution feasibility.
By volume, gummies lead. By growth pace, beverages are climbing the fastest.
End User:
Cost tier stratification separates direct-to-consumer premium positioning from bulk supply relationships serving licensed retailers.
- Individuals:Direct purchasers through subscription platforms and dispensary counters demand batch-specific certificate of analysis documentation. California's urban coastal markets show concentration of wellness-oriented repeat buyers seeking consistent-dose regimens. Subscription models capture highest customer lifetime value.
- Retailers:Licensed dispensaries and health food chains require compliant labeling, child-resistant packaging, and interstate shipping documentation. Colorado's established retail corridors maintain stringent third-party testing requirements that filter supplier pools. Procurement consolidation favors multi-SKU vendors.
- Restaurants:Foodservice integration remains limited by FDA food additive prohibition and liability exposure.
- Health Stores:Natural product retailers emphasize USDA organic certification and THC-free isolate formulations for drug-test-conscious consumers.
Individuals generate highest per-unit margins. Retailers command aggregate volume throughput.
Packaging Type:
Application context drives material selection — child safety mandates dominate dispensary-bound formats, while shelf differentiation priorities govern wellness retail.
- Bags:Flexible pouches with resealable closures and opaque barriers protect photosensitive cannabinoids in gummy formats. Oregon manufacturers favor sustainable film substrates to align with state environmental regulations. Bags dominate gummy category shipment economics.
- Bottles:Amber or cobalt glass provides UV protection for liquid beverages and oil-based tinctures. Colorado beverage producers specify pharmaceutical-grade closures to prevent oxidation during distribution. Bottles carry premium positioning in beverage segments.
- Boxes:Rigid paperboard enables graphic differentiation for gift-oriented chocolate assortments.
- Tins:Metal containers signal heritage positioning for artisan chocolate lines in specialty retail.
Bags minimize unit economics for high-velocity SKUs. Bottles command structural premium in beverage expansion.
Dosage Form:
Margin structure separates full-spectrum premium tiers from standardized isolate competition, with broad spectrum occupying intermediate positioning.
- Full Spectrum:Whole-plant extracts retain minor cannabinoids and terpenes that support entourage effect claims. California's medical cannabis patient population drives demand for comprehensive cannabinoid profiles with documented terpene content. Full spectrum captures highest price per milligram.
- Broad Spectrum:THC-free formulations preserve minor cannabinoids through selective remediation processes. Workplace drug testing sensitivity in professional services sectors accelerates broad spectrum substitution across Colorado and Oregon urban markets. Broad spectrum bridges compliance and efficacy positioning.
- Isolate:Crystalline CBD offers maximum standardization and THC-free certainty for risk-averse retailers.
- Others:Water-soluble powders and nanoencapsulated concentrates enable beverage formulation flexibility.
Full spectrum commands price premium. Isolate shows steepest volume expansion in conventional retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Oakland's refrigerated cargo infrastructure underwrites California's dominance in CBD edibles distribution, connecting Pacific Northwest extraction facilities to Asia-Pacific export markets.
United States
California's dispensary networks and Colorado's retail corridors concentrate demand for precision-dosed gummies and nanoencapsulated beverages. FDA food additive rulemaking creates interstate commerce ambiguity that fragments manufacturer compliance strategies. Denver-Boulder extraction clusters supply biomass-derived isolates to national wellness retail chains.
Canada
Health Canada's cannabis regulations permit edibles in provincial distribution networks, attracting US manufacturers seeking regulatory clarity. Provincial retail monopolies in Ontario and British Columbia standardize testing requirements that filter supplier qualification. Calgary-based extraction facilities serve prairie province distribution channels with THC-compliant formulations.
Germany
EFSA's novel food assessment pathway drives eighteen-to-thirty-six-month product development timelines for hemp-derived CBD entrants. BfArM's medical cannabis framework creates parallel compliance tracks for wellness versus pharmaceutical positioning. Cologne-Düsseldorf logistics hubs coordinate EU-wide distribution for certified isolate suppliers.
Switzerland
Swissmedic's tolerance for low-THC cannabis products enables CBD edible commercialization ahead of broader EU harmonization. Zurich and Geneva wellness retail corridors attract premium-positioned brands seeking regulatory predictability. Basel pharmaceutical manufacturing heritage supplies analytical chemistry talent for stability testing protocols.
United Kingdom
FSA's novel food authorization deadline compresses market entry windows for unvalidated CBD product lines. London health store chains prioritize third-party certified isolates for drug-test-conscious professional services workers. Manchester-Leeds manufacturing corridors develop white-label production capacity for continental European brands.
CBD Edibles Market Vendor Landscape
Listed leaders compete with private specialists across compliance documentation and channel access dimensions. The vendor base stratifies between multi-state licensed operators and single-jurisdiction craft producers. Three archetypes dominate: precision-dosing technology specialists, fruit-forward formulation brands, and pharmaceutical-grade certification seekers. Competitive moves concentrate on Current Good Manufacturing Practice accreditation and direct-to-subscription platform development.
Among California-based confectionery specialists, Kiva Confections and Wyld exemplify divergent positioning strategies within the premium tier. Kiva Confections represents precision-dosing technology leadership through state-licensed dispensary penetration. Wyld occupies a position anchored in fruit-forward formulation dominance across Pacific Northwest retail channels. Wana Brands exemplifies the multi-jurisdictional licensing archetype with presence across Colorado, California, and emerging state markets. These three entities collectively illustrate how geographic concentration, product format specialization, and regulatory compliance depth define competitive differentiation in fragmented state-by-state market development.
| Leading Market Players |
|---|
| Kiva Confections |
| Wyld |
| Wana Brands |
| Dixie Elixirs |
| Coda Signature |
| Charlotte's Web |
| Medterra CBD |
| CBD American Shaman |
| CBDfx |
| Others |
Supply Flow & Price Mechanics
Current Good Manufacturing Practice certification gates both supply qualification and price differentiation simultaneously, separating FDA-aligned manufacturers from uncertified competitors while compressing margin pools for isolate-based products facing THC-free workplace testing demand.
Pricing Analysis
Volume-discount tiering structures stratify across premium full-spectrum, standard broad-spectrum, and economy isolate formulations. Price differentiation rests on certification depth and geographic delivery complexity, with California dispensary networks absorbing transport premiums that Oregon manufacturers embed in landed costs. Pricing pressure intensifies in isolate tiers as broad-spectrum alternatives capture drug-test-conscious professionals. Individual subscribers show lowest price sensitivity; bulk retailers negotiate hardest on per-milligram terms.
Supply Chain Analysis
Just-in-time inventory strategies dominate beverage formats where nanoemulsion shelf stability is limited, while strategic stockpiling of hemp biomass concentrates in Kentucky and Oregon extraction clusters. Raw material flows draw from Colorado cultivation cooperatives, California indoor growing operations, and Oregon outdoor harvests. Single-source vulnerability concentrates in analytical chemistry talent pools for cannabinoid quantification. Distribution runs through state-licensed dispensary networks and health store retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CBD edibles market is entering a cyclical recovery phase as FDA rulemaking clarity and state licensing maturation converge, with wellness retail channel expansion driving normalized demand patterns after regulatory uncertainty compression.
For Market Incumbents: Shield market position by deepening Current Good Manufacturing Practice certification moats against uncertified craft competitors, and consolidate multi-state licensing footprints to capture procurement consolidation at licensed retailers facing SKU rationalization pressure.
For New Entrants and Emerging Players: Anchor in Canadian provincial distribution networks where Health Canada regulations provide regulatory predictability absent from US interstate commerce ambiguity, and pursue white-label beverage manufacturing partnerships leveraging nanoencapsulation technology gaps.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across nanoencapsulation equipment and pharmaceutical-grade testing infrastructure, favoring acquisition targets with existing FDA-aligned quality systems and established direct-to-subscription customer bases as indicators of long-term viability through regulatory consolidation phases.
| Strategic Initiative | Industry Significance |
|---|---|
| Current Good Manufacturing Practice Certification | FDA-aligned quality systems create defensible positioning against uncertified competitors in state-licensed channels. |
| Nanoencapsulation Technology Investment | Lipid-based emulsification enables beverage format expansion into wellness retail outside traditional dispensaries. |
| Direct-to-Subscription Platform Development | Automated replenishment models capture highest customer lifetime value in California urban coastal markets. |
| Multi-State Licensing Consolidation | Combined California-Colorado-Oregon permits reduce compliance fragmentation and procurement qualification costs. |
| Canadian Market Entry | Health Canada regulatory clarity permits edibles distribution through provincial networks underserved by US suppliers. |
Methodological Framework
A standing panel of extraction facility operators, dispensary procurement managers, wellness retail category buyers, and regulatory compliance officers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against FDA docket submissions, state cannabis licensing databases, USDA hemp cultivation reports, and third-party certificate of analysis repositories. Bottom-up SKU-level enumeration triangulated against top-down channel revenue estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including product format, dosage form spectrum, packaging type, and end-user channel. CAGRs derived from regression analysis of historical state-level sales trajectories, incorporating hemp biomass yield variance, regulatory enforcement intensity indices, and wellness retail shelf space allocation trends as industry-specific inputs.
Material uncertainties — FDA final rulemaking timing, state-level THC threshold adjustments, and hemp cultivation weather impacts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory trajectory and channel evolution. Revision becomes warranted when FDA food additive prohibition crosses resolution thresholds or multi-state licensing reciprocity agreements achieve critical mass.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
Africa Medical Cannabis Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabis Cultivation Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
Trichome Separator/Extractor Market