
 Cannabis Pharmaceuticals Market | 2026-2036
Cannabis Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Pharmaceuticals Market Intelligence
Specialty pharmacy distribution is rewriting how cannabinoid therapies reach patients in regulated markets. Jazz Pharmaceuticals leverages its orphan drug infrastructure to sustain controlled-substance logistics across multiple continents. Tilray Brands anchors European supply through its German cultivation and distribution assets. Curaleaf Holdings competes via vertical integration from cultivation through retail pharmacy partnerships in North America.
Cannabis pharmaceuticals comprise purified or standardized cannabinoid formulations manufactured under current Good Manufacturing Practice conditions with defined purity profiles, stability data, and batch consistency documentation; these products serve as prescription therapeutics for indications where conventional treatments demonstrate insufficient efficacy or tolerability. Oils dominate current prescription volumes due to established titration protocols and clinician familiarity, while capsules capture margin pools through extended-release formulations that improve compliance in chronic pain cohorts. Neurological disorders represent the fastest-expanding application segment as payers increasingly recognize cannabinoid efficacy in treatment-resistant epilepsy and spasticity.
The FDA maintains Schedule V classification for Epidiolex while DEA scheduling constraints limit interstate commerce for THC-containing formulations, creating a bifurcated regulatory landscape that shapes manufacturer investment priorities. Germany's BfArM cannabis agency implements strict batch-release testing that filters out non-compliant suppliers and concentrates procurement among GMP-certified manufacturers. Stakeholders must monitor how FDA rescheduling deliberations and EMA centralized assessment pathways for cannabinoid novel therapies will reshape competitive access requirements.
Market Dynamics
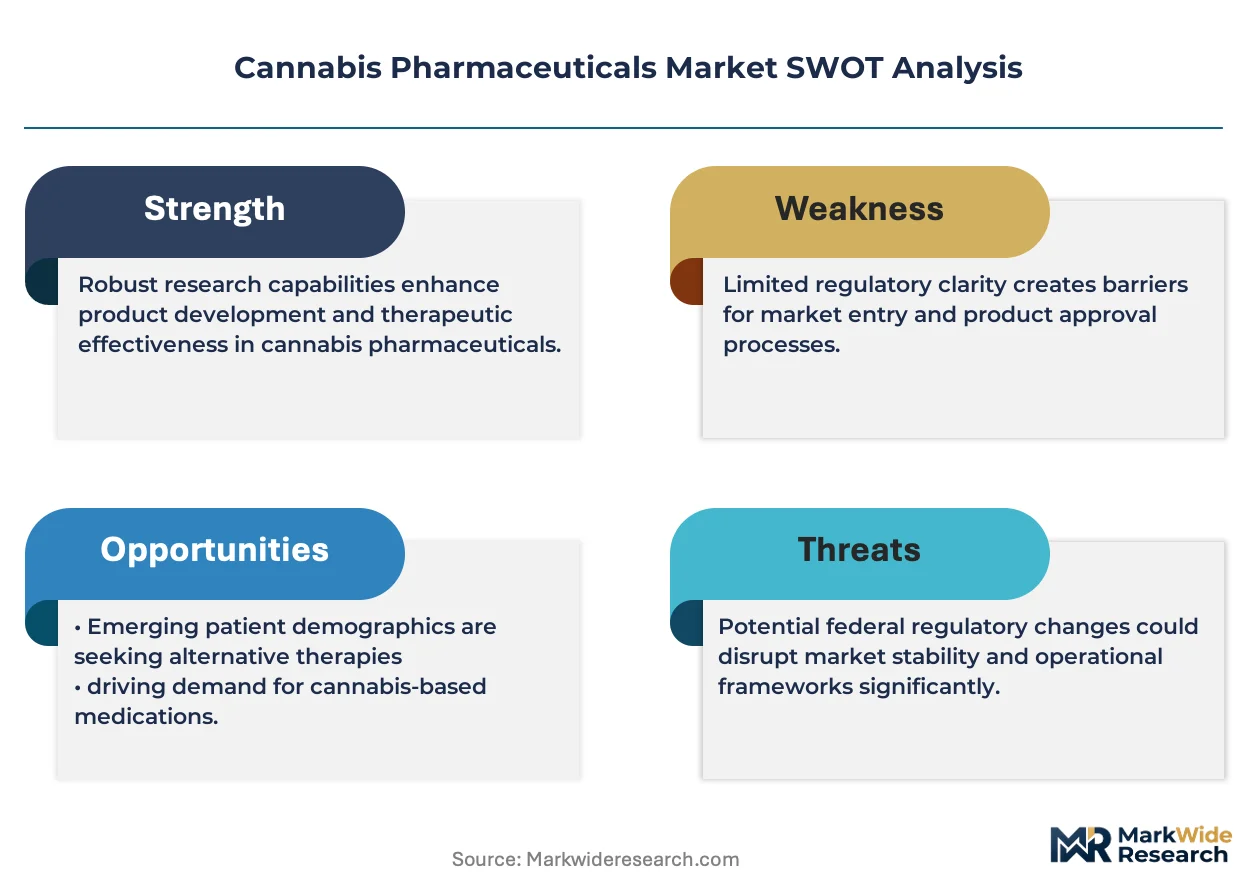
Regulatory fragmentation between Schedule V and Schedule I classifications is bifurcating investment flows, forcing manufacturers to choose between THC-inclusive pipelines and CBD-isolate strategies that cannot easily pivot.
Growth Catalysts
- Statutory Reimbursement Frameworks:Germany's statutory health insurance reimbursement for cannabis-based medicines establishes a payment precedent that other European social insurance systems are evaluating for adoption.
- Neurological Indication Expansion:Treatment-resistant epilepsy and spasticity cohorts demonstrate measurable outcomes where conventional anticonvulsants and muscle relaxants fail, expanding prescriber comfort with cannabinoid protocols.
- GMP Certification Concentration:Batch-release testing requirements from Germany's BfArM filter out non-compliant suppliers, concentrating procurement among certified manufacturers and reducing price competition from unverified sources.
Market Restraints
- DEA Interstate Commerce Constraints:Schedule I classification for THC-containing formulations prevents cross-state distribution efficiencies that other pharmaceutical categories enjoy, fragmenting manufacturing scale.
- Active Pharmaceutical Ingredient Sourcing Concentration:GMP-certified cannabinoid API production concentrates among three European contract manufacturers, creating single-source vulnerability for pipeline products.
- Stability Data Requirements:EMA centralized assessment pathways demand 24-month stability documentation that delays market entry for novel formulations by 18-30 months versus conventional small molecules.
Strategic Opportunities
- French Hospital Pilot Programs:ANSM-supervised therapeutic cannabis pilots in pain and palliative care units create a regulatory pathway for hospital formulary inclusion ahead of full reimbursement authorization.
- Orphan Disease Designation Pathways:FDA and EMA orphan drug incentives for rare epilepsy syndromes reduce clinical trial size requirements and extend market exclusivity periods for targeted formulations.
- Specialty Pharmacy Direct Distribution:Controlled-substance logistics partnerships bypass wholesale consolidation, capturing margin pools that traditional pharmaceutical distribution channels previously extracted.
Industry Challenges
- GMP Manufacturing Talent Scarcity:Cannabinoid extraction and purification expertise at pharmaceutical-grade standards remains concentrated among personnel who transitioned from botanical supplement or generic API backgrounds.
- Cross-Jurisdictional Labeling Complexity:Divergent THC threshold definitions between FDA, EMA, and Health Canada require country-specific packaging runs that prevent manufacturing scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Pharmaceuticals Market |
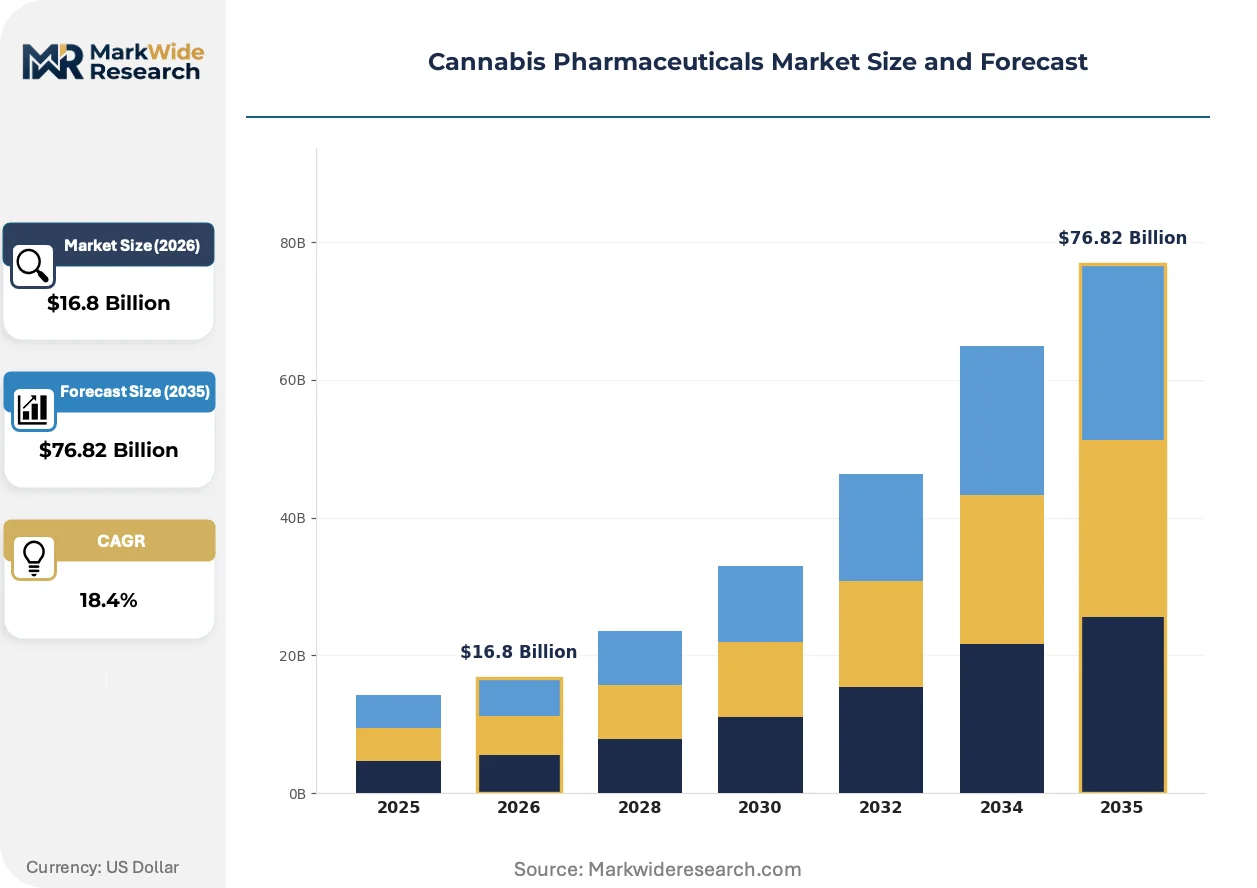
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $76.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Capsules, Edibles, Topicals Application: Pain Management, Neurological Disorders, Cancer Treatment, Gastrointestinal Issues End User: Pharmacies, Hospitals, Rehabilitation Centers, Homecare Providers Formulation: Full-Spectrum, Broad-Spectrum, Isolate, Infused Products |
| Companies Covered | Jazz Pharmaceuticals, AbbVie, Bausch Health Companies, Insys Therapeutics, Tilray Brands, Canopy Growth Corporation, Aurora Cannabis, Curaleaf Holdings, Green Thumb Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Pharmaceuticals Market Strategic Shifts & Innovations
Continuous manufacturing platforms and synthetic biology routes are compressing production timelines while regulatory harmonization efforts attempt to reduce the compliance burden of multi-territory launches.
Biosynthetic cannabinoid production via engineered yeast strains is rendering obsolete agricultural cultivation for high-purity APIs. Neurology-focused biotechs are adopting these platforms to secure supply security independent of crop variability and pesticide residue concerns. The shift collapses the 12-18 month cultivation cycle to 2-3 week fermentation batches, compressing working capital requirements by 60-70 percent for pipeline products.
EMA's centralized assessment pathway for cannabinoid novel therapies is harmonizing batch-release standards across EU member states. The policy eliminates redundant national testing requirements that previously duplicated BfArM protocols in Germany, ANSM reviews in France, and AIFA evaluations in Italy. Manufacturers targeting European market entry now optimize dossier preparation for centralized rather than decentralized regulatory submission.
Hospital pharmacy procurement committees are consolidating cannabinoid purchasing through single-source agreements with specialty distributors. The concentration displaces fragmented physician-driven dispensing that characterized early access programs. Germany and Australia exhibit the most pronounced consolidation, where statutory reimbursement frameworks incentivize formulary standardization over individualized product selection.
Cannabis Pharmaceuticals Market Segmentation
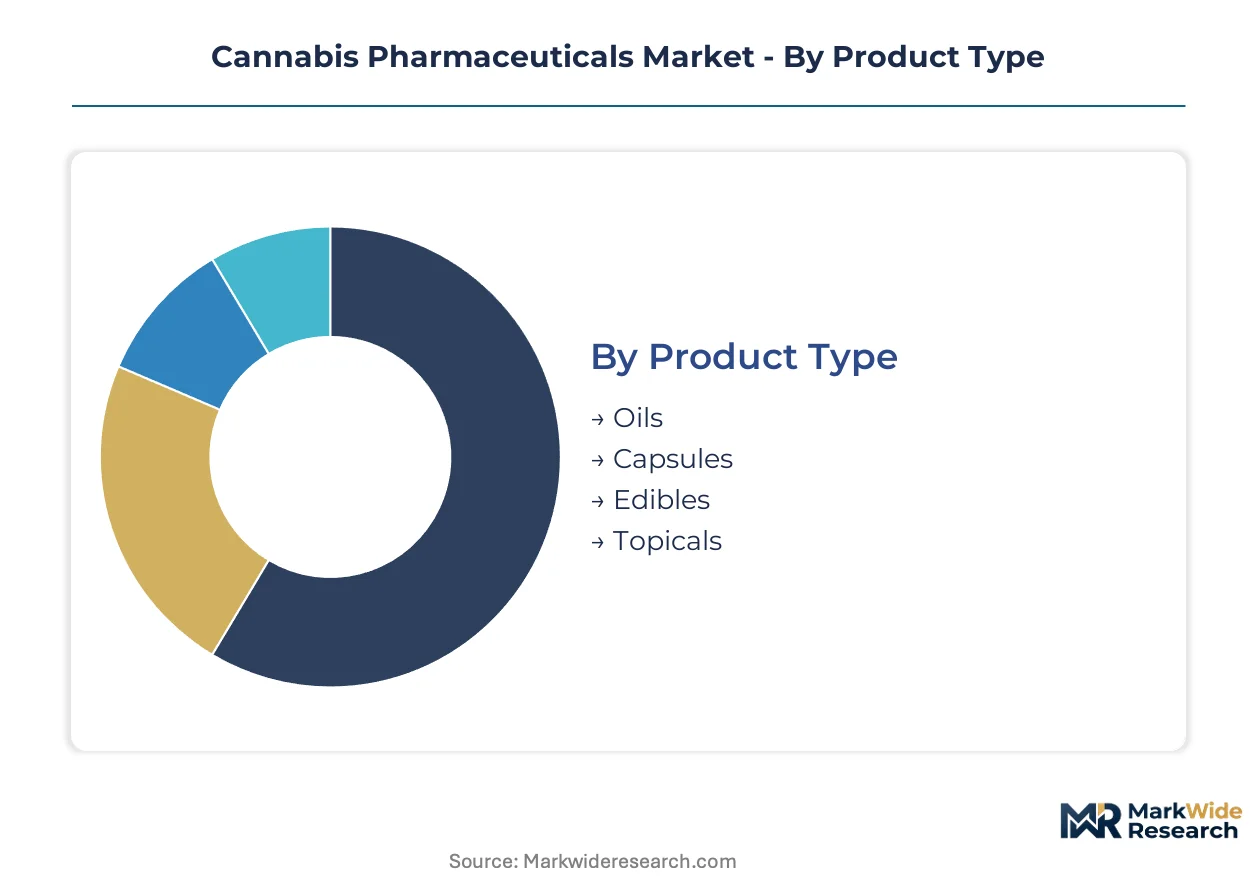
Cannabis pharmaceutical segmentation reveals how formulation chemistry, delivery mechanics, and prescriber setting interact to determine reimbursement eligibility and patient access. Understanding these cross-cutting dimensions exposes where manufacturers capture margin versus where they compete on volume.
Product Type:
Oils turn over fastest in prescription workflows due to titration flexibility, while capsules and edibles cycle more slowly through chronic therapy protocols. Topicals occupy the slowest inventory velocity as they require specialist referral pathways.
- Oils:Liquid formulations enable milligram-precision dosing adjustments that neurologists prefer for epilepsy titration protocols. German statutory health insurance reimbursement frameworks prioritize oil-based prescriptions for treatment-resistant spasticity, concentrating demand in BfArM-certified supply chains.
- Capsules:Extended-release matrix formulations improve compliance in chronic pain cohorts through standardized dosing intervals. Hospital pharmacy procurement committees in Australia consolidate purchasing through single-source agreements that favor capsule stability profiles over oil variability.
- Edibles:Gastroresistant formulations bypass first-pass metabolism for specific palliative applications.
- Topicals:Transdermal patches and creams serve localized neuropathic pain with limited systemic absorption.
Oils dominate installed base. Capsules represent where expansion concentrates.
Application:
Cost tiering separates neurological indications with orphan drug pricing from pain management protocols competing against generic opioids. Cancer treatment applications command premium positioning through hospital formulary inclusion.
- Pain Management:Chronic and neuropathic pain protocols compete against established analgesic classes, requiring outcome-based differentiation. French ANSM-supervised hospital pilot programs create procurement pathways ahead of full reimbursement authorization.
- Neurological Disorders:Treatment-resistant epilepsy and multiple sclerosis spasticity demonstrate measurable efficacy where conventional anticonvulsants fail. FDA orphan drug incentives reduce clinical trial size requirements for rare epilepsy syndromes, accelerating development timelines.
- Cancer Treatment:Chemotherapy-induced nausea and appetite stimulation serve oncology supportive care.
- Gastrointestinal Issues:Inflammatory bowel disease and functional GI disorders represent emerging prescriber comfort zones.
Pain management commands volume share. Neurological disorders represent the steepest expansion trajectory.
End User:
Customer type determines regulatory burden intensity, with hospitals facing stricter controlled-substance custody requirements than retail pharmacies. Homecare providers operate under variable state-level licensing that fragments distribution scale.
- Pharmacies:Specialty pharmacy networks manage controlled-substance logistics through direct distribution partnerships that bypass wholesale consolidation. German and Australian markets exhibit pronounced procurement concentration through single-source distributor agreements.
- Hospitals:Inpatient formulary committees standardize cannabinoid selection under centralized pharmacy governance. EMA centralized assessment pathways harmonize batch-release standards that hospital procurement committees reference for EU-wide supplier qualification.
- Rehabilitation Centers:Long-term care facilities manage spasticity and chronic pain in post-acute recovery cohorts.
- Homecare Providers:Outpatient nursing services administer continuing therapy for mobility-limited patients.
Pharmacies anchor prescription volume. Hospitals concentrate regulatory investment.
Formulation:
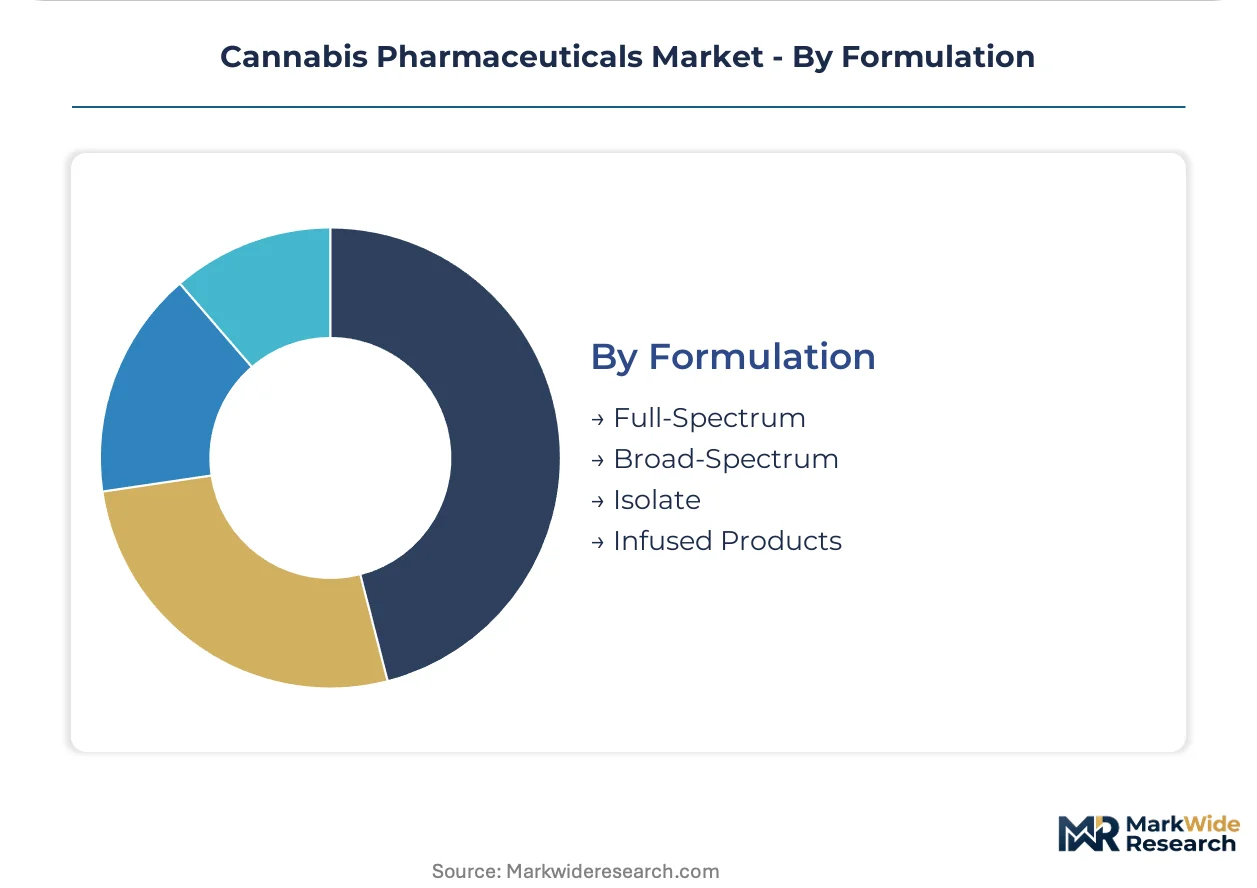
Supply concentration filters formulation availability, with full-spectrum extraction requiring GMP-certified botanical processing that only three European contract manufacturers currently provide. Isolate production shifts toward biosynthetic platforms that collapse cultivation cycles.
- Full-Spectrum:Whole-plant extracts retaining minor cannabinoids and terpenes require agricultural sourcing with pesticide residue controls. BfArM batch-release testing filters out non-compliant suppliers, concentrating procurement among certified manufacturers.
- Broad-Spectrum:THC-free formulations with retained minor cannabinoids serve jurisdictions with strict THC thresholds. Health Canada and FDA divergent THC definitions require country-specific packaging runs that prevent manufacturing scale economies.
- Isolate:Single-molecule CBD or THC APIs enable precise formulation standardization.
- Infused Products:Co-formulation with conventional pharmaceuticals requires compatibility stability data.
Full-spectrum dominates current prescription patterns. Isolate formulations are gaining share fastest through biosynthetic production adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Statutory reimbursement frameworks in Germany have established the dominant payment precedent for cannabis-based medicines, with other European social insurance systems now evaluating adoption. The United States maintains bifurcated scheduling constraints that fragment interstate distribution. Australia and Canada have developed distinct procurement concentration patterns through specialty pharmacy networks.
Germany
Treatment-resistant epilepsy and spasticity cohorts drive prescription volume through BfArM-certified supply chains. The statutory health insurance reimbursement framework prioritizes oil-based prescriptions, creating concentrated demand. North Rhine-Westphalia hosts the densest cluster of GMP-certified contract manufacturers serving hospital pharmacy procurement committees.
United States
FDA orphan drug incentives accelerate development timelines for rare epilepsy syndromes, reducing clinical trial size requirements. DEA Schedule I classification for THC-containing formulations prevents cross-state distribution efficiencies that other pharmaceutical categories enjoy. Greater Boston anchors neurological indication research with specialized academic medical center formulary committees.
Canada
Health Canada divergent THC threshold definitions require country-specific packaging runs that prevent manufacturing scale economies with US operations. The centralized assessment pathway for cannabinoid novel therapies harmonizes batch-release standards across provincial health authorities. Ontario concentrates specialty pharmacy direct distribution partnerships that bypass wholesale consolidation.
Australia
Hospital pharmacy procurement committees consolidate cannabinoid purchasing through single-source agreements with specialty distributors. The Therapeutic Goods Administration supervises therapeutic cannabis pilots creating regulatory pathways for hospital formulary inclusion. Victoria exhibits pronounced procurement concentration where statutory frameworks incentivize formulary standardization.
Cannabis Pharmaceuticals Market Key Industry Players
On the supply side, the industry is bifurcating between THC-inclusive pipelines and CBD-isolate strategies that cannot easily pivot. The vendor base separates into pharmaceutical-grade manufacturers with GMP certification and botanical processors lacking batch-release documentation. Three strategic archetypes dominate: orphan drug infrastructure deployers, European cultivation asset holders, and vertically integrated North American operators. Capacity expansion and specialty pharmacy direct distribution partnerships represent the dominant competitive moves reshaping margin capture.
Within the orphan drug infrastructure tier, Jazz Pharmaceuticals exemplifies controlled-substance logistics deployment across multiple continents. Tilray Brands anchors European supply security through German cultivation and distribution assets. Curaleaf Holdings occupies a position representing vertical integration from cultivation through retail pharmacy partnerships in North American markets.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals |
| AbbVie |
| Bausch Health Companies |
| Insys Therapeutics |
| Tilray Brands |
| Canopy Growth Corporation |
| Aurora Cannabis |
| Curaleaf Holdings |
| Green Thumb Industries |
| Others |
Cost & Logistics Intelligence
North Rhine-Westphalia's GMP-certified contract manufacturing cluster concentrates pharmaceutical-grade cannabinoid extraction capacity, positioning certified suppliers to command premium pricing over botanical processors lacking BfArM batch-release documentation. This geographic concentration of validated production assets creates asymmetric pricing power that downstream buyers in German statutory health insurance frameworks cannot easily circumvent.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and wellness-tier products, with GMP-certified APIs commanding substantial premiums over non-validated botanical extracts. Pricing stratifies across three tiers: orphan-designated neurological therapies at premium positioning, chronic pain oils at mid-market reimbursement rates, and wellness-adjacent CBD isolates at commodity levels. Cost compression in wellness-tier isolates is intensifying because biosynthetic production platforms are collapsing fermentation cycles from months to weeks. Hospital pharmacy procurement committees exhibit lowest price sensitivity due to statutory reimbursement guarantees, while retail pharmacy cash-pay segments face highest sensitivity to out-of-pocket costs.
Supply Chain Analysis
Three European contract manufacturers—Bachem, Evonik, and Siegfried—hold dominant positions in GMP-certified cannabinoid API production, concentrating supply security among this limited vendor set. Production gravity centers on Germany, Switzerland, and Denmark, with North American capacity constrained by DEA Schedule I licensing requirements for THC-containing formulations. Raw material dependencies include pharmaceutical-grade ethanol for extraction, engineered yeast strains for biosynthetic routes, and specialized chromatography resins for purification. Single-source vulnerability pervades the API tier, where qualified alternative suppliers require 18-24 month qualification timelines. Distribution runs through specialty pharmacy direct partnerships that bypass wholesale consolidation, capturing margin pools previously extracted by traditional pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement as hospital pharmacy committees in Germany and Australia displace fragmented physician-driven dispensing through single-source distributor agreements. This consolidation concentrates volume leverage among fewer decision-makers, compressing margins for non-differentiated suppliers.
For Market Incumbents: Harden GMP certification moats through backward integration into biosynthetic production platforms that collapse working capital requirements and eliminate agricultural variability risks. Defend formulary positioning by deepening orphan drug infrastructure across multiple continents, as DEA rescheduling deliberations threaten to fragment interstate distribution advantages for THC-inclusive portfolios. Priority investments should center on EMA centralized assessment pathway dossiers that unlock EU-wide hospital procurement access.
For New Entrants and Emerging Players: Establish a beachhead in French ANSM-supervised hospital pilot programs, where therapeutic cannabis access precedes full reimbursement authorization and creates procurement relationships ahead of formulary standardization. Target Australian specialty pharmacy networks exhibiting pronounced procurement concentration under TGA-supervised frameworks. The most penetrable segment is extended-release capsule formulations for chronic pain compliance, where manufacturing scale requirements are lower than neurological indication pipelines. A go-to-market angle emphasizing 24-month stability data readiness accelerates EMA pathway eligibility.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biosynthetic platform holders over agricultural cultivation assets, as fermentation-based production renders obsolete crop-dependent supply chains. Long-term viability across the projection horizon rests on regulatory arbitrage capabilities—specifically, navigating divergent THC threshold definitions between FDA, EMA, and Health Canada without country-specific manufacturing duplication. Acquisition targets should display GMP certification plus centralized regulatory dossier preparation. The signal to watch is FDA rescheduling momentum, which would unlock interstate commerce efficiencies and reshape competitive economics for THC-inclusive portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Centralized Assessment Pathway | Harmonizes batch-release standards across EU member states, eliminating redundant national testing. |
| Biosynthetic Production Platform | Collapses 12-18 month cultivation cycles to 2-3 week fermentation batches, compressing working capital. |
| Specialty Pharmacy Direct Distribution | Bypasses wholesale consolidation, capturing margin pools through controlled-substance logistics partnerships. |
| Orphan Disease Designation Pursuit | Reduces clinical trial size requirements and extends market exclusivity for rare epilepsy syndromes. |
| GMP Certification Investment | BfArM batch-release testing filters non-compliant suppliers, concentrating procurement among certified manufacturers. |
Research Approach
A standing panel of regulatory affairs leads, hospital formulary directors, specialty pharmacy procurement managers, and payer access specialists provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation from FDA filings, EMA submission databases, ClinicalTrials.gov records, and German statutory health insurance reimbursement data. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources to establish analytical coherence.
Scenario bracketing anchored the forecast framework, with volume and value outputs reflecting analytical cross-checks across product type, application indication, end-user channel, and formulation chemistry dimensions. CAGRs derived from segmented growth trajectory analysis incorporating regulatory approval timelines, reimbursement expansion patterns, and manufacturing capacity buildout schedules. Biosynthetic production adoption curves and DEA rescheduling probability assessments informed industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in statutory reimbursement authorization timelines or EMA centralized assessment pathway processing speeds would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and GMP certification expansion rates. Quarterly review of FDA rescheduling deliberations, BfArM batch-release approval volumes, and biosynthetic platform commercialization milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Morocco Medical Cannabis Market
Cannabis/Marijuana
Cannabinoid CB2 Products Market
Cannabis/Marijuana
Mexico Medical Cannabis Market
Cannabis/Marijuana
Medical Marijuana Market
Cannabis/Marijuana
Cannabis Cultivation Market
Cannabis/Marijuana
Europe Medical Cannabis Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
Medical Cannabis Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market