
 Europe Casino Gambling Market | 2026-2036
Europe Casino Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Casino Gambling Market Insights
The Europe casino gambling sector is pivoting between high-touch physical venues and algorithm-driven digital platforms, splitting capital allocation and customer acquisition strategies into divergent operational models. Groupe Lucien Barrière leverages its heritage real estate portfolio to anchor premium hospitality-linked gaming across France and Switzerland. Entain PLC competes through proprietary technology stacks that sustain cross-border online scalability. Flutter Entertainment PLC dominates sports-betting integration, extending its reach into live dealer and casino crossover products.
Europe casino gambling encompasses regulated games of chance and skill operated through licensed physical premises or digital interfaces, governed by return-to-player percentages, random number generation certification, and anti-money-laundering protocols. Its primary commercial purpose is to generate taxable entertainment revenue while enforcing player protection standards. Slot machines and live dealer games capture disproportionate margin pools as operators shift floor space and server capacity toward higher-frequency, lower-overhead formats. Brick-and-mortar venues retain structural importance for tax compliance and VIP relationship management, though mobile apps absorb incremental user growth across Southern and Eastern Europe.
The EU AI Act and national gambling authorities in France, the United Kingdom, and Malta constrain automated decision-making in player targeting and risk scoring, forcing operators to reengineer loyalty algorithms and deposit-limit triggers. GDPR and country-specific self-exclusion registries further tighten data handling requirements, raising compliance costs for pan-European platform providers. Stakeholders must weigh regulatory fragmentation against scale economics when prioritizing market entry or technology investment across the continent's layered licensing environment.
Market Dynamics
The EU AI Act is forcing casino operators across France, Germany, and the United Kingdom to dismantle automated player-tracking systems and rebuild compliance architectures around human-in-the-loop decision protocols.
Growth Catalysts
- GDPR-aligned data portability:Cross-border player verification systems now interoperate between Malta, Gibraltar, and UK licensing jurisdictions, reducing onboarding friction for digital platforms.
- Live dealer studio technology:Real-time streaming infrastructure from Riga and Bucharest is lowering per-table operational costs for operators serving multiple European markets simultaneously.
- France's integrated resort licensing:Regional prefectures are approving mixed-use entertainment complexes that bundle gaming floors with conference and hospitality assets, expanding taxable revenue bases.
Market Restraints
- Fragmented national licensing:Each EU member state maintains distinct technical standards for random number generation certification, multiplying compliance engineering costs for platform providers.
- Payment processor concentration:Three Nordic banking consortia dominate cross-border gambling transaction clearing, extracting elevated interchange fees from operators in Southern and Eastern Europe.
- Self-exclusion registry interoperability gaps:Denmark's Spillemyndigheden system does not automatically sync with Sweden's Spelinspektionen database, creating compliance blind spots for multi-market operators.
Strategic Opportunities
- Romania and Bulgaria digital licensing:These markets show underpenetrated mobile casino adoption relative to Western European saturation, with lower customer acquisition costs for compliant entrants.
- CE marking convergence for gaming hardware:Unified electromagnetic compatibility standards are reducing recertification burdens for slot machine manufacturers shipping across the single market.
- Hybrid loyalty architectures:Convergence of blockchain-based reward tokens with traditional tiered programs is enabling cross-property redemption between physical and digital channels.
Industry Challenges
- AI audit talent scarcity:The EU AI Act mandates algorithmic impact assessments that few gambling operators can staff internally, forcing reliance on expensive external consultancies.
- Legacy floor system integration:Decades-old slot machine protocols in established venues resist real-time data extraction needed for modern player protection analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Casino Gambling Market |
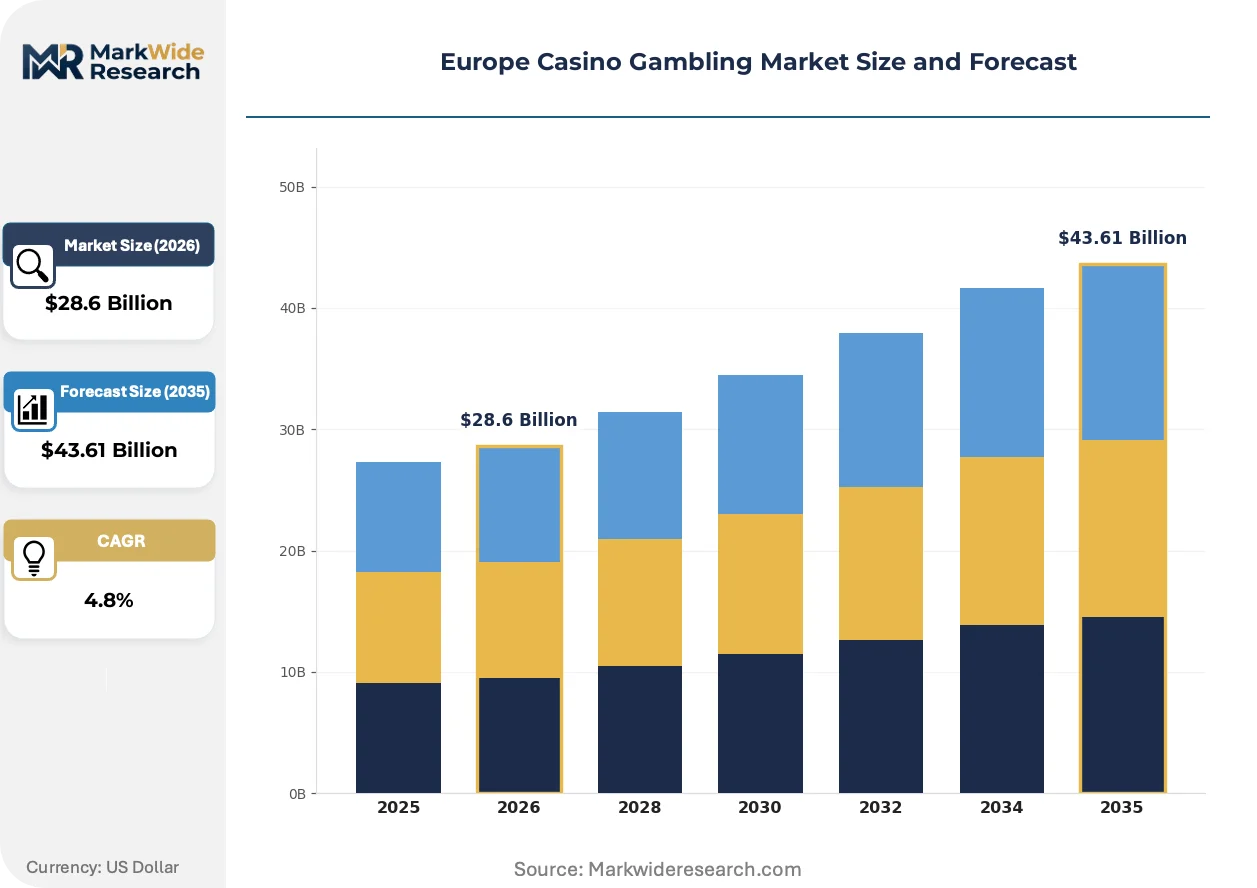
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slot Machines, Table Games, Poker, Bingo End User: Players, Operators, Regulators, Affiliates Distribution Channel: Online Platforms, Brick-and-Mortar, Mobile Apps, Events Game Type: Classic Games, Live Dealer Games, Lottery Games, Skill-Based Games |
| Companies Covered | Groupe Lucien Barrière, Groupe Partouche, Casinos Austria AG, Holland Casino, Rank Group, Entain PLC, Betsson AB, 888 Holdings PLC, Flutter Entertainment PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Casino Gambling Market Trends and Innovations
Algorithmic oversight requirements are fragmenting technology stacks while player protection mandates accelerate investment in transparent, auditable gaming systems across European jurisdictions.
Live dealer infrastructure is modularizing across Baltic and Romanian studio clusters, allowing operators to lease table capacity by the hour rather than building captive broadcast facilities. Mid-tier platforms in Spain and Italy are adopting this model fastest, compressing capital deployment timelines from eighteen months to under ninety days. The shift is displacing traditional studio ownership economics and enabling rapid market testing without fixed asset commitment.
The EU AI Act's risk classification framework for automated decision-making is mandating human review protocols for player deposit-limit algorithms and promotional targeting systems. Operators must now maintain audit trails documenting manual overrides of machine-generated risk scores. France's ANJ and the UK's Gambling Commission are conducting parallel enforcement actions, with the largest digital platforms facing simultaneous compliance reviews across both jurisdictions.
Recreational player segments are fragmenting their engagement across multiple micro-platforms rather than consolidating loyalty with single operators. This pattern is most pronounced in Germany, where strict deposit limits under the Glücksspielneuregulierungsstaatsvertrag have compressed average session values. Smaller specialized apps focusing on single game verticals are capturing churn from full-service platforms, forcing incumbents to unbundle their product suites into standalone branded experiences.
Europe Casino Gambling Market Segmentation
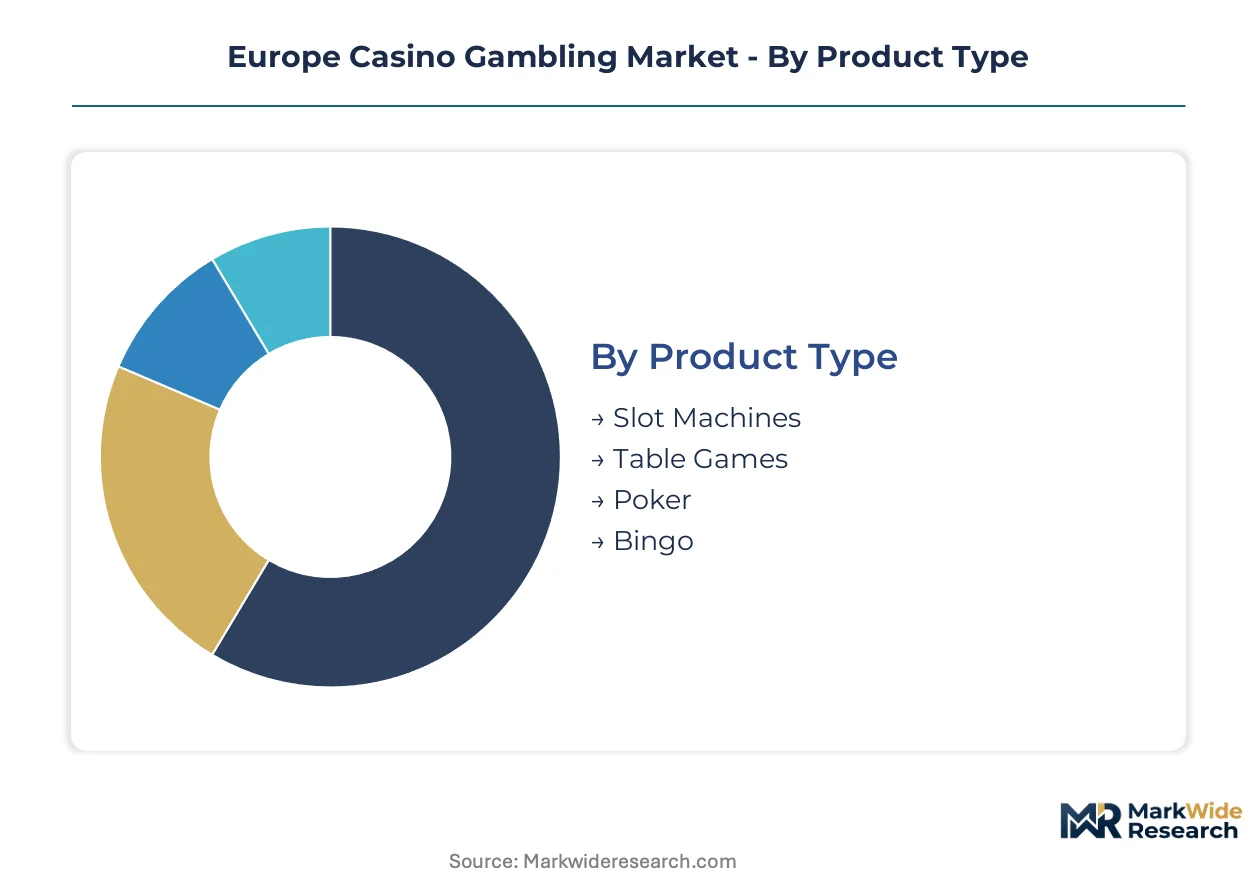
Segmentation in the Europe casino gambling market reveals divergent capital intensity and regulatory exposure across product formats and delivery channels. Operators allocate resources based on margin profiles, compliance burdens, and player acquisition economics that vary sharply between physical and digital deployments.
Product Type:
Technology sophistication and hardware certification requirements differentiate product categories, with electronic gaming machines commanding distinct supply chains from human-dealt alternatives.
- Slot Machines:Electronic gaming terminals with certified random number generators and return-to-player percentages audited by national authorities. Demand concentrates in France and Germany where venue licensing permits high-density floor configurations, though GDPR-compliant player tracking systems raise retrofit costs for legacy estates.
- Table Games:Physical gaming surfaces for roulette, blackjack, and baccarat requiring trained croupiers and pit management infrastructure. Deployment clusters in United Kingdom integrated resorts and Swiss hospitality venues where VIP relationship economics justify higher labor overhead.
- Poker:Card-based skill hybrids operating under distinct regulatory classifications from pure chance games in several jurisdictions.
- Bingo:Number-matching formats with lower per-session stakes and established charitable gaming exemptions in UK and Italian markets.
Mature deployment sits with slot machines. Newer deployment is concentrated in live dealer-adjacent table game formats.
End User:
Stakeholder economics fragment across revenue capture points, with platform providers and regulatory bodies extracting value through divergent mechanisms.
- Players:Recreational and professional gamblers whose deposit patterns and session behaviors trigger divergent compliance protocols under EU AI Act risk classifications. French and British authorities mandate distinct self-exclusion registry participation for high-frequency account holders.
- Operators:Licensed venue owners and digital platform providers bearing direct regulatory liability for anti-money-laundering controls and responsible gaming enforcement. Concentration in Malta, Gibraltar, and UK licensing jurisdictions shapes tax optimization strategies.
- Regulators:National gambling authorities and EU-level bodies imposing technical standards and audit requirements.
- Affiliates:Third-party marketers compensated on player acquisition metrics subject to tightening disclosure rules.
Revenue capture concentrates with operators. Compliance cost burden falls heaviest on player-facing platforms.
Distribution Channel:
Channel selection determines fixed asset exposure and customer acquisition cost structures, with mobile deployment offering lowest entry barriers for new entrants.
- Online Platforms:Browser-based gaming portals serving multiple jurisdictions through shared technical infrastructure. Demand concentrates in Southern and Eastern Europe where broadband penetration supports live dealer streaming from Baltic studio clusters, though payment processor concentration in Nordic banking consortia elevates transaction costs.
- Brick-and-Mortar:Licensed physical venues with taxable gaming floors and hospitality amenities. Regional prefectures in France approve mixed-use complexes bundling conference facilities with gaming operations.
- Mobile Apps:Native applications capturing incremental user growth through app store distribution.
- Events:Temporary gaming installations tied to hospitality or entertainment programming.
Capital deployment runs deepest in brick-and-mortar. User acquisition costs are compressing fastest in mobile apps.
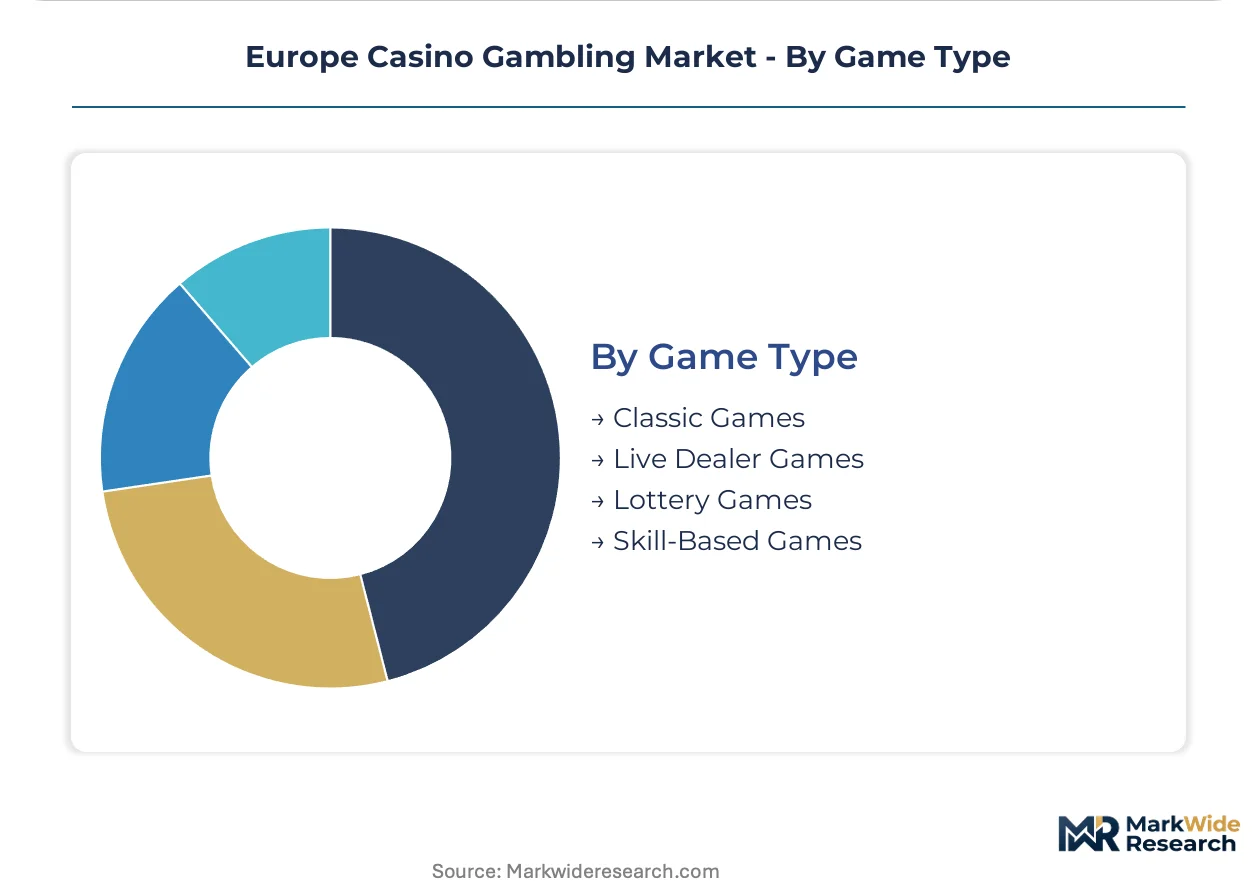
Game Type:
Format selection influences regulatory scrutiny intensity and player protection protocol requirements under divergent national classifications.
- Classic Games:Traditional chance-based formats with established return-to-player benchmarks and long-standing regulatory precedents. Deployment concentrates in German land-based venues operating under Glücksspielneuregulierungsstaatsvertrag deposit limits that compress session economics.
- Live Dealer Games:Real-time streamed table action with human croupiers broadcast from Riga and Bucharest studios. Spanish and Italian mid-tier platforms adopt modular leasing arrangements, reducing capital deployment timelines from eighteen months to under ninety days.
- Lottery Games:State-licensed or state-operated number draws with distinct tax treatment.
- Skill-Based Games:Hybrid formats with partial player influence over outcomes, attracting distinct regulatory classification debates.
Regulatory clarity is strongest for classic games. Technology investment is climbing steepest in live dealer formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riga anchors Europe's live dealer infrastructure, with Bucharest and Baltic studio clusters feeding real-time streams to operators across the continent. These broadcast hubs concentrate technical talent and multilingual croupier pools while reducing per-table economics for mid-tier platforms.
France
Regional prefectures in Provence-Alpes-Côte d'Azur and Île-de-France approve mixed-use integrated resorts bundling conference facilities with gaming floors. ANJ enforcement tightens deposit-limit protocols for high-frequency account holders. Deauville and Cannes hospitality clusters sustain premium VIP relationship economics through heritage real estate assets.
United Kingdom
The Gambling Commission mandates parallel compliance reviews with French regulators for cross-border digital platforms. London's fintech infrastructure supports real-time payment processing despite Nordic banking consortium concentration. Regional betting shop networks in England and Scotland face floor space reconfiguration toward higher-margin electronic gaming terminals.
Germany
Glücksspielneuregulierungsstaatsvertrag deposit limits compress average session values, fragmenting recreational player engagement across multiple micro-platforms. Baden-Württemberg and Bavaria land-based venues retrofit legacy slot protocols for GDPR-compliant player tracking. Stuttgart and Munich integrated resort proposals await regional government approval.
Spain
Dirección General de Ordenación del Juego licensing expands for modular live dealer leasing arrangements from Baltic studios. Barcelona and Madrid digital platforms adopt ninety-day deployment timelines versus eighteen-month captive builds. Andalusian regional authorities test hybrid loyalty architectures linking hospitality and gaming spend.
Italy
Agenzia delle Dogane e dei Monopoli maintains distinct technical standards for random number generation certification, multiplying compliance engineering costs. Milan and Rome mid-tier operators unbundle product suites into standalone branded experiences. Southern regions show underpenetrated mobile adoption relative to northern saturation.
Europe Casino Gambling Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and real estate heritage. The vendor base splits between integrated resort operators with captive hospitality assets and technology-native platforms scaling across borders through shared infrastructure. Three archetypes dominate: heritage French hospitality groups, Nordic-listed digital specialists, and UK-headquartered cross-border sports-betting integrators. M&A activity concentrates on live dealer studio acquisitions and proprietary technology stack consolidation.
Within the heritage hospitality tier, Groupe Lucien Barrière and Groupe Partouche anchor premium real estate-linked gaming across France and Switzerland. Entain PLC and Flutter Entertainment PLC exemplify the technology-native archetype, occupying positions defined by cross-border platform scalability and sports-betting integration into live dealer crossover products. These four entities represent the structural split between physical venue tax compliance and digital customer acquisition economics.
| Leading Market Players |
|---|
| Groupe Lucien Barrière |
| Groupe Partouche |
| Casinos Austria AG |
| Holland Casino |
| Rank Group |
| Entain PLC |
| Betsson AB |
| 888 Holdings PLC |
| Flutter Entertainment PLC |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap operators in France and Switzerland anchor premium pricing through heritage real estate portfolios, while Nordic-listed digital specialists compress margins via shared infrastructure economics. This ownership bifurcation shapes divergent supply chain strategies: hospitality-linked groups prioritize captive floor asset utilization, technology-native platforms optimize server capacity leasing from Baltic studio clusters.
Pricing Analysis
Value-based pricing tied to player lifetime yield governs operator revenue models across European jurisdictions. Three-tier pricing structure across VIP hospitality bundles, standard digital access, and economy mobile tiers differentiates margin capture, with certification grade for responsible gaming compliance emerging as a secondary price driver. Cost compression in mid-tier digital segments is intensifying because modular live dealer leasing erodes captive studio economics. Smaller specialized apps show highest price sensitivity; integrated resort operators with conference bundling demonstrate lowest.
Supply Chain Analysis
Freight cost exposure concentrates in gaming hardware shipments from Germany, Austria, and Italy to venue operators across Southern Europe. Slot machine manufacturing draws from precision electronics suppliers in Taiwan, specialized cabinetry producers in Poland, and certified random number generator component vendors in the United Kingdom. Single-source vulnerability sits with Nordic banking consortia dominating cross-border payment clearing. Distribution runs through licensed platform providers maintaining Malta, Gibraltar, and UK regulatory umbrellas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance costs are forcing a consolidation play, eliminating sub-scale operators unable to fund algorithmic audit infrastructure and human-in-the-loop system rebuilds.
For Market Incumbents: Anchor market position through backward integration into live dealer studio capacity in Riga and Bucharest, securing proprietary broadcast infrastructure against modular leasing erosion. Prioritize GDPR-compliant player tracking retrofits in German land-based estates to preempt enforcement action from regional gambling authorities. Vertical integration into hospitality-linked real estate in Provence-Alpes-Côte d'Azur reinforces premium tier pricing power against digital commoditization. For New Entrants and Emerging Players: Enter via underpenetrated mobile casino adoption in Southern Italy and rural Spain, where broadband penetration now supports live dealer streaming but incumbent platform presence remains thin. Target Romania and Bulgaria digital licensing jurisdictions for lower customer acquisition costs and streamlined compliance pathways. Pursue single-vertical app strategies unbundling poker or bingo from full-service suites to capture churn from deposit-constrained German recreational players. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier digital platforms with modular studio leasing contracts in Spain and Italy, where ninety-day deployment timelines enable rapid market share capture without fixed asset commitment. Long-term viability centers on proprietary technology stack ownership enabling cross-border scalability within EU AI Act constraints. Watch for simultaneous compliance review announcements from France's ANJ and the UK's Gambling Commission as inflection indicators for regulatory enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Live Dealer Studio Acquisition | Captive broadcast infrastructure from Riga clusters reduces per-table economics for mid-tier operators. |
| GDPR Compliance Retrofit | Player tracking system upgrades in German venues preempt regional authority enforcement actions. |
| Hybrid Loyalty Architecture Launch | Blockchain-token convergence with tiered programs enables cross-property redemption between physical and digital channels. |
| Modular Studio Leasing Expansion | Hourly table capacity contracts from Bucharest clusters compress capital deployment timelines to under ninety days. |
| Cross-Border Platform Integration | Shared technical infrastructure serving Malta, Gibraltar, and UK jurisdictions optimizes tax and compliance engineering. |
Research Methodology
Independent corroboration across operator compliance officers, regulatory affairs leads at national gambling authorities, live dealer studio technical directors, and payment processor risk managers underwrites the qualitative findings. Primary interviews with platform engineering heads and hospitality asset managers combined with secondary validation from ANJ enforcement bulletins, UK Gambling Commission compliance reviews, EU AI Act implementation guidance, and customs records of gaming hardware shipments. Bottom-up venue capacity modeling and top-down taxable revenue estimates triangulate market sizing.
Comparable-period anchoring to pre-Glücksspielneuregulierungsstaatsvertrag baseline metrics in Germany and pre-EU AI Act algorithmic deployment patterns across France and the United Kingdom structures the forecast framework. Segmentation dimensions span product type, distribution channel, end user archetype, and regulatory jurisdiction cluster. CAGRs derive from installed base growth rates and average revenue per user trajectories across the projection horizon. Player protection protocol intensity and self-exclusion registry interoperability progress serve as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under simultaneous multi-jurisdiction enforcement actions or payment processor consolidation. Forecasts reflect assumptions regarding regulatory implementation timelines and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Gaming As a Service Market
Gaming
Racing Games Market
Gaming
Europe Serious Gaming Market
Gaming
RPG Games Market
Gaming
Online Casino Market
Gaming
VR Racing Gaming Market
Gaming
VR Gaming Accessories Market
Gaming
Global Tarot Cards Market
Gaming
Mobile Game Controller Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Gaming Software Market
Gaming
China Subscription-Based Gaming Market
Gaming
AAA Games Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
MMORPG Gaming Market
Gaming
Arcade Cabinet Market