
 Mobile Game Controller Market | 2026-2036
Mobile Game Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Game Controller Market Insights
EU RoHS restrictions on hazardous substances in electronics is broadening material compliance requirements across peripheral supply chains. GameSir leverages in-house firmware development to sustain low-latency wireless performance. Razer anchors premium positioning through chroma lighting ecosystems and tournament-grade components. SteelSeries competes across multiple connectivity standards while maintaining cross-platform compatibility.
A mobile game controller is a handheld input device engineered with tactile switches, analog thumbsticks, and accelerometer arrays to translate physical gestures into digital commands for smartphone and tablet gaming. Manufacturing integrates injection-molded ABS housings with membrane or mechanical actuation layers to achieve sub-20 millisecond input lag thresholds. Wireless controllers lead volume shipments as Bluetooth 5.3 and USB-C protocols displace legacy wired configurations across mid-tier and premium tiers. The competitive gamer segment commands disproportionate margin pools due to willingness to pay for customizable button mapping and force-feedback haptics. Ergonomic design features represent a maturing baseline rather than a differentiator, with touch sensitivity modules emerging as the fastest-growing capability category.
FCC Part 15 emissions standards govern wireless controller certification in the United States, while CE marking under EU RED Directive mandates radio equipment conformity across European member states. China's MIIT enforces SRRC certification for Bluetooth and Wi-Fi enabled devices entering domestic channels, creating segmented compliance pathways. Stakeholders must monitor evolving battery transportation regulations and right-to-repair legislative momentum that could mandate modular controller architectures and standardized component access.
Market Dynamics
Bluetooth Low Energy and haptic feedback engineering are compressing input lag thresholds below 20 milliseconds, forcing manufacturers to redesign analog actuation layers and wireless protocol stacks to retain competitive positioning among eSports-grade peripherals.
Growth Catalysts
- EU RoHS hazardous substance restrictions:Material compliance mandates are accelerating substitution of lead-based solder and brominated flame retardants in ABS housing production, creating upgrade cycles across peripheral supply chains.
- Competitive gamer willingness-to-pay:Tournament-grade component demand concentrates margin pools around customizable button mapping and force-feedback haptic modules, sustaining premium tier expansion.
- China MIIT SRRC certification pathway:Domestic channel enforcement for Bluetooth-enabled devices is standardizing radio equipment conformity testing, reducing market fragmentation for certified entrants.
Market Restraints
- Injection-molded ABS resin cost volatility:Petrochemical feedstock price swings compress gross margins for housing manufacturers locked into annual supply contracts.
- Touch sensitivity module supply concentration:Capacitive sensor fabrication clusters in South Korean and Taiwanese foundries create single-source vulnerability for force-feedback integration.
- FCC Part 15 emissions certification timeline:Wireless protocol validation delays average 14-22 weeks, extending product launch windows and freezing working capital in pre-certified inventory.
Strategic Opportunities
- India BIS electronics standard adoption:Mandatory certification for wireless peripherals creates first-mover advantage for brands establishing local testing partnerships ahead of enforcement expansion.
- Cloud gaming service integration:Controller-as-a-service bundling with Microsoft xCloud and NVIDIA GeForce NOW subscriptions opens recurring revenue models beyond hardware monetization.
- Right-to-repair legislative momentum:Proposed EU and US state-level mandates for modular component access would reward standardized screw patterns and swappable thumbstick assemblies with regulatory preference.
Industry Challenges
- Firmware engineering talent scarcity:Low-latency wireless stack optimization requires specialized Bluetooth 5.3 protocol expertise concentrated among semiconductor vendor ecosystems, inflating compensation premiums.
- Cross-platform compatibility testing burden:Validation across iOS, Android, and emerging handheld console operating systems fragments QA resources and extends certification cycles.
- Battery transportation regulation compliance:UN 38.3 lithium-ion cell testing and IATA air freight restrictions add documentation overhead and geographic routing complexity to fulfillment operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Game Controller Market |
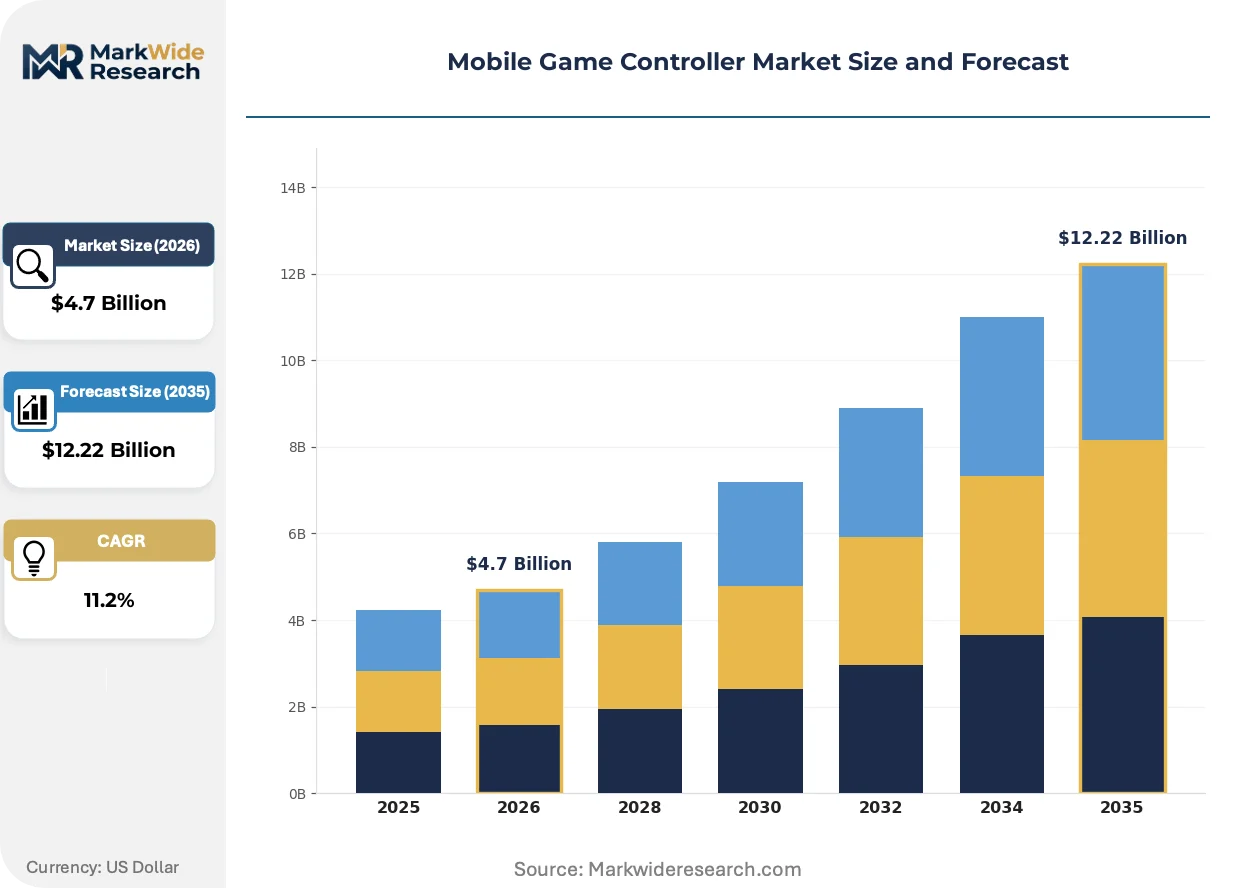
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.22 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Controllers, Wireless Controllers, Gamepads, Joysticks Connectivity: Bluetooth, USB-C, Wi-Fi, Proprietary End User: Casual Gamers, Competitive Gamers, Professional eSports Players, Game Developers Feature: Touch Sensitivity, Haptic Feedback, Customizable Buttons, Ergonomic Design |
| Companies Covered | GameSir, Razer, SteelSeries, Flydigi, IPEGA, Backbone, Betop, Gamevice, Turtle Beach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Game Controller Market Trends and Innovations
Controller architecture is bifurcating between ultra-low-latency tournament specifications and mass-market ergonomic baselines, with sensor fusion and adaptive trigger mechanisms emerging as the primary vectors of hardware differentiation.
Hall-effect magnetic sensors are overtaking carbon-based potentiometer thumbsticks in premium tier designs. These contactless position encoders eliminate drift degradation common in competitive gaming environments. eSports tournament organizers are mandating Hall-effect certification for official peripherals. The technology is overtaking legacy analog modules by enabling multi-million-cycle durability guarantees that compress total cost of ownership for professional players.
EU F-Gas Regulation phase-down schedules are pressuring refrigerant-dependent thermal management in high-performance controller charging docks. Manufacturers are substituting vapor chamber and graphene spreader solutions for compressor-based cooling. The regulation is compressing design cycles for dock accessories sold through European retail channels, with compliance deadlines accelerating R&D resource allocation toward passive thermal architectures.
Direct-to-consumer channel expansion is fragmenting traditional electronics retail dependency. Specialty gaming peripheral brands are bypassing distributor markups through TikTok Shop and YouTube creator affiliate ecosystems. China and Southeast Asian markets exhibit the steepest channel shift velocity, with live-commerce conversion rates for controller accessories exceeding legacy e-commerce benchmarks by substantial margins in tier-one city clusters.
Mobile Game Controller Market Segmentation
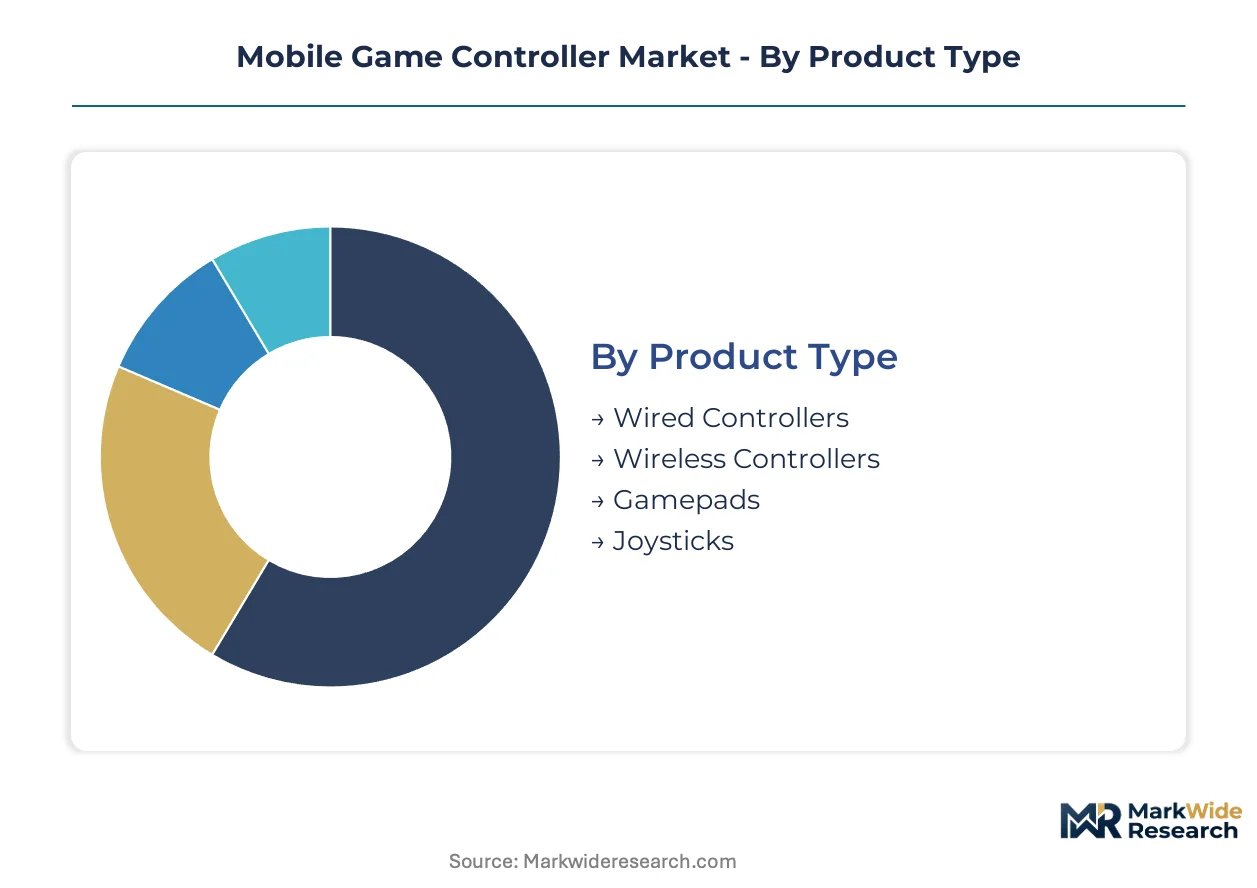
Controller architecture fragments across connectivity protocols, user sophistication tiers, and sensory capability stacks. Each segmentation axis carries distinct margin profiles and certification burdens that reshape supplier positioning. Manufacturers must align R&D allocation with the specific performance thresholds and compliance pathways governing each category.
Product Type:
Supply concentration for analog actuation modules and wireless protocol stacks varies sharply across housing form factors, compressing margins for categories dependent on shared component ecosystems.
- Wireless Controllers:Bluetooth 5.3 and USB-C protocol integration enables sub-20 millisecond input lag thresholds. Demand concentrates among competitive gamers in China and South Korea where tournament infrastructure mandates low-latency peripherals. FCC Part 15 certification timelines average 14-22 weeks, freezing working capital in pre-certified inventory.
- Wired Controllers:Legacy USB-A configurations retain cost advantages in emerging markets with limited wireless infrastructure penetration. Procurement concentrates in India and Southeast Asian tier-two cities where BIS electronics standard adoption is accelerating compliance requirements for certified entrants.
- Gamepads:Clamshell designs with integrated phone mounts dominate mass-market volume shipments through direct-to-consumer channels.
- Joysticks:Arcade-style lever mechanisms serve retro gaming and flight simulation niches with specialized tactile feedback requirements.
Today's leader: Wireless Controllers. Tomorrow's challenger: Gamepads.
Connectivity:
Protocol selection determines geographic market access through divergent certification pathways and radio equipment conformity mandates.
- Bluetooth:Low Energy 5.3 stacks deliver the responsiveness benchmarks eSports tournament organizers now mandate for official peripherals. Component sourcing clusters around semiconductor vendors with specialized firmware engineering talent, inflating compensation premiums for low-latency optimization expertise.
- USB-C:Universal charging compatibility and audio passthrough integration anchor mid-tier positioning across iOS and Android ecosystems. Adoption accelerates in European retail channels where CE marking under EU RED Directive standardizes conformity testing.
- Wi-Fi:Direct connection protocols reduce intermediary latency for cloud gaming service integration with Microsoft xCloud and NVIDIA GeForce NOW.
- Proprietary:Vendor-locked radio stacks enable ecosystem capture but fragment cross-platform compatibility testing resources.
Bluetooth anchors current volume. USB-C gains share fastest as mid-tier manufacturers consolidate around universal standards.
End User:
Willingness-to-pay gradients across gamer sophistication tiers concentrate margin pools in segments demanding tournament-grade component specifications.
- Competitive Gamers:Customizable button mapping and force-feedback haptic modules command premium pricing. Hall-effect magnetic sensor adoption eliminates drift degradation, with tournament organizers mandating certification for official peripherals. Procurement concentrates in the United States and South Korea where eSports prize pools sustain professional hardware investment cycles.
- Casual Gamers:Ergonomic baselines and price accessibility drive purchasing decisions in mass-market channels. Demand clusters in China and India where mobile gaming infrastructure maturation outpaces peripheral penetration rates.
- Professional eSports Players:Multi-million-cycle durability guarantees and sub-10 millisecond input lag specifications define procurement criteria.
- Game Developers:Debug and testing configurations require protocol analyzer compatibility and firmware access layers.
Competitive Gamers dominate margin capture. Professional eSports Players represent the steepest expansion trajectory as tournament prize pools compound.
Feature:
Capability modularization enables tiered pricing stratification across sensory enhancement and physical customization vectors.
- Haptic Feedback:Force-feedback actuators and adaptive trigger mechanisms differentiate premium tier positioning. Engineering talent scarcity for low-latency wireless stack optimization concentrates among semiconductor vendor ecosystems, constraining supplier expansion.
- Touch Sensitivity:Capacitive sensor modules integrate pressure-responsive input layers for gesture-based control schemes. Fabrication clusters in South Korean and Taiwanese foundries create single-source vulnerability for force-feedback integration.
- Customizable Buttons:Remappable actuation layers and interchangeable faceplates serve competitive gamer workflow preferences.
- Ergonomic Design:Injection-molded ABS housing geometries with textured grip surfaces have matured from differentiator to baseline expectation.
Haptic Feedback commands premium positioning. Touch Sensitivity climbs fastest as sensor fusion architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The mobile game controller industry traces its commercial origins to Japanese arcade peripheral manufacturers and South Korean eSports equipment fabricators who pioneered low-latency wireless protocols for competitive gaming environments.
United States
FCC Part 15 emissions certification governs wireless controller market access with 14-22 week validation timelines freezing working capital in pre-certified inventory. Tournament prize pools in Los Angeles and Atlanta sustain professional hardware investment cycles among competitive gamers. Seattle and Austin host cloud gaming service integration hubs where controller-as-a-service bundling with Microsoft xCloud and NVIDIA GeForce NOW subscriptions opens recurring revenue models.
China
MIIT SRRC certification for Bluetooth-enabled devices standardizes radio equipment conformity testing, reducing market fragmentation for certified entrants. Domestic demand concentrates in Shenzhen and Dongguan where injection-molded ABS housing production clusters around petrochemical feedstock suppliers. Shanghai and Beijing anchor eSports tournament infrastructure that mandates low-latency peripherals for official competition use.
South Korea
MFDS-equivalent radio equipment standards and national eSports association procurement criteria drive tournament-grade component specifications. Seoul and Busan host professional gaming leagues where Hall-effect magnetic sensor certification is becoming mandatory for official peripherals. Incheon houses capacitive sensor fabrication foundries that supply force-feedback integration modules to global peripheral manufacturers.
Germany
CE marking under EU RED Directive mandates radio equipment conformity across European member states, with RoHS hazardous substance restrictions accelerating substitution of lead-based solder in ABS housing production. Berlin and Munich anchor premium peripheral distribution through specialized gaming retail channels. Hamburg serves as the primary logistics hub for EU F-Gas Regulation-compliant thermal management solutions in controller charging dock accessories.
India
BIS electronics standard adoption for wireless peripherals creates first-mover advantage for brands establishing local testing partnerships ahead of enforcement expansion. Demand clusters in Mumbai and Bengaluru where mobile gaming infrastructure maturation outpaces peripheral penetration rates. Delhi-NCR hosts emerging direct-to-consumer channel operations through TikTok Shop and YouTube creator affiliate ecosystems.
Mobile Game Controller Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the mobile game controller value chain, with injection-molded ABS housing manufacturers and semiconductor firmware developers occupying distinct risk-return profiles. The vendor base stratifies into three tiers: integrated peripheral brands controlling wireless protocol stacks, specialized haptic feedback engineering houses, and contract assemblers serving private-label retail channels. Dominant competitive moves include strategic partnerships with cloud gaming service platforms and geographic expansion through direct-to-consumer channel infrastructure.
Among Asia-Pacific-based peripheral specialists, GameSir exemplifies the in-house firmware development archetype, while Razer and SteelSeries anchor premium-tier positioning through chroma lighting ecosystems and cross-platform compatibility standardization. These three companies represent contrasting strategic postures: captive wireless optimization expertise, ecosystem-driven brand premiumization, and multi-protocol interoperability engineering.
| Leading Market Players |
|---|
| GameSir |
| Razer |
| SteelSeries |
| Flydigi |
| IPEGA |
| Backbone |
| Betop |
| Gamevice |
| Turtle Beach |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock volatility in ABS resin markets cascades through injection-molded housing costs into three-tier pricing stratification across premium tournament-grade, standard mid-tier, and economy entry-level controller segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the mobile game controller market. Premium tiers capture margin through Hall-effect magnetic sensor certification and force-feedback haptic modules demanded by competitive gamers. Price differentiation stems from component certification grade and customization depth. Cost compression in economy tiers is intensifying because of ABS resin contract volatility. Casual gamers in emerging markets exhibit highest price sensitivity; professional eSports players show least elasticity.
Supply Chain Analysis
Direct-to-consumer channels through TikTok Shop and creator affiliate ecosystems now handle volume shipments previously routed through electronics distributors. Component sourcing draws from South Korean and Taiwanese foundries for capacitive sensors, Chinese injection-molding clusters for ABS housings, and German precision engineering for analog actuation modules. Single-source vulnerability in touch sensitivity module fabrication creates supply chain risk. Distribution runs through direct-to-consumer platforms fastest in China and Southeast Asian tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile game controller market compounds steadily as cloud gaming infrastructure expands and tournament-grade peripheral demand concentrates margin pools around low-latency wireless expertise.
For Market Incumbents: Anchor premium positioning through captive firmware development capabilities that sustain sub-20 millisecond input lag thresholds. Deepen backward integration into Hall-effect magnetic sensor supply chains to secure tournament certification mandates. Defend against direct-to-consumer channel disruption by building proprietary creator affiliate ecosystems in China and Southeast Asia.
For New Entrants and Emerging Players: Bluetooth 5.3 protocol optimization expertise offers a technology-first wedge into mid-tier wireless controller segments underserved by established firmware engineering houses. Target India's BIS certification pathway ahead of enforcement expansion for first-mover regulatory positioning. Pursue cloud gaming service bundling partnerships as the primary go-to-market angle for recurring revenue capture.
For Investors and Strategic Acquirers: Roll-up economics work for specialized haptic feedback engineering houses because firmware talent scarcity concentrates pricing power among semiconductor vendor ecosystems. Five-to-ten year viability hinges on cloud gaming platform integration depth. Watch for right-to-repair legislative passage in EU member states as the signal indicating modular controller architecture mandates will reward standardized component access investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Talent Acquisition | Captive Bluetooth 5.3 expertise secures tournament-grade certification mandates from eSports organizers. |
| Hall-Effect Sensor Integration | Contactless thumbstick modules eliminate drift degradation and compress total cost of ownership for professional players. |
| Cloud Gaming Platform Partnership | Controller-as-a-service bundling with Microsoft xCloud and NVIDIA GeForce NOW opens recurring revenue streams beyond hardware monetization. |
| Direct-to-Consumer Channel Buildout | TikTok Shop and YouTube creator affiliate ecosystems bypass distributor markups in China and Southeast Asian tier-one cities. |
| Right-to-Repair Compliance Investment | Modular architectures with standardized screw patterns and swappable thumbstick assemblies secure regulatory preference under proposed EU mandates. |
Research Methodology
Multiple input streams — primary interviews with peripheral engineering directors, eSports tournament organizers, and electronics procurement managers; secondary validation through FCC certification databases, MIIT SRRC filings, and customs trade records; plus bottom-up manufacturer shipment triangulation against top-down gaming hardware spend estimates — were reconciled to construct market sizing.
Data-stream reconciliation across connectivity protocol, user sophistication tier, and sensory capability segmentation dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from installed base growth curves and replacement cycle compression in competitive gaming segments. Forecast inputs incorporated cloud gaming subscriber penetration rates and tournament infrastructure investment pipelines.
The model holds under stable Bluetooth protocol evolution and continued eSports prize pool expansion; deviation in right-to-repair legislative timelines or lithium-ion transportation regulation severity would shift replacement cycle assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global Subscription-Based Gaming Market
Gaming
MMORPG Gaming Market
Gaming
Advanced Digital Gaming Market
Gaming
South Asia Mobile Gaming Market
Gaming
Playstation Network (PSN) Market
Gaming
Mobile MOBA Games Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
Racing Games Market
Gaming
Gaming Software Market
Gaming
Arcade Games Market
Gaming
North America Gaming Market
Gaming
Console Games Market
Gaming
China Subscription-Based Gaming Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Global Esports Market
Gaming
Connected Game Console Market