
 RPG Games Market | 2026-2036
RPG Games Market Size, Share, and Industry Trends Forecast 2026-2036
RPG Games Market Insights
Mobile esports viewership is pivoting toward RPG-adjacent competitive formats, drawing publishers toward cross-platform development. Nintendo leverages its first-party hardware-software integration to sustain premium pricing for fantasy RPG franchises. Square Enix anchors its portfolio in narrative-driven single-player experiences that command full-price retail. NetEase Games competes through aggressive localization for Western multiplayer markets.
Role-playing games constitute interactive software where players assume character identities within persistent narrative frameworks, typically featuring progression systems built on experience points, skill trees, and inventory management across play sessions spanning 20 to 100+ hours. Their commercial purpose centers on maximizing lifetime player value through emotional narrative investment and ongoing content retention mechanics. Mobile monetization now leads revenue generation through gacha mechanics and battle pass structures, while PC and console platforms retain the highest per-user spend through one-time purchases and premium DLC. Fantasy genre titles occupy the largest development budget share, though sci-fi RPGs are gaining fastest among North American and European audiences seeking immersive sim alternatives.
ESRB ratings in the United States, PEGI classifications across European Union member states, and China's NPPA approval requirements collectively shape content boundaries, age-gating mechanics, and release timelines for international publishers. Japan's CERO system adds further compliance layers for domestic distribution, particularly regarding gambling-adjacent gacha systems. Stakeholders must monitor evolving loot box legislation in Germany and the United Kingdom, where consumer protection agencies are scrutinizing randomized reward mechanics as potential regulatory flashpoints.
Market Dynamics
Cloud gaming infrastructure and 5G rollouts are removing hardware barriers to entry, fundamentally reshaping how players access RPG experiences across device ecosystems. This technological shift is expanding the addressable player base beyond traditional console and PC ownership.
Growth Catalysts
- Mobile-first demographics:Southeast Asia's expanding smartphone penetration is creating new player cohorts previously excluded by hardware costs.
- Cross-platform development:Publishers are converging mobile, PC, and console experiences to capture fragmented attention spans across device types.
- Gacha monetization frameworks:Japan's CERO-compliant loot box mechanics have established regulatory precedents enabling sustainable free-to-play revenue models.
Market Restraints
- Input cost volatility:Talent acquisition for narrative design and live-service engineering commands premium compensation in Tokyo and Seoul development clusters.
- Regulatory friction:Germany's evolving consumer protection scrutiny of randomized reward mechanics creates compliance uncertainty for gacha-dependent publishers.
- Technical limitation:Latency constraints in cloud gaming infrastructure degrade real-time multiplayer RPG responsiveness in bandwidth-constrained markets.
Strategic Opportunities
- Underpenetrated geography:India's emerging mobile gaming audience represents whitespace for localized RPG content with regional mythological IP.
- Technology convergence:AI-assisted procedural narrative generation is converging with traditional hand-crafted storytelling to compress development timelines.
- Distribution innovation:TikTok and YouTube Shorts are emerging as primary discovery channels displacing traditional platform storefront curation.
Industry Challenges
- Skill scarcity:Live-service operations expertise remains concentrated among Seoul and Shanghai studios, creating talent pipeline bottlenecks for Western publishers.
- Certification complexity:China's NPPA approval timelines extend 12-18 months for foreign titles, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RPG Games Market |
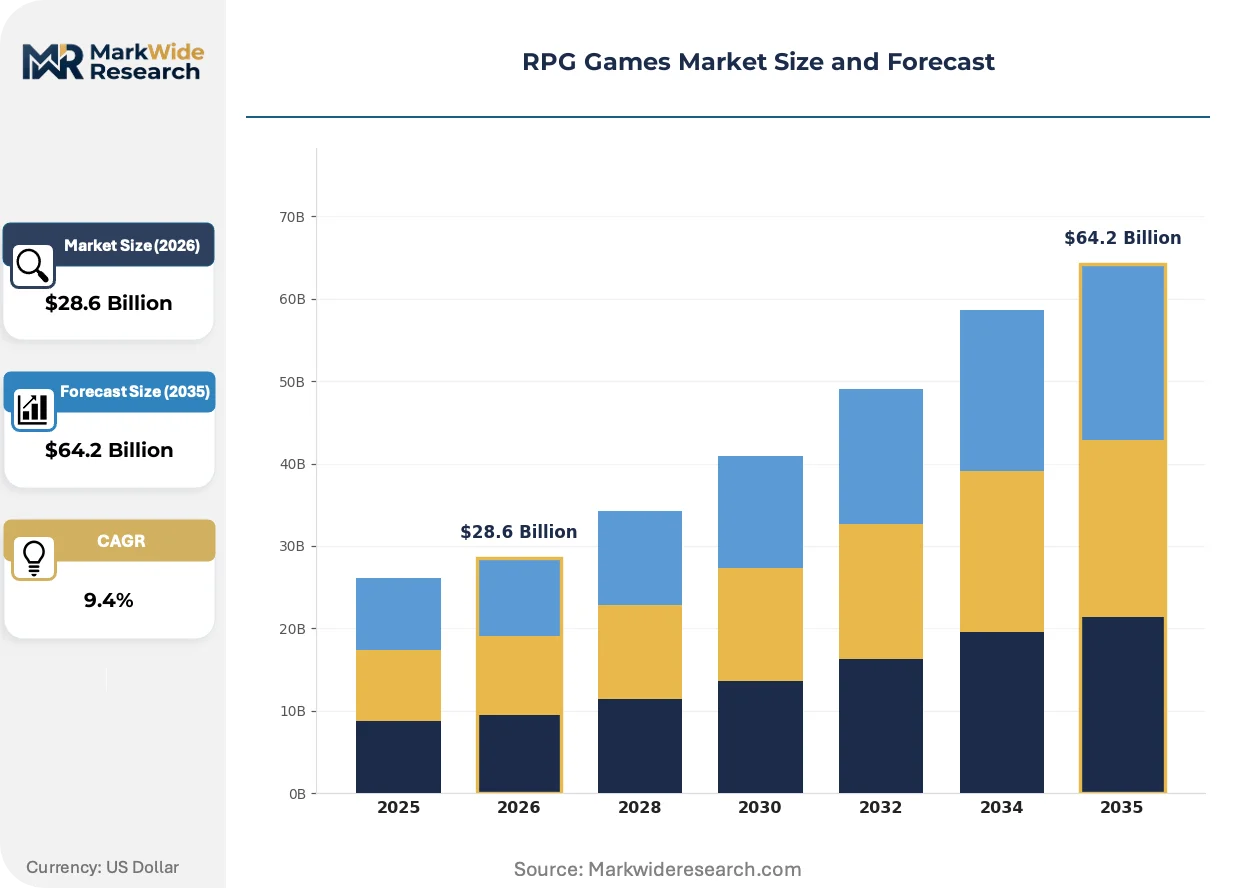
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: PC, Console, Mobile, Cloud Gameplay Mode: Single-player, Multiplayer, Co-op, Online Genre: Fantasy, Sci-Fi, Historical, Horror Monetization Model: Free-to-play, Subscription, One-time Purchase, DLC |
| Companies Covered | Nintendo, Electronic Arts, Square Enix, Nexon, NetEase Games, Bethesda Softworks, Sony Interactive Entertainment, Take-Two Interactive, Capcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RPG Games Market Trends and Innovations
Generative AI tools are compressing asset production pipelines while blockchain-based ownership models are fragmenting traditional publisher-player economic relationships. These forces are reshaping how RPG content is created, distributed, and monetized.
Procedural narrative generation is decentralizing content creation authority away from centralized writing teams toward algorithmic systems that adapt quest structures to individual player behavior. Mid-size studios in Poland and Sweden are adopting these tools most aggressively to compete with Japanese and Korean narrative production scale. The technology is decentralizing the historical concentration of storytelling expertise within Tokyo and Osaka development houses.
The United Kingdom's Gambling Commission and Advertising Standards Authority are tightening disclosure requirements for loot box mechanics, forcing publishers to implement probability transparency overlays and spending limit tools. This regulatory pressure is accelerating the pivot toward battle pass and cosmetic-only monetization in titles targeting British and European audiences. Premium single-player RPGs with fixed-price models are gaining relative competitive positioning against gacha-dependent live-service competitors in these jurisdictions.
Player acquisition through short-form video platforms is displacing traditional paid advertising and platform feature placement as the dominant user growth channel. Southeast Asian mobile RPG publishers are reallocating 60-70% of marketing spend toward TikTok creator partnerships and playable ad units. Indonesia and Vietnam represent the most advanced adoption curves, where influencer-driven discovery now determines launch week performance more than App Store algorithmic positioning.
RPG Games Market Segmentation
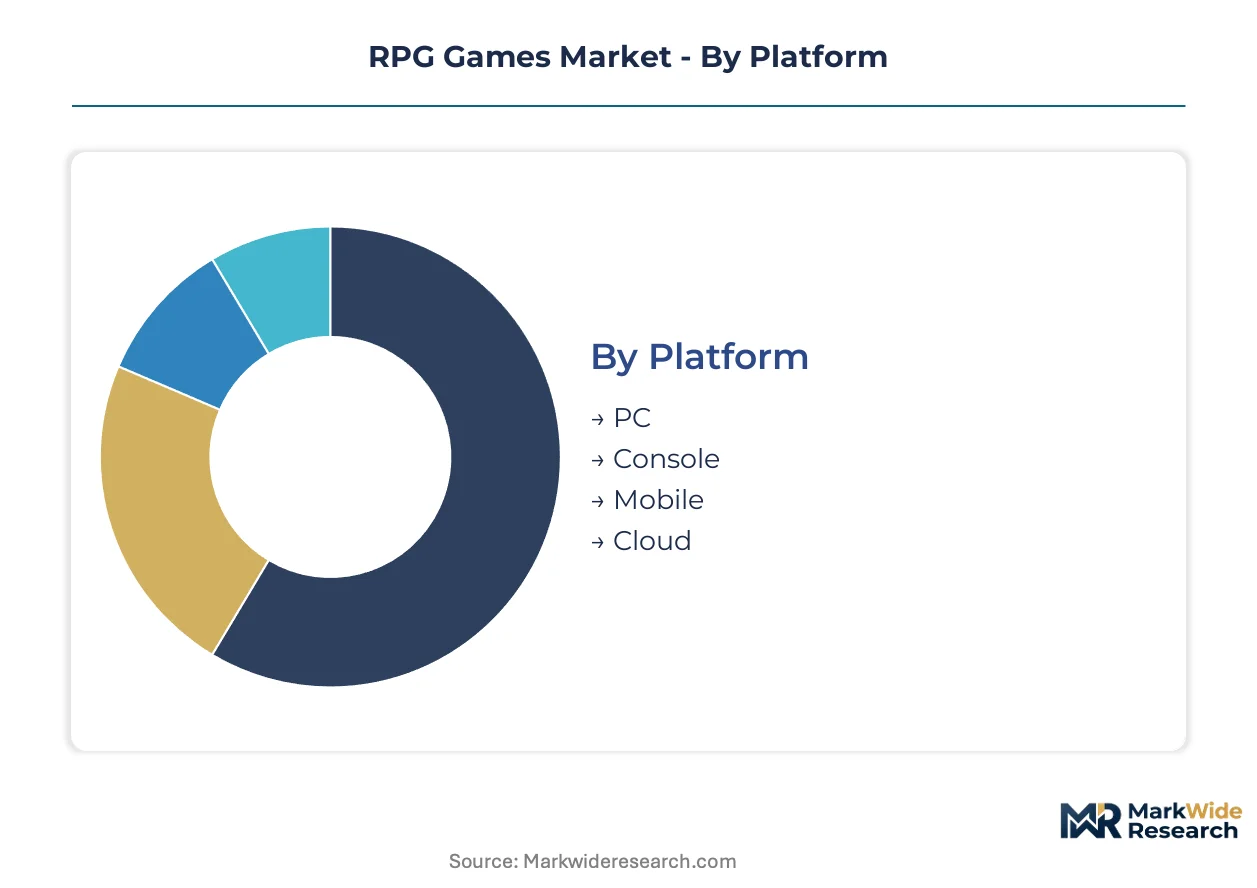
RPG market segmentation reveals how platform economics, social mechanics, thematic preferences, and pricing psychology fragment player spending across distinct value pools. Publishers configure development resources against these dimensions to optimize lifetime revenue per cohort.
Platform:
Hardware ownership costs and accessibility determine where publishers concentrate development budgets and marketing firepower.
- PC:Open architecture enables modding ecosystems and direct-to-consumer storefront relationships. Steam's regional pricing tiers unlock emerging market penetration that console hardware cannot match, though anti-cheat requirements complicate multiplayer architecture.
- Console:First-party hardware-software integration sustains premium pricing for narrative-driven franchises. Sony and Nintendo certification processes add 6-12 month lead times that compress revenue recognition windows for seasonal release strategies.
- Mobile:Touch-optimized interfaces and gacha monetization dominate Southeast Asian revenue generation. India's sub-$200 smartphone penetration creates whitespace for localized RPG content with compressed asset requirements.
- Cloud:Latency-sensitive combat systems degrade on 5G infrastructure in bandwidth-constrained markets. Microsoft's xCloud and NVIDIA's GeForce NOW are expanding addressable audiences beyond traditional hardware ownership.
Volume sits with Mobile; growth tilts toward Cloud.
Gameplay Mode:
Social interaction intensity shapes content production costs, server infrastructure requirements, and retention mechanic design.
- Single-player:Hand-crafted narrative arcs command full-price retail in Japan's legacy RPG ecosystem. Square Enix and FromSoftware anchor portfolios here, with 40-80 hour campaigns justifying premium positioning.
- Multiplayer:Live-service operations demand continuous content pipelines and anti-cheat infrastructure. Seoul and Shanghai studios concentrate expertise here, creating talent acquisition bottlenecks for Western publishers.
- Co-op:Session-based progression systems balance narrative investment with social obligation mechanics. Monster Hunter's drop-in structure demonstrates scalable retention without persistent world costs.
- Online:Persistent world architecture requires regional server deployment and localized customer support. NetEase and Tencent dominate operational scale here.
Revenue concentrates in Multiplayer; player preference is shifting fastest toward Co-op.
Genre:
Thematic positioning determines art pipeline costs, voice acting requirements, and licensing opportunities for established IP.
- Fantasy:Medieval European and East Asian mythologies occupy the largest development budget share. Magic systems and bestiary design require extensive concept art pipelines that Polish and Swedish mid-size studios are compressing through AI-assisted generation.
- Sci-Fi:Immersive sim alternatives are gaining fastest among North American and European audiences seeking systemic narrative emergence. Starfield and Cyberpunk demonstrate demand for branching quest architectures.
- Historical:Period accuracy demands consulting relationships and archival research that extend pre-production timelines. Assassin's Creed's educational mode illustrates ancillary revenue potential.
- Horror:Audio design and lighting systems drive atmospheric tension with compressed asset requirements. Resident Evil's remake strategy demonstrates premium pricing power for nostalgia-driven releases.
Development investment clusters in Fantasy; audience expansion is steepest in Sci-Fi.
Monetization Model:
Player payment psychology and regulatory scrutiny determine revenue stability and geographic addressability.
- Free-to-play:Gacha mechanics and battle pass structures dominate Southeast Asian mobile revenue. Germany's consumer protection scrutiny of randomized rewards is accelerating probability transparency requirements.
- Subscription:Xbox Game Pass and PlayStation Plus are consolidating discovery and retention for catalog depth. Microsoft's Bethesda acquisition demonstrates first-party content leverage for service differentiation.
- One-time Purchase:Fixed-price models gain competitive positioning against gacha-dependent competitors in British and European jurisdictions. Nintendo's premium pricing sustainability relies on hardware-software integration.
- DLC:Expansion packs and cosmetic microtransactions extend lifetime value for established player bases. FromSoftware's Shadow of the Erdtree demonstrates pricing power for narrative extensions.
Revenue generation concentrates in Free-to-play; regulatory pressure is forcing fastest adaptation in Subscription bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Tokyo-Osaka corridor anchors global RPG development through METI-backed content production zones and consolidated studio networks. South Korea's Pangyo Techno Valley drives live-service MMO operations with Gyeonggi Province tax incentives. China's Shanghai Free-Trade Zone accelerates foreign publisher licensing through streamlined NPPA approval pathways.
United States
California's Silicon Valley and Washington state's Seattle-Tacoma corridor concentrate single-player narrative development and cloud gaming infrastructure investment. The FTC scrutinizes platform exclusivity arrangements under antitrust frameworks. Austin, Texas hosts expanding live-service operations studios competing for engineering talent with West Coast clusters.
Japan
Tokyo's Shibuya and Osaka's Umeda districts sustain premium single-player RPG production through CERO-compliant monetization frameworks. METI's Cool Japan initiative subsidizes cultural IP export. Kyoto-based Nintendo leverages hardware-software integration to maintain pricing power for fantasy franchises.
South Korea
Seoul's Gangnam and Pangyo districts dominate live-service MMO operations through aggressive 5G infrastructure deployment. The Korea Creative Content Agency funds regional mythological IP localization. Busan's G-Star exhibition anchors annual publisher distribution negotiations.
China
Shanghai's Pudong district and Shenzhen's Nanshan district concentrate mobile RPG publishing through NPPA licensing frameworks. Guangdong Province's software industry tax incentives attract foreign joint ventures. Hangzhou's Alibaba ecosystem drives short-form video player acquisition.
RPG Games Market Competitive Landscape
Top-tier vendors anchor premium single-player and first-party hardware-integrated segments, while mid-tier studios compete through live-service operations and regional localization. The vendor base fragments across platform-specific optimization requirements and regulatory compliance specializations. Two strategic archetypes dominate: integrated hardware-software platforms and cross-platform live-service operators. Competitive moves concentrate on exclusive IP acquisition and cloud infrastructure partnerships.
Within the integrated platform tier, Nintendo and Sony Interactive Entertainment occupy positions sustained by hardware-software synergy. Square Enix exemplifies the narrative-driven single-player archetype through Tokyo-based production clusters. NetEase Games represents aggressive Western market localization strategies among Asia-Pacific publishers.
| Leading Market Players |
|---|
| Nintendo |
| Electronic Arts |
| Square Enix |
| Nexon |
| NetEase Games |
| Bethesda Softworks |
| Sony Interactive Entertainment |
| Take-Two Interactive |
| Capcom |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between CERO-compliant premium releases and free-to-play mobile titles manifests in pricing power concentrated among Tokyo-Osaka studios with hardware-software integration, while supply chain configurations fragment across cloud infrastructure providers and regional server deployment clusters. This bifurcation rewards first-party platform holders with sustained premium positioning while compressing margins for cross-platform live-service operators dependent on bandwidth-constrained emerging markets.
Pricing Analysis
Short lead-time certification for first-party Nintendo and Sony releases commands full-price retail positioning, while spot inventory clearance through seasonal Steam sales and mobile gacha soft-launches discount access for price-sensitive cohorts. Pricing stratifies across premium single-player narrative arcs, standard multiplayer live-service tiers, and economy free-to-play entry points. Price differentiation hinges on CERO compliance overhead and voice acting localization depth. Pricing pressure stems from talent acquisition costs in Seoul and Shanghai engineering clusters. Southeast Asian mobile-first players exhibit highest price sensitivity; Japanese console enthusiasts demonstrate lowest.
Supply Chain Analysis
Direct-to-consumer storefront channels handle hyperscale demand through Steam's regional pricing infrastructure and mobile platform holder commission structures. Geographic supply concentration centers on Japan's Tokyo-Osaka corridor for narrative production, South Korea's Pangyo Techno Valley for live-service engineering, and China's Shanghai-Shenzhen axis for mobile publishing operations. Raw material dependencies include cloud compute capacity from AWS and Azure, 5G infrastructure deployment from Huawei and Ericsson, and graphics engine licensing from Epic and Unity. Supply chain risk concentrates in single-source vulnerability for live-service talent pipelines. Distribution runs through platform holder certification processes and short-form video discovery algorithms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RPG market functions as a vertical-integration race where cloud infrastructure control and first-party hardware-software synergy represent the decisive upstream and downstream levers. Publishers must secure captive distribution channels and proprietary engine technology to defend margin structures.
For Market Incumbents: Deepen exclusive IP acquisition in fantasy and sci-fi narrative franchises to lock out subscription service competitors. Fortify live-service engineering capacity through captive Seoul studio networks or acquisition of Shanghai operations expertise. Regulatory scrutiny of gacha mechanics in Germany and the United Kingdom threatens monetization stability; accelerate battle pass and cosmetic-only pivot for European jurisdiction compliance.
For New Entrants and Emerging Players: AI-assisted procedural narrative generation offers technology-first wedge into mid-tier development cost structures dominated by Polish and Swedish studios. India's sub-$200 smartphone penetration represents the most penetrable geography for regional mythological IP localization. Go-to-market execution should prioritize TikTok creator partnership channels over traditional platform storefront algorithmic positioning.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-tier studios possessing live-service operational expertise given cloud gaming infrastructure rollout acceleration. Long-term viability across the analysis window favors publishers with diversified platform presence and regulatory compliance specializations. Signal to watch: NPPA approval timeline compression for foreign titles entering China's Shanghai Free-Trade Zone licensing pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive IP Acquisition | Nintendo's hardware-software integration sustains premium pricing for fantasy franchises against cross-platform competitors. |
| Cloud Infrastructure Partnership | Microsoft's xCloud and NVIDIA's GeForce NOW expand addressable audiences beyond traditional console and PC ownership barriers. |
| Live-Service Engineering Scale-Up | Seoul and Shanghai studio networks concentrate expertise that Western publishers must acquire to compete in multiplayer retention. |
| Regional Localization Investment | NetEase's aggressive Western market adaptation demonstrates revenue capture potential for Asia-Pacific publishers. |
| Regulatory Compliance Certification | CERO-compliant monetization frameworks enable sustainable gacha revenue models that German consumer protection scrutiny threatens. |
Research Methodology
Platform holder financial disclosures, NPPA licensing databases, and regional trade flow records formed the secondary backbone, supplemented by primary interviews with live-service operations directors, narrative design leads, platform partnership managers, and mobile monetization strategists. Bottom-up triangulation across studio production timelines and top-down validation against platform revenue recognition windows anchored market sizing. CERO regulatory filings and METI content production zone subsidies provided geographic concentration benchmarks.
Historical trendline analysis across installed base transitions from console generations to cloud streaming adoption established baseline growth parameters. Segmentation modeling incorporated platform economics, gameplay mode social intensity, genre thematic positioning, and monetization model regulatory exposure. CAGRs derived from cohort retention curve analysis and content pipeline throughput metrics. Forecast inputs included 5G infrastructure deployment schedules and short-form video platform advertising spend reallocation patterns.
Several conditions sit outside the modeled scope, including unannounced hardware generation transitions, abrupt loot box legislation passage in additional European jurisdictions, and geopolitical disruption to China foreign title licensing. Forecasts reflect assumptions regarding sustained Southeast Asian smartphone penetration and cloud latency improvement trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
AAA Games Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
Europe Gaming Peripherals Market
Gaming
Flat Gaming Monitors Market
Gaming
South Korea Gaming Peripherals Market
Gaming
Germany Gaming Headset Market
Gaming
Playstation Network (PSN) Market
Gaming
Online Casual Games Market
Gaming
Russia in-Game Advertising Market
Gaming
China Gaming Headsets Market
Gaming
Mobile MOBA Games Market
Gaming
Gaming Software Market
Gaming
South Asia Mobile Gaming Market
Gaming
Europe Video Game Software Market
Gaming
PC Games Market
Gaming
Puzzle Video Game Market