
 Global Casino Market | 2026-2036
Global Casino Market Size, Share, and Industry Trends Forecast 2026-2036
Global Casino Market Analysis
The EU Green Deal is shifting sustainability compliance onto casino operators with large physical footprints, mandating building retrofits and carbon disclosure across European properties. MGM Resorts International leverages its scale to consolidate energy-efficient resort operations across multiple jurisdictions. Las Vegas Sands Corporation anchors its competitive stance through massive integrated resort developments in Asia and North America. Caesars Entertainment differentiates via loyalty program density and regional casino network breadth across the United States.
Casinos constitute commercial entertainment venues where probability-based and skill-based games operate under regulated house-edge mathematics, with slot machines programmed to specific return-to-player percentages and table games governed by standardized odds structures; their primary purpose is to generate gaming revenue while bundling hospitality, retail, and entertainment amenities that extend visitor dwell time. Sports betting through online platforms captures the fastest expansion as regulatory liberalization opens state and provincial markets, while VIP player segments command disproportionate margin pools due to high-volume wagering and premium service attach rates. Physical casinos retain structural dominance in total revenue but face margin compression from hybrid model investments.
The Nevada Gaming Commission, the UK Gambling Commission, and Singapore's Casino Regulatory Authority each enforce distinct licensing frameworks that shape market access, anti-money laundering protocols, and responsible gambling technology mandates. China's Ministry of Culture and Tourism restricts mainland marketing for Macau operators, directly constraining demand generation tactics for Galaxy Entertainment Group and SJM Holdings Limited. Stakeholders must monitor regulatory divergence between permissive online frameworks and tightening land-based compliance as the primary strategic uncertainty.
Market Dynamics
The EU Green Deal is forcing physical casino operators across Europe to retrofit aging properties for energy efficiency, compressing operating margins while redirecting capital toward sustainability compliance rather than gaming floor expansion.
Growth Catalysts
- Online platform regulatory liberalization:State-level sports betting legalization in the United States is drawing casual gamblers into regulated digital ecosystems, expanding addressable player pools beyond traditional geographic constraints.
- Integrated resort development:Mixed-use hospitality-gaming-entertainment complexes in Singapore and the United Arab Emirates are extending visitor dwell time and diversifying revenue streams beyond pure gaming yield.
- Return-to-player optimization algorithms:Machine learning systems for slot floor configuration are enabling operators to maximize theoretical hold while maintaining player engagement metrics.
Market Restraints
- Macau marketing restrictions:China's Ministry of Culture and Tourism constraints on mainland demand generation tactics directly limit customer acquisition for operators with heavy exposure to the territory.
- Construction cost escalation:Integrated resort development timelines face input cost volatility in steel, glass, and specialized gaming equipment, stretching project IRRs.
- Anti-money laundering compliance density:Layered KYC and transaction monitoring mandates from the UK Gambling Commission and Nevada Gaming Commission are elevating operational overhead without revenue offset.
Strategic Opportunities
- Japan integrated resort authorization:The country's first casino licenses under IR Implementation Act guidelines offer greenfield development rights in Osaka and Yokohama for qualified consortiums.
- Brazil sports betting framework:Federal Law 14.790 established a regulated online sports wagering regime, creating channel access for platform operators previously confined to gray markets.
- AI-driven responsible gambling systems:Real-time behavioral analytics for problem gambling detection are converging with regulatory mandates, creating vendor opportunity in compliance technology.
Industry Challenges
- Legacy system integration friction:Hybrid physical-digital operations require bridging decades-old slot machine protocols with modern cloud infrastructure, complicating real-time data unification.
- Specialized compliance talent scarcity:Shortages of professionals versed in both gaming mathematics and multi-jurisdictional AML frameworks are elongating staffing cycles for new market entries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Casino Market |
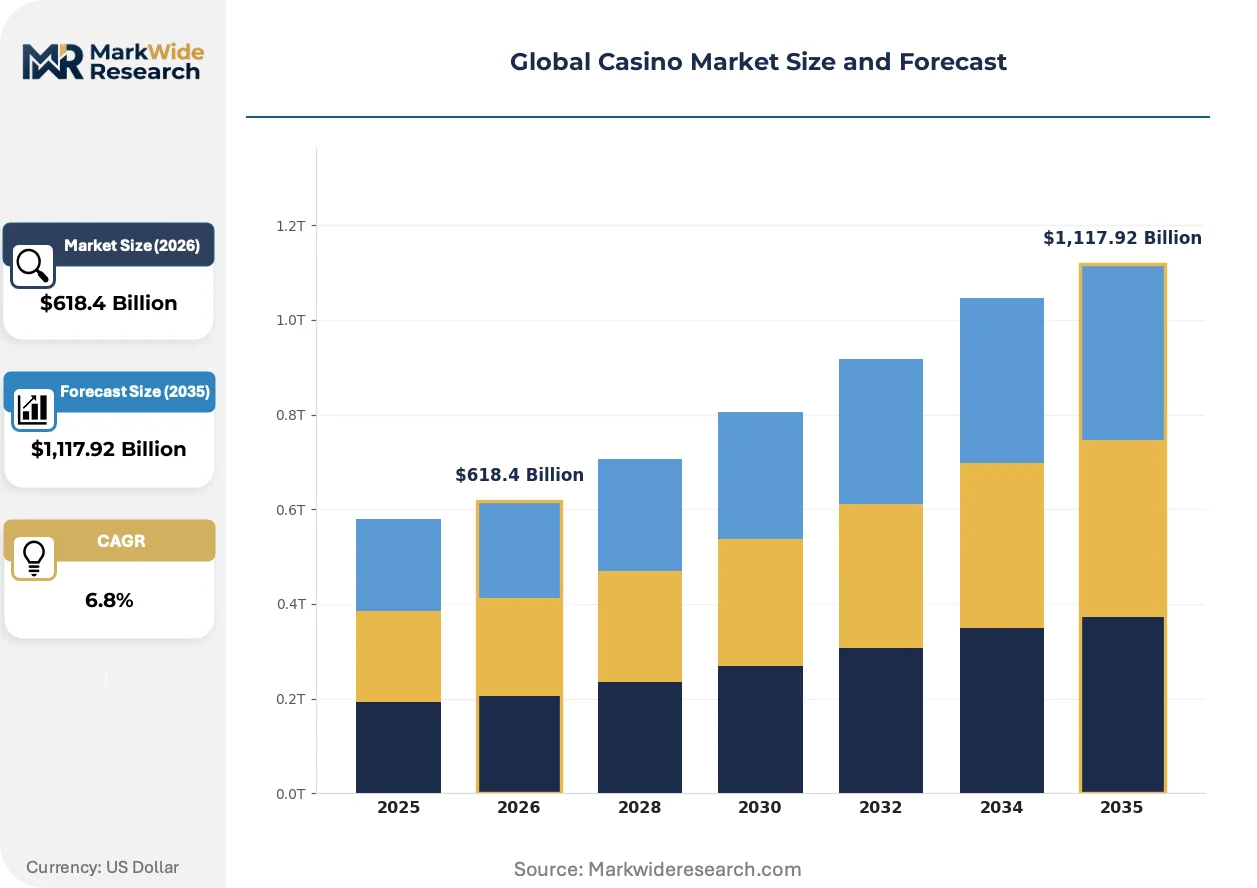
| Market Size in 2026 | $618.4 Billion |
| Market Size in 2035 | $1,117.92 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Table Games, Slot Machines, Sports Betting, Electronic Gaming Machines Customer Type: Casual Gamblers, High Rollers, VIP Players, Tourists Distribution Channel: Physical Casinos, Online Platforms, Mobile Applications, Hybrid Models Game Category: Traditional Games, Video Slots, Live Dealer Games, Skill Games |
| Companies Covered | MGM Resorts International, Las Vegas Sands Corporation, Caesars Entertainment, Wynn Resorts, Galaxy Entertainment Group, Melco Resorts & Entertainment, SJM Holdings Limited, Genting Berhad, Crown Resorts Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Casino Market Emerging Trajectories
Digital wagering infrastructure is actively displacing legacy retail bookmaking, while sustainability mandates and immersive entertainment technologies are redefining capital allocation priorities for physical asset operators.
Live dealer streaming technology is converging with augmented reality interfaces to replicate tactile table game experiences within remote gaming environments. Asian-facing operators are deploying these hybrid systems at scale to capture VIP segments previously requiring physical presence. The structural consequence is compressing the experiential gap between remote and on-premise play, threatening premium service attach rates at flagship properties.
CSRD disclosure mandates are extending carbon reporting requirements to casino operators with European physical footprints, mandating Scope 3 supply chain transparency. Properties in France, Germany, and the Netherlands face accelerated retrofit deadlines under national building efficiency transpositions. Large integrated resort developers are responding by bundling renewable energy procurement into master planning rather than retrofitting existing assets.
Subscription-based loyalty programs are displacing traditional points-accrual models among younger player demographics. Regional casino networks in the United States are piloting monthly fee structures offering guaranteed rewards, dining credits, and entertainment access. This shift is most visible in tribal gaming jurisdictions where regulatory flexibility permits experimental pricing architectures.
Global Casino Market Segmentation
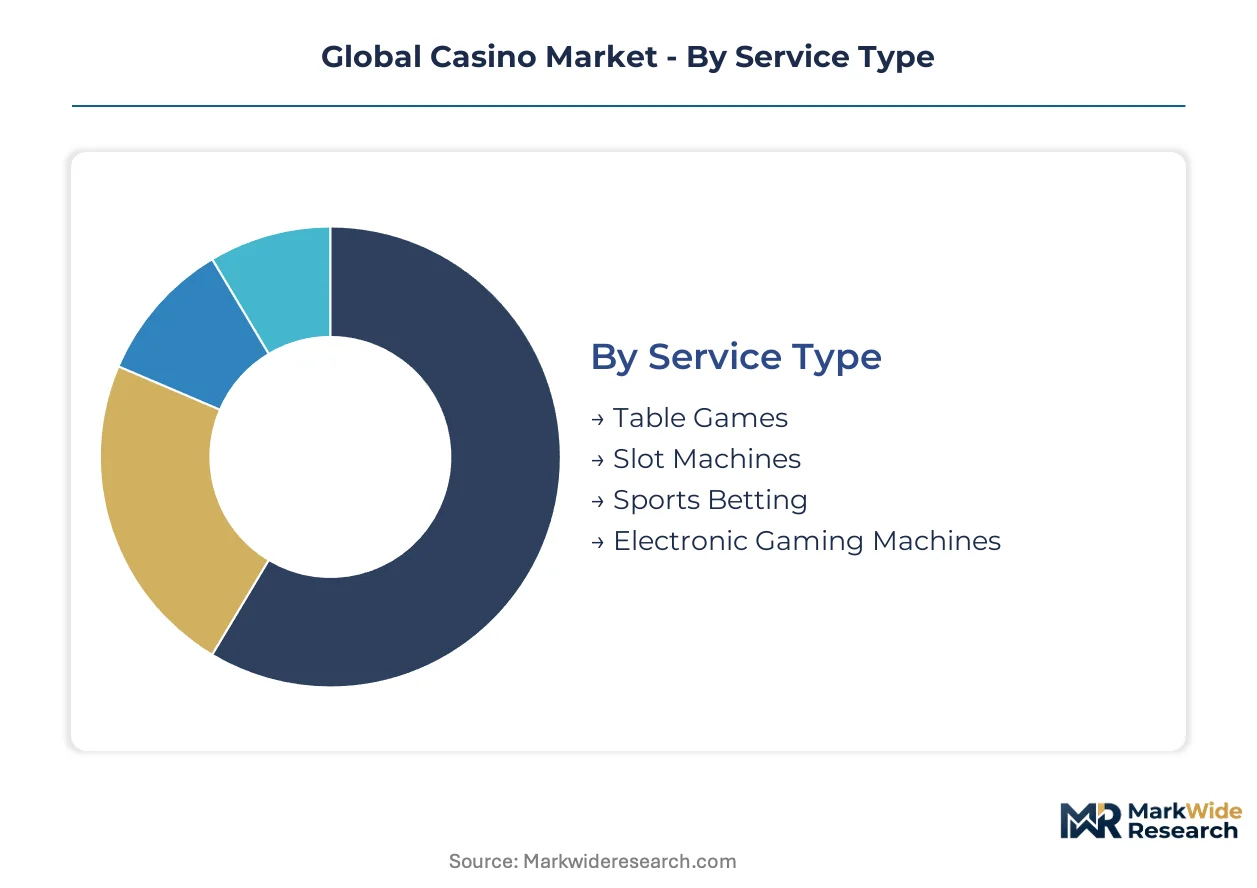
Casino market segmentation tracks how wagering behavior fragments across service formats, customer economics, access channels, and game mechanics. Operators calibrate floor mix and digital investment to match these demand profiles against jurisdictional regulatory constraints.
Service Type:
Standardized house-edge mathematics dominate mass-market segments while customized service tiers capture premium volume across this category.
- Table Games:Probability-based contests including blackjack, roulette, and baccarat governed by fixed odds structures and dealer-mediated pacing. Demand concentrates in Macau and Singapore integrated resorts where VIP junket operators channel high-volume play through private salons.
- Slot Machines:Electronic gaming terminals programmed to specific return-to-player percentages with configurable volatility profiles and themed intellectual property skins. Deployment clusters in US regional casino markets where casual players drive session frequency over average bet size.
- Sports Betting:Wager placement on athletic contests through retail books or digital platforms with dynamic odds adjustment.
- Electronic Gaming Machines:Video lottery terminals and electronic table games blending automated play with reduced labor overhead.
Leading the category by volume: Slot Machines. Growing fastest: Sports Betting.
Customer Type:
Spend concentration and service intensity separate recreational participants from professionally managed gaming relationships.
- Casual Gamblers:Recreational participants with limited session frequency and constrained loss tolerance, typically engaging slot floors or low-limit table games during leisure travel. This segment dominates US regional casino count but generates lower per-capita yield than premium tiers.
- VIP Players:High-net-worth individuals wagering substantial volumes with dedicated hosts, private gaming rooms, and complimentary amenities calibrated to theoretical loss projections. Macau operators structure junket commission agreements specifically around this segment's margin contribution.
- High Rollers:Elevated-stakes players below VIP thresholds but above mass-market parameters.
- Tourists:Non-local visitors with incidental gaming exposure bundled into broader entertainment itineraries.
Volume leadership rests with Casual Gamblers; VIP Players deliver disproportionate margin density.
Distribution Channel:
Capital intensity and regulatory licensing requirements create starkly different competitive dynamics across access modes.
- Physical Casinos:Land-based venues requiring substantial real estate, construction, and localized gaming license procurement with multi-year development timelines. Singapore's Marina Bay Sands and Resorts World Sentosa anchor this channel through integrated resort economics spanning hospitality, retail, and convention business.
- Online Platforms:Internet-based wagering systems operating under state or national licensing frameworks with lower customer acquisition costs and 24-hour accessibility. US state-level sports betting liberalization has accelerated platform launches by established casino operators and pure-play digital entrants.
- Mobile Applications:Smartphone-optimized interfaces with geolocation verification and streamlined payment integration.
- Hybrid Models:Cross-channel loyalty programs and account linking between physical and digital play.
Physical Casinos retain revenue dominance; Online Platforms are climbing the fastest.
Game Category:
Mechanical randomness versus player agency defines the core experience differentiation across this dimension.
- Traditional Games:Established table contests including craps, poker, and roulette with centuries-old rule structures and tactile chip handling. European physical casinos in France, Germany, and the United Kingdom maintain floor space allocation favoring these formats for their cultural resonance with older demographics.
- Live Dealer Games:Streaming video interfaces connecting remote players to human dealers operating physical tables in studio environments. Asian-facing operators deploy these systems at scale to replicate VIP baccarat experiences for mainland Chinese players constrained by travel restrictions.
- Video Slots:Themed electronic terminals with bonus mechanics and progressive jackpots.
- Skill Games:Contests incorporating player decision-making with material outcome influence, including poker and certain arcade-style formats.
Traditional Games lead by installed base; Live Dealer Games show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Las Vegas anchors the world's largest concentration of integrated resort investment, with the Las Vegas Strip corridor generating sustained capital flows into mixed-use hospitality-gaming developments. National regulatory frameworks and localized licensing regimes shape competitive access across major jurisdictions.
United States
State-level sports betting liberalization drives digital platform expansion beyond traditional geographic constraints. The Nevada Gaming Commission enforces strict anti-money laundering protocols and responsible gambling technology mandates. The Las Vegas Strip cluster continues anchoring integrated resort development with multi-billion dollar mixed-use projects.
China
Macau's VIP junket-dependent revenue model faces structural pressure from mainland travel restrictions and marketing constraints. The Ministry of Culture and Tourism restricts demand generation tactics targeting mainland residents. The Pearl River Delta concentration remains the world's largest gaming revenue hub despite regulatory compression.
Singapore
Marina Bay Sands and Resorts World Sentosa anchor the city-state's duopoly integrated resort structure with strict localization requirements. The Casino Regulatory Authority enforces entry levies for citizens and permanent residents to limit domestic participation. The Greater Southern Waterfront corridor concentrates Asia's premium mass-market gaming development.
Japan
The IR Implementation Act authorizes the country's first casino licenses in Osaka and Yokohama with strict concession terms and local employment mandates. METI coordinates integrated resort policy with prefectural governments for zoning and infrastructure. The Osaka Bay area represents the primary greenfield development opportunity for qualified consortiums.
Australia
Crown Resorts and The Star Entertainment Group dominate the Sydney-Melbourne-Perth metropolitan casino landscape with regulatory scrutiny intensifying. State-level gaming commissions enforce enhanced due diligence for VIP patron programs. The Barangaroo precinct in Sydney anchors the newest integrated resort concentration with harbor-front positioning.
Global Casino Market Vendor Landscape
Premium-margin players sit above commodity-margin players across service intensity and loyalty program density. The market structure consolidates around three tiers: integrated resort developers with hospitality diversification, regional casino network operators with geographic breadth, and pure-play digital platform specialists. Strategic archetypes include scale-driven consolidators leveraging cross-property synergies, experience-focused developers emphasizing non-gaming amenities, and technology-forward operators bridging physical-digital convergence. Dominant competitive moves include portfolio diversification through integrated resort development and strategic partnerships for regulatory access in emerging jurisdictions.
Within the integrated resort tier, MGM Resorts International and Las Vegas Sands Corporation exemplify scale-driven operators with multi-jurisdictional footprints. Caesars Entertainment occupies a position emphasizing loyalty program density and regional network breadth across the United States. These three entities represent distinct archetypes: hospitality-integrated development, Asia-focused premium mass positioning, and domestic regional consolidation respectively.
| Leading Market Players |
|---|
| MGM Resorts International |
| Las Vegas Sands Corporation |
| Caesars Entertainment |
| Wynn Resorts |
| Galaxy Entertainment Group |
| Melco Resorts & Entertainment |
| SJM Holdings Limited |
| Genting Berhad |
| Crown Resorts Limited |
| Others |
Supply Flow & Price Mechanics
Integrated resort operators and regional casino networks diverge sharply in cost structures and procurement scale, with the former leveraging hospitality bundling to mask gaming yield compression while the latter face raw margin exposure on slot floor refreshes and loyalty program subsidies. This bifurcation shapes how MGM Resorts International and Caesars Entertainment negotiate equipment financing against pure-play digital platforms with minimal physical asset drag.
Pricing Analysis
Theoretical hold percentages anchor value-based pricing for slot machine placements, with manufacturers calibrating return-to-player algorithms against floor positioning premiums. Price differentiation rests on jurisdictional licensing tier and proprietary intellectual property skins, with premium branded content commanding placement fees above commodity hardware. Cost compression in US regional markets is intensifying because tribal gaming jurisdictions are expanding competitive supply without corresponding demand growth. Casual gamblers exhibit highest price sensitivity to minimum bet thresholds, while VIP Players tolerate elevated theoretical holds in exchange for dedicated host services and private salon access.
Supply Chain Analysis
Specialized technician shortages in Nevada and Macau are elongating installation timelines for electronic gaming machines and live dealer streaming infrastructure. Manufacturing concentration centers on Japan for precision gaming equipment, Taiwan for display and semiconductor components, and China for structural metalwork and assembly. Raw material dependencies span specialized glass for table surfaces, rare earth elements for electronic terminals, and imported hardwoods for premium furniture fixtures. Single-source vulnerability runs through proprietary slot machine operating systems licensed to a concentrated vendor base. Distribution runs through direct manufacturer-operator relationships for major integrated resorts, with regional casino networks purchasing through consolidated gaming equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as regulatory compliance density and capital intensity for integrated resort development force sub-scale operators toward acquisition or exit. Sustainability retrofit mandates and AML technology investments disproportionately burden smaller footprints without revenue diversification.
For Market Incumbents: Anchor defensive positioning through backward integration into renewable energy procurement for European properties facing EU Green Deal retrofit deadlines, while consolidating loyalty program data across hybrid physical-digital channels to offset margin compression from pure-play digital entrants. Prioritize certification investment in AI-driven responsible gambling systems to preempt regulatory mandates from the UK Gambling Commission and Nevada Gaming Commission. For New Entrants and Emerging Players: Enter via Brazil's federally regulated sports betting framework under Law 14.790, where established brand recognition from gray market operations provides immediate channel access before multinational casino operators complete platform localization. Target Japan's Osaka Bay integrated resort consortium opportunities as sub-contractors for hospitality technology and gaming equipment supply, leveraging regulatory flexibility before operating licenses finalize. For Investors and Strategic Acquirers: Exit pathways concentrate in regional casino network rollup by integrated resort developers seeking geographic diversification beyond Las Vegas Strip concentration. Long-term viability favors operators with demonstrated compliance technology deployment and hybrid revenue streams spanning gaming, hospitality, and entertainment. Watch for inflection signals in Macau travel restriction easing by China's Ministry of Culture and Tourism, which would reactivate VIP junket commission structures and premium mass-market yield recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Resort Development | Osaka and Yokohama licenses under Japan's IR Implementation Act anchor Asia-Pacific greenfield investment. |
| Regulatory Technology Investment | AI-driven responsible gambling systems satisfy UK Gambling Commission and Nevada Gaming Commission mandates. |
| Hybrid Platform Integration | Cross-channel loyalty programs bridge physical casino visitation with digital sports betting engagement. |
| Sustainability Retrofit Bundling | Renewable energy procurement into master planning addresses EU Green Deal Scope 3 disclosure requirements. |
| VIP Junket Restructuring | Commission agreement recalibration responds to Macau marketing constraints from mainland travel restrictions. |
Methodological Framework
Multi-period observation of regulatory licensing timelines, capital expenditure disclosures, and player yield metrics anchored the trend analysis, supplemented by interviews with casino operations executives, gaming equipment procurement directors, regulatory compliance officers, and hospitality technology vendors. Secondary validation drew from Nevada Gaming Commission enforcement actions, UK Gambling Commission licensing registers, Singapore Casino Regulatory Authority annual reports, and SEC 10-K filings from listed operators. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices mapped wagering volume projections against jurisdictional regulatory capacity, integrated resort development pipelines, and digital platform adoption curves. Segmentation dimensions spanned service format, customer economics, distribution channel, and game mechanics, with additional modeling for theoretical hold percentage sensitivity and loyalty program attach rates. CAGRs were derived through regression analysis of historical revenue trajectories adjusted for regulatory event impacts. Forecast inputs included construction cost indices for integrated resort development and state-level sports betting legalization velocity.
Revisions become necessary when regulatory liberalization timelines accelerate or stall, construction input cost volatility exceeds historical bands, or Macau travel policy shifts materially alter Asia-Pacific demand assumptions. Material deviation in these triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
LAMEA in-Game Advertising Market
Gaming
Console Games Market
Gaming
United States Gaming Accessories Market
Gaming
MMORPG Gaming Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Board Games Market
Gaming
Australia Casino Tourism Market
Gaming
Slot Machine Market
Gaming
VR Gaming Market
Gaming
Connected Game Console Market
Gaming
Mobile Game Controller Market
Gaming
Shooter Game Market
Gaming
Serious Games Market
Gaming
China Subscription-Based Gaming Market
Gaming
North America Gaming Market
Gaming
South Asia Mobile Gaming Market